
 Drip Irrigation Market | 2026-2036
Drip Irrigation Market Size, Share, and Industry Trends Forecast 2026-2036
Drip Irrigation Market Intelligence
India's expansion of domestic manufacturing for irrigation components is rewriting regional supply dynamics and influencing export pricing. Jain Irrigation Systems Limited leverages its significant production footprint in the country to serve both local and international markets. Netafim competes on technology leadership in pressure-compensating drippers. The Toro Company differentiates through its extensive distribution network and brand recognition, particularly in North American markets.
Drip irrigation is a micro-irrigation method delivering water directly to a plant's root zone at controlled flow rates, typically 0.5 to 4 liters per hour. This technique minimizes evaporation and is crucial for efficient water usage in agriculture. While dripper emitters constitute a large product segment, demand for subsurface drip line systems is accelerating in high-value fruit and vegetable cultivation. Fertigation-compatible systems are also becoming a standard requirement for commercial farms.
Water conservation mandates and subsidy programs, such as the USDA's Environmental Quality Incentives Program and India's PMKSY scheme, directly stimulate market adoption. In Europe, the EU's Common Agricultural Policy links financial support to sustainable water management practices, favoring efficient irrigation. System selection will increasingly hinge on balancing initial capital outlay with long-term water savings and crop yield improvements.
Market Dynamics
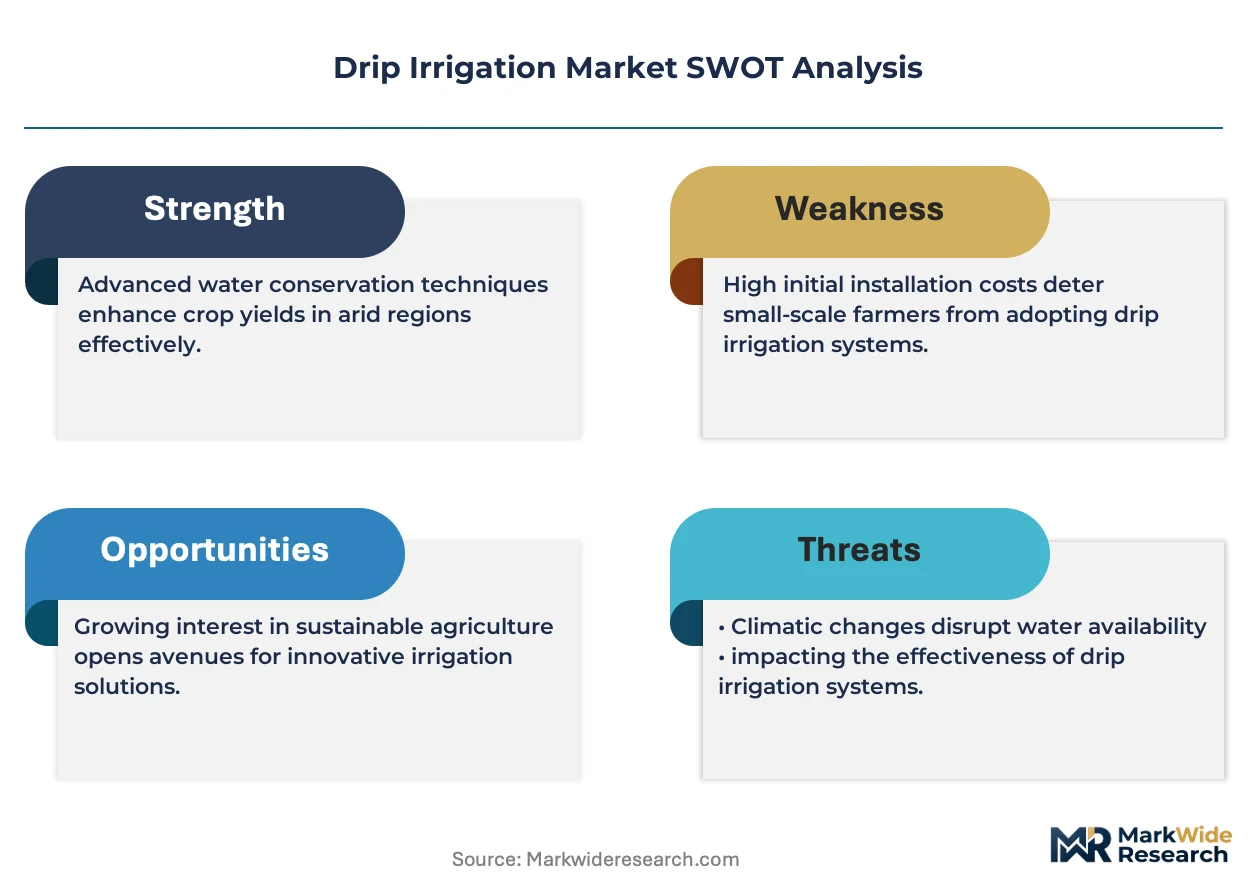
The market's central dynamic is the collision between urgent water scarcity mandates and the high initial capital investment required for advanced systems. Government subsidies, particularly in agricultural economies, are the primary mechanism mediating this tension and accelerating adoption among commercial farms.
Growth Catalysts
- Water Conservation Mandates:Government policies, such as India's Pradhan Mantri Krishi Sinchayee Yojana (PMKSY), provide direct financial incentives and subsidies for farmers to adopt micro-irrigation, directly boosting demand for drip systems to meet water efficiency targets.
- Fertigation System Integration:The ability to combine irrigation with fertilization allows for precise nutrient application directly to the root zone. This technique is gaining favor in high-value horticulture as it demonstrably improves crop quality and yield while reducing fertilizer waste.
- Advancements in Polymer Science:Development of more durable, UV-resistant, and clog-resistant polyethylene and PVC materials for drip lines and emitters is extending system lifespan and reducing long-term maintenance costs, improving the overall value proposition for end-users.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of purchasing and installing a complete drip irrigation system, including pumps, filters, and tubing, remains a primary barrier for small-scale and marginal farmers, particularly in developing economies without robust subsidy support.
- Emitter Clogging and Maintenance:System performance is highly sensitive to water quality. Emitters are prone to clogging from sediment, mineral deposits, or algae, requiring rigorous filtration and periodic maintenance, which adds operational complexity and cost.
- Raw Material Price Volatility:The price of polyethylene, the primary raw material for drip tubing and emitters, is subject to fluctuations in global petrochemical markets. This volatility can impact manufacturer margins and lead to unpredictable end-product pricing.
Strategic Opportunities
- Expansion in Sub-Saharan Africa:Many nations in Sub-Saharan Africa face severe water stress yet have very low penetration of micro-irrigation. This region represents a significant long-term growth opportunity, driven by food security initiatives and international development aid.
- Smart Irrigation with IoT and AI:Integrating drip systems with IoT sensors for soil moisture, weather data, and AI-powered analytics platforms enables fully automated, predictive irrigation. This creates an opportunity for higher-margin, data-driven water management solutions.
- Application in Controlled Environment Agriculture:The rise of urban vertical farms and commercial greenhouses creates a new, high-value market segment. Drip irrigation is essential in these controlled environments for precise water and nutrient delivery to soilless media.
Industry Challenges
- Technical Skill Gaps:A shortage of trained personnel for proper system design, installation, and ongoing maintenance persists, especially in rural and remote agricultural regions. Improper installation can lead to system failure and undermine farmer confidence in the technology.
- Last-Mile Distribution Logistics:Reaching fragmented and geographically dispersed smallholder farms presents a significant logistical challenge. Establishing efficient and cost-effective distribution and service networks in these areas is a major operational hurdle for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drip Irrigation Market |
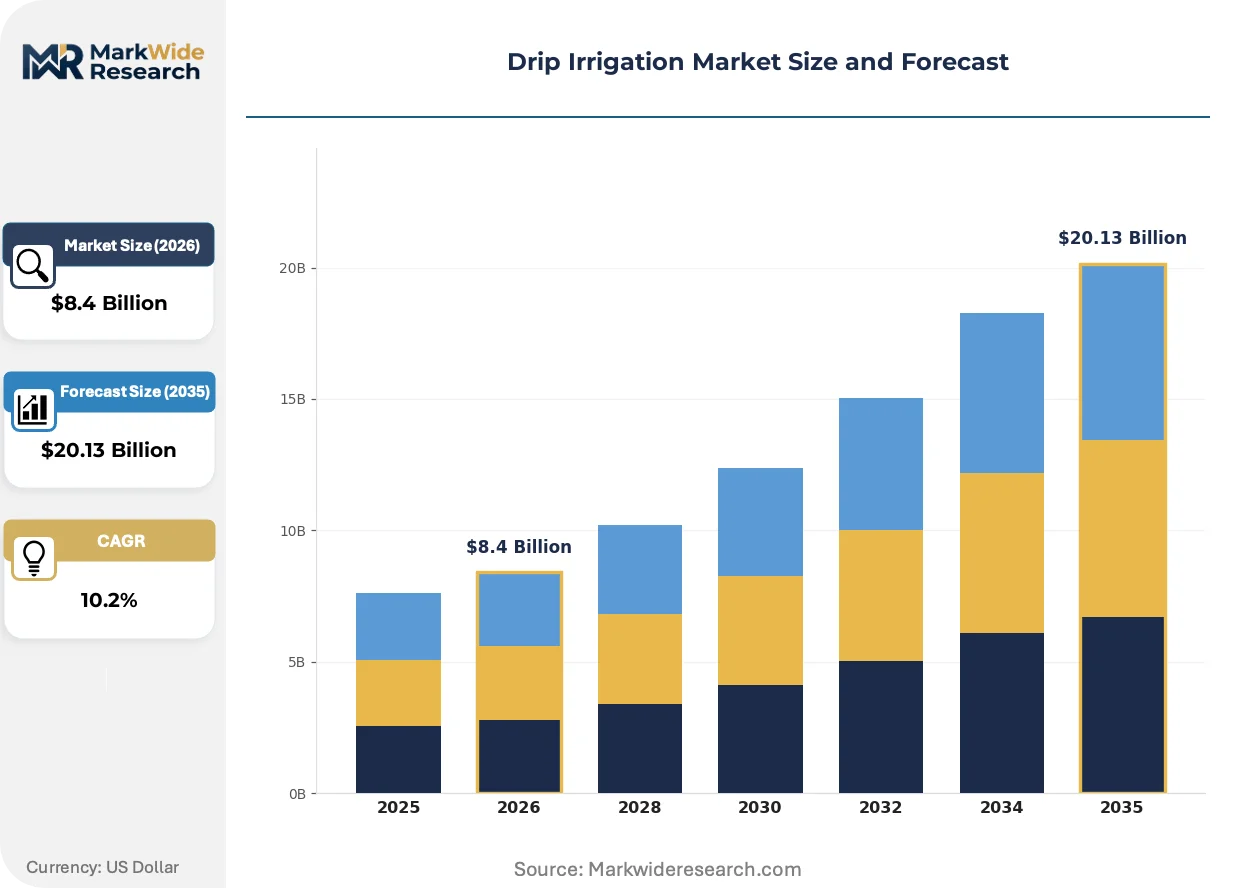
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $20.13 Billion |
| CAGR (2026 – 2036) | 10.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dripper Emitters, Micro Tubing, Spray Emitters, Drip Tape, Subsurface Drip Line Crop Type: Fruits, Vegetables, Cereals, Pulses, Ornamentals Technology: Pressure Compensating, Non-Pressure Compensating, On-Demand, Fertigation End User: Commercial Farms, Greenhouses, Nurseries, Government Agencies |
| Companies Covered | Jain Irrigation Systems Limited, Netafim, The Toro Company, Rain Bird Corporation, Hunter Industries, Rivulis, Lindsay Corporation, Irritec, Chinadrip Irrigation Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drip Irrigation Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward automation and data-driven precision. This shift is transforming drip irrigation from a simple water delivery method into an integrated component of sophisticated farm management systems, with a focus on maximizing resource efficiency.
Pressure-compensating (PC) drippers are a critical innovation that ensures a uniform flow rate regardless of pressure variations caused by long lateral lines or uneven terrain. Large-scale agricultural operations, particularly those cultivating orchards and vineyards on sloped land, are rapidly adopting this technology. The use of PC drippers is collapsing the performance gap between systems on ideal flat ground and those on challenging topographies, broadening the viable application landscape.
In Europe, the EU's Common Agricultural Policy (CAP) directly links farm subsidies to compliance with environmental standards, including sustainable water management. This regulatory framework creates a powerful financial incentive for farmers to invest in water-efficient technologies like drip irrigation to secure funding. The policy most acutely affects agricultural producers in water-stressed member states like Spain and Italy, who are accelerating system upgrades.
A notable behavioral change is the move away from piecemeal component purchasing toward acquiring integrated, service-oriented solutions. This model disrupts traditional distributor channels by bundling system design, installation, and ongoing maintenance support into a single package. The shift is most pronounced in large agribusiness enterprises in Australia and the United States, where managing operational risk and ensuring long-term system performance are key procurement drivers.
Drip Irrigation Market Segmentation
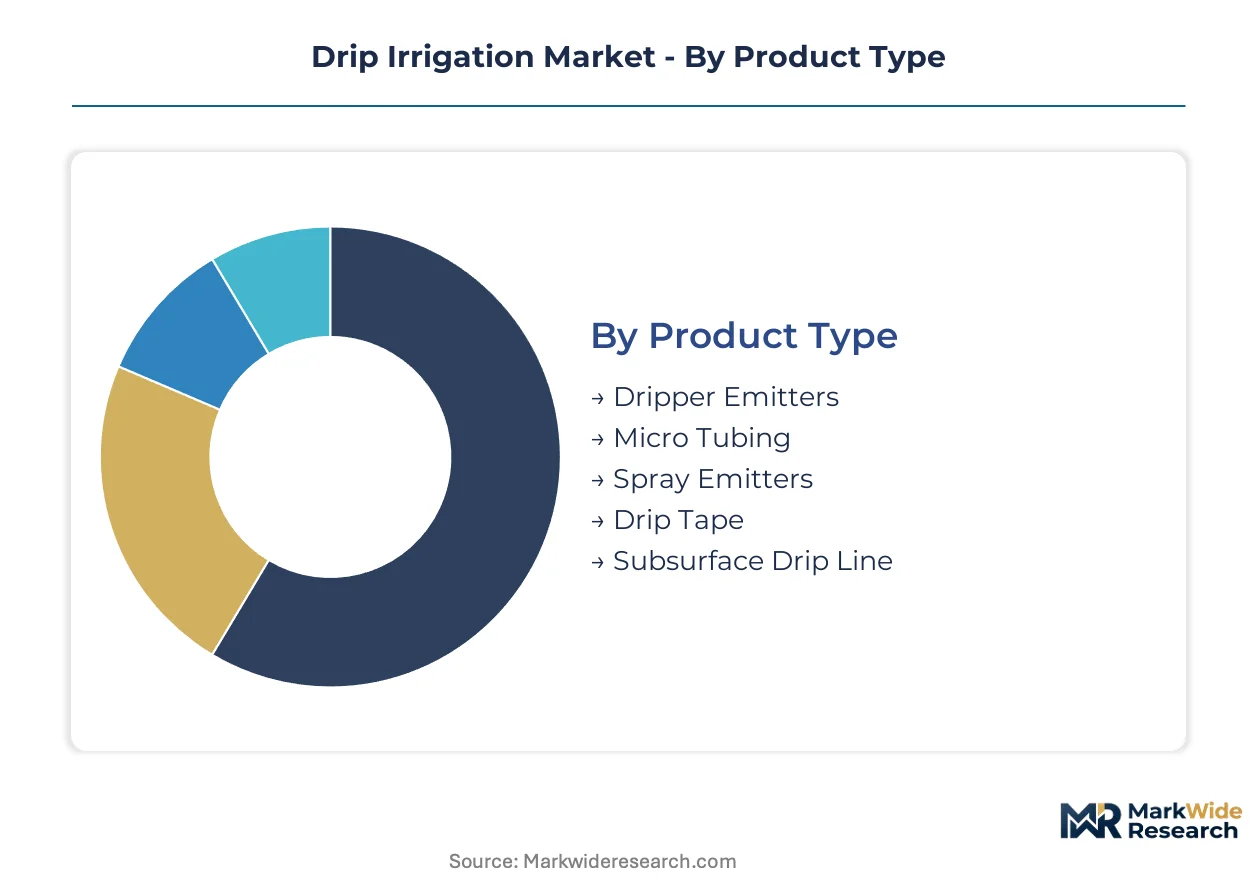
The Drip Irrigation Market is analyzed through its diverse segmentation, reflecting varied application needs and technological advancements. Understanding these distinctions is crucial for identifying specific demand pockets and tailoring solutions for water-efficient agriculture. Product variations and end-user requirements significantly influence market dynamics.
Product Type:
Product type differentiation reflects the diverse irrigation requirements across various agricultural settings.
- Dripper Emitters:These components precisely release water at controlled flow rates directly to the plant root zone. Demand concentrates in horticulture and row crops, where precise moisture management directly impacts yield quality.
- Subsurface Drip Line:Installed beneath the soil surface, this system delivers water directly to the root zone, minimizing evaporation and surface runoff. Its application is expanding rapidly in high-value fruit and vegetable cultivation across arid regions like India.
- Micro Tubing:Small diameter tubes connect main lines to individual emitters, facilitating localized water delivery to specific plants.
- Spray Emitters:These devices disperse water in a fine spray over a small area, suitable for dense plant arrangements in nurseries.
- Drip Tape:Thin-walled, collapsible tubing with integrated emitters, offering a cost-effective solution for seasonal row crops.
Dripper Emitters command the established base. The steepest expansion runs through Subsurface Drip Line.
Crop Type:
Application across different crop types outlines the varied requirements for water delivery and nutrient management.
- Fruits:Drip irrigation optimizes water usage for orchards and vineyards, ensuring consistent fruit development and quality. Producers in Spain and California increasingly adopt advanced systems for water efficiency.
- Vegetables:Precise water and nutrient delivery to vegetable crops minimizes disease and maximizes yield per acre. Farmers in India and the Mediterranean region prioritize drip systems for intensive vegetable cultivation.
- Cereals:Large-scale cereal farms are beginning to integrate drip systems in water-stressed regions to improve yield stability.
- Pulses:Drip irrigation provides controlled moisture for pulse crops, enhancing germination and overall plant health in arid zones.
- Ornamentals:Nurseries and commercial landscapers utilize drip systems for efficient watering of high-value ornamental plants.
The largest segment remains Fruits, while Vegetables exhibits the fastest growth due to intensive farming practices.
Technology:
Technological advancements define the capabilities and efficiency levels available to end-users.
- Pressure Compensating:These drippers maintain a uniform flow rate despite pressure variations, crucial for long lateral lines or uneven terrain. Large agricultural operations in Europe and North America adopt this technology for consistent water application.
- Fertigation:This technology integrates fertilizer delivery directly into the irrigation water, enabling precise nutrient application to the root zone. Commercial farms increasingly demand fertigation-compatible systems to boost crop yields and reduce waste.
- Non-Pressure Compensating:These basic drippers have flow rates that vary with pressure, suitable for flat terrains and shorter irrigation lines.
- On-Demand:Systems responsive to real-time sensor data, delivering water only when soil moisture levels drop below a set threshold.
Pressure Compensating technology forms the core of high-performance systems. Fertigation integration is rapidly becoming a standard requirement.
End User:
The end-user landscape illustrates varied operational scales and investment capacities within the agricultural sector.
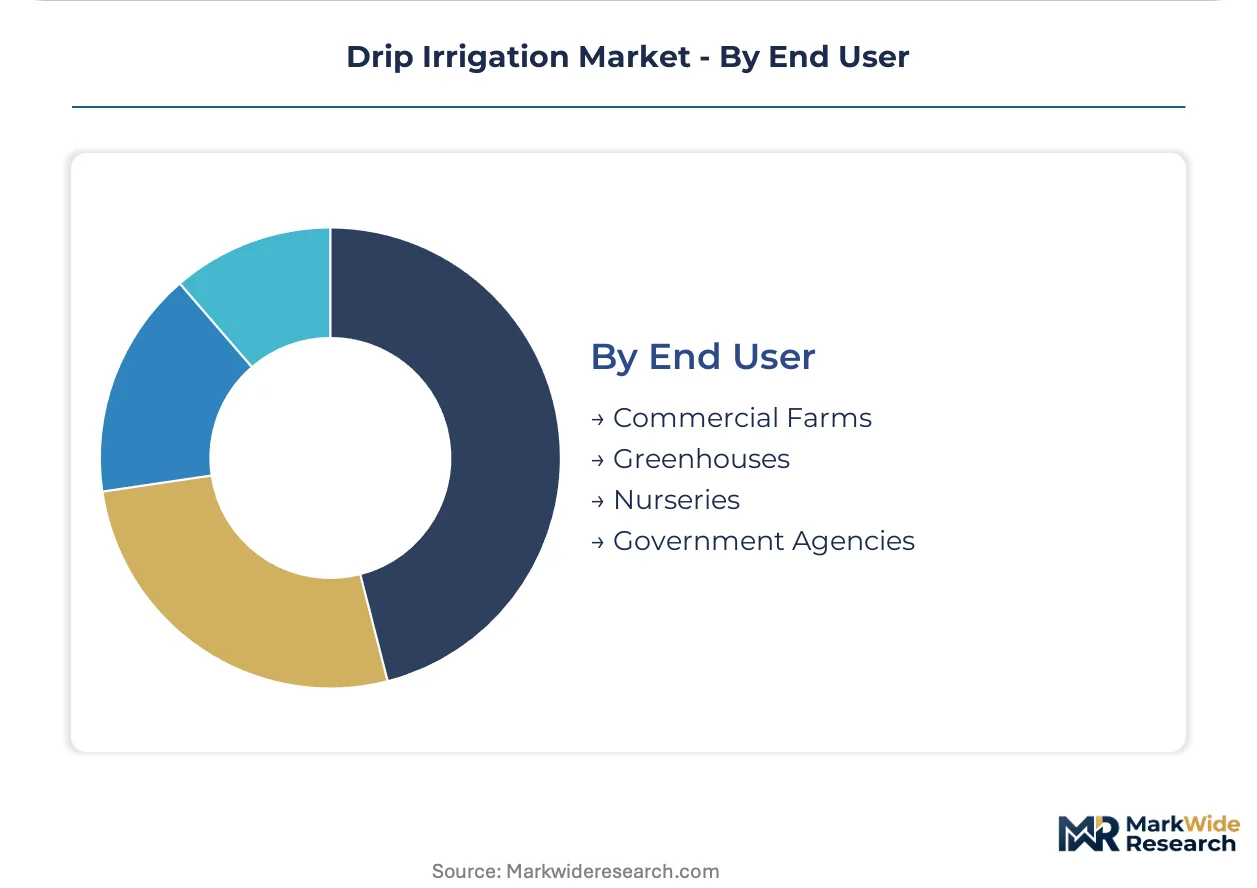
- Commercial Farms:These large-scale agricultural enterprises are the primary adopters of drip irrigation, driven by water conservation mandates and government subsidies. Operations in India and the United States are rapidly modernizing their irrigation infrastructure.
- Greenhouses:Controlled environment agriculture relies heavily on drip systems for precise water and nutrient delivery to soilless media. Urban vertical farms represent a high-value growth segment for these specialized applications.
- Nurseries:Horticultural nurseries use drip irrigation for efficient watering of young plants, minimizing water waste and promoting healthy growth.
- Government Agencies:Public sector bodies implement drip irrigation in demonstration projects or large-scale land development schemes to promote water efficiency.
Commercial Farms represent the dominant user group. Greenhouses are gaining share fastest due to specialized cultivation needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA's Environmental Quality Incentives Program (EQIP) promotes water conservation technologies across US agriculture. This initiative, alongside similar programs in other nations, stimulates demand for efficient irrigation systems. Farmers prioritize drip irrigation to enhance water efficiency and secure financial support.
India
Water scarcity and a large agricultural base drive significant demand for drip irrigation in India. The Pradhan Mantri Krishi Sinchayee Yojana (PMKSY) provides direct financial incentives and subsidies for micro-irrigation adoption. Maharashtra, a key agricultural state, hosts major manufacturing facilities like Jain Irrigation Systems Limited, serving both domestic and export markets.
United States
Demand for drip irrigation in the United States stems from the need for water conservation in arid regions and efficient cultivation of high-value crops. The USDA's Environmental Quality Incentives Program (EQIP) supports farmers in implementing water-saving practices. California's Central Valley, a major agricultural hub, sees widespread adoption of advanced drip systems for specialty crops.
Spain
Spain, a water-stressed member state, is a significant market for drip irrigation, driven by EU agricultural policies. The EU's Common Agricultural Policy (CAP) links financial support to sustainable water management practices. Producers in Andalusia, a region with intensive horticulture, are accelerating system upgrades to improve water efficiency and secure subsidies.
South Africa
South Africa faces severe water stress, making efficient irrigation critical for food security and agricultural productivity. The National Water Act provides a framework for water resource management, encouraging water-saving technologies. The Western Cape, a key fruit-producing region, increasingly adopts drip systems for vineyards and orchards.
Australia
Australia’s large-scale agribusinesses adopt drip irrigation to manage water resources effectively across vast agricultural lands. The National Water Initiative aims to improve water efficiency and productivity in the agricultural sector. The Murray-Darling Basin, a major irrigated agricultural area, is a significant consumer of integrated drip irrigation solutions.
Drip Irrigation Market Key Industry Players
Capability concentration sits with specialized technology providers focused on precision, while scale advantage sits with large manufacturers offering broad product portfolios. The market exhibits a tiered structure, with global leaders and regional players competing across different segments. Strategic archetypes include technology innovators, integrated solution providers, and cost-effective component suppliers. Key competitive moves involve geographic expansion into emerging markets and portfolio diversification to include smart irrigation solutions.
Within the integrated solution provider archetype, Jain Irrigation Systems Limited, with its extensive manufacturing footprint, exemplifies a vertically integrated approach. Netafim, a technology leader, occupies a position focused on advanced pressure-compensating drippers. The Toro Company, known for its broad distribution, represents a major player with strong brand recognition in North American markets.
| Leading Market Players |
|---|
| Jain Irrigation Systems Limited |
| Netafim |
| The Toro Company |
| Rain Bird Corporation |
| Hunter Industries |
| Rivulis |
| Lindsay Corporation |
| Irritec |
| Chinadrip Irrigation Equipment |
| Others |
Cost & Logistics Intelligence
Underutilization in certain Asian manufacturing facilities drives aggressive pricing strategies among component suppliers for drip irrigation systems. This capacity surplus influences global product pricing and market entry dynamics for new entrants.
Pricing Analysis
Geographic price spreads for drip irrigation systems vary significantly, with lower costs observed in India due to large-scale domestic manufacturing. The dominant pricing model is project-based, often bundling system design, installation, and initial support services. Price differentiation stems from brand premium, particularly for advanced pressure-compensating drippers, and the level of after-sales service provided. Pricing softness reflects raw material price volatility, especially for polyethylene components. Small-scale farmers exhibit high price sensitivity, while large commercial farms prioritize long-term value and system reliability.
Supply Chain Analysis
Jain Irrigation Systems Limited, with its extensive production footprint in India, exemplifies concentrated manufacturing capacity within the drip irrigation sector. The supply chain relies on polyethylene and PVC, sourced globally for tubing, emitters, and connectors. Geographic supply concentration is notable in India and China, which produce a significant volume of components. Raw material price volatility represents a structural risk to manufacturer margins. Downstream distribution primarily operates through established distributor networks and direct sales channels to large agribusinesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drip irrigation market experiences a buyer power shift, driven by the increasing consolidation of large commercial farms seeking integrated solutions. This concentration influences vendor offerings and service models.
For Market Incumbents:Pre-empt emerging competition by deepening vertical integration into smart irrigation software and sensor manufacturing. This move mitigates the threat from technology-focused startups and secures channel control. Expand manufacturing capacity in India to leverage cost advantages and serve local demand, while also improving regional export competitiveness.
For New Entrants and Emerging Players:Establish a beachhead in Sub-Saharan Africa by offering modular, cost-effective drip tape systems for smallholder farms. This region presents a penetrable segment due to very low micro-irrigation penetration and severe water stress. A direct-to-farmer sales model, supported by local training and micro-financing partnerships, offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Capital is best deployed toward integrated solution providers with strong R&D in AI-powered water management and local manufacturing capabilities. Such entities offer long-term viability by addressing evolving agricultural needs for precision and sustainability. The signal to watch is the rate of government subsidy expansion in new agricultural economies like those in Sub-Saharan Africa.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate IoT Sensors & AI Analytics | Enhances precision water management for commercial farms, improving crop yields. |
| Expand Domestic Manufacturing in India | Reduces production costs and strengthens market position in a high-demand agricultural economy. |
| Acquire Specialized Software Firms | Boosts capabilities in data-driven irrigation scheduling and nutrient delivery for agribusinesses. |
| Develop Clog-Resistant Emitter Materials | Extends system lifespan and reduces maintenance for end-users, particularly in challenging water quality environments. |
| Form Partnerships for Last-Mile Distribution | Improves market access to fragmented smallholder farms in rural and remote agricultural regions. |
Research Approach
Operator-level perspectives from farm managers, irrigation system engineers, and agricultural policy advisors anchored the qualitative base for this analysis. Primary interviews were combined with secondary validation from USDA reports, EU agricultural policy documents, and company annual filings. This approach ensured robust bottom-up and top-down triangulation across diverse data points.
Scenario-bracketing established the quantitative framework across the analysis window, integrating volume and value outputs. Segmentation dimensions modeled included product type, crop type, technology, end user, and regional water stress levels. Compound annual growth rates were derived from historical trends and projected adoption rates, with government subsidy levels serving as a key forecast input.
Sensitivities concentrate around shifts in government water conservation mandates and raw material price volatility. Forecasts reflect assumptions regarding technological advancements and agricultural investment patterns. Quarterly review of policy changes and commodity market indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market