
 Global Fertilizers Market | 2026-2036
Global Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fertilizers Market Foresight
Consolidation among Brazilian soybean cooperatives and fragmentation across African contract farming schemes is realigning procurement power toward volume buyers in the Americas while opening smaller parcel demand in East Africa. Nutrien Ltd. leverages its retail distribution network across North American farm belts to sustain direct-to-grower relationships. Yara International ASA anchors European nitrogen capacity while competing for specialty product share in Asian horticulture zones. The Mosaic Company dominates phosphate rock sourcing from its Florida operations and extends into premium micronutrient blends for precision agriculture.
Fertilizers are chemical or biological soil amendments formulated to deliver essential macronutrients—nitrogen, phosphorus, and potassium—along with secondary and trace elements that correct nutrient deficiencies and optimize plant metabolic function; manufacturing routes include Haber-Bosch ammonia synthesis, phosphate rock acidulation, and potash evaporation or flotation extraction. Nitrogenous fertilizers occupy the largest volume share due to universal crop demand and established ammonia infrastructure, though biofertilizers represent the fastest-expanding category as microbial inoculant formulations gain regulatory approval for organic systems. Phosphatic products concentrate margin pools in premium-grade low-cadmium segments where OCP Group and Mosaic compete on ore quality and beneficiation technology.
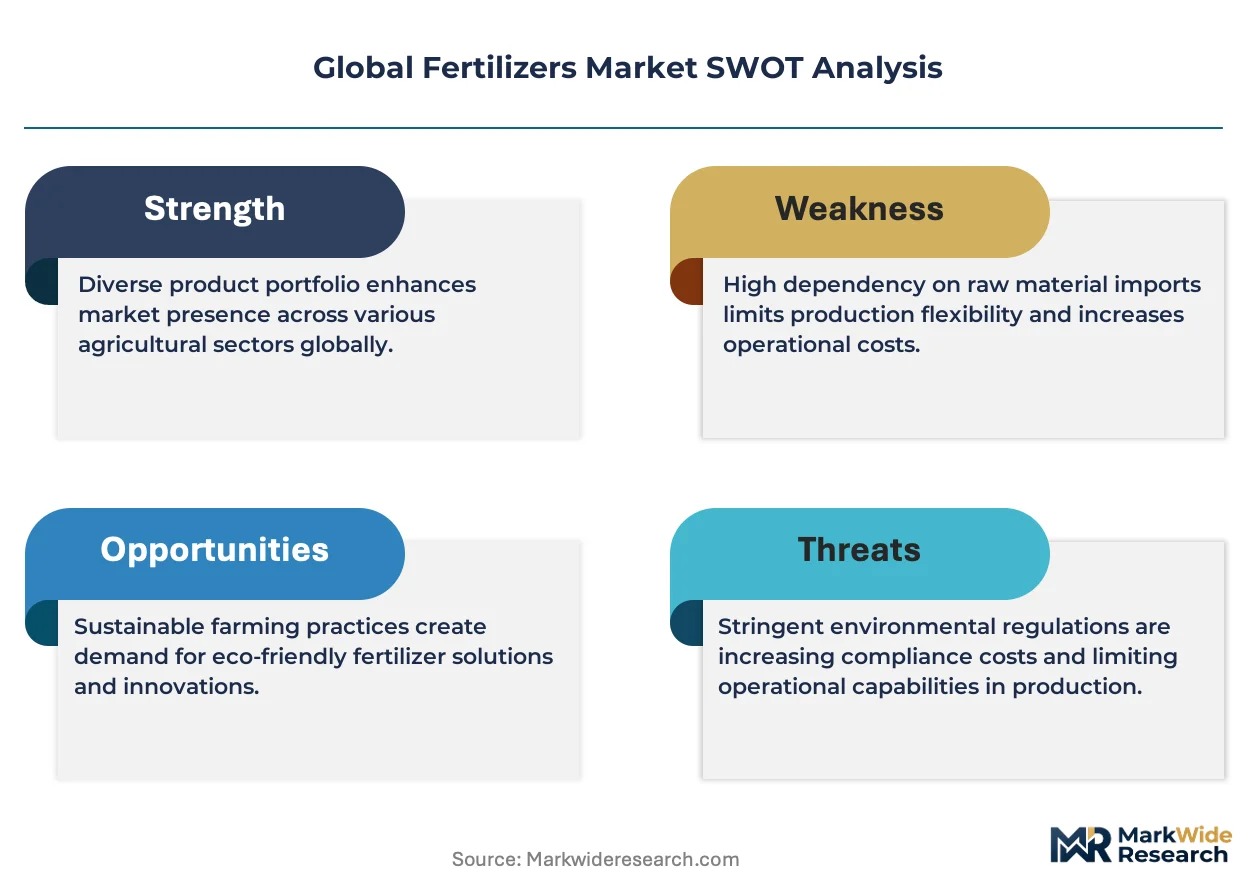
The EPA oversees water runoff standards under the Clean Water Act that constrain nitrogen application rates in US watersheds, while the EU Fertilizing Products Regulation harmonizes CE-marking requirements for recycled and organic nutrient sources across member states. India's Fertilizer Ministry administers the Nutrient Based Subsidy scheme that fixes retail urea prices and channels imported DAP through state trading corporations. Stakeholders must monitor how carbon border adjustments and renewable ammonia pilot projects reshape feedstock cost structures and product certification requirements.
Market Dynamics
The EU Fertilizing Products Regulation's cadmium limits on phosphate imports are forcing beneficiation technology upgrades across Moroccan and Russian rock suppliers while redirecting procurement flows toward Florida and Peruvian ore sources.
Growth Catalysts
- Nutrient Based Subsidy:India's Fertilizer Ministry fixes retail urea prices and channels imported DAP through state trading corporations, locking in demand from 146 million smallholder cooperatives.
- Controlled-release nitrogen:Specialty crop growers in Brazil expand polymer-coated urea applications to reduce leaching losses and comply with watershed protection mandates.
- Microbial inoculants:Biofertilizers gain regulatory approval for organic systems as EFSA and India's FSSAI clear rhizobium and azotobacter formulations for commercial use.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis costs fluctuate with Henry Hub and TTF pricing, compressing margins for nitrogenous fertilizer producers without captive methane supply.
- Phosphate rock concentration:Morocco's OCP Group and The Mosaic Company control over 70% of export-grade ore, creating supply security risks for European and Asian blenders.
- Clean Water Act constraints:EPA nitrogen application rate limits in Chesapeake Bay and Mississippi River watersheds cap per-acre dosing for corn and soybean growers.
Strategic Opportunities
- East African contract farming:Fragmented smallholder schemes in Ethiopia and Tanzania open demand for micronutrient sachets and mobile soil testing services.
- Renewable ammonia pilots:Electrolysis-based hydrogen feedstock projects in Norway and Chile promise carbon-intensity certifications for premium export markets.
- Precision agriculture convergence:Variable-rate application hardware and soil sensor networks enable site-specific nutrient prescriptions for Brazilian soybean cooperatives.
Industry Challenges
- CE-marking compliance timelines:EU Fertilizing Products Regulation harmonization requires 18-24 month certification cycles for recycled nutrient products, delaying market entry.
- Agronomist talent scarcity:Soil science and crop nutrition expertise concentrates at major retailers, leaving independent distributors without technical support capacity.
- Legacy blending equipment:Batch mixing infrastructure at regional cooperatives lacks automated dosing precision for micronutrient inclusion at sub-1% rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fertilizers Market |
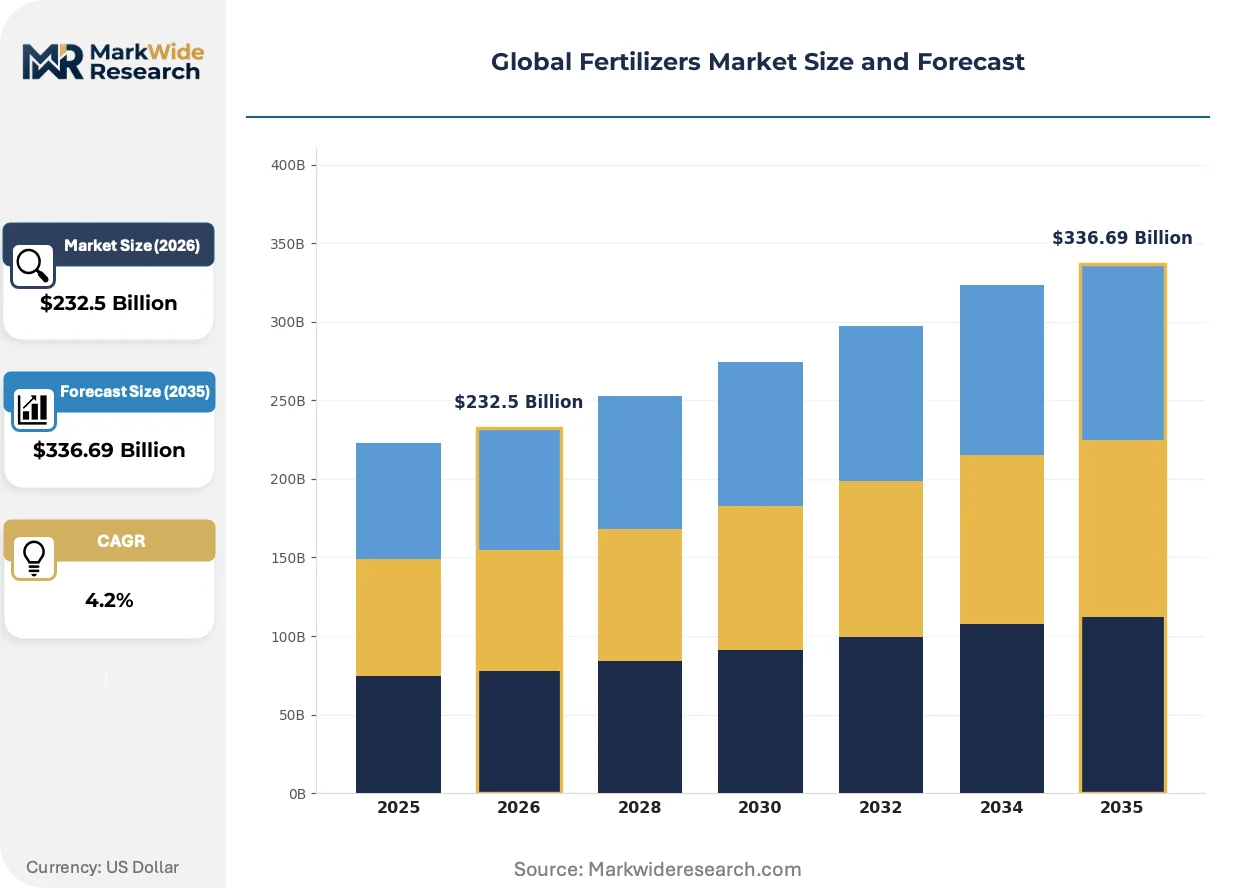
| Market Size in 2026 | $232.5 Billion |
| Market Size in 2035 | $336.69 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphatic, Potassic, Biofertilizers, Micronutrient Fertilizers Application: Cereal Crops, Oilseed Crops, Horticulture, Pulses, Plantation Crops End User: Farmers, Agricultural Cooperatives, Contractors, Government Agencies Distribution Channel: Wholesale Dealers, Retail Stores, E-commerce Platforms, Direct Sales |
| Companies Covered | Nutrien Ltd., The Mosaic Company, Yara International ASA, CF Industries Holdings, Inc., ICL Group Ltd., K+S Aktiengesellschaft, Grupa Azoty, OCP Group, SQM S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fertilizers Market Shifts & Advancements
Digital soil mapping and polymer chemistry advances are compressing application windows while regulatory pressure on carbon intensity reshapes feedstock sourcing strategies across nitrogen and phosphate value chains.
Polymer-coated controlled-release fertilizers are integrating sulfur and polymer membrane technologies to synchronize nutrient release with crop uptake curves. Specialty vegetable growers in Spain and California adopt these formulations to reduce split-application labor costs. The technology is integrating precision agriculture platforms by enabling single-pass basal dressing that matches variable-rate seeding maps.
REACH and the EU Fertilizing Products Regulation now mandate cadmium limits of 60 mg/kg P2O5 for phosphate fertilizers sold in member states, with staged reductions to 20 mg/kg by 2028. This forces importers to source from low-cadmium ore bodies or invest in beneficiation washing circuits. Premium-grade phosphate producers in Florida and Peru capture margin expansion as European blenders reformulate product slates.
Direct-to-grower digital platforms displace traditional cooperative procurement committees for input purchasing decisions. Younger farm operators in Australia's wheat belt and Canada's prairie provinces subscribe to subscription-based nutrient programs bundled with satellite imagery and yield analytics. This shift concentrates order flow toward retailers with integrated agronomy software rather than independent distributors relying on seasonal field calls.
Global Fertilizers Market Segmentation
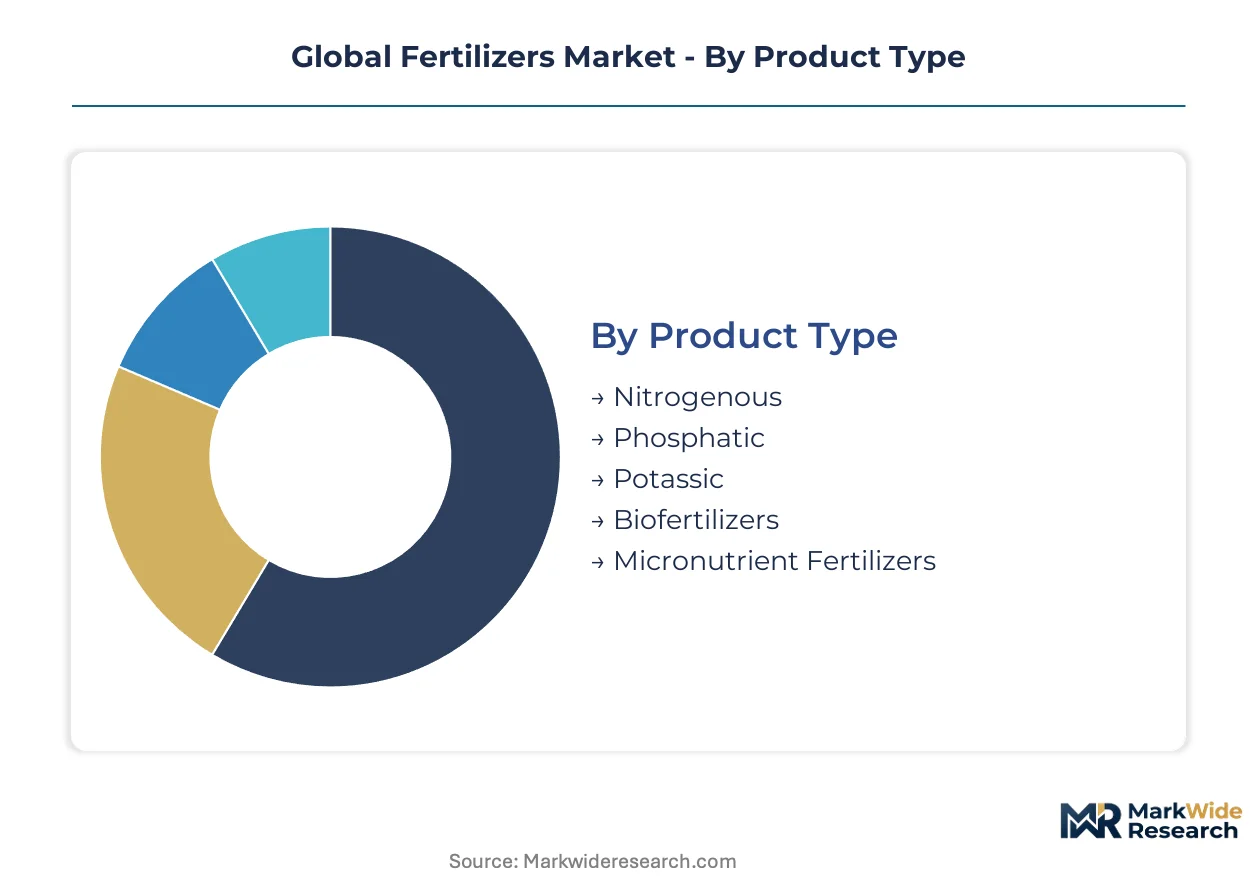
Segmentation in fertilizers reveals how nutrient chemistry, crop specificity, and procurement channels create distinct margin pools and loyalty patterns. Manufacturers align R&D pipelines and distribution investments against these divides to defend position in volatile feedstock markets.
Product Type:
Replacement cycles vary dramatically across product chemistry, with nitrogenous grades demanding annual reapplication while biofertilizers establish multi-season soil biology that extends repurchase intervals.
- Nitrogenous:Ammonia-based formulations synthesized via Haber-Bosch process dominate volume throughput due to universal crop demand and established infrastructure. Indian wheat-rice belt procurement through state subsidy programs locks in baseline offtake from 146 million smallholder cooperatives, though Henry Hub gas price spikes compress blender margins.
- Phosphatic:Phosphate rock acidulation yields single and triple superphosphate grades where beneficiation technology determines cadmium compliance against tightening EU Fertilizing Products Regulation limits. Florida and Peruvian ore sources capture European procurement shifts as Moroccan suppliers upgrade washing circuits.
- Potassic:MOP and SOP grades from Saskatchewan and Belarusian evaporation operations supply chloride-sensitive horticulture zones.
- Biofertilizers:Microbial inoculant formulations gain EFSA and India's FSSAI clearance for organic system integration.
- Micronutrient Fertilizers:Zinc, boron, and manganese blends address deficiency corrections in precision agriculture protocols.
Nitrogenous fertilizers sit at the top of the volume ranking, with biofertilizers climbing the fastest as regulatory pathways mature for commercial microbial deployment.
Application:
Margin capture diverges sharply between commodity grain belts and specialty crop zones, with horticulture commanding premium pricing for controlled-release formulations while cereal applications prioritize cost minimization.
- Cereal Crops:Wheat, rice, and corn cultivation in India's Indo-Gangetic plain and US Midwest corn belt drives bulk urea and DAP offtake through state trading corporations and cooperative elevators. Volume concentration here forces price discipline that limits branded premium capture.
- Horticulture:Vegetable and fruit operations in Spain's Almería province and California's Central Valley adopt polymer-coated nitrogen and micronutrient sachets to synchronize nutrient release with precision irrigation scheduling, supporting 40-60% price premiums over commodity grades.
- Oilseed Crops:Brazilian soybean cooperatives expand controlled-release applications to reduce leaching under watershed protection mandates.
- Pulses:Rhizobium inoculant compatibility creates biofertilizer entry points in Australian lentil and Indian chickpea rotations.
- Plantation Crops:Oil palm and rubber estates in Indonesia and Vietnam source bulk potassic shipments through long-term offtake contracts.
Cereal crops anchor absolute volume demand, while horticulture generates the steepest margin expansion trajectory through specialty formulation premiums.
End User:
Procurement sophistication scales with operational scale, fragmenting vendor strategies between technical agronomy support for cooperatives and price-optimized bulk supply for independent farmers.
- Farmers:Individual operators below 50 hectares rely on seasonal credit terms and dealer field calls, creating loyalty vulnerability to price undercutting during planting windows.
- Agricultural Cooperatives:Brazilian soybean and North American corn belt collectives consolidate procurement volumes that command direct manufacturer pricing and embedded agronomy software subscriptions.
- Contractors:Custom application services in Ukraine and Argentina bundle nutrient programs with equipment fleets, shifting product selection toward compatibility with variable-rate spreaders.
- Government Agencies:India's Fertilizer Ministry and Ethiopia's Agricultural Transformation Agency administer subsidy distribution and strategic reserve management.
Agricultural cooperatives concentrate procurement volume power, with contractors gaining share fastest as custom application services expand across Black Sea and South American grain zones.
Distribution Channel:
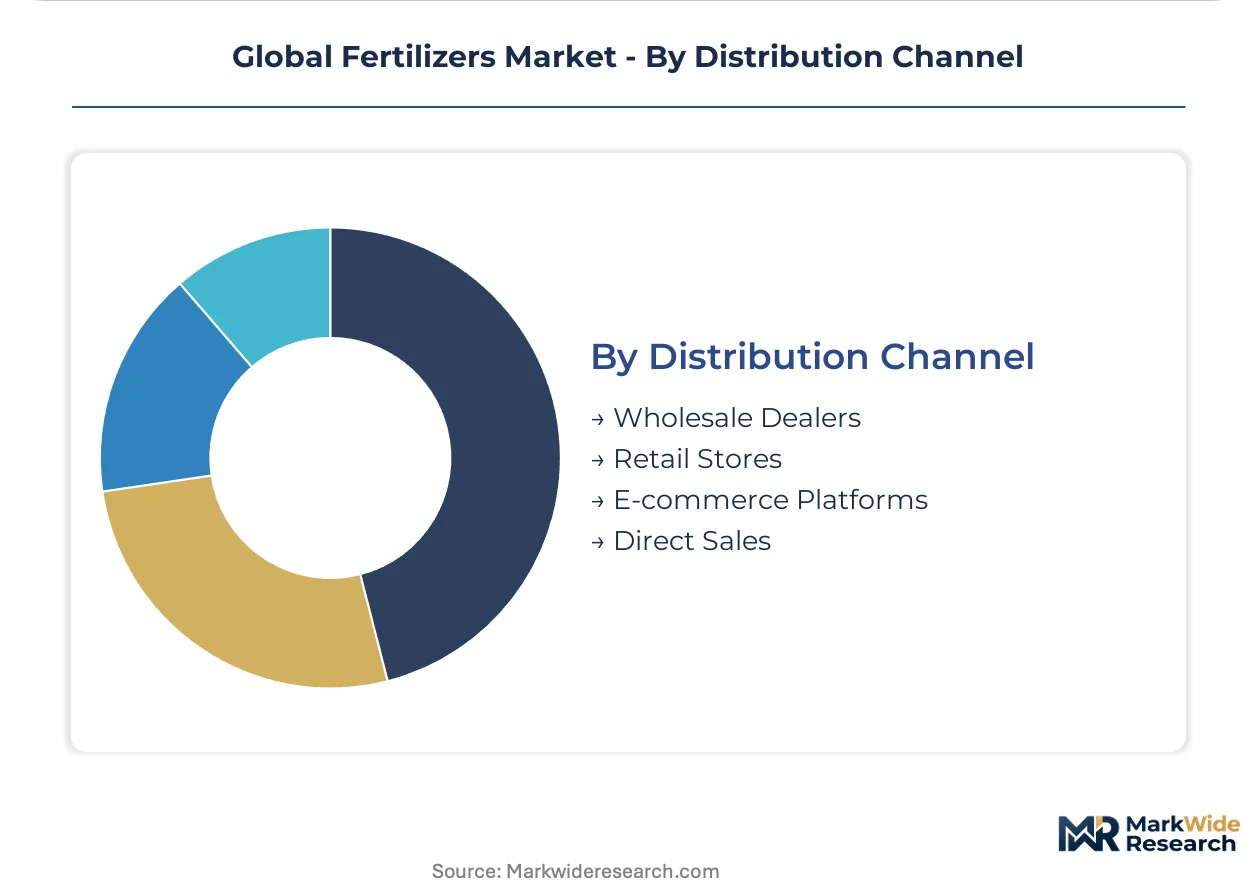
Channel economics reflect working capital intensity and technical service requirements, with digital platforms disrupting traditional cooperative committee purchasing in developed markets while wholesale networks retain dominance in credit-constrained emerging economies.
- Wholesale Dealers:Regional distributors with warehouse networks and seasonal credit facilities dominate African and South Asian procurement, though inventory risk exposure to currency volatility constrains product range breadth.
- Retail Stores:Farm supply cooperatives and independent dealers in US Midwest and Australian wheat belts sustain relationships through embedded agronomist staffing and loyalty program structures.
- E-commerce Platforms:Direct-to-grower digital subscriptions displace traditional procurement in Canada's prairie provinces and Australia's wheat belt, bundling nutrient programs with satellite imagery analytics.
- Direct Sales:Manufacturer field teams serve Brazilian soybean cooperatives and large-scale plantation operators with volume pricing and custom blending services.
Wholesale dealers retain volume leadership in emerging market penetration, with e-commerce platforms expanding most quickly among younger farm operators in developed agricultural economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's wheat-rice belt channels more subsidized urea than Brazil's entire soybean sector imports, yet both markets now confront watershed nitrogen limits that redirect procurement toward controlled-release formulations.
United States
Corn belt cooperatives in Iowa and Illinois consolidate procurement volumes exceeding 40 million metric tons annually. EPA Clean Water Act enforcement in Chesapeake Bay and Mississippi River watersheds caps per-acre nitrogen dosing for row-crop operators. Precision agriculture clusters in Nebraska and Kansas deploy variable-rate spreaders that synchronize nutrient application with real-time soil sensor data.
Brazil
Soybean cooperatives in Mato Grosso and Paraná states expand polymer-coated urea programs to reduce leaching under state environmental mandates. ANVISA and state agricultural secretaries tighten buffer zone requirements for fertilizer storage facilities near water bodies. The Cerrado agricultural frontier around Rondonópolis anchors controlled-release nitrogen trials for double-crop soybean-corn rotations.
India
The Indo-Gangetic plain consumes over 60 percent of national fertilizer volume through Nutrient Based Subsidy channels administered by the Fertilizer Ministry. State trading corporations import DAP through Paradip and Kandla ports for redistribution to 146 million smallholder cooperatives. Punjab and Haryana rice-wheat systems face groundwater depletion pressures that accelerate micro-irrigation and fertigation adoption.
China
Shandong and Hebei provinces maintain ammonia synthesis capacity serving domestic cereal and horticulture demand. MEE emission standards and dual carbon goals force coal-to-gas feedstock conversions at nitrogenous fertilizer complexes. The Yangtze River Delta specialty crop zone around Shanghai sources premium compound fertilizers for protected vegetable cultivation.
Germany
The Rhine-Ruhr industrial corridor hosts blending operations distributing low-cadmium phosphate formulations compliant with EU Fertilizing Products Regulation limits. ECHA REACH registrations and CE-marking requirements extend certification timelines for recycled nutrient products entering member state markets. Bavarian potato and sugar beet cooperatives pilot precision nitrogen tools to meet Fertilizer Ordinance reduction targets.
Global Fertilizers Market Competitive Landscape
North American producers anchor one tier; European and Middle Eastern specialists hold differentiated positions in premium nitrogen and phosphate segments. The vendor base concentrates around integrated miners with captive ore supply and regional blenders dependent on imported feedstock. Three archetypes dominate: vertically integrated resource owners with retail distribution networks, nitrogen specialists with coastal ammonia export terminals, and phosphate rock miners with beneficiation technology advantages. Competitive moves center on backward integration into mining assets and forward integration into precision agriculture software platforms.
Within the integrated resource tier, Nutrien Ltd. and The Mosaic Company exemplify divergent geographic anchoring strategies. Nutrien represents the North American model combining Saskatchewan potash mining with farm belt retail networks. Mosaic occupies the phosphate-specialist position with Florida mining operations and premium micronutrient blending capabilities. Yara International ASA sits within the European nitrogen archetype, leveraging Norwegian ammonia capacity for specialty product competition in Asian horticulture zones.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| Yara International ASA |
| CF Industries Holdings, Inc. |
| ICL Group Ltd. |
| K+S Aktiengesellschaft |
| Grupa Azoty |
| OCP Group |
| SQM S.A. |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Morocco and Russia anchor phosphate rock supply, while private-equity-rolled-up North American retailers consolidate procurement volumes that command direct manufacturer pricing. This ownership fragmentation creates divergent pricing discipline: state-controlled miners prioritize long-term offtake security over spot maximization, whereas financialized distributors extract working capital efficiencies that compress blender margins.
Pricing Analysis
Capacity additions in the Middle East and North Africa are reshaping price floors for ammonia-based nitrogenous grades. Three-tier pricing structure across premium, standard, and economy levels separates polymer-coated controlled-release formulations from commodity urea and subsidized DAP distributed through Indian state trading corporations. Price differentiation hinges on cadmium certification tiers under EU Fertilizing Products Regulation limits and volume scale at Brazilian soybean cooperatives. Cost compression in standard-grade phosphatic products is intensifying because Moroccan beneficiation upgrades lag compliance deadlines. Smallholder farmers in India's wheat-rice belt exhibit highest price sensitivity due to fixed retail urea prices under Nutrient Based Subsidy schemes, while horticulture operators in Spain's Almería province accept premium positioning for precision-compatible micronutrient blends.
Supply Chain Analysis
Skilled technician availability constraints in Saskatchewan potash evaporation operations and Florida phosphate beneficiation facilities limit throughput expansion despite ore reserve abundance. Supply concentrates in Morocco, Russia, and the United States for phosphate rock; Belarus, Canada, and Russia for potash; and China, India, and the United States for nitrogenous synthesis. Raw material dependencies center on natural gas feedstock for Haber-Bosch ammonia production, sulfuric acid for phosphate acidulation, and specialized polymer resins for controlled-release coating systems. Single-source vulnerability runs through OCP Group's dominance of low-cadmium ore export capacity. Distribution runs through agricultural cooperatives in developed markets and wholesale dealer networks with seasonal credit facilities in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier shifts toward controlled-release and micronutrient formulations that command certification-linked pricing premiums. Cost-down drivers include renewable ammonia pilot projects that promise carbon-intensity credentials for export market access.
For Market Incumbents: Anchor retail distribution relationships through embedded agronomy software subscriptions that lock in Brazilian and North American cooperative procurement committees. Defend against digital-platform disintermediation by acquiring precision agriculture hardware capabilities and securing backward integration into low-cadmium phosphate ore sources ahead of EU Fertilizing Products Regulation staged reductions. For New Entrants and Emerging Players: Direct-to-grower digital platforms offer the most penetrable route into Australia's wheat belt and Canada's prairie provinces where younger farm operators displace traditional cooperative purchasing. Target East African contract farming schemes in Ethiopia and Tanzania with micronutrient sachet formulations and mobile soil testing services bundled through agtech partnerships. Pursue regulatory clearance pathways for rhizobium and azotobacter biofertilizer formulations in India and European organic systems. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders lacking captive ore supply but possessing established wholesale networks in subsidy-dependent markets. Long-term viability favors integrated resource owners with beneficiation technology advantages and coastal ammonia export terminal access. Monitor renewable ammonia project commissioning announcements in Norway and Chile as inflection indicators for carbon-intensity certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captures low-cadmium ore reserves ahead of EU Fertilizing Products Regulation 2028 compliance deadlines. |
| Renewable Ammonia Pilot Development | Secures carbon-intensity certifications for premium nitrogen exports to European and Asian horticulture zones. |
| Precision Agriculture Platform Acquisition | Locks in direct-to-grower relationships through bundled nutrient programs with satellite imagery analytics. |
| Biofertilizer Regulatory Clearance | Opens organic system penetration as EFSA and India's FSSAI expand microbial inoculant approval pathways. |
| East African Distribution Network Buildout | Captures fragmented smallholder demand through micronutrient sachets and mobile soil testing services. |
Research Methodology
Multiple input streams — executive interviews with fertilizer manufacturing plant managers, procurement leads at Brazilian soybean cooperatives, and Indian state trading corporation distribution officers; secondary validation against customs and trade data, SEC 10-K filings, and Fertilizer Association of India consumption reports; and technical R&D director consultations — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured operational metrics from ammonia synthesis complexes, phosphate beneficiation facilities, and potash evaporation operations across the value chain.
Historical volume trajectories were cross-referenced against panel input from regional distribution heads to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product chemistry tier, crop application type, end-user scale category, and distribution channel format. CAGRs were derived from feedstock cost curve analysis and subsidy program budget allocations. Forecast inputs incorporated natural gas price volatility scenarios and EU cadmium limit compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for electrolysis-based renewable ammonia would alter the outlook if hydrogen feedstock costs compress faster than projected. Practitioners should monitor EPA Clean Water Act enforcement intensity in Chesapeake Bay and Mississippi River watersheds, EU Fertilizing Products Regulation certification timeline delays, and Indian Nutrient Based Subsidy budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Phosphate Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
France Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
United States Fertilizers Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Global Potash Fertilizer Market