
 South America Fertilizers Market | 2026-2036
South America Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fertilizers Market Analytics
Consolidation among Brazilian commercial farms is realigning procurement leverage across the South America fertilizers landscape. Yara International ASA dominates coastal distribution networks through its Brazilian blending facilities. The Mosaic Company leverages its phosphate rock access from Peru to sustain supply continuity for Andean buyers. SQM anchors specialty potassium and nitrate output for Chilean and Argentine vegetable exporters.
Fertilizers are nutrient-dense chemical or organic compounds formulated with specified N-P-K ratios, typically manufactured through Haber-Bosch ammonia synthesis or phosphate rock acidulation, designed to replenish soil macronutrients and micronutrients for commercial crop production. NPK complexes command the largest volume share due to their multi-nutrient efficiency in soybean and corn rotations. Urea competes aggressively on price per unit nitrogen, though volatility in natural gas feedstock costs compresses margin stability for merchants. Calcium ammonium nitrate occupies a narrower but defensible position among specialty crop growers and greenhouse operators seeking lower volatilization losses.
ANVISA and Brazil's Ministry of Agriculture enforce contaminant thresholds on imported phosphate rock, while Argentina's Senasa monitors fertilizer residue limits for export-bound grain. These frameworks elevate compliance costs for traders but create structural preference for certified suppliers with integrated quality laboratories. Stakeholders must monitor evolving traceability mandates and carbon border adjustment discussions in European destination markets that condition access for South American agricultural exports.
Market Dynamics
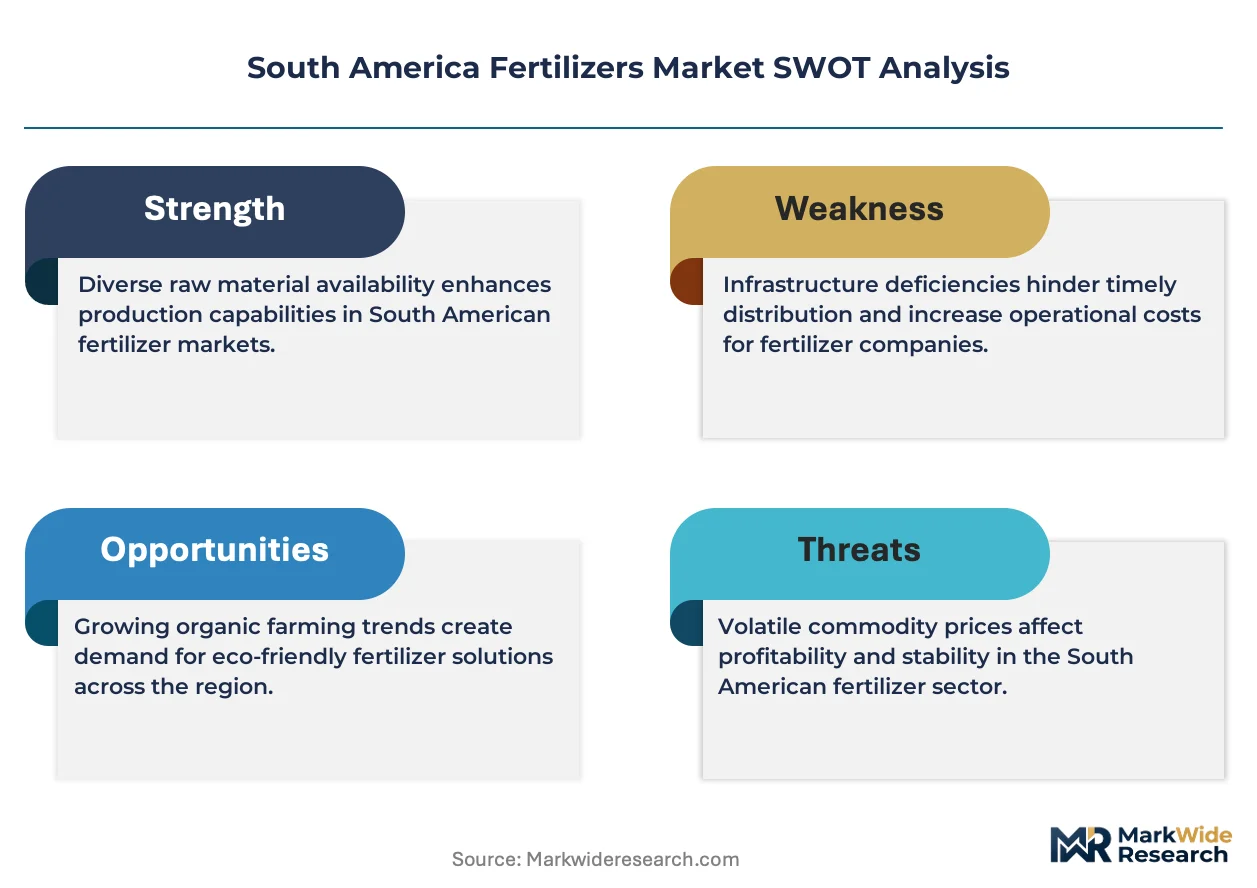
ANVISA's tightening cadmium and arsenic thresholds on phosphate rock imports are forcing Brazilian blenders to rebuild supplier qualification protocols and absorb elevated laboratory testing costs. This regulatory compression is reshaping procurement hierarchies across the continent's largest fertilizer market.
Growth Catalysts
- ANVISA contaminant enforcement:Stricter thresholds on heavy metals in phosphate imports are accelerating investment in certified laboratory infrastructure among Brazilian distributors.
- Soybean expansion in Cerrado:Double-cropping intensity across Mato Grosso and Goiás is pulling higher NPK application rates per hectare.
- Controlled-release formulations:Polymer-coated urea adoption is spreading among precision agriculture operators seeking volatilization reduction.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis margins compress when Henry Hub and Bolivian pipeline contracts spike, destabilizing urea pricing.
- Peruvian phosphate concentration:Andean supply dependence creates single-point vulnerability for Chilean and Ecuadorian NPK blenders.
- Port infrastructure congestion:Santos and Paranaguá terminal bottlenecks extend inventory cycles for imported raw materials.
Strategic Opportunities
- Uruguay's underpenetrated rice belt:The country's eastern wetlands present untapped demand for calcium ammonium nitrate in flooded paddy systems.
- Brazilian biofertilizer registration pathway:MAPA's streamlined microbial inoculant approval process opens formulation diversification for domestic manufacturers.
- Direct-to-farm digital platforms:E-procurement channels are collapsing traditional distributor tiers in Argentina's Pampas region.
Industry Challenges
- Soil science specialization scarcity:Agronomists with precision nutrient mapping expertise command premiums that mid-size cooperatives cannot match.
- ANVISA certification timelines:New product registrations now require eighteen-to-twenty-four month laboratory validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fertilizers Market |
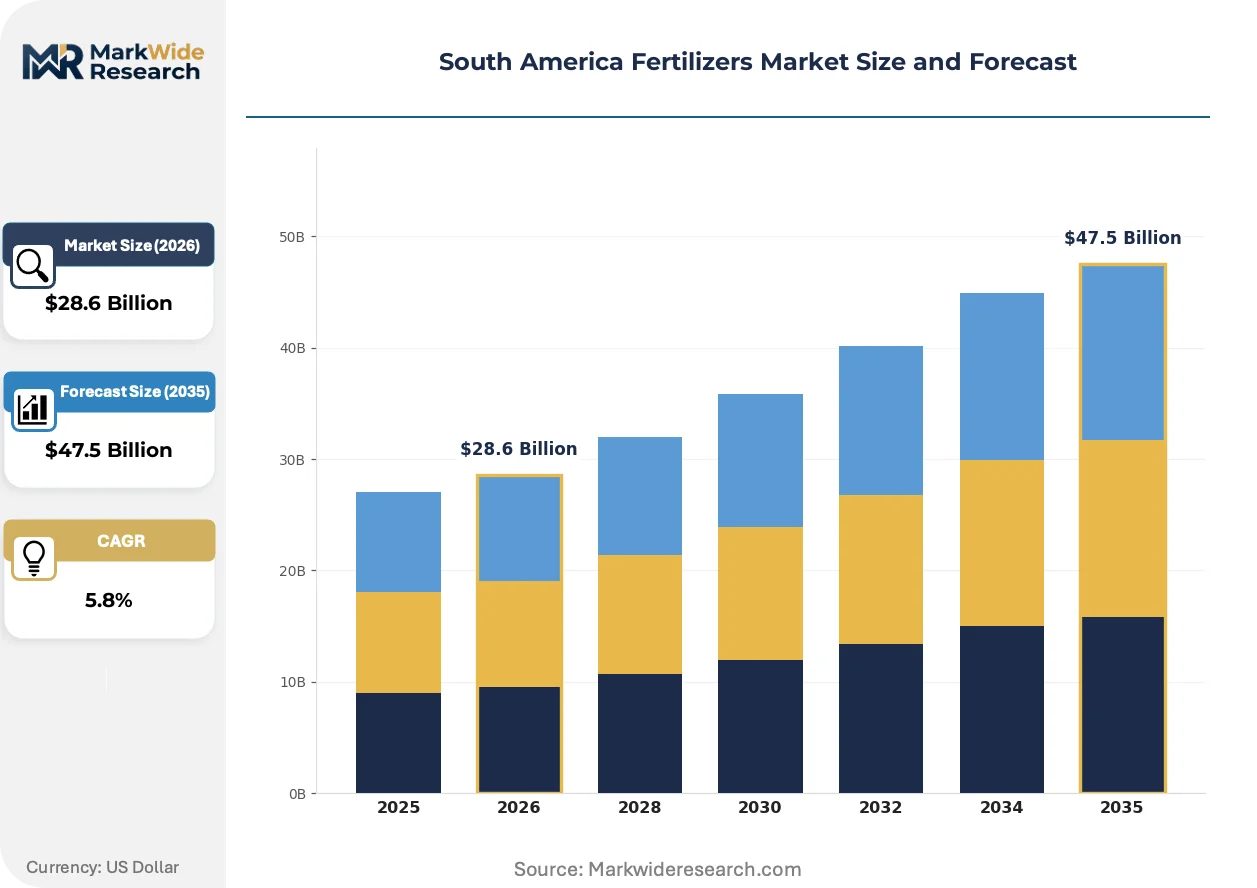
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, NPK, Calcium Ammonium Nitrate Application: Corn, Soybeans, Wheat, Vegetables Distribution Channel: Direct Sales, Retail, E-commerce, Cooperative End User: Agricultural Producers, Commercial Farms, Greenhouses, Specialty Crop Growers |
| Companies Covered | ICL Group Ltd, EuroChem Group, Yara International ASA, OCP Group, Sociedad Química y Minera (SQM), The Mosaic Company, K+S Aktiengesellschaft, Petrobras, Nutrien Ltd., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fertilizers Market Evolving Landscape
Digital soil mapping and variable-rate application systems are compressing the information gap between fertilizer manufacturers and farm-level nutrient management. These tools are redistributing technical authority across the value chain.
Variable-rate spreader technology is decentralizing agronomic decision-making from centralized cooperative agronomists to individual farm operators. Large soybean producers in Mato Grosso are deploying tractor-mounted sensors that adjust NPK blends in real time. This diffusion is compressing the role of traditional blending facility advisors.
ANVISA's 2024 update to Portaria 601 is mandating lot-level traceability documentation for all imported phosphate rock entering Brazilian territory. Blending facilities must now maintain chain-of-custody records from mine origin to final formulation. Argentine exporters supplying European grain markets are accelerating compliance investments to preempt EU carbon border adjustment mechanisms.
Cooperative procurement consolidation is displacing independent distributor networks across the southern Brazilian states. Large farming syndicates in Rio Grande do Sul now negotiate directly with Yara and Mosaic for volume-contracted NPK formulations. This concentration is most visible in the soybean-corn rotation belts where input costs represent thirty-five percent of operational expenditure.
South America Fertilizers Market Segmentation
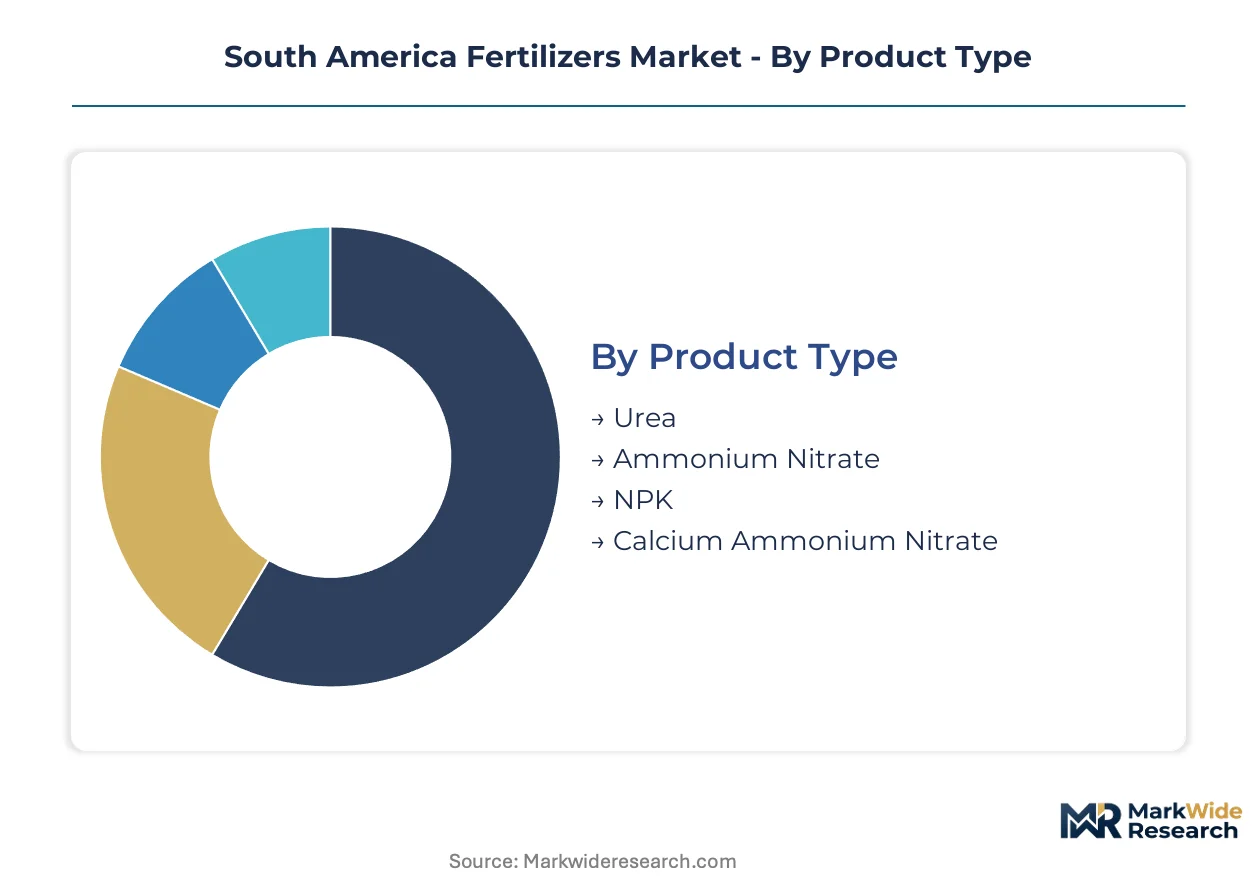
Fertilizer segmentation in South America reflects distinct agronomic cycles and procurement hierarchies. Product formulation choices track crop-specific nutrient uptake patterns, while distribution channel selection correlates with farm scale and credit access.
Product Type:
Replacement cycles for fertilizer formulations accelerate when soil testing reveals nutrient depletion thresholds. Brazilian soybean operators rotate between urea top-dressing and NPK base dressing based on residual phosphorus levels in Cerrado soils.
- Urea:A 46% nitrogen granular formulation synthesized via Haber-Bosch ammonia conversion. Demand concentrates in Mato Grosso double-cropping systems where growers apply 150-200 kg/ha during corn's vegetative stage, constrained by natural gas price volatility at Petrobras ammonia plants.
- NPK:Multi-nutrient complexes with tailored nitrogen-phosphorus-potassium ratios, typically 20-20-20 or 15-30-15 for soybean establishment. Brazilian Cerrado commercial farms specify blend ratios through direct Yara and Mosaic contracts, driven by precision agriculture adoption requiring variable-rate compatibility.
- Ammonium Nitrate:High-nitrogen soluble granules with 34% N content and explosive handling restrictions. Argentine Pampas wheat producers favor this formulation for rapid nitrogen uptake during tillering phases.
- Calcium Ammonium Nitrate:A 27% nitrogen compound with 8% calcium content and lower volatilization profile. Chilean vegetable exporters in O'Higgins Region specify this grade for greenhouse tomato and pepper production.
NPK complexes sit at the top of the volume ranking, with calcium ammonium nitrate climbing the fastest among specialty segments.
Application:
Cost tier differentiation separates commodity grain applications from high-value specialty crop inputs. Vegetable and fruit applications command premium formulation prices due to micronutrient enrichment and controlled-release coating requirements.
- Soybeans:Brazil's dominant oilseed absorbs 60% of regional phosphate consumption, with phosphorus-hungry Cerrado soils demanding 400-500 kg/ha of P2O5 over three-year rotations. Goiás and Mato Grosso operators negotiate annual volume contracts with blending facilities.
- Corn:Second-crop safrinha corn in Brazil's Center-West requires intensive nitrogen top-dressing at V6-V8 growth stages. Double-cropping intensity pulls 180-220 kg N/ha application rates, constrained by rainfall-dependent sidedressing windows.
- Wheat:Argentine Pampas winter wheat relies on split nitrogen applications with calcium ammonium nitrate at tillering and flag leaf stages. Buenos Aires and Córdoba provinces concentrate milling-quality production.
- Vegetables:Chilean export-oriented tomato, pepper, and lettuce operations in Valparaíso and Biobío regions specify soluble NPK formulations with chelated micronutrients for drip irrigation systems.
Soybeans anchor absolute volume consumption, though vegetables generate the steepest margin expansion trajectory per hectare.
Distribution Channel:
Customer type fragmentation splits procurement between consolidated commercial operators and fragmented smallholder networks. Large farming syndicates disintermediate traditional distributor tiers through direct manufacturer relationships.
- Direct Sales:Volume-contracted deliveries from Yara, Mosaic, and SGM blending facilities to farming cooperatives exceeding 10,000 hectares. Rio Grande do Sul and Mato Grosso syndicates negotiate formula pricing indexed to international urea benchmarks.
- Cooperative:Member-owned purchasing consortia aggregate small and mid-scale producer demand. Cotrijal and Coamo in southern Brazil maintain regional blending facilities with agronomic advisory services.
- Retail:Independent agricultural supply stores serving sub-500 hectare operations with bagged urea and standard NPK grades. Credit terms and delivery logistics determine retailer loyalty in Paraná and Santa Catarina.
- E-commerce:Digital platforms including Agrofy and Agrotop collapsing traditional distributor margins. Argentine Pampas operators increasingly compare real-time prices across multiple suppliers before procurement.
Direct sales channels capture the largest revenue concentration, with e-commerce gaining share fastest among younger farm operators.
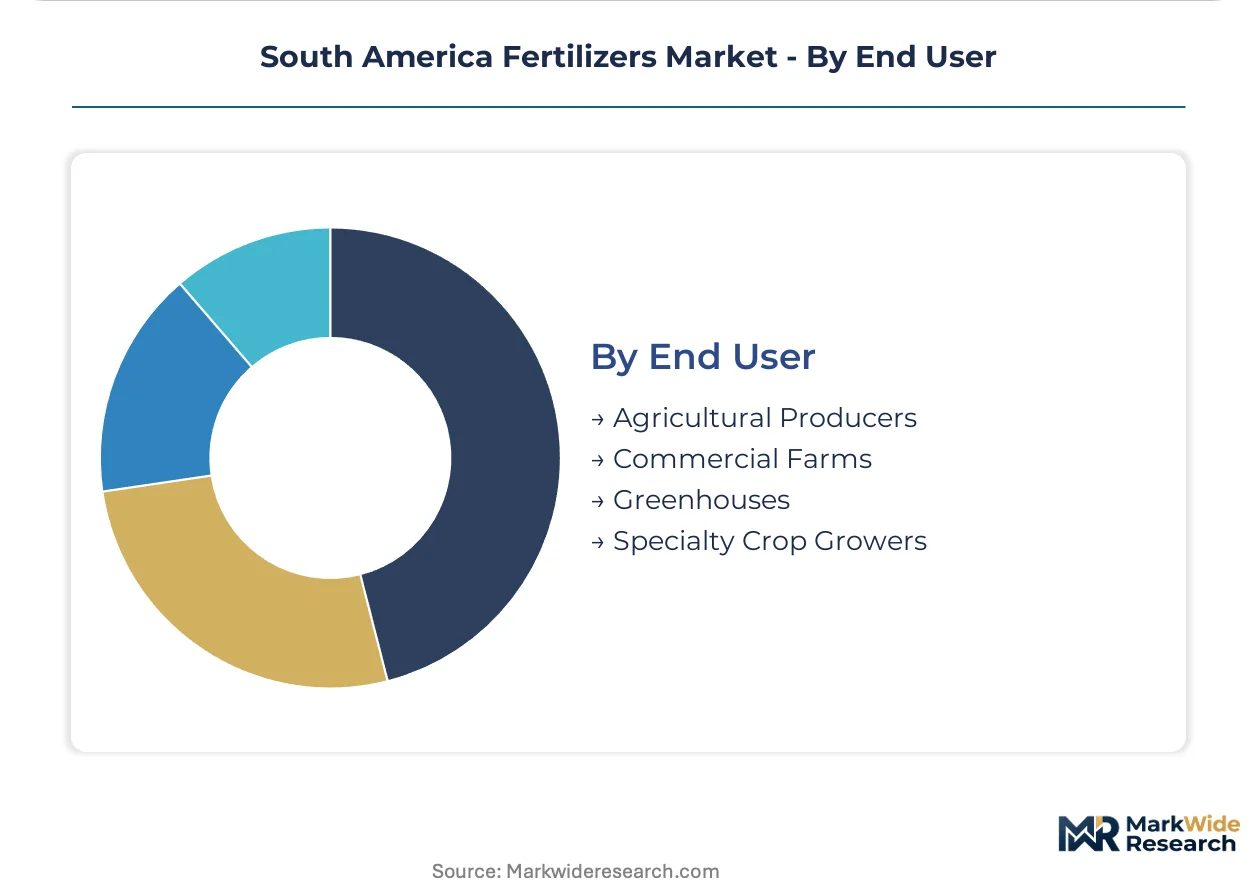
End User:
Geographic concentration of end users mirrors Brazil's agricultural frontier expansion and Argentina's Pampas grain belt density. Soil heterogeneity across these zones drives formulation customization requirements.
- Commercial Farms:Operations exceeding 5,000 hectares in Brazil's Cerrado and MATOPIBA frontier. SLC Agrícola and BrasilAgro deploy variable-rate spreaders with real-time sensor adjustment.
- Agricultural Producers:Mid-scale family operations of 500-2,000 hectares dominating Argentine wheat and soybean production. Buenos Aires province cooperatives supply technical assistance alongside input procurement.
- Greenhouses:Chilean hydroponic tomato and berry exporters in O'Higgins and Maule regions. Controlled-environment agriculture demands soluble fertilizers with electrical conductivity below 2.0 dS/m.
- Specialty Crop Growers:Uruguayan rice producers in eastern wetlands and Brazilian coffee operators in Minas Gerais. Calcium ammonium nitrate specifications dominate flooded paddy and acid soil applications.
Commercial farms command the dominant procurement volume position, with greenhouse operations expanding most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs larger fertilizer volumes than Argentina and Chile combined, though regulatory divergence across the three markets is fragmenting procurement strategies. ANVISA's contaminant thresholds reshape Brazilian import flows while Argentine cooperatives consolidate purchasing power. Chilean specialty crop exporters drive premium formulation demand.
Brazil
Mato Grosso and Goiás soybean operators pull 180-220 kg N/ha application rates for double-cropped safrinha corn. ANVISA's Portaria 601 mandates lot-level traceability for all phosphate rock entering Brazilian ports. Santos and Paranaguá terminal congestion extends inventory cycles for urea and NPK raw materials arriving from overseas suppliers.
Argentina
Buenos Aires and Córdoba wheat producers favor calcium ammonium nitrate for split nitrogen applications during tillering phases. Senasa monitors fertilizer residue limits for export-bound grain shipments to European markets. The Pampas grain belt concentrates demand for specialty blends through cooperative procurement channels displacing traditional distributor tiers.
Chile
O'Higgins and Maule region greenhouse operators specify soluble NPK formulations with electrical conductivity below 2.0 dS/m for hydroponic tomato and berry exports. The country's national agricultural regulator enforces quality standards for specialty potassium and nitrate outputs. Valparaíso and Biobío processing clusters anchor SQM's domestic distribution networks for vegetable exporters.
Peru
Andean phosphate rock extraction sustains supply continuity for Chilean and Ecuadorian NPK blenders dependent on imported raw materials. The country's mining ministry oversees environmental compliance for extraction operations in the Sechura Desert. Concentrated Andean supply creates single-point vulnerability for regional fertilizer manufacturers lacking alternative phosphate sources.
Uruguay
Eastern wetland rice producers present untapped demand for calcium ammonium nitrate in flooded paddy systems requiring lower volatilization profiles. The country's agricultural ministry promotes sustainable input practices for export-oriented grain production. Treinta y Tres and Rocha departments concentrate specialty crop cultivation with underpenetrated fertilizer application intensity relative to regional benchmarks.
South America Fertilizers Market Competitive Landscape
Brazilian producers anchor one tier; European and North American specialists hold formulation technology and coastal distribution advantages. The market structures around three distinct player categories: integrated mining-blending conglomerates with captive phosphate or potash access, coastal distribution specialists operating regional blending facilities, and state-backed energy-chemical hybrids leveraging ammonia synthesis capacity. Capacity expansion and direct-to-farm digital channel development represent the dominant competitive moves reshaping procurement hierarchies.
Among integrated resource holders, The Mosaic Company exemplifies upstream phosphate control feeding Andean supply chains, while Yara International ASA occupies a position as coastal distribution anchor with Brazilian blending facility networks. Nutrien Ltd. represents the scale-driven archetype with integrated retail and wholesale operations spanning multiple South American territories. These three entities collectively illustrate how backward integration into mining assets and forward integration into farm-level advisory services differentiate competitive positioning across price-volatile commodity and premium specialty formulation segments.
| Leading Market Players |
|---|
| ICL Group Ltd |
| EuroChem Group |
| Yara International ASA |
| OCP Group |
| Sociedad Química y Minera (SQM) |
| The Mosaic Company |
| K+S Aktiengesellschaft |
| Petrobras |
| Nutrien Ltd. |
| Others |
Value Network & Pricing Analysis
ANVISA's lot-level traceability mandates for phosphate rock imports are forcing Brazilian blenders to absorb elevated laboratory validation costs and rebuild supplier qualification protocols, compressing margins across the NPK formulation tier while accelerating procurement consolidation toward certified integrated suppliers.
Pricing Analysis
Capacity additions in Brazil's Center-West blending corridor are reshaping price floors for urea and NPK complexes. Contract-based long-term offtake agreements dominate procurement between commercial farming syndicates and coastal distributors, with price differentiation driven by volume scale and ANVISA certification tier. Cost compression in standard-grade formulations is intensifying because natural gas feedstock volatility at Petrobras ammonia plants destabilizes merchant margins. Smallholder cooperatives exhibit highest price sensitivity, while greenhouse operators in Chile's O'Higgins Region show lowest sensitivity due to micronutrient-enriched specialty requirements.
Supply Chain Analysis
Regional distribution centers in Santos and Paranaguá anchor hub-and-spoke patterns for imported urea and phosphate rock entering Brazilian territory. Geographic supply concentration centers on Peru for phosphate rock extraction, Bolivia for pipeline natural gas, and Trinidad and Tobago for ammonia feedstock. Raw material dependencies include phosphate rock acidulation, Haber-Bosch ammonia synthesis, and potash extraction from SQM's Chilean operations. Single-source vulnerability pervades Andean phosphate supply for Ecuadorian and Chilean blenders lacking alternative mine access. Distribution runs through cooperative procurement consortia displacing independent retail tiers across Argentina's Pampas grain belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in South American fertilizers rest on controlled-release formulation premiums and digital procurement channel compression of distributor markups.
For Market Incumbents: Lock in backward integration into Peruvian phosphate rock access or captive ammonia synthesis capacity to defend against merchant feedstock volatility. Secure ANVISA-certified laboratory infrastructure ahead of competitor qualification timelines. Channel control through direct-to-farm digital platforms in Argentina's Pampas region represents the critical defensive lever against e-commerce disintermediation. For New Entrants and Emerging Players: Launch via specialty calcium ammonium nitrate formulations targeting Uruguay's underpenetrated eastern wetland rice belt, where flooded paddy systems demand lower volatilization profiles absent from incumbent portfolios. Penetrate Chilean greenhouse vegetable exporters through soluble NPK grades with chelated micronutrients for drip irrigation systems. A technical agronomy advisory bundle accelerates adoption among precision agriculture operators lacking in-house soil science specialization. For Investors and Strategic Acquirers: Asymmetric upside sits with Brazilian biofertilizer manufacturers positioned for MAPA's streamlined microbial inoculant registration pathway. Five-to-ten year viability favors integrated mining-blending conglomerates with captive phosphate access and coastal distribution density. Watch for ANVISA certification timeline compression as inflection signal—accelerated approvals would unlock formulation diversification premiums for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Sechura Desert supply secures ANVISA-compliant feedstock for Andean blenders. |
| Controlled-Release Coating Technology Investment | Polymer-coated urea adoption spreads among Mato Grosso precision agriculture operators. |
| Direct-to-Farm Digital Platform Launch | Agrofy-style e-procurement collapses distributor margins in Argentine cooperative networks. |
| Biofertilizer Registration Pathway Navigation | MAPA's microbial inoculant stream opens formulation diversification for domestic manufacturers. |
| Certified Laboratory Infrastructure Expansion | ANVISA Portaria 601 compliance creates structural preference for integrated quality control. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Peru, and Uruguay, with primary inputs from each territory combining interviews with blending facility operators, cooperative procurement managers, agronomic advisors at commercial farming syndicates, and regulatory affairs specialists at ANVISA and Senasa. Secondary validation draws from customs and trade flow databases, SEC filings of listed fertilizer manufacturers, agricultural ministry production statistics, and port authority throughput records. Bottom-up volume modeling triangulates against top-down macroeconomic agricultural output projections.
Granularity-level modeling disaggregates demand across product type, application crop, distribution channel, and end-user farm scale throughout the forecast period. Segmentation dimensions include formulation grade tier, regional regulatory cluster, and precision agriculture adoption intensity. CAGRs derive from trend extrapolation of historical application rates, crop expansion patterns, and input cost elasticity estimates. Natural gas benchmark volatility and phosphate rock contaminant threshold evolution serve as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather disruption to Brazilian safrinha corn planting windows or abrupt Bolivian pipeline supply interruptions. Outputs reflect documented assumptions around regulatory enforcement consistency and cooperative consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market