
 Fertilizer Applicators Market | 2026-2036
Fertilizer Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Applicators Market Analysis
EPA nutrient management regulations are repositioning the cost-of-entry calculus for equipment manufacturers across North America. John Deere leverages its precision agriculture ecosystem to sustain technology leadership in variable-rate application systems. AGCO Corporation anchors its competitive stance through deep manufacturing scale in pneumatic distribution platforms. Kuhn Group differentiates via specialized European engineering heritage in liquid injection architectures.
Fertilizer applicators are mechanical or electro-hydraulic machines designed to distribute nutrient formulations at controlled rates, typically spanning working widths from 12 to 90 feet with application accuracy measured in pounds per acre or gallons per minute, serving the primary commercial purpose of optimizing crop yield while minimizing environmental runoff. Broadcast spreaders occupy the largest installed base across broadacre grain operations, though liquid applicators represent the fastest-growing configuration as farmers shift toward fertigation and side-dressing techniques. Electro-hydraulic technology segments command the strongest margin pools due to integration complexity with GPS-guided prescription maps and real-time soil sensor feedback loops.
USDA conservation compliance standards and EPA Clean Water Act provisions jointly shape equipment specifications, mandating buffer zone capabilities and documentation systems that manufacturers must embed at the design stage. The EU Green Deal's Farm to Fork strategy and REACH chemical registration requirements create parallel certification burdens for exporters serving European horticulture and turf management segments. Stakeholders must monitor how emerging state-level nitrate reduction mandates in the US and EU member country fertilizer ordinances fragment compliance requirements across their distribution footprints.
Market Dynamics
Precision agriculture adoption is compressing equipment replacement cycles across large-scale row-crop operations, forcing manufacturers to integrate GPS-guided prescription mapping and real-time soil sensor feedback loops into core product architectures. EPA nutrient management mandates are simultaneously raising the engineering bar for buffer zone documentation and variable-rate control systems.
Growth Catalysts
- USDA Conservation Compliance:Federal standards mandating nutrient management documentation drive demand for integrated application monitoring systems across Corn Belt operations.
- Variable-rate electro-hydraulics:GPS-guided prescription mapping enables pound-per-acre accuracy that reduces input waste and satisfies environmental audit requirements.
- Fertigation technique migration:Row-crop operators increasingly favor liquid side-dressing methods that demand specialized injection architectures and tank systems.
Market Restraints
- Steel and component volatility:Boom fabrication and pneumatic distribution systems face margin pressure from fluctuating alloy and hydraulic component input costs.
- Midwest manufacturing concentration:Fabrication capacity clusters in Illinois, Iowa, and Nebraska create geographic supply risk during regional logistics disruptions.
- Clean Water Act documentation burdens:EPA mandates require embedded sensor arrays and data logging systems that add baseline cost to every unit shipped.
Strategic Opportunities
- EU Green Deal Farm to Fork:REACH chemical registration and fertilizer ordinances create certified-equipment demand gaps for exporters serving European horticulture segments.
- Real-time sensor convergence:Integration of soil moisture probes with electro-hydraulic control valves enables closed-loop application adjustment without operator intervention.
- Turf management channels:Golf course and municipal park maintenance segments remain underpenetrated by precision liquid systems relative to broadacre grain operations.
Industry Challenges
- Electro-hydraulic technician scarcity:Integration of GPS, sensor feedback, and hydraulic control demands cross-trained service personnel that dealer networks struggle to recruit.
- Legacy controller incompatibility:Older tractor hydraulic systems lack the flow modulation precision required for variable-rate applicator heads, forcing expensive retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Applicators Market |
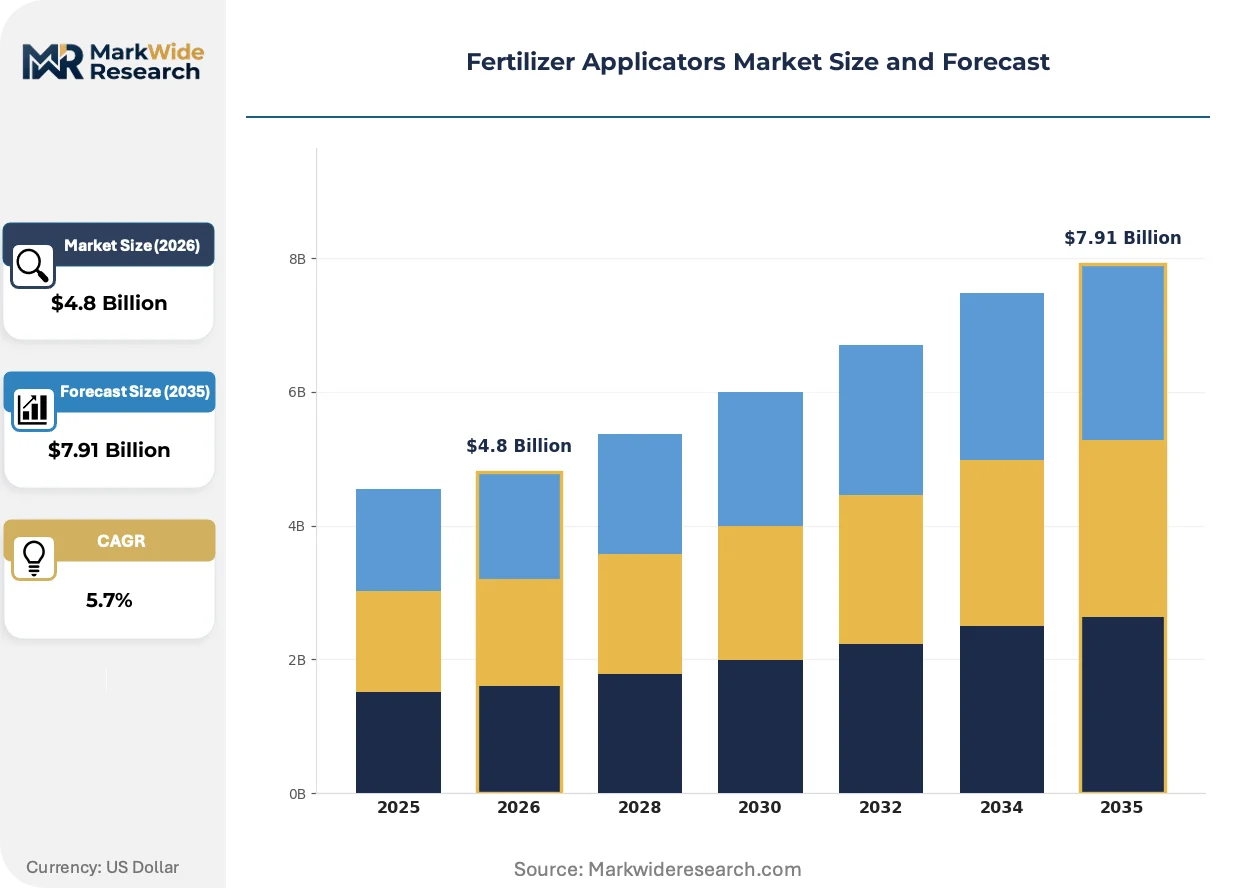
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadcast Spreaders, Drop Spreaders, Liquid Applicators, Granular Applicators End User: Agriculture, Horticulture, Forestry, Landscaping Technology: Mechanical, Pneumatic, Electro-Hydraulic, Manual Application: Crop Fertilization, Lawn Care, Garden Use, Turf Management |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kuhn Group, Kubota Corporation, Buhler Industries, Hardi International, Great Plains Manufacturing, Valmont Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Applicators Market Emerging Trajectories
Electro-hydraulic control architectures are displacing mechanical linkages as the dominant engineering paradigm, while regulatory documentation requirements and shifting procurement patterns reshape how equipment value is captured and delivered.
Real-time soil sensor integration is rewriting the competitive logic of application accuracy. These probe arrays measure moisture, organic matter, and residual nitrogen at 12-inch depth intervals, transmitting data to electro-hydraulic manifold controllers that adjust gallon-per-minute flow within 0.3 seconds. Large-scale operators in Illinois and Iowa are adopting these systems at replacement cycle points, compressing the payback justification from five seasons to two. The technology is rewriting margin structures by embedding subscription telemetry revenue into hardware sales.
EPA Clean Water Act provisions are mandating buffer zone geofencing and automated shutoff capabilities that manufacturers must certify before shipment. These provisions require GPS boundary mapping, nozzle-by-nozzle control, and tamper-evident data logging that satisfies third-party audit protocols. Liquid applicator configurations face the steepest compliance burden, driving engineering resource allocation toward injection pump and boom architecture redesigns.
Service contract unbundling is fragmenting how operators acquire application technology. Equipment purchasers increasingly separate hardware acquisition from telemetry subscriptions, seasonal calibration services, and prescription map generation. Dealer networks in Nebraska and Kansas are responding with tiered service packages that decouple capital expenditure from operational support. This pattern is most visible among 2,000-plus acre operations that internalize agronomic decision-making while outsourcing technical maintenance.
Fertilizer Applicators Market Segmentation
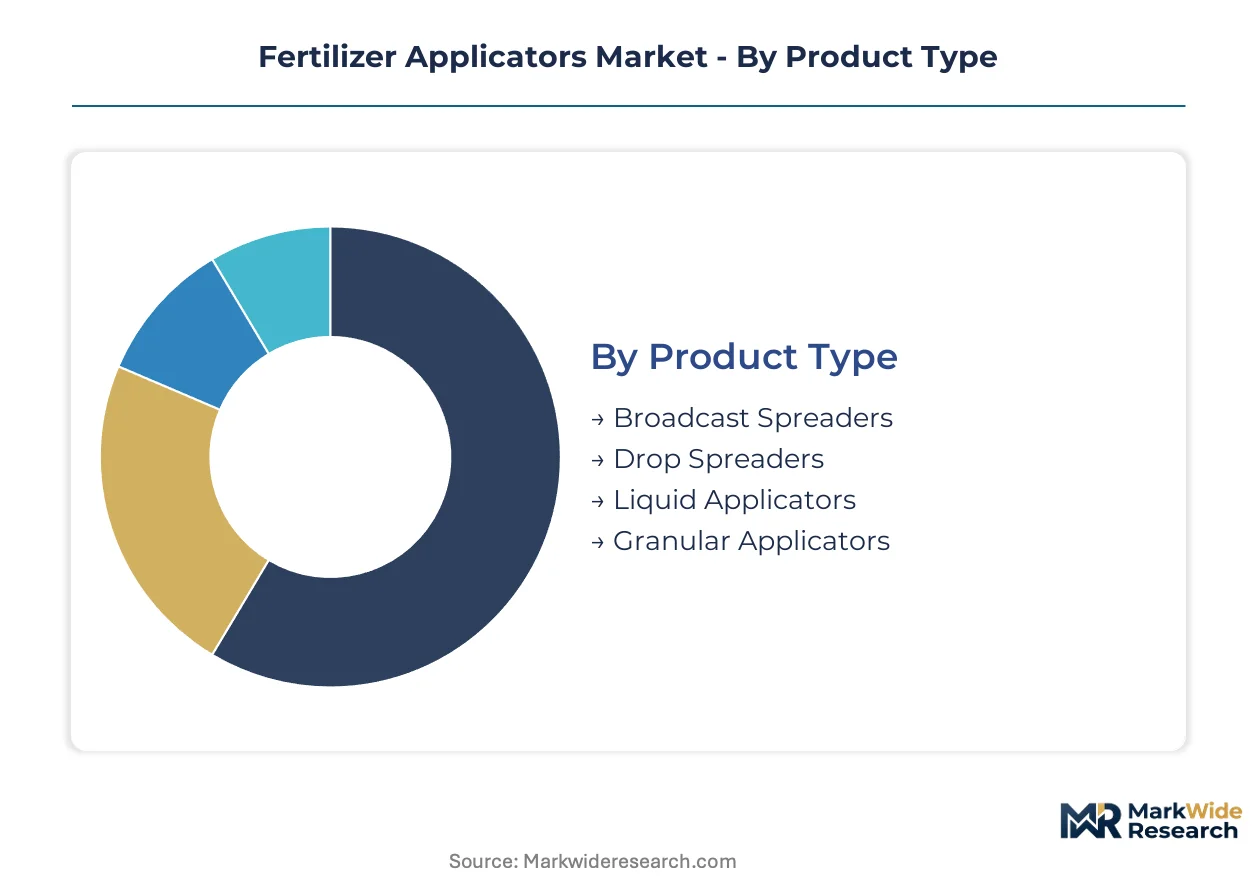
Equipment specification choices in fertilizer applicators cascade through capital expenditure, operating cost, and compliance posture. Segment boundaries align with farm scale, crop type, and regulatory jurisdiction rather than simple product taxonomy.
Product Type:
Working width and nutrient form dictate replacement timing and dealer service relationships.
- Broadcast Spreaders:Centrifugal or pendulum distribution mechanisms propel dry granules across 30- to 90-foot swaths. Corn Belt grain operations in Illinois and Iowa anchor installed base maintenance, though EPA buffer zone mandates accelerate controller retrofit demand.
- Liquid Applicators:Tank-mounted pump systems with boom-mounted injection nozzles deliver variable-rate gallons-per-minute precision. Side-dressing adoption in Nebraska and Kansas drives fastest segment expansion as operators shift from pre-plant to in-season nitrogen timing.
- Drop Spreaders:Gravity-fed metering delivers granules directly beneath the unit with minimal drift. Turf management contractors in municipal parks departments favor these units for phosphorus restriction zones.
- Granular Applicators:Pneumatic distribution systems convey prilled product through hose networks to multiple openers. Strip-till operations in the Dakotas specify these for deep-band placement below the seed row.
Volume sits with broadcast spreaders; growth tilts toward liquid applicators.
End User:
Operational scale and agronomic sophistication separate procurement patterns across buyer categories.
- Agriculture:Row-crop enterprises above 2,000 acres dominate equipment revenue, specifying electro-hydraulic integration with prescription mapping software. USDA conservation compliance documentation requirements embed monitoring systems as standard rather than optional.
- Horticulture:Vegetable and fruit operations in California's Central Valley and Florida's Ridge district demand specialized narrow-profile units for bedded crops. REACH chemical registration in EU export markets shapes stainless steel specification for food safety certification.
- Forestry:Post-harvest reforestation and mid-rotation fertilization of pine plantations in the US Southeast specifies high-flotation chassis and corrosion-resistant components for acidic soil conditions.
- Landscaping:Commercial grounds maintenance contractors prioritize maneuverability over capacity, with walk-behind and compact towable units serving golf course roughs and corporate campus applications.
Revenue concentrates in agriculture; horticulture commands the steepest technology premium.
Technology:
Control architecture determines margin structure and service contract attach rates.
- Electro-Hydraulic:GPS-guided valve manifolds modulate flow within 0.3-second response loops to soil sensor feedback. Large-scale operators in the Corn Belt specify these systems for variable-rate prescription execution and automated documentation.
- Pneumatic:Air-stream distribution of dry product enables uniform spacing across wide boom configurations. Manufacturing scale advantages in pneumatic platforms sustain competitive positioning for mid-market grain operations.
- Mechanical:Ground-drive linkages and fixed-rate metering dominate legacy installed base and entry-level price points. Replacement cycle compression pushes these configurations toward smaller hobby farms and rental fleets.
- Manual:Hand-cranked or push-type units serve garden-scale applications with minimal precision requirements. These products bypass dealer networks through retail and e-commerce channels.
Electro-hydraulic systems capture margin leadership; pneumatic platforms retain volume dominance in grain belts.
Application:
Timing and placement technique reshape equipment configuration requirements.
- Crop Fertilization:Pre-plant, side-dress, and fertigation timing options demand compatible tank systems, pump capacities, and boom heights. Corn and soybean rotations in the Midwest drive specification for high-clearance late-season nitrogen application.
- Turf Management:Golf course superintendents and sports field managers specify boomless nozzle configurations for undulating terrain. EU member country fertilizer ordinances fragment compliance requirements for equipment exporters serving European turf segments.
- Lawn Care:Residential and commercial lawn service operators favor compact broadcast spreaders with basic rate control. Seasonal demand concentration in spring and fall creates rental market opportunities.
- Garden Use:Small-scale vegetable and ornamental applications sustain demand for handheld and walk-behind units through farm supply retailers.
Equipment value concentrates in crop fertilization; turf management offers the most underpenetrated precision upgrade pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Corn Belt tax-incentive zones for precision agriculture equipment accelerate manufacturing concentration. Equipment fabrication clusters in Illinois, Iowa, and Nebraska draw from specialized supplier networks serving variable-rate application system demand.
United States
EPA Clean Water Act provisions mandate buffer zone geofencing and automated shutoff capabilities for liquid applicator configurations. USDA conservation compliance standards require embedded sensor arrays and tamper-evident data logging systems. Manufacturing gravity centers on Moline, Illinois and Omaha, Nebraska, where electro-hydraulic control valve production scales to serve 2,000-plus acre row-crop operations.
Germany
EU Green Deal Farm to Fork strategy and REACH chemical registration requirements create certified-equipment demand for horticulture exporters. ECHA fertilizer ordinances fragment compliance specifications across member state jurisdictions. Stuttgart and Munich industrial corridors anchor pneumatic distribution platform engineering for strip-till deep-band placement systems serving Eastern European grain markets.
Brazil
Cerrado expansion and double-crop soybean rotations compress equipment replacement cycles for high-capacity broadcast spreaders. ANVISA agricultural chemical registration timelines shape liquid applicator specification for side-dressing nitrogen timing. São Paulo state manufacturing clusters produce corrosion-resistant chassis configurations for acidic soil conditions in Mato Grosso and Goiás production zones.
Canada
Prairie Provinces carbon tax incentives for precision agriculture adoption drive variable-rate electro-hydraulic system procurement across Saskatchewan and Alberta grain belts. Health Canada PMRA buffer zone documentation requirements parallel EPA mandates for cross-border equipment certification. Winnipeg and Regina fabrication centers specialize in high-flotation chassis for post-harvest reforestation applications in British Columbia pine plantations.
Australia
Murray-Darling Basin nutrient management plans mandate pound-per-acre accuracy for dryland wheat operations facing water allocation constraints. TGA-equivalent state-level fertilizer ordinances in New South Wales and Victoria require GPS-guided prescription mapping integration. Toowoomba and Dubbo equipment dealerships concentrate liquid applicator maintenance capacity for cotton fertigation systems in Queensland irrigation districts.
Fertilizer Applicators Market Vendor Landscape
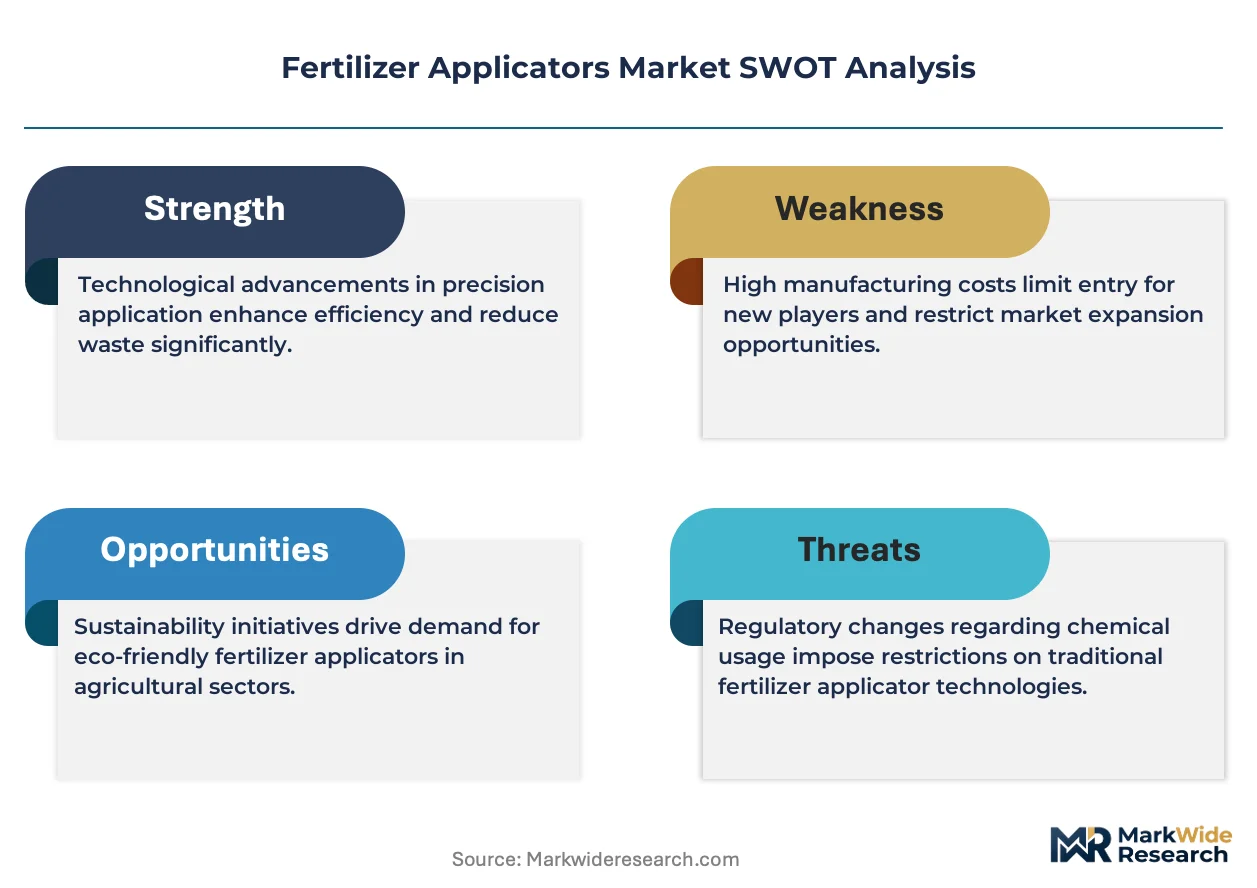
Diversified conglomerates compete with focused pure-play specialists across technology tiers in fertilizer applicator supply. Consolidation pressure concentrates electro-hydraulic control architecture development among precision agriculture ecosystem integrators. Three archetypes dominate: full-line agricultural equipment manufacturers with telemetry subscription platforms, pneumatic distribution specialists with manufacturing scale advantages, and liquid injection engineering houses with European heritage. Competitive moves center on strategic partnerships for sensor integration and geographic expansion into EU Green Deal compliance-certified segments.
Among North American full-line manufacturers, John Deere, CNH Industrial, and AGCO Corporation exemplify diversified conglomerate positioning. John Deere anchors precision agriculture ecosystem integration through its Moline, Illinois headquarters concentration. CNH Industrial occupies structural positioning across Case IH and New Holland brand architectures. AGCO Corporation represents manufacturing scale leverage in pneumatic distribution platforms through its Jackson, Minnesota fabrication complex.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kuhn Group |
| Kubota Corporation |
| Buhler Industries |
| Hardi International |
| Great Plains Manufacturing |
| Valmont Industries |
| Others |
Supply Flow & Price Mechanics
Electro-hydraulic certification tiers split the Fertilizer Applicators Market into divergent pricing strata, where EPA-compliant variable-rate systems command substantial premiums over mechanical legacy configurations while sourcing identical hydraulic valve blocks from Moline, Illinois and Omaha, Nebraska fabrication clusters. This bifurcation concentrates margin capture among telemetry-integrated OEMs and compresses commodity spreader pricing toward alloy input cost floors.
Pricing Analysis
Short lead-time premiums distinguish electro-hydraulic configurations ordered for immediate Corn Belt planting windows from spot-inventory mechanical units liquidated through dealer auction channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and telemetry subscription bundling, with USDA conservation compliance documentation requirements driving price differentiation toward audited variable-rate systems. Cost compression in pneumatic distribution platforms is intensifying because steel alloy volatility erodes fabrication margins. Mid-market grain operations in Iowa and Nebraska exhibit highest price sensitivity, while 2,000-plus acre operators accepting prescription mapping bundles show lowest elasticity.
Supply Chain Analysis
Welding technician scarcity across Illinois, Iowa, and Nebraska fabrication corridors constrains boom assembly throughput and extends order backlogs for high-clearance liquid applicator configurations. Supply draws from specialized hydraulic component suppliers in Moline, pneumatic distribution engineering in Jackson, Minnesota, and corrosion-resistant chassis fabrication in São Paulo state for Brazilian Cerrado exports. Raw material dependencies center on alloy steel for boom structures, electro-hydraulic control valves for precision manifolds, and corrosion-resistant coatings for acidic soil applications. Single-source vulnerability concentrates in GPS guidance module procurement from limited semiconductor fabricators. Distribution runs through manufacturer-owned dealer networks in the Corn Belt and independent agricultural equipment distributors in export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabrication capacity constraints across Midwest welding corridors prop pricing power for electro-hydraulic configurations, with EPA documentation mandates preventing rapid supply response.
For Market Incumbents: Anticipate margin erosion from emerging liquid injection specialists by deepening backward integration into hydraulic valve production and securing exclusive telemetry platform partnerships with prescription mapping software providers. Capacity addition in São Paulo state addresses Brazilian Cerrado demand while hedging Midwest labor tightness. Certification investment in EU Green Deal Farm to Fork compliance creates export moats against European pneumatic specialists. For New Entrants and Emerging Players: Launch via turf management channel partnerships targeting golf course superintendents in Florida and California, where precision liquid systems remain underpenetrated relative to broadacre grain saturation. Geographic white space concentrates in Australian cotton fertigation districts facing Murray-Darling Basin nutrient accuracy mandates. Go-to-market angle emphasizes subscription telemetry unbundling that separates hardware acquisition from seasonal calibration services. For Investors and Strategic Acquirers: Re-rating potential sits with liquid injection engineering houses given EPA Clean Water Act buffer zone mandate acceleration and electro-hydraulic technician scarcity that entrenches specialized service relationships. Long-term viability favors targets with captive hydraulic component sourcing and embedded prescription mapping software integration. Signal to watch is state-level nitrate reduction mandate proliferation that fragments compliance specifications and rewards configurable platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Valve Production | Moline and Omaha fabrication clusters secure supply continuity for EPA-mandated variable-rate control systems. |
| EU Green Deal Compliance Certification | REACH chemical registration alignment unlocks horticulture export demand in Stuttgart and Munich corridors. |
| Turf Management Channel Partnership | Florida golf course superintendents present precision liquid upgrade pathway absent grain-belt saturation. |
| Telemetry Subscription Unbundling | Nebraska and Kansas dealer networks decouple capital expenditure from operational support for 2,000-plus acre operators. |
| Corrosion-Resistant Chassis Capacity Expansion | São Paulo state fabrication addresses Brazilian Cerrado acidic soil conditions and ANVISA registration timelines. |
Methodological Framework
USDA conservation compliance filings, EPA Clean Water Act enforcement records, and equipment registration databases in Illinois, Iowa, and Nebraska formed the secondary backbone, supplemented by customs data tracking pneumatic distribution platform exports to Eastern European grain markets. Primary interviews with precision agriculture product managers at full-line OEMs, electro-hydraulic control valve procurement leads, and aftermarket service heads at Corn Belt dealer networks validated specification trends and replacement cycle compression patterns. Bottom-up triangulation across manufacturer shipment disclosures and top-down reconciliation against USDA farm equipment expenditure surveys anchored volume estimates.
Historical trendline analysis of electro-hydraulic adoption rates in 2,000-plus acre operations established baseline penetration curves, while segmentation modeling across product type, technology architecture, application timing, and end-user scale generated discrete growth trajectories. CAGRs were derived from equipment replacement cycle compression dynamics and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated EPA buffer zone geofencing certification timelines and EU Green Deal Farm to Fork strategy phased requirements.
Steel alloy price volatility, electro-hydraulic technician labor availability, and state-level nitrate reduction mandate proliferation are the dominant revision risks that could compress or extend manufacturer margin structures. Forecasts reflect assumptions regarding precision agriculture subsidy continuity and cross-border equipment certification reciprocity. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion and pricing power assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
India Fertilizers Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Water Soluble NPK Fertilizers Market