
 Neem-Based Fertilizers Market | 2026-2036
Neem-Based Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Neem-Based Fertilizers Market Intelligence
Synthetic nitrogen is realigning toward botanical alternatives as input costs destabilize conventional fertilizer economics. Fortune Biotech leverages its extraction infrastructure to secure raw neem supply across South Indian growing regions. EID Parry anchors production scale through its integrated sugarcane-neem processing corridors in Tamil Nadu. Ozone Biotech differentiates via cold-press azadirachtin retention methods that sustain higher active compound yields.
Neem-based fertilizers incorporate azadirachtin, nimbin, and salannin compounds extracted from Azadirachta indica seed kernels through solvent or mechanical pressing methods, serving primarily as nitrogen-fixing soil amendments with systemic pest-deterrent properties. Liquid formulations lead volume adoption among export-oriented horticulture operations, while granular products command stronger margin pools in domestic cereal grain applications. Soil application dominates technical deployment, though drip irrigation compatibility is expanding fastest among protected cultivation systems in water-stressed agrarian zones.
India's BIS mandates minimum azadirachtin thresholds for organic fertilizer certification, while the country's national agricultural regulator enforces residue limits that shape product registration pathways. The EU's REACH framework and F-Gas Regulation restrict synthetic chemical alternatives, indirectly expanding neem-based import eligibility across European horticulture supply chains. Stakeholders must monitor evolving dual carbon compliance requirements in China and the EU Green Deal's embedded carbon accounting rules, as these will determine which extraction and formulation technologies retain cost-advantaged market access.
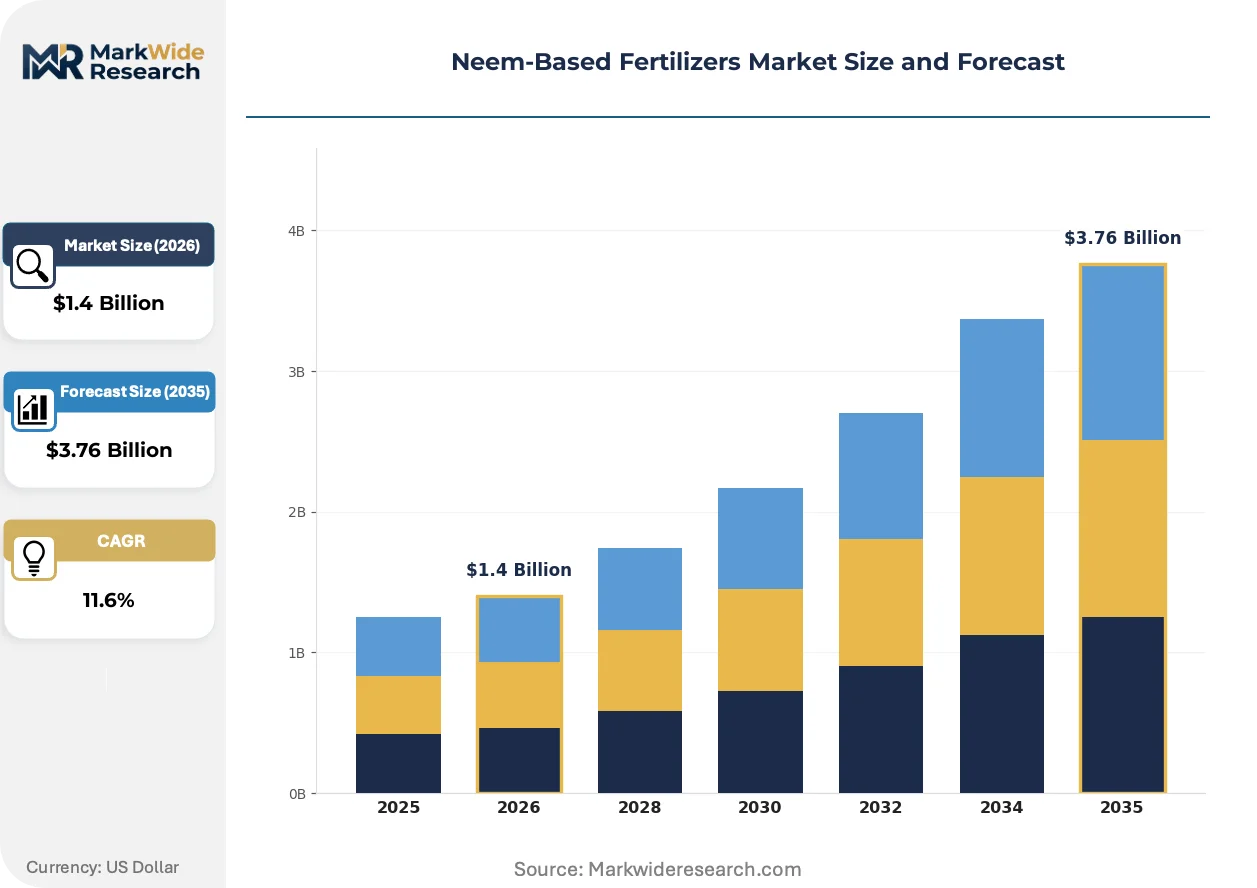
Market Dynamics
Synthetic nitrogen price volatility is compressing farm margins across Maharashtra and Gujarat, accelerating substitution toward neem-based soil amendments with integrated pest management properties.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic chemical alternatives expand import eligibility for neem-based formulations across European horticulture supply chains.
- India's PLI scheme for agrochemical manufacturing:Production-linked incentives accelerate formal channel development and domestic processing capacity expansion.
- Water-stressed agrarian zones:Drip irrigation compatibility drives fastest adoption among protected cultivation systems seeking reduced chemical runoff.
Market Restraints
- Raw neem seed kernel concentration:Supply dependency on South Indian growing regions creates harvest-season price volatility and quality inconsistency.
- Cold-press extraction capex intensity:Azadirachtin retention equipment requires significant capital outlay, limiting processor entry.
- Synthetic urea substitution threat:Government-subsidized conventional nitrogen maintains cost advantage in price-sensitive cereal segments.
Strategic Opportunities
- EU Green Deal embedded carbon accounting:Carbon-border adjustments favor low-extraction-footprint neem formulations over energy-intensive synthetics.
- Export-oriented horticulture operations:Liquid formulation demand concentrates in premium produce segments seeking residue-free certification.
- Cooperative farming networks:Gujarat's procurement collectives enable direct manufacturer-farmer relationships bypassing traditional distributor markups.
Industry Challenges
- Azadirachtin assay standardization:BIS certification protocols vary across regional laboratories, extending product registration timelines.
- Multi-compound formulation expertise:Nimbin and salannin stabilization requires specialized biochemical talent scarce in agrarian processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neem-Based Fertilizers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Liquid Fertilizers, Granular Fertilizers, Bio-Pesticides Formulation: Extracts, Powders, Emulsions, Suspensions Application Method: Soil Application, Foliar Spraying, Drip Irrigation, Seed Treatment Crops: Vegetables, Fruits, Cereal Grains, Flowers |
| Companies Covered | Parker Biotech Private Limited, Fortune Biotech, Agro Extracts Limited, Ozone Biotech, PJ Margo, GreeNeem, EID Parry, The National Fertiliser Limited, Agrilife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neem-Based Fertilizers Market Strategic Shifts & Innovations
Extraction technology convergence with precision agriculture is redefining product formulation requirements. Active compound retention methods now determine competitive positioning more than raw material access.
Cold-press mechanical extraction is unifying azadirachtin stability with solvent-free processing credentials. Protected cultivation operators in water-stressed zones adopt these formulations fastest. The technology is unifying premium pricing power with regulatory pre-qualification for EU organic supply chains.
REACH framework amendments tighten residue limits on imported agrochemicals. Neem-based alternatives gain relative compliance advantage as synthetic registration costs escalate. Horticulture exporters in Maharashtra reconfigure supplier portfolios toward BIS-certified domestic processors.
Cooperative procurement collectives displace traditional distributor networks in Gujarat's farming belts. Volume aggregation enables direct manufacturer contracting with transparent azadirachtin grade specifications. This channel compression is most visible in sugarcane-neem integrated processing corridors where captive supply meets consolidated demand.
Neem-Based Fertilizers Market Segmentation
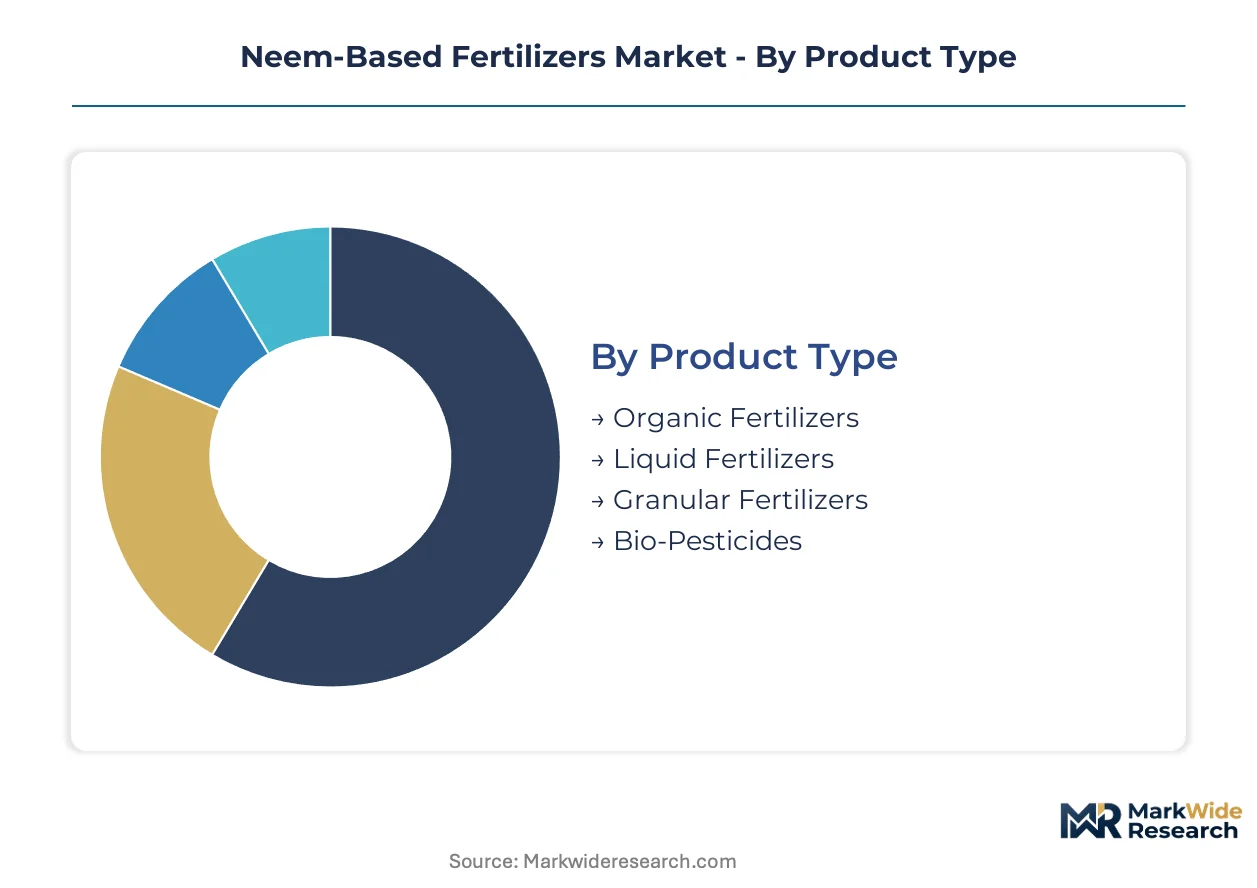
Neem-based fertilizer segmentation reflects divergent technical requirements across organic certification tiers, extraction methods, and application infrastructure. Product differentiation separates commodity soil amendments from precision-formulated inputs for protected cultivation systems.
Product Type:
Standardization dominates commodity-grade organic fertilizers, while liquid and bio-pesticide formulations demand customized azadirachtin concentration protocols and stabilizer packages.
- Liquid Fertilizers:Azadirachtin-nimbin suspensions in aqueous or oil-based carriers enable drip-line integration and foliar delivery systems. Demand concentrates in Maharashtra's export-oriented grape and pomegranate operations, where residue-free certification commands premium procurement budgets.
- Granular Fertilizers:Neem cake pellets and compressed seed kernel formulations provide slow-release nitrogen fixation for cereal grain basins. Gujarat's cooperative procurement networks aggregate volume for domestic wheat and rice applications, though synthetic urea subsidies compress margin pools.
- Organic Fertilizers:Composted neem biomass blended with farmyard manure serves smallholder operations seeking BIS certification compliance.
- Bio-Pesticides:High-azadirachtin concentrates target integrated pest management programs in protected vegetable cultivation.
Leading the category by volume: Granular Fertilizers. Growing fastest: Liquid Fertilizers.
Formulation:
Cost tiers separate solvent-extracted concentrates from mechanical-press alternatives, with emulsion stability determining end-use access.
- Emulsions:Oil-in-water systems stabilize azadirachtin for foliar spraying and drip irrigation compatibility. Tamil Nadu's sugarcane-neem processing corridors favor captive emulsion production for integrated supply chains.
- Extracts:Solvent-based azadirachtin concentrates achieve highest purity grades for export horticulture. Water-stressed zones in Gujarat adopt extract-based drip formulations to minimize runoff compliance risks.
- Powders:Spray-dried neem cake fines serve bulk soil amendment applications with minimal processing overhead.
- Suspensions:Aqueous azadirachtin dispersions require continuous agitation systems, limiting adoption to mechanized farming operations.
Margin concentration: Emulsions. Steepest expansion trajectory: Extracts.
Application Method:
Customer type stratification separates smallholder soil broadcasters from precision-agriculture adopters seeking input-output traceability.
- Drip Irrigation:Compatible liquid formulations integrate with fertigation systems in protected cultivation. Adoption accelerates in Maharashtra's water-stressed grape belts, where reduced chemical runoff aligns with EU import residue limits.
- Soil Application:Traditional neem cake incorporation dominates cereal grain regions with limited irrigation infrastructure. Gujarat's cooperative networks standardize bulk procurement for wheat and cotton rotations.
- Foliar Spraying:High-pressure atomization of azadirachtin emulsions targets pest pressure in vegetable greenhouse operations.
- Seed Treatment:Neem oil coatings on germinating seeds provide systemic protection for soybean and groundnut cultivation.
Widest deployment: Soil Application. Technology transition point: Drip Irrigation.
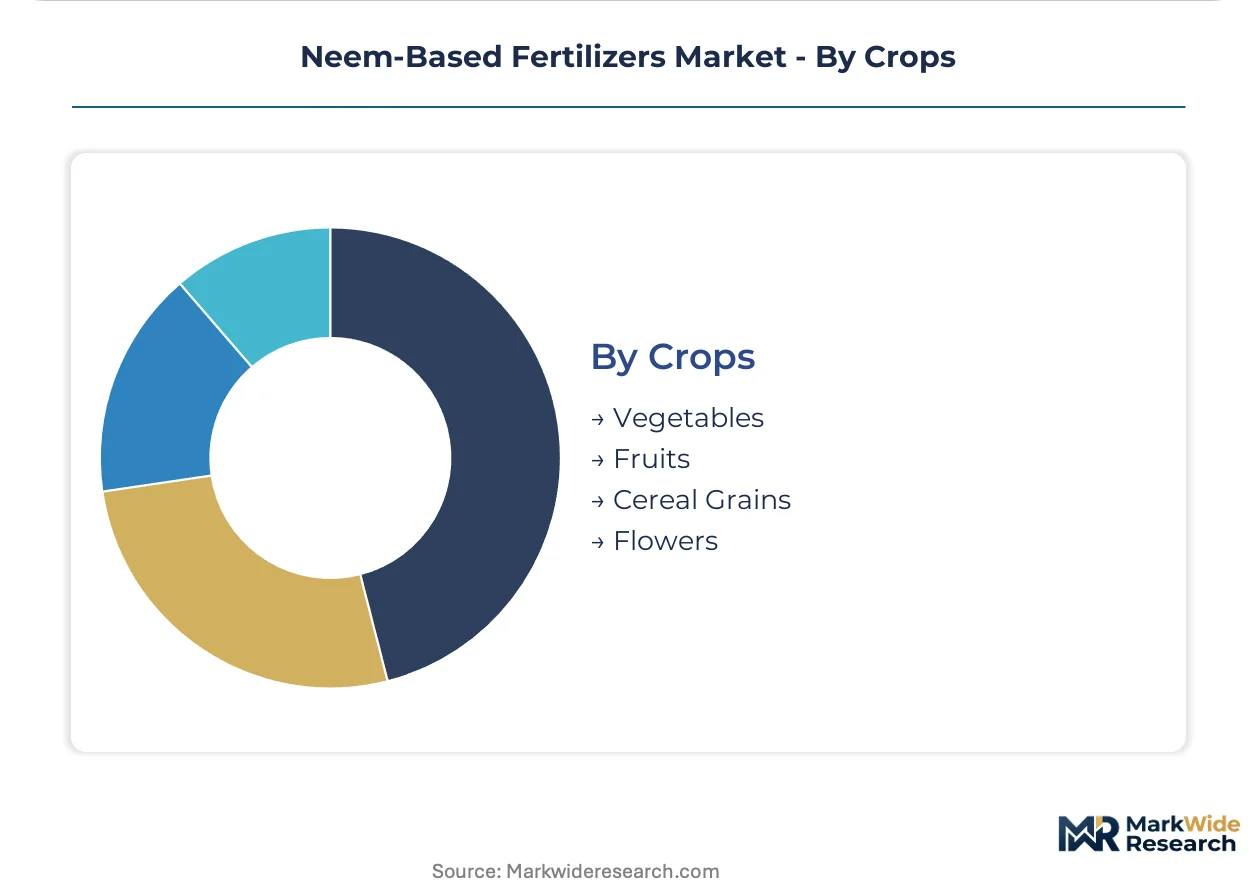
Crops:
Application maturity separates residue-sensitive horticulture from price-elastic cereal segments.
- Vegetables:Protected cultivation of tomatoes, peppers, and cucurbits demands certified organic inputs for EU and Middle East export channels. Maharashtra's polyhouse clusters specify BIS-certified liquid formulations with verified azadirachtin assays.
- Fruits:Grape, pomegranate, and mango operations integrate neem-based pest management with globalGAP certification requirements. Gujarat's cooperative processors aggregate demand for integrated sugarcane-neem supply corridors.
- Cereal Grains:Wheat and rice applications face synthetic nitrogen substitution economics, limiting neem penetration to organic-certified pockets.
- Flowers:Rose and chrysanthemum export operations adopt residue-free protocols for European floriculture markets.
Revenue concentration: Vegetables. Premium pricing power: Fruits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the majority of neem-based fertilizer demand through its organic farming corridors, while regulatory tailwinds in Europe and input cost pressures in North America are accelerating cross-border formulation trade.
India
Maharashtra's export-oriented grape and pomegranate belts drive liquid formulation procurement for EU residue compliance. The PLI scheme for agrochemical manufacturing subsidizes domestic cold-press extraction capacity expansion. Tamil Nadu's sugarcane-neem integrated processing corridors anchor captive supply chains for southern agrarian markets.
United States
California's Central Valley specialty crop operators adopt neem-based soil amendments to satisfy organic certification premiums for domestic retail channels. EPA biopesticide registration pathways shape import eligibility for azadirachtin concentrates. Florida's protected tomato cultivation clusters specify drip-compatible emulsions for integrated pest management programs.
Germany
Bavaria's precision horticulture sector sources REACH-compliant neem extracts for greenhouse vegetable operations serving northern European retail chains. The EU F-Gas Regulation restricts synthetic chemical alternatives, expanding import quotas for botanical formulations. Lower Saxony's organic cereal cooperatives aggregate demand for granular neem cake amendments.
Brazil
São Paulo state's soybean and citrus belts integrate neem seed treatment coatings to reduce synthetic pesticide dependency for export certification. ANVISA bioinput registration timelines determine market access for imported azadirachtin formulations. Minas Gerais's dairy-forage systems adopt neem-based soil amendments for organic milk supply chain compliance.
Australia
New South Wales protected vegetable growers specify BIS-certified liquid neem formulations for residue-sensitive Asian export markets. The country's national agricultural regulator enforces maximum residue limits that favor third-party-assayed botanical inputs. Queensland's mango and avocado orchards deploy foliar neem applications for fruit fly management in integrated programs.
Neem-Based Fertilizers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated processors commanding premium-tier positioning in export horticulture channels while toll extractors serve domestic commodity applications. Market structure tilts toward regional concentration, as raw neem seed kernel procurement radii limit efficient plant placement. Three archetypes dominate: captive sugarcane-neem processors with backward integration into seed supply, cold-press technology specialists leveraging azadirachtin retention premiums, and cooperative-linked formulators serving Gujarat's bulk procurement collectives. Capacity expansion and extraction technology licensing represent the dominant competitive moves, as processors seek to pre-empt azadirachtin assay standardization advantages.
Among integrated processors with captive agricultural supply chains, EID Parry and Fortune Biotech exemplify scale-driven positioning through southern India's sugarcane-neem corridor infrastructure. Ozone Biotech occupies a specialist tier defined by cold-press mechanical extraction credentials. These three anchors illustrate how technology differentiation and supply chain configuration determine access to premium horticulture segments versus commodity cereal applications.
| Leading Market Players |
|---|
| Parker Biotech Private Limited |
| Fortune Biotech |
| Agro Extracts Limited |
| Ozone Biotech |
| PJ Margo |
| GreeNeem |
| EID Parry |
| The National Fertiliser Limited |
| Agrilife |
| Others |
Cost & Logistics Intelligence
Export-oriented horticulture operations in Maharashtra and Gujarat anchor premium pricing tiers through residue-free certification requirements, while domestic cereal grain buyers negotiate commodity-grade neem cake contracts on volume-scaled terms. This buyer-archete stratification separates cold-press azadirachtin concentrates commanding certification premiums from solvent-extracted bulk formulations competing with subsidized synthetic nitrogen.
Pricing Analysis
Volume concentrates in granular neem cake for domestic wheat and rice applications where synthetic urea subsidies compress margins, while margin pools accrue to liquid azadirachtin emulsions for EU-export grape and pomegranate operations. Three-tier pricing structure separates BIS-certified premium formulations from standard cold-press grades and economy solvent-extracted bulk. Price differentiation hinges on azadirachtin assay thresholds and drip-irrigation compatibility certification. Cost compression in commodity cereal tiers is intensifying because government nitrogen subsidies retain farm-gate cost advantages. Cooperative procurement networks in Gujarat exhibit highest price sensitivity; export horticulture clusters in Maharashtra demonstrate least.
Supply Chain Analysis
Azadirachtin concentrate supply rests on South Indian growing regions in Tamil Nadu, Karnataka, and Andhra Pradesh where neem seed kernel harvesting concentrates during monsoon windows. Raw material dependencies include neem seed kernel availability, cold-press mechanical extraction equipment, and stabilizer chemistries for nimbin-salannin retention. Single-source vulnerability runs through South Indian seed procurement radii where harvest-season quality inconsistency disrupts processor input schedules. Distribution runs through cooperative farming networks displacing traditional distributor markups in Gujarat, while formal channels serve Maharashtra's export-oriented operations through BIS-certified processor direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive neem seed supply and cold-press extraction infrastructure determine access to premium horticulture segments. Players are pursuing backward integration into South Indian growing regions to secure raw material quality consistency and harvest-window procurement control.
For Market Incumbents: To counter synthetic nitrogen subsidy erosion in domestic cereal segments, anchor scale through sugarcane-neem integrated processing corridors in Tamil Nadu while deepening cold-press capacity to capture EU Green Deal carbon-border compliance premiums. Prioritize BIS certification pre-qualification to extend azadirachtin assay standardization advantages before regulatory harmonization closes registration windows. For New Entrants and Emerging Players: Enter via drip-irrigation-compatible liquid formulation white space in Maharashtra's water-stressed grape belts where protected cultivation operators seek reduced chemical runoff compliance. Target cooperative procurement aggregation models in Gujarat enabling direct manufacturer-farmer relationships bypassing distributor markups. Lead with transparent azadirachtin grade specifications and cold-press solvent-free credentials to differentiate from incumbent solvent-extracted commodity supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor cold-press technology specialists with proven azadirachtin retention methods in South Indian processing corridors where capital intensity limits competitive replication. Long-term viability over the projection horizon hinges on EU REACH framework compliance positioning and carbon-border adjustment readiness. Watch EU F-Gas Regulation enforcement tightening as the inflection signal accelerating synthetic chemical substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Supply | Captive neem kernel procurement in Tamil Nadu and Karnataka secures harvest-window quality control. |
| Cold-Press Extraction Capacity Expansion | Mechanical azadirachtin retention equipment qualifies processors for EU organic supply chain eligibility. |
| BIS Certification Pre-Qualification | Standardized assay protocols accelerate product registration timelines ahead of regulatory harmonization. |
| Cooperative Channel Development | Direct manufacturer contracting in Gujarat displaces distributor markups through volume aggregation. |
| Drip Irrigation Formulation R&D | Aqueous azadirachtin emulsions capture protected cultivation demand in Maharashtra's water-stressed zones. |
Research Approach
Trade databases, BIS certification registries, and EU REACH submission filings formed the secondary backbone, cross-referenced against primary interviews with neem processing plant managers, FSSAI compliance officers at organic fertilizer firms, Maharashtra grape export cooperative procurement leads, and Tamil Nadu sugarcane-neem integrated corridor operators. Bottom-up unit economics triangulated against top-down agrarian input spending patterns validated volume and value estimates across the analysis window.
Bottom-up modeling anchored forecasts in processor capacity utilization, seed kernel yield assumptions, and azadirachtin retention rates by extraction method, while top-down verification referenced national organic farming adoption curves and PLI scheme disbursement trajectories. Segmentation dimensions included product type, formulation chemistry, application infrastructure, and crop-specific residue compliance tiers. CAGRs derived from fitted growth curves incorporating input cost volatility and regulatory substitution elasticity parameters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU carbon-border adjustment acceleration or monsoon harvest disruption scenarios. Forecasts reflect documented assumptions on synthetic nitrogen price trajectories and BIS assay standardization timelines. A small set of triggers—EU F-Gas Regulation enforcement intensity, PLI scheme extension decisions, and South Indian seed harvest yields—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Potash Market
Fertilizers
France Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Thailand Fertilizers Market