
 Asia-Pacific Fertilizers Market | 2026-2036
Asia-Pacific Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fertilizers Market Outlook
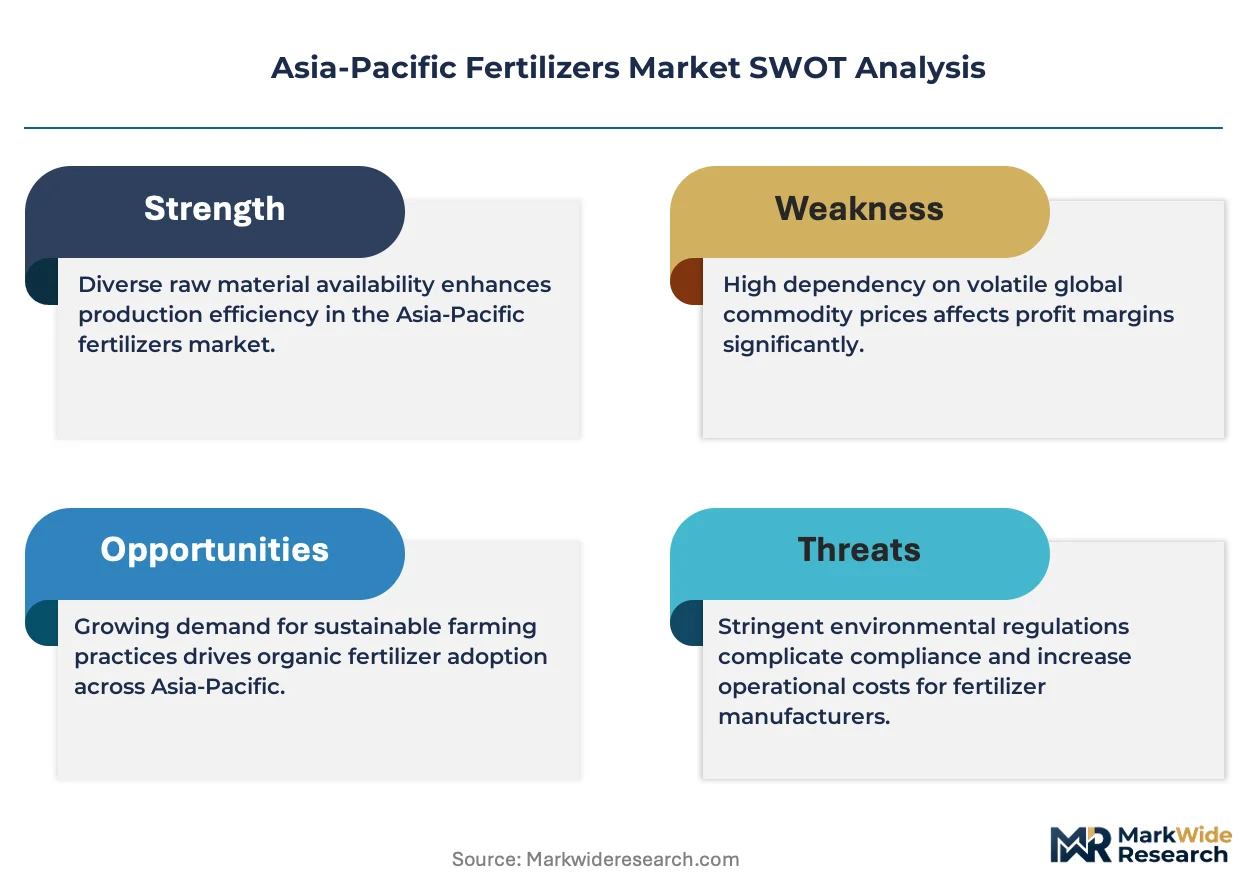
A capital-intensity divergence between integrated ammonia producers and regional blenders is rotating procurement leverage toward upstream chemical assets. Yara International ASA leverages its integrated ammonia-urea network across Australian grain belts. Coromandel International Ltd. anchors its position through deep backward integration into phosphoric acid and sulfuric acid production. Nutrien Ltd. competes via controlled-release technology specialization that commands premium positioning in Japanese horticulture.
Asia-Pacific fertilizers encompass nitrogenous, phosphatic, and potassic compounds formulated to replenish soil macronutrients, typically manufactured through Haber-Bosch ammonia synthesis, phosphate rock acidulation, or potash evaporation and crystallized to specified N-P-K ratios for crop-specific dosing. Urea dominates volume flows across the region's rice-wheat systems, while controlled-release formulations capture expanding margin pools in high-value horticultural applications. Agricultural crops absorb the majority of tonnage, though turf and ornamental segments in Australia's urban centers sustain faster value growth per hectare treated.
China's MIIT enforces GB standards on fertilizer product quality and environmental discharge, while India's FSSAI and CEA jointly monitor soil health parameters that influence subsidy eligibility. Australia's TGA-equivalent agricultural chemical regulator, together with Japan's JIS standards for compound fertilizers, tightens contaminant thresholds and pushes reformulation toward lower-carbon manufacturing routes. Stakeholders must track how Indonesia's emerging national fertilizer quality mandate and Vietnam's tightening groundwater protection rules redirect import sourcing and domestic blending requirements.
Market Dynamics
India's PLI scheme for agrochemical manufacturing is redirecting capital toward domestic ammonia-urea complexes, altering procurement leverage across Southeast Asian rice belts and compressing import dependency ratios for nitrogenous inputs.
Growth Catalysts
- China's dual carbon goals:GB standards on fertilizer discharge are accelerating retrofit demand for low-carbon ammonia plants. Shandong province's vegetable cooperatives are consolidating procurement to secure certified low-emission urea supply.
- Controlled-release coating technology:Polymer-sulfur hybrid formulations are expanding addressable acreage in Japanese precision horticulture. METI subsidies for smart agriculture equipment are bundling these inputs with sensor-based dosing systems.
- Rice-wheat system intensification:Southeast Asian governments are expanding subsidized fertilizer distribution windows to match double-cropping calendars. Vietnam's Mekong Delta irrigation upgrades are synchronizing nitrogen application with water delivery schedules.
Market Restraints
- Phosphate rock import concentration:Over 70% of regional phosphoric acid feedstock transits through a single maritime chokepoint. Australian blenders face 14-21 day supply uncertainty from this geographic bottleneck.
- Natural gas price volatility:Ammonia synthesis margins collapse when Asian LNG spot prices exceed contract thresholds. Chinese integrated producers with captive coal-gasification assets capture structural cost advantages over gas-dependent regional competitors.
- Potash substitution ceiling:Chloride-sensitive crops in Japan's greenhouse sector cannot tolerate standard muriate of potash. Sulfate of potash supply remains concentrated among three offshore suppliers with limited Asia-Pacific inventory positioning.
Strategic Opportunities
- Indonesia's emerging quality mandate:Draft national fertilizer standards are creating first-mover advantages for certified importers with in-country blending infrastructure. The regulation favors producers with ISO 17025 accredited laboratories.
- Drone-based variable-rate application:Convergence of UAV swarm technology with real-time soil sensing is enabling per-plant nutrient dosing. Australian broadacre wheat operations are piloting subscription-based input-plus-application bundles.
- Vietnam's groundwater protection rules:Nitrate leaching limits in the Red River Delta are mandating slow-release formulations for vegetable farming. Domestic blenders without coating capabilities face exclusion from this procurement pool.
Industry Challenges
- Process control engineering scarcity:Haber-Bosch plant optimization requires expertise in high-pressure catalytic systems that regional technical institutes undersupply. Indonesian and Vietnamese greenfield projects are competing for the same limited talent pool.
- Legacy ERP integration:Established distributors in India's fragmented retail channel operate on decade-old inventory systems that resist API connectivity with government subsidy verification portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fertilizers Market |
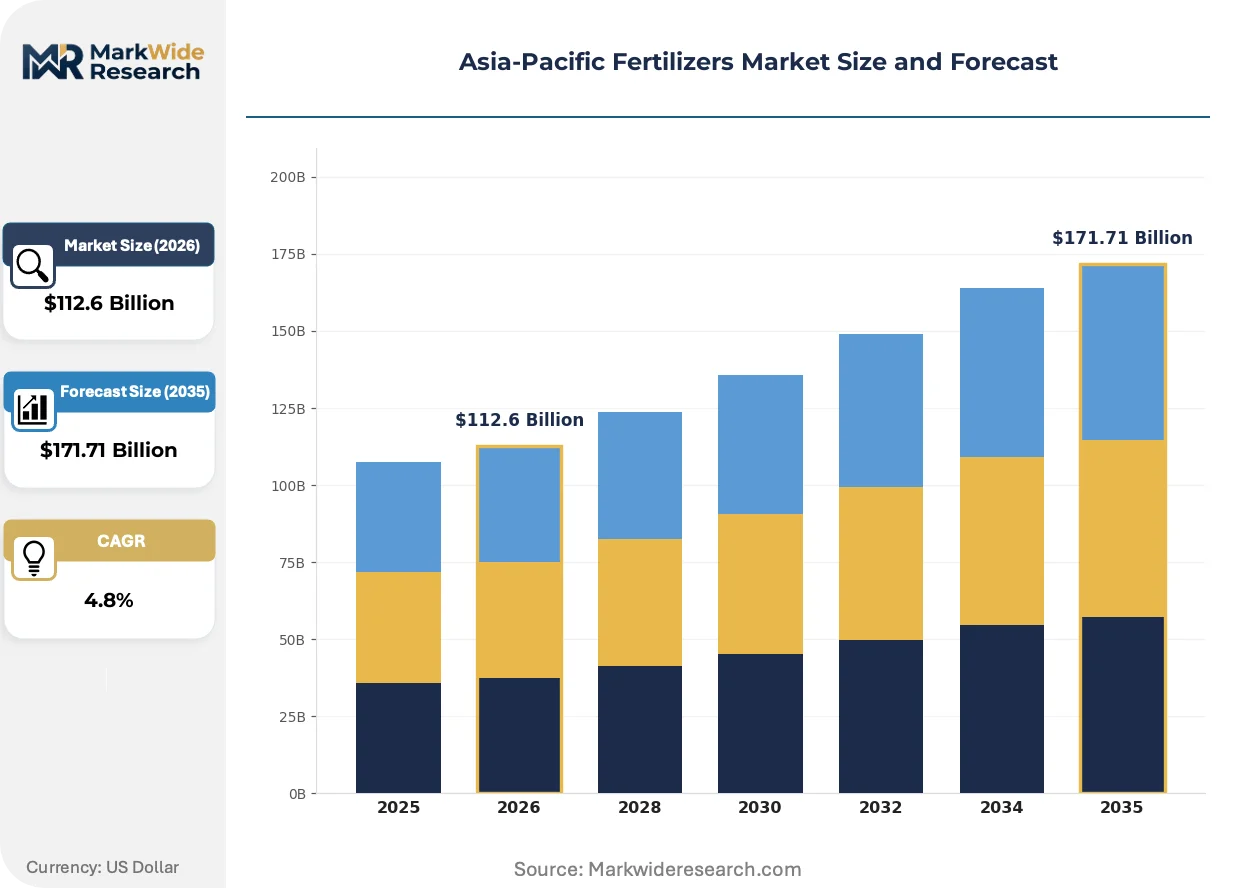
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $171.71 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Potassium Chloride, Phosphatic Fertilizers Application: Agricultural Crops, Horticultural Crops, Turf & Ornamental, Others Form: Granular, Liquid, Powder, Controlled Release End User: Farmers, Cooperatives, Distributors, Government Agencies |
| Companies Covered | Coromandel International Ltd., Sinofert Holdings Limited, ICL Group Ltd, Yara International ASA, Xinyangfeng Agricultural Technology Co., Ltd., Nutrien Ltd., The Mosaic Company, Sumitomo Chemical Co., Ltd., Sinochem Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fertilizers Market Strategic Shifts
Biostimulant-fertilizer hybrids are redefining product boundaries across Asia-Pacific cropping systems, with microbial inoculants and seaweed extracts displacing pure chemical positioning in premium horticulture segments.
Nano-encapsulated nitrogen formulations are fragmenting the traditional urea market by enabling foliar application with 40-60% lower volatilization losses. Japanese strawberry greenhouse operators are adopting these materials at 3-4x standard urea pricing. The technology is fragmenting procurement patterns away from commodity spot purchases toward contracted specialty input programs with embedded agronomic advisory.
China's MIIT enforcement of GB 38400-2019 on fertilizer heavy metal limits is forcing reformulation across phosphate product lines. Acidulation processes using lower-grade rock are being phased out in favor of purified phosphoric acid routes. Hebei province's compound fertilizer cluster is absorbing the highest compliance costs, with smaller blenders exiting rather than upgrading wastewater treatment infrastructure.
Direct-to-farm digital platforms are compressing distributor margins in India's subsidy-heavy urea channel. State-mandated ePOS verification at retail points is enabling bypass models where manufacturers aggregate farmer demand for bulk delivery. Andhra Pradesh and Telangana are the primary geographies where this channel disruption is visible, with cooperative societies losing volume to app-based procurement collectives.
Asia-Pacific Fertilizers Market Segmentation
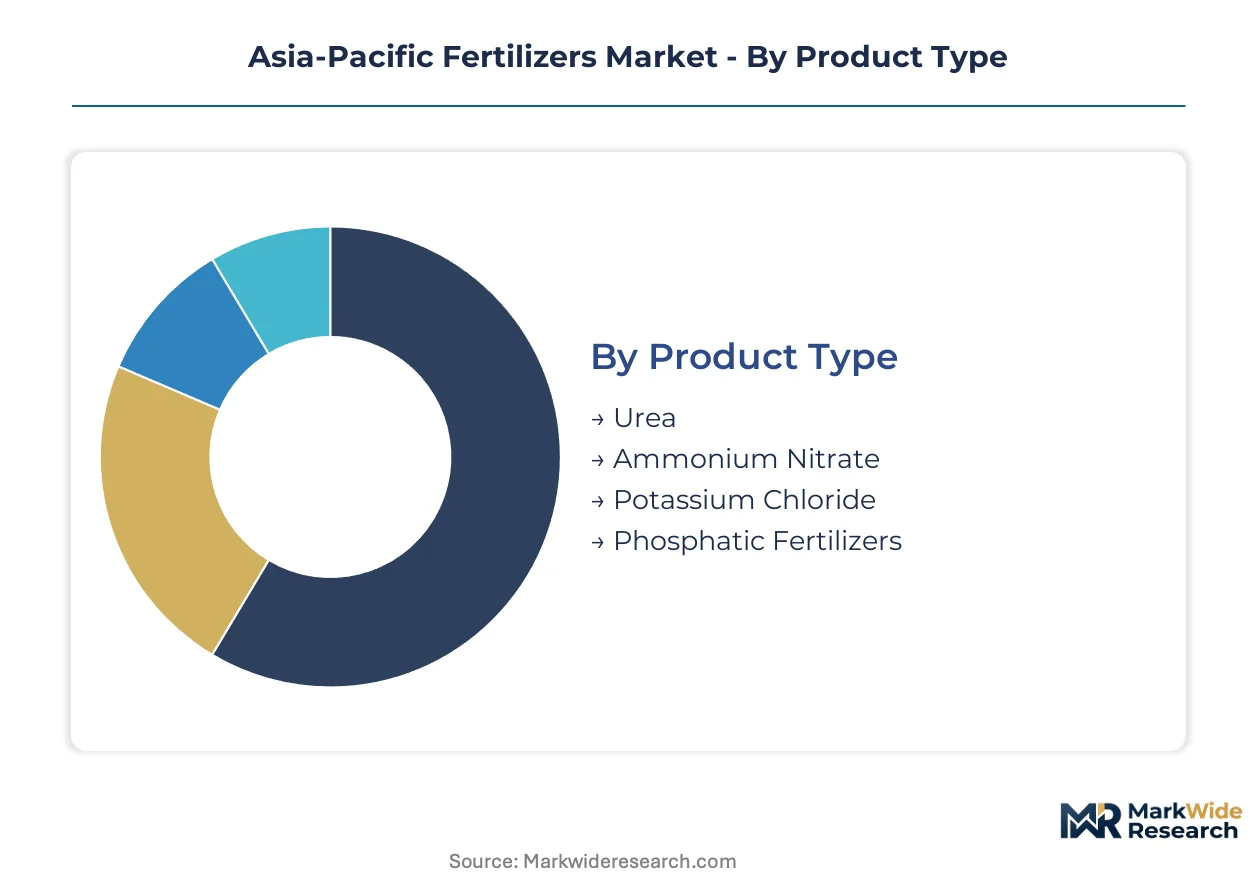
Product boundaries across Asia-Pacific fertilizers fragment along crop-specific nutrient dosing requirements and regulatory compliance tiers. Procurement patterns diverge sharply between subsidized bulk channels serving rice-wheat systems and premium specialty formulations targeting Japanese greenhouse operations.
Product Type:
Domestic production dominates nitrogenous categories across China and India, while phosphatic and potassic lines depend heavily on import flows through Southeast Asian ports.
- Urea:Synthesized via Haber-Bosch ammonia conversion with 46% nitrogen content, this compound commands volume leadership across the region's cereal cultivation belts. Shandong and Hebei vegetable cooperatives are consolidating procurement to secure certified low-emission supply under MIIT's GB standards enforcement.
- Ammonium Nitrate:Higher nitrogen density at 34% with lower volatilization losses than urea, this formulation concentrates demand in Australian broadacre wheat operations where transport costs favor concentrated inputs. Western Australian grain belts absorb the majority of regional trade flows.
- Potassium Chloride:Standard muriate of potash delivers 60-62% K2O for chloride-tolerant crops across Southeast Asian rice systems.
- Phosphatic Fertilizers:Diammonium phosphate and triple superphosphate products acidulated from phosphate rock feedstock serve India's subsidized distribution network.
Urea commands the established base. The steepest expansion runs through phosphatic formulations as India's PLI scheme redirects capital toward domestic acidulation capacity.
Application:
Margin structures stratify sharply between commodity tonnage in open-field cereals and precision-dosed specialty inputs in protected cultivation.
- Agricultural Crops:Rice-wheat rotation systems across the Indo-Gangetic Plain and Mekong Delta absorb the majority of nitrogenous tonnage. Vietnam's irrigation upgrades are synchronizing application schedules with water delivery windows.
- Horticultural Crops:Polymer-sulfur hybrid controlled-release formulations command premium positioning in Japanese strawberry greenhouse operations. METI subsidies for smart agriculture equipment bundle these inputs with sensor-based dosing infrastructure.
- Turf & Ornamental:Australian urban centers sustain faster value growth per hectare treated through sports field and landscape maintenance contracts.
- Others:Forestry and plantation applications in Indonesia and Malaysia represent emerging demand pockets outside traditional cropping calendars.
Agricultural crops anchor volume procurement. Horticultural applications are climbing the fastest as greenhouse acreage expands across East Asian markets.
Form:
Physical state determines logistics economics and application equipment compatibility across the region's fragmented retail infrastructure.
- Granular:Standard prilled and granular formulations dominate bulk handling systems across India's cooperative distribution network. Mechanical spreader compatibility preserves this format's lock on rice-wheat belt procurement.
- Liquid:Fertigation-compatible solutions concentrate in Australian broadacre operations and Vietnamese vegetable farming where drip irrigation penetration is highest. Nano-encapsulated nitrogen variants in this category enable foliar application with reduced volatilization losses.
- Powder:Finely ground formulations serve specialty blending operations and direct soil amendment in high-value horticulture.
- Controlled Release:Polymer-coated and sulfur-coated products capture expanding margin pools where labor costs or environmental regulations constrain application frequency.
Granular formats retain the volume base. Controlled release formulations are gaining share fastest as nitrate leaching limits tighten across Vietnam's Red River Delta vegetable zones.
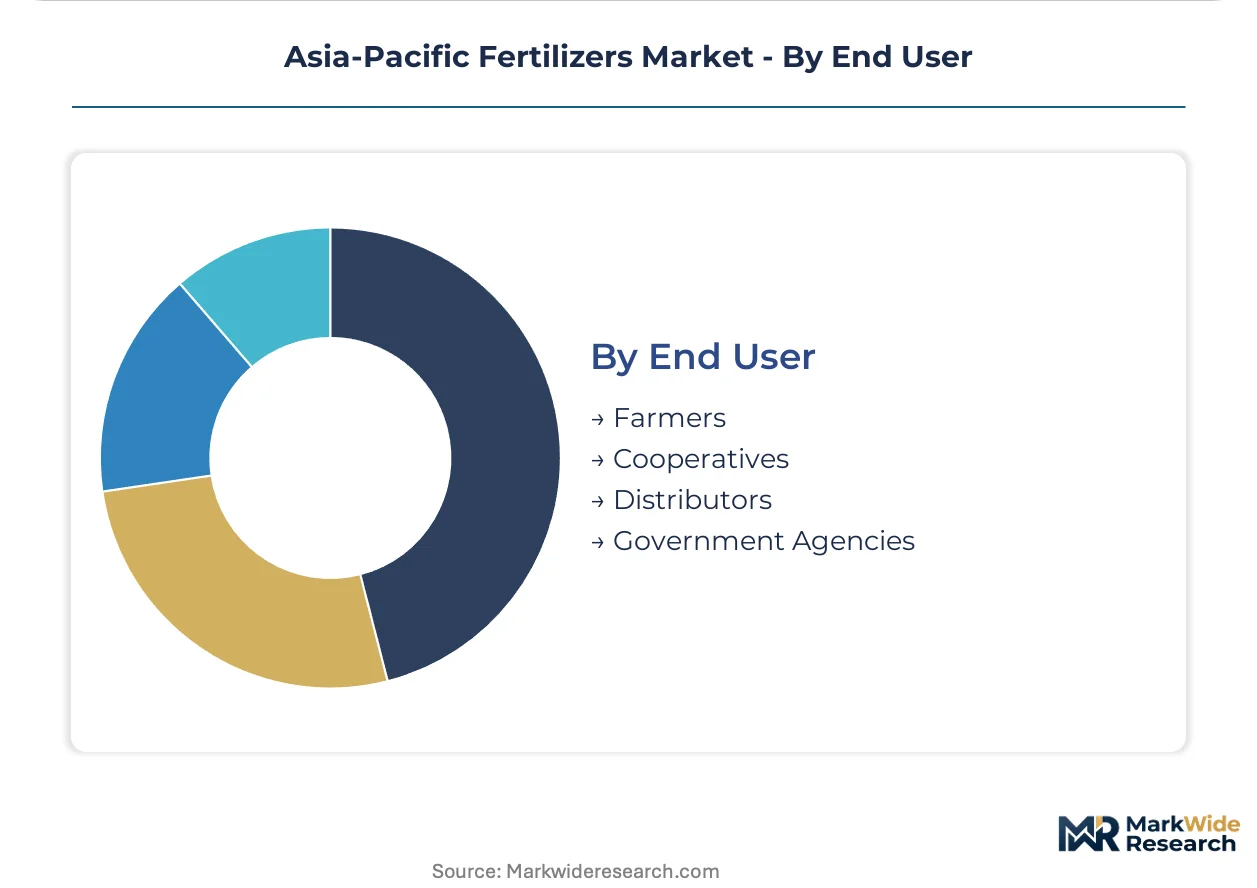
End User:
Channel structure fragments between state-mandated procurement systems and emerging direct-to-farm aggregation platforms.
- Farmers:Individual smallholders across India's fragmented landholding pattern access subsidized urea through biometric-linked retail points. Andhra Pradesh and Telangana are witnessing the fastest channel disruption as app-based procurement collectives bypass cooperative societies.
- Cooperatives:Consolidated procurement entities in China's Shandong province negotiate directly with integrated ammonia-urea producers for certified low-carbon supply.
- Distributors:Legacy inventory systems in India's retail channel resist API connectivity with government subsidy verification portals, compressing margins for established intermediaries.
- Government Agencies:State fertilizer corporations in Indonesia and Vietnam manage import licensing and strategic reserve stocking for domestic food security mandates.
Government agencies and cooperatives control the established procurement base. Direct farmer aggregation platforms are expanding most quickly where digital infrastructure and subsidy verification systems converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage tilts toward Chinese integrated producers with captive coal-gasification assets, while Australian blenders absorb margin compression from LNG-linked ammonia costs. This asymmetry is reshaping procurement flows across Southeast Asian rice belts.
China
Shandong and Hebei vegetable cooperatives are consolidating procurement to secure certified low-emission urea supply. MIIT enforcement of GB 38400-2019 on heavy metal limits is forcing acidulation process upgrades across phosphate product lines. Hebei's compound fertilizer cluster is absorbing the highest compliance costs as smaller blenders exit rather than upgrade wastewater treatment.
India
The Indo-Gangetic Plain's rice-wheat rotation systems absorb the majority of nitrogenous tonnage through subsidized distribution networks. The PLI scheme for agrochemical manufacturing is redirecting capital toward domestic ammonia-urea complexes. Andhra Pradesh and Telangana are witnessing the fastest channel disruption as app-based procurement collectives bypass cooperative societies.
Japan
Polymer-sulfur hybrid controlled-release formulations command premium positioning in strawberry greenhouse operations. METI subsidies for smart agriculture equipment are bundling specialty inputs with sensor-based dosing infrastructure. Kanto region precision horticulture is driving nano-encapsulated nitrogen adoption at 3-4x standard urea pricing.
Vietnam
Mekong Delta irrigation upgrades are synchronizing nitrogen application schedules with water delivery windows. Groundwater protection rules in the Red River Delta are mandating slow-release formulations for vegetable farming. Domestic blenders without coating capabilities face exclusion from this procurement pool.
Australia
Western Australian grain belts absorb the majority of ammonium nitrate regional trade flows where transport costs favor concentrated inputs. Urban centers sustain faster value growth per hectare treated through sports field and landscape maintenance contracts. Broadacre wheat operations are piloting subscription-based input-plus-application bundles with drone-based variable-rate technology.
Asia-Pacific Fertilizers Market Competitive Environment
Concentration sits with integrated ammonia-urea producers who control upstream synthesis assets. The vendor base stratifies across three tiers: state-linked conglomerates with captive raw material positions, regional blenders dependent on imported intermediates, and specialty formulators targeting precision horticulture. Strategic moves center on backward integration into phosphoric acid production and coating technology licensing for controlled-release portfolios.
Within the integrated producer tier, Yara International ASA and Nutrien Ltd. occupy positions defined by upstream asset control and technology specialization respectively. Coromandel International Ltd. exemplifies the backward-integrated archetype through in-house acid production. Among Asia-Pacific headquartered conglomerates, Sinochem Group and Sinofert Holdings Limited represent state-linked structures with domestic distribution density. Sumitomo Chemical Co., Ltd. anchors the specialty formulation segment with polymer-coating capabilities for premium horticulture applications.
| Leading Market Players |
|---|
| Coromandel International Ltd. |
| Sinofert Holdings Limited |
| ICL Group Ltd |
| Yara International ASA |
| Xinyangfeng Agricultural Technology Co., Ltd. |
| Nutrien Ltd. |
| The Mosaic Company |
| Sumitomo Chemical Co., Ltd. |
| Sinochem Group |
| Others |
Value Chain & Pricing Dynamics
Fourteen to twenty-one day phosphate rock transit uncertainty through a single maritime chokepoint concentrates procurement leverage among integrated ammonia-urea producers with captive feedstock positions. This inventory risk premium flows directly into contract pricing differentials between Chinese coal-gasification operators and LNG-dependent regional blenders.
Pricing Analysis
Controlled-release coating premiums command 3-4x standard urea spreads in Japanese precision horticulture, while commodity granular formulations trade on volume-scale discounts through India's subsidized cooperative channels. Price differentiation hinges on MIIT GB 38400-2019 certification tier and backward integration into phosphoric acid production. Cost compression in Australian ammonium nitrate supply is intensifying because LNG-linked ammonia synthesis margins collapse when spot prices exceed contract thresholds. Smallholder farmers across India's biometric-linked retail points exhibit highest price sensitivity, whereas Shandong vegetable cooperatives purchasing certified low-emission urea demonstrate lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate state fertilizer corporation procurement in Indonesia and Vietnam, while just-in-time inventory management prevails among Australian broadacre wheat operators piloting subscription-based input bundles. Geographic supply concentration centers on China for urea synthesis, Morocco and Jordan for phosphate rock acidulation, and Belarus and Canada for potash crystallization. Raw material flows rest on natural gas feedstock, lower-grade phosphate rock, and muriate of potash intermediates. Single maritime chokepoint vulnerability in phosphate rock transit creates structural supply risk. Distribution runs through state-mandated cooperative networks in India and direct-to-farm digital platforms in Andhra Pradesh and Telangana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue in agronomic advisory and sensor-based dosing system bundling expands faster than commodity fertilizer tonnage, creating recurring-income opportunities for input manufacturers with precision agriculture integration capabilities.
For Market Incumbents: Fortify backward integration into phosphoric acid and sulfuric acid production to defend against import dependency compression under India's PLI scheme. Lock in ISO 17025 laboratory accreditation ahead of Indonesia's emerging quality mandate to preserve procurement access. Channel control through direct-to-farm digital platforms in India's ePOS-verified retail network offers defensive positioning against cooperative society bypass models. For New Entrants and Emerging Players: ISO 17025 certification fast-track unlocks first-mover positioning in Indonesia's draft national fertilizer standards enforcement. Drone-based variable-rate application services in Australian broadacre wheat operations represent the most penetrable white-space target. Vietnam's Red River Delta slow-release formulation mandate creates entry opportunity for coating technology specialists without domestic incumbent infrastructure. Go-to-market through subscription-based input-plus-application bundles bypasses legacy distributor margin compression. For Investors and Strategic Acquirers: Carve-out targets emerge from state-linked conglomerates divesting non-core blending assets amid regulatory compliance cost absorption. Long-term viability favors controlled-release technology specialists with polymer-sulfur hybrid formulation patents and METI subsidy bundling relationships. Watch for inflection signal in Indonesian national fertilizer quality mandate enforcement timeline and domestic laboratory accreditation backlog.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphoric Acid | Captive acidulation capacity insulates margin pressure from phosphate rock import concentration. |
| Controlled-Release Coating Technology Licensing | Polymer-sulfur hybrid formulations capture premium positioning in Japan's METI-subsidized smart agriculture sector. |
| Direct-to-Farm Digital Platform Development | App-based procurement collectives in Andhra Pradesh and Telangana bypass legacy cooperative distribution margins. |
| ISO 17025 Laboratory Accreditation Investment | Certified testing infrastructure secures procurement eligibility under Indonesia's emerging quality mandate. |
| Drone-Based Variable-Rate Application Services | Subscription bundles with UAV swarm technology enable per-plant nutrient dosing in Australian broadacre operations. |
Study Parameters
Cross-validation between primary interviews with ammonia plant managers, procurement leads at Southeast Asian rice cooperatives, distribution channel partners, and technical R&D directors anchors the qualitative findings against secondary data from customs and trade flow records, Fertilizer Association of India reports, SEC 10-K filings of listed producers, and GB standards enforcement disclosures from China's MIIT. Bottom-up tonnage estimates from crop-specific application rates reconcile with top-down market value assessments across nitrogenous, phosphatic, and potassic product categories.
Sensitivity analysis around natural gas price volatility bands and phosphate rock transit disruption scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application crop category, physical form, and end-user channel structure, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from trend extrapolation of historical consumption patterns adjusted for PLI scheme capital redirection and irrigation infrastructure upgrade timelines in Vietnam's Mekong Delta.
Underlying assumptions cover sustained subsidy eligibility in India's biometric-linked retail network and MIIT enforcement continuity for GB 38400-2019 heavy metal limits, with deviation risk concentrated in LNG spot price spikes exceeding ammonia synthesis breakeven thresholds and Indonesian quality mandate implementation delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
France Fertilizer Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market