
 North America Organic Fertilizers Market | 2026-2036
North America Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organic Fertilizers Market Outlook
Specialty crop growers is bifurcating from commodity grain operations as the dominant demand archetype in the North America organic fertilizers landscape. California Organic Fertilizers Inc. leverages its West Coast manufacturing base to supply high-nitrogen compost blends for vineyard and orchard clients. Suståne Natural Fertilizer Inc. anchors its position through granular slow-release technology derived from aerobically composted turkey litter. The Scotts Miracle-Gro Company competes through garden center shelf space and direct-to-consumer liquid formulations.
North America organic fertilizers comprise plant or animal-derived materials containing one or more recognized nutrients, typically manufactured through composting, anaerobic digestion, or mechanical processing to achieve minimum total nitrogen content of two percent by dry weight. These inputs restore soil organic matter and microbial activity while satisfying USDA National Organic Program standards for certified crop production. Compost leads product type volume due to established municipal collection infrastructure and lower per-ton production costs. Seaweed extract commands premium positioning in greenhouse applications where foliar feeding protocols demand rapid nutrient uptake. Granular form dominates agricultural field distribution through compatibility with conventional spreader equipment, while liquid concentrates accelerate in turf management contracts requiring precision application.
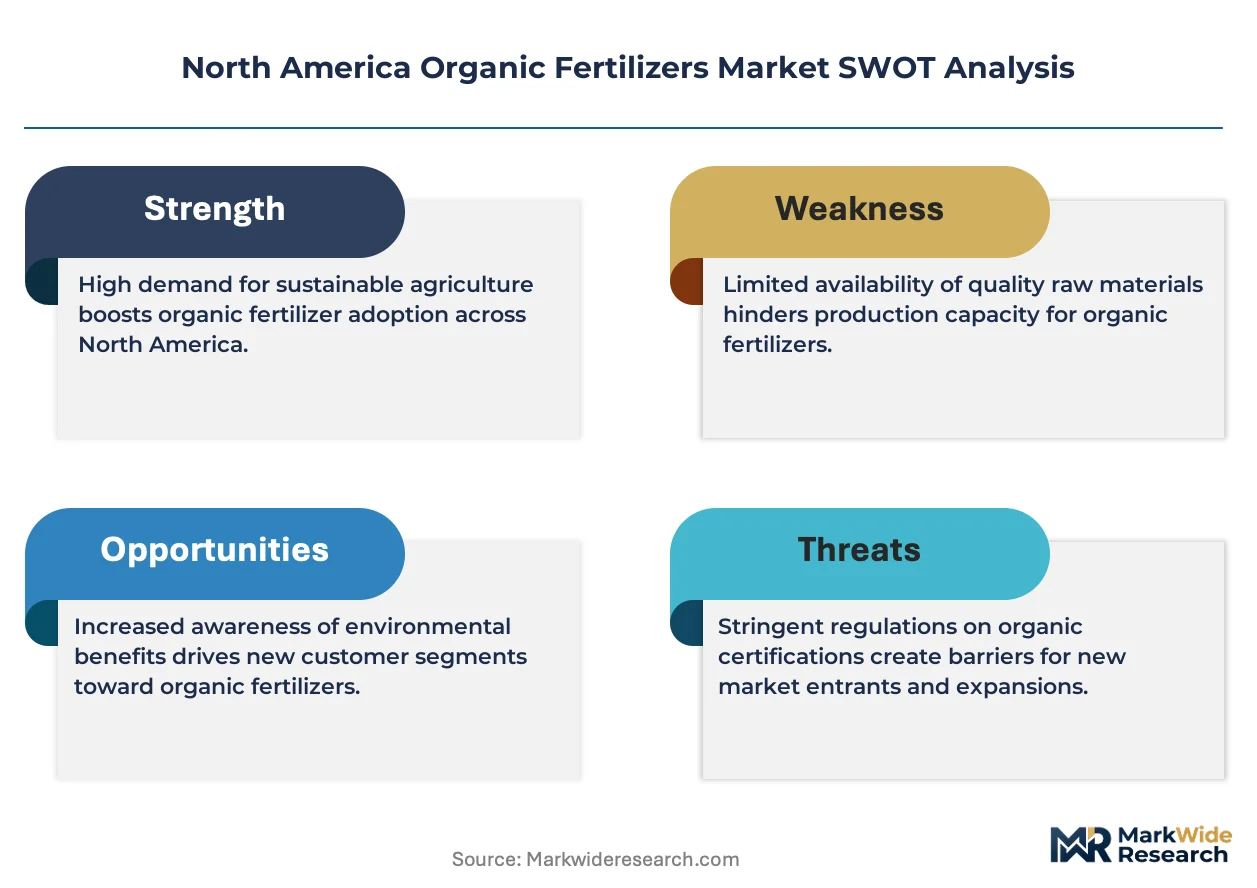
USDA National Organic Program standards, EPA biosolids regulations under 40 CFR Part 503, and Canadian Food Inspection Agency fertilizer registration requirements collectively shape product formulation, labeling, and interstate commerce. State-level organic certification programs in California, Washington, and Oregon impose additional input material traceability obligations that filter supplier eligibility. Stakeholders must monitor evolving state legislation on per- and polyfluoroalkyl substance limits in compost feedstocks, as these thresholds will determine which manufacturing processes retain market access.
Market Dynamics
USDA National Organic Program enforcement deadlines are compressing procurement timelines for certified organic inputs, forcing specialty crop growers to lock in supplier relationships eighteen months ahead of planting cycles and reshaping competitive positioning across the value chain.
Growth Catalysts
- California CCOF Certification:Vineyard and orchard operators in the Central Valley accelerate certified organic input procurement ahead of state-mandated buffer zone requirements.
- Aerobic Composting Technology:Municipalities in Washington and Oregon expand curbside organics collection, diverting feedstock toward commercial compost manufacturing at scale.
- 40 CFR Part 503:EPA biosolids regulations tighten pathogen reduction standards, pushing municipal wastewater facilities toward anaerobic digestion partnerships with fertilizer blenders.
Market Restraints
- Turkey Litter Supply Concentration:Minnesota and Arkansas operations control over sixty percent of aerobically composted poultry litter feedstock, creating geographic supply vulnerability.
- Seaweed Harvest Volatility:Atlantic coast kelp bed variability and Canadian Maritime licensing delays constrain liquid extract raw material availability.
- Synthetic Nitrogen Price Arbitrage:Commodity grain operators in the Corn Belt face persistent cost gaps between conventional urea and certified organic nitrogen alternatives.
Strategic Opportunities
- Greenhouse Foliar Feeding:Controlled-environment agriculture facilities in Ontario and British Columbia adopt precision liquid concentrate application systems for rapid nutrient uptake protocols.
- Canadian Food Inspection Agency Registration:Streamlined fertilizer product approval pathways enable US manufacturers to cross-border distribute without redundant efficacy testing.
- Per- and Polyfluoroalkyl Substance Limits:Emerging state legislation in Washington and Maine creates first-mover advantage for composters with verified PFAS-free feedstock chains.
Industry Challenges
- Microbial Consortia Expertise:Formulation chemists with aerobic composting and anaerobic digestion process knowledge command premium compensation, constraining mid-tier manufacturer expansion.
- USDA Organic Certification Timeline:Input material traceability documentation requirements extend supplier qualification cycles to fourteen months, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organic Fertilizers Market |
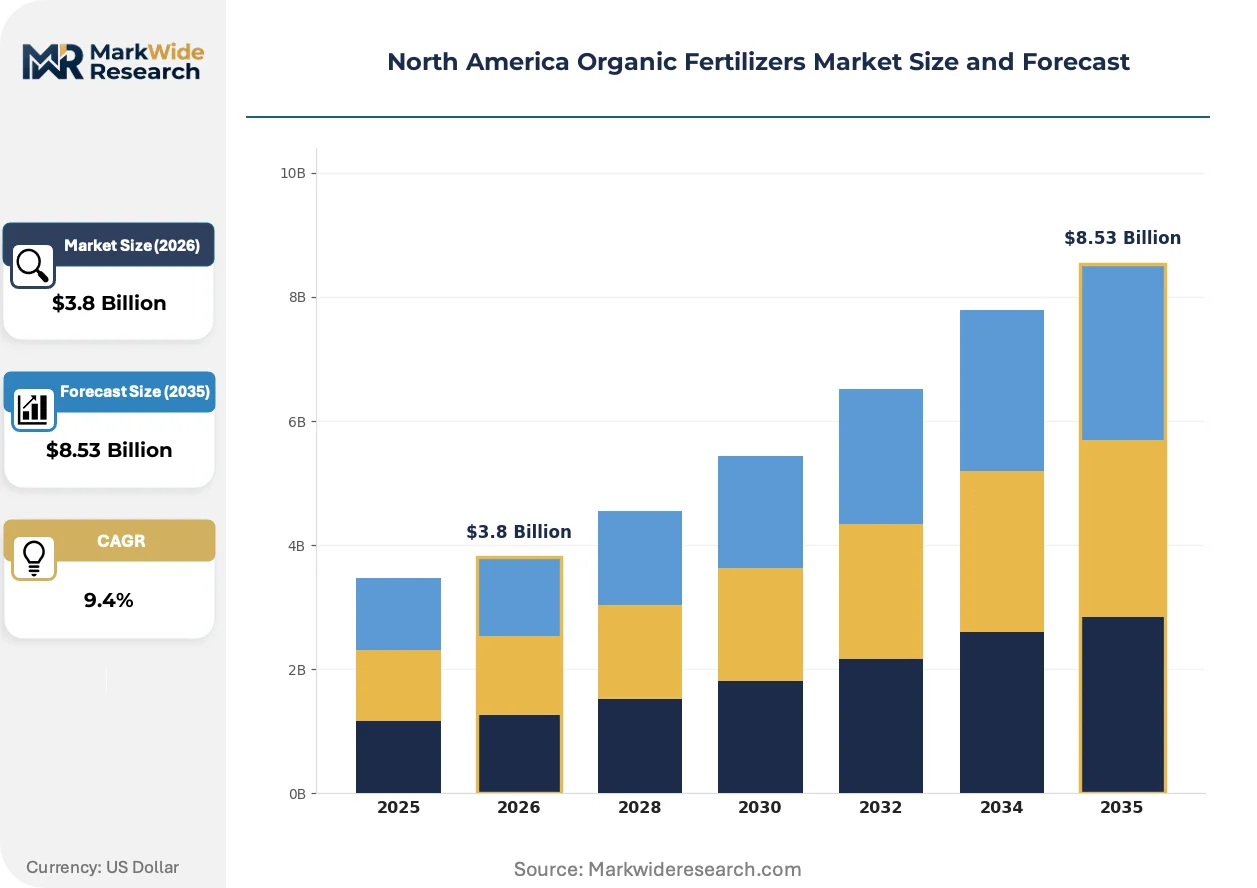
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Bone Meal, Seaweed Extract Application: Agricultural Fields, Home Gardens, Greenhouses, Turf Management Form: Granular, Liquid, Powder, Pellets Distribution Channel: Online Retail, Specialty Stores, Garden Centers, Agricultural Supply Stores |
| Companies Covered | California Organic Fertilizers Inc., Suståne Natural Fertilizer Inc., The Scotts Miracle-Gro Company, Cedar Grove Composting Inc., E.B. Stone & Sons Inc., The Espoma Company, Central Iowa Organic Fertilizer, True Organic Products Inc., Midwestern BioAg, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organic Fertilizers Market Strategic Shifts
Liquid seaweed extract concentrates are compressing application protocols in controlled-environment agriculture, while regulatory pressure on synthetic input residues accelerates certified organic formulation R&D across the continent.
Precision fermentation-derived biofertilizers are displacing traditional compost-based nitrogen sources in greenhouse lettuce and tomato operations. Dutch-Canadian technology licensors license microbial strain libraries to Ontario vertical farming facilities. This displacement is compressing the premium pricing window for conventional compost blends in protected agriculture.
USDA National Organic Program's updated National List of Allowed and Prohibited Substances restricts magnesium chloride and sodium nitrate sourcing for organic crop production. California Organic Fertilizers Inc. and Pacific Northwest blenders reformulate micronutrient packages to maintain NOP compliance. Vineyard operators in Napa and Sonoma counties absorb higher input costs to retain certification status.
Direct-to-grower digital procurement platforms bypass traditional agricultural distributor networks. Specialty crop operators in Florida's Belle Glade region and California's Imperial Valley contract directly with compost manufacturers for scheduled bulk delivery. This channel compression is most visible in high-value permanent crop segments where traceability documentation carries certification audit weight.
North America Organic Fertilizers Market Segmentation
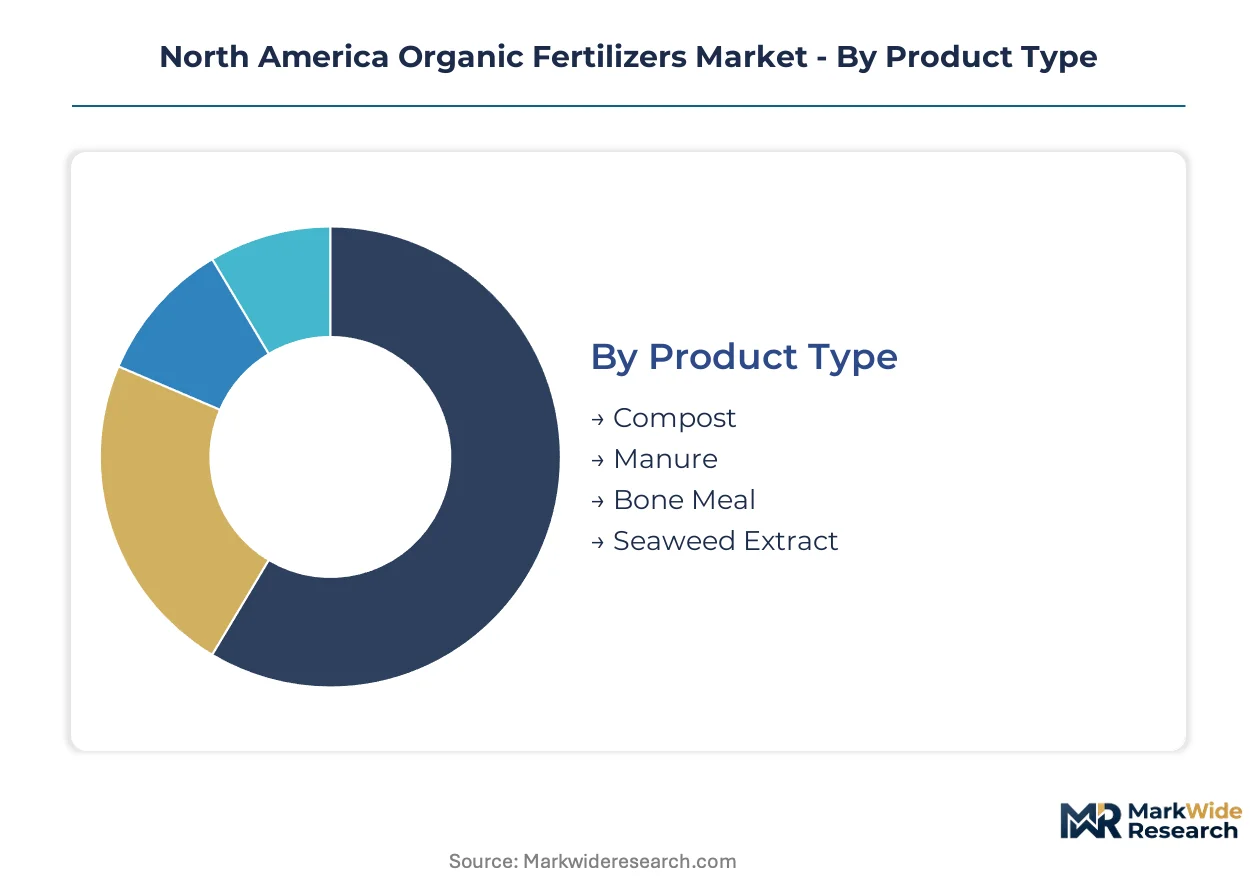
Segmentation in the North America organic fertilizers market reveals distinct procurement patterns across product types and end-use environments. Each dimension exposes different supply chain pressures, from municipal compost infrastructure to greenhouse precision application requirements.
Product Type:
Domestic production dominates compost and manure categories through established North American feedstock networks, while seaweed extract relies heavily on Atlantic and Pacific coastal harvest zones with Canadian Maritime licensing constraints.
- Compost:Aerobically processed organic matter from municipal curbside collection and agricultural residuals, typically achieving 1.5-3% nitrogen content by dry weight. Demand concentrates in California Central Valley vineyards and Washington State orchard operations ahead of CCOF certification deadlines. Municipal infrastructure expansion in Oregon and British Columbia diverts feedstock toward commercial manufacturing at scale.
- Seaweed Extract:Concentrated liquid formulations derived from kelp and brown algae through cold-press or alkaline extraction methods. Greenhouse operators in Ontario and controlled-environment agriculture facilities across the United States adopt foliar feeding protocols requiring rapid nutrient uptake. Atlantic coast kelp bed variability and Canadian licensing delays constrain raw material availability.
- Manure:Aerobically composted poultry, cattle, and swine litter processed to pathogen reduction standards under 40 CFR Part 503.
- Bone Meal:Steamed and ground animal bones providing phosphorus and calcium for specialty crop micronutrient supplementation.
Compost commands the established base. The steepest expansion runs through seaweed extract.
Application:
Volume scale separates field agriculture from high-value specialty segments, with cost-per-acre economics driving dramatically different formulation choices across the four application environments.
- Agricultural Fields:Large-scale row crop and permanent crop operations requiring bulk tonnage delivery and compatibility with conventional spreader equipment. Corn Belt commodity grain operators face persistent cost gaps against synthetic nitrogen alternatives, slowing organic transition. California vineyard and orchard operators absorb higher input costs to retain USDA National Organic Program certification status.
- Greenhouses:Controlled-environment agriculture facilities demanding precision liquid concentrate application systems for rapid nutrient uptake protocols. Dutch-Canadian technology licensors deploy microbial strain libraries to Ontario vertical farming facilities. Precision fermentation-derived biofertilizers displace traditional compost-based nitrogen sources in lettuce and tomato operations.
- Home Gardens:Consumer-scale packaging through garden center retail and direct-to-consumer digital channels.
- Turf Management:Golf course, municipal park, and sports field contracts requiring uniform coverage and aesthetic performance standards.
Agricultural fields absorb the volume base. Greenhouse applications are climbing the fastest.
Form:
Equipment compatibility and application precision determine form selection, with granular products leveraging existing agricultural machinery networks while liquid concentrates penetrate protected agriculture.
- Granular:Slow-release pellets and coarse particles distributed through conventional spinner spreaders and pneumatic application equipment. Compatibility with existing farm machinery preserves adoption economics for transitioning commodity operators. Suståne Natural Fertilizer anchors positioning through aerobically composted turkey litter granulation technology.
- Liquid:Concentrated extracts and suspensions enabling foliar feeding and fertigation integration in precision agriculture systems. Scotts Miracle-Gro competes through garden center shelf space and direct-to-consumer bottle formulations. Ontario and British Columbia controlled-environment facilities adopt precision dosing infrastructure.
- Powder:Fine-ground materials requiring dissolution or soil incorporation prior to plant availability.
- Pellets:Densified uniform particles reducing dust and improving handling characteristics for mechanical spreading.
Granular formulations hold the installed base. Liquid concentrates are gaining share fastest.
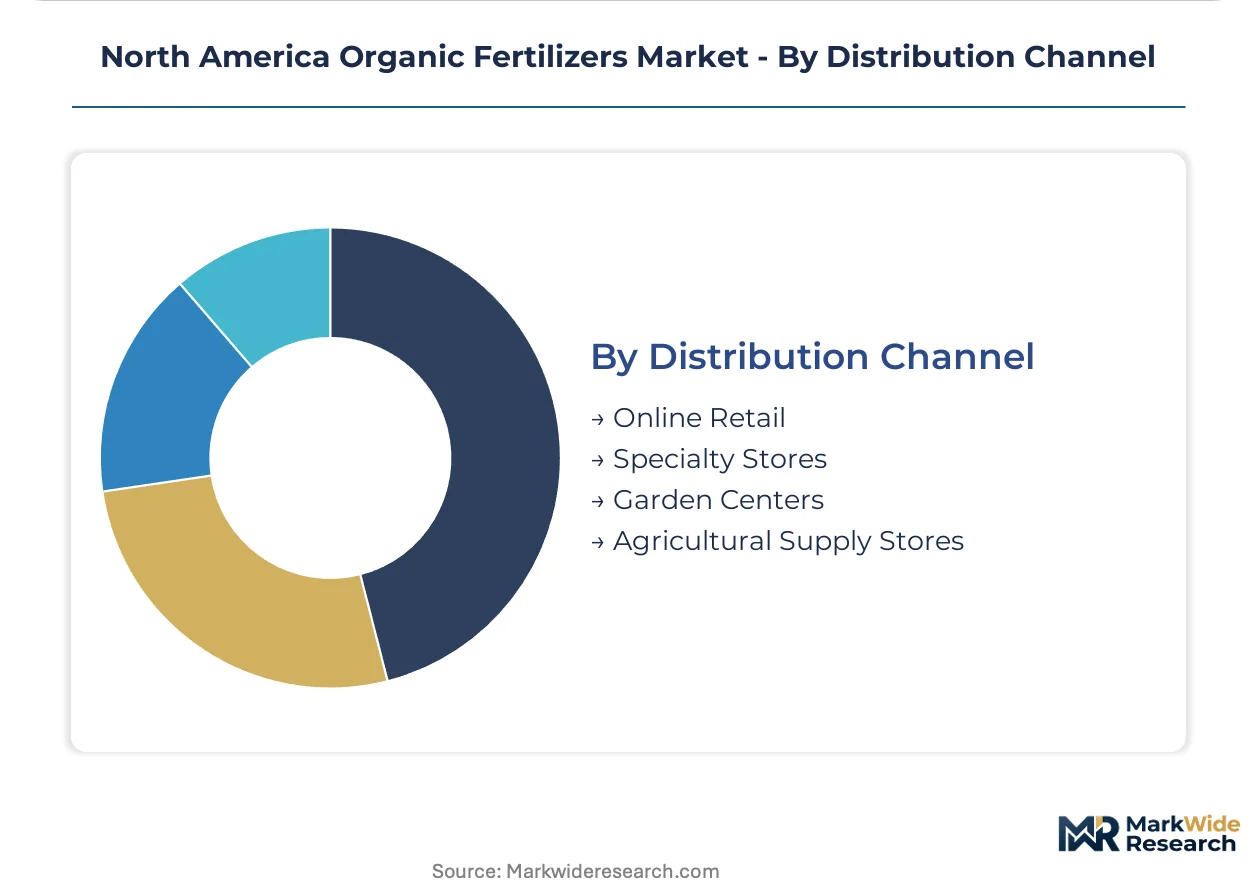
Distribution Channel:
Channel structure bifurcates between high-volume agricultural supply relationships and fragmented consumer access points, with digital platforms compressing traditional distributor layers.
- Agricultural Supply Stores:Regional and cooperative distributors serving commercial farming operations with bulk delivery, technical support, and traceability documentation for certification audits. Specialty crop operators in Florida's Belle Glade region and California's Imperial Valley contract directly with compost manufacturers for scheduled bulk delivery, bypassing traditional networks.
- Specialty Stores:Independent organic and sustainable agriculture retailers curating certified input portfolios for transition and certified operations. California, Washington, and Oregon state-level organic certification programs impose additional input material traceability obligations that filter supplier eligibility.
- Online Retail:Direct-to-grower digital procurement platforms enabling price transparency and scheduled delivery for remote operations.
- Garden Centers:Mass-market and independent retailers serving consumer lawn and garden segments with branded packaged goods.
Agricultural supply stores maintain the volume foundation. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach rail intermodal complex underwrites California's dominance in organic fertilizer distribution, connecting Central Valley production zones to Pacific Northwest and Southwest markets through dedicated bulk cargo corridors.
United States
California vineyard and orchard operators in Napa and Sonoma counties accelerate certified organic input procurement ahead of CCOF buffer zone enforcement deadlines. USDA National Organic Program standards reshape supplier qualification timelines across the state. The Imperial Valley specialty crop belt contracts directly with compost manufacturers for scheduled bulk delivery, bypassing traditional agricultural distributor networks.
Canada
Ontario and British Columbia controlled-environment agriculture facilities adopt precision liquid concentrate application systems for greenhouse lettuce and tomato operations. Canadian Food Inspection Agency fertilizer registration requirements enable streamlined cross-border distribution pathways for US manufacturers. The Fraser Valley mushroom substrate and berry production cluster sources municipal compost from Metro Vancouver's expanded curbside organics collection infrastructure.
Mexico
Sinaloa and Baja California protected agriculture exporters transition toward certified organic production protocols to maintain US market access. Mexico's national organic certification program aligns with USDA equivalency arrangements for seamless northbound shipment. The Bajío region strawberry and berry corridor develops dedicated composting partnerships with Guanajuato municipal waste authorities.
North America Organic Fertilizers Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and certification depth, producing a tiered structure where public companies leverage garden center shelf space while family-owned composters dominate bulk agricultural contracts. The vendor base separates into three strategic archetypes: West Coast vineyard specialists, Midwest poultry litter processors, and mass-market consumer brands. Capacity expansion and direct-to-grower digital procurement represent the dominant competitive moves reshaping distributor relationships.
Within the regional specialist tier, California Organic Fertilizers Inc. and Suståne Natural Fertilizer Inc. exemplify contrasting geographic anchoring strategies—West Coast compost manufacturing versus Midwest poultry litter processing. The Scotts Miracle-Gro Company occupies the mass-market position through garden center retail presence. These three represent the structural segmentation between agricultural bulk supply and consumer packaged goods channels.
| Leading Market Players |
|---|
| California Organic Fertilizers Inc. |
| Suståne Natural Fertilizer Inc. |
| The Scotts Miracle-Gro Company |
| Cedar Grove Composting Inc. |
| E.B. Stone & Sons Inc. |
| The Espoma Company |
| Central Iowa Organic Fertilizer |
| True Organic Products Inc. |
| Midwestern BioAg |
| Others |
Value Chain & Pricing Dynamics
Municipal composting capacity utilization above eighty percent in the Pacific Northwest creates scale economies that compress per-ton production costs and establish regional price floors below which smaller aerobic composters cannot sustainably operate. These scale dynamics concentrate supply authority among three West Coast operators while forcing Midwest poultry litter processors to absorb higher logistics costs to remain competitive in California vineyard contracts.
Pricing Analysis
Volume-discount tiering structures separate contract commitments into three levels: scheduled bulk delivery to agricultural fields commands the lowest per-unit rates, greenhouse precision concentrates extract mid-tier premiums, and garden center packaged goods capture the highest markup multiples. Certification grade under USDA National Organic Program standards and delivery distance from manufacturing clusters constitute the primary price differentiation drivers. Pricing pressure stems from synthetic nitrogen price arbitrage in Corn Belt commodity grain operations, where cost gaps persist against certified organic alternatives. Commodity grain operators exhibit the highest price sensitivity, while Napa and Sonoma vineyard operators absorb elevated input costs to retain organic certification status.
Supply Chain Analysis
Strategic stockpile preferences dominate agricultural field procurement, with California vineyard operators locking in eighteen-month supplier relationships ahead of planting cycles, whereas greenhouse operators maintain just-in-time liquid concentrate inventories given rapid foliar feeding turnover. Feedstock supply concentrates in the United States, Canada, and Mexico through municipal curbside collection infrastructure, Atlantic and Pacific coastal kelp harvest zones, and Midwest poultry litter processing clusters. Raw material dependencies rest on municipal organic waste streams, marine algae biomass, and aerobically composted poultry litter. Single-source vulnerability runs through Minnesota and Arkansas turkey litter operations controlling over sixty percent of certified feedstock. Distribution runs through agricultural supply stores, direct-to-grower digital platforms, and garden center retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than base product sales, with traceability documentation and certification audit support emerging as recurring-revenue layers commanding premium pricing above commodity compost tonnage.
For Market Incumbents: Compound defensive positioning through backward integration into municipal feedstock collection contracts and captive supply of PFAS-verified organic waste streams. Precision fermentation-derived biofertilizers threaten traditional compost-based nitrogen in protected agriculture, requiring incumbents to deepen microbial consortia expertise through targeted R&D investment in anaerobic digestion partnerships. For New Entrants and Emerging Players: Anchor in Mexico's Sinaloa and Baja California protected agriculture corridors, where USDA equivalency arrangements enable seamless northbound shipment and local composting infrastructure remains underdeveloped. Direct-to-grower digital procurement platforms offer the most penetrable channel, bypassing entrenched agricultural distributor relationships through scheduled bulk delivery contracts with traceability documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among composters with locked municipal feedstock agreements and multi-year vineyard supply contracts. Long-term viability across the five-to-ten year window favors operators with verified PFAS-free feedstock chains ahead of Washington and Maine enforcement thresholds. Acquisition targets should demonstrate established CCOF certification pathways and existing rail intermodal access. The signal to watch is state-level PFAS limit legislation crossing implementation thresholds, which will abruptly disqualify legacy composters with contaminated feedstock sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Municipal Feedstock | Secures captive supply of CCOF-compliant organic waste streams ahead of certification deadlines. |
| PFAS-Free Feedstock Verification Program | Creates first-mover advantage under emerging Washington and Maine state legislation. |
| Direct-to-Grower Digital Platform Launch | Bypasses traditional agricultural distributor networks in California Imperial Valley and Florida Belle Glade. |
| Precision Liquid Concentrate Capacity Expansion | Captures greenhouse foliar feeding demand in Ontario and British Columbia controlled-environment facilities. |
| Cross-Border CFIA Registration Completion | Enables streamlined US manufacturer distribution into Canadian prairie agricultural markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with compost manufacturing plant managers, vineyard procurement directors at Central Valley operations, greenhouse facility operators in Ontario, agricultural supply cooperative buyers, and USDA National Organic Program certification auditors. Secondary validation drew from EPA 40 CFR Part 503 filings, Canadian Food Inspection Agency fertilizer registration databases, California CCOF certification records, municipal curbside organics collection reports, and SEC 10-K disclosures from listed agricultural input companies. Bottom-up volume modeling triangulated against top-down value estimates across product type, application environment, and form factor dimensions.
Across the analysis window, the forecasting framework modeled segmentation dimensions including compost versus seaweed extract versus manure product categories, agricultural field versus greenhouse versus home garden applications, and granular versus liquid versus powder forms. CAGRs were derived through trend extrapolation of historical procurement patterns and regulatory deadline impacts. Industry-specific inputs incorporated CCOF buffer zone enforcement timelines, EPA biosolids pathogen reduction standards, and Canadian Maritime kelp harvest licensing constraints.
Material uncertainties — Atlantic coast kelp bed variability, state PFAS limit legislation progression, and synthetic nitrogen price volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding enforcement consistency and feedstock availability without guarantee. Revision becomes warranted when regulatory threshold crossings or supply disruptions exceed modeled sensitivity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Mineral Fertilizers Market