
 Japan Greenhouse Horticulture Market | 2026-2036
Japan Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Greenhouse Horticulture Market Insights
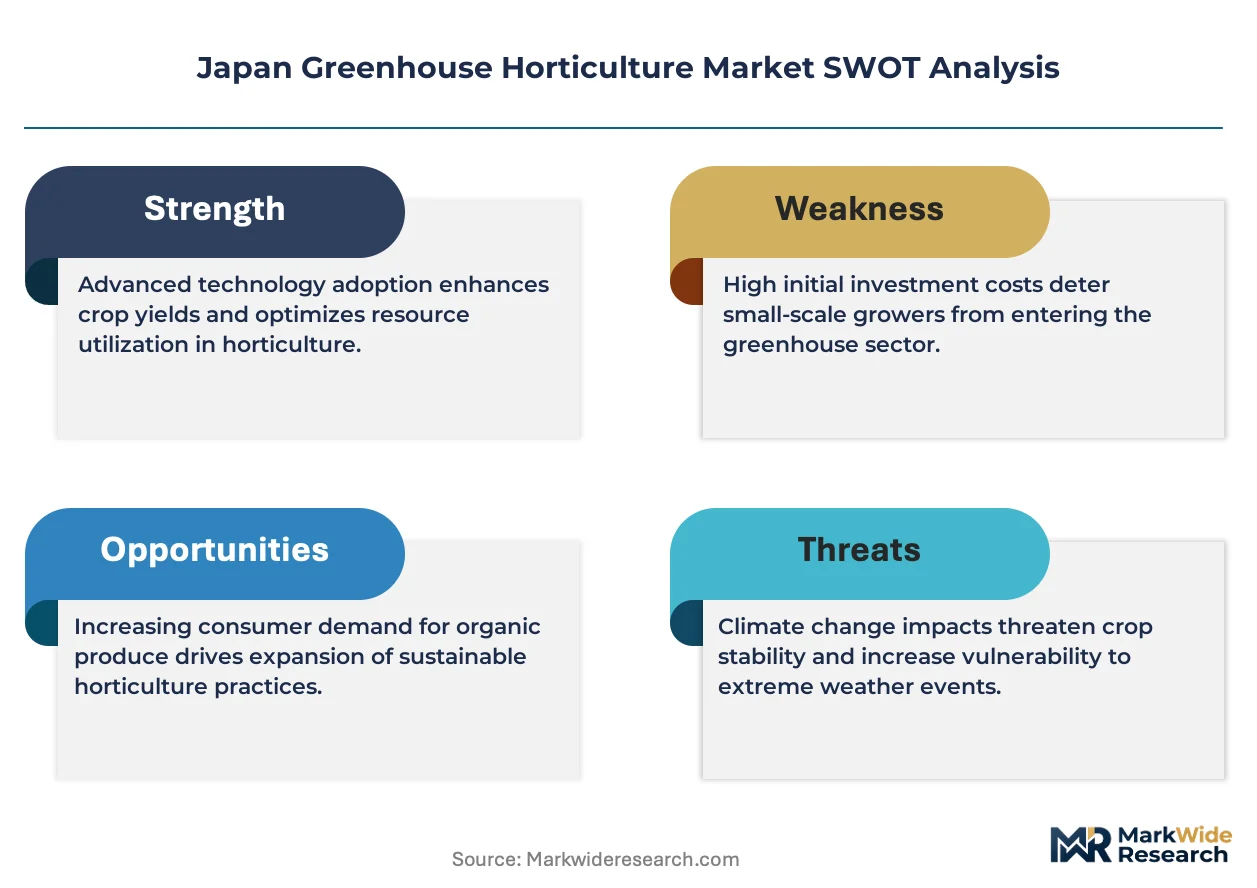
Aging farm labor pools in rural prefectures is redrawing competitive dynamics across Japan's protected-culture sector. DENSO Corporation leverages its automotive sensor expertise to develop precision environmental controls for glasshouse operators. Signify Co. Ltd. anchors its position through Philips-branded horticultural LED systems optimized for low-energy Japanese utility tariffs. GRA&GREEN specializes in grafting technology that extends crop viability against soil-borne pathogens in humid greenhouse conditions.
Greenhouse horticulture encompasses the cultivation of vegetables, fruits, flowers, and herbs within controlled-environment structures using regulated temperature, humidity, light spectra, and CO2 enrichment to optimize photosynthetic efficiency and yield consistency year-round. Hydroponics dominates the technology dimension due to its water-use efficiency and compatibility with Japan's limited arable land base, while soil-based systems retain share among herb growers prioritizing terroir-linked flavor profiles. Vegetables command the largest product-type volume, though flowers generate disproportionate margin pools through premium cultivars sold via direct sales channels to funeral and ceremonial markets.
METI enforces energy-conservation standards that shape capital-investment decisions for heating and lighting systems, while the Ministry of Agriculture, Forestry and Fisheries administers subsidy programs for smart-agriculture infrastructure that reduce operational carbon intensity. JIS standards for agricultural machinery and structural materials govern equipment procurement and greenhouse construction specifications. Stakeholders must monitor evolving prefectural ordinances on agricultural land conversion and water-use permits as urban encroachment intensifies competition for production sites near major consumption centers.
Market Dynamics
METI energy-efficiency mandates are compressing capital-deployment timelines for greenhouse operators, forcing simultaneous LED retrofits and climate-control upgrades across Aichi and Shizuoka prefectures where glasshouse density concentrates.
Growth Catalysts
- Smart-agriculture subsidies:MAFF infrastructure grants reduce operational carbon intensity for operators adopting sensor-integrated environmental controls.
- Chubu glasshouse cluster:Aichi and Shizuoka prefectures host Japan's densest concentration of vegetable operations, generating knowledge spillovers and specialized supplier ecosystems.
- Contracted procurement expansion:Tokyo and Osaka restaurant chains are locking in long-term supply agreements for greenhouse-grown produce, de-risking operator revenue streams.
Market Restraints
- Utility tariff volatility:Electricity costs for climate control and supplemental lighting fluctuate with regional grid capacity constraints, squeezing margin predictability for mid-scale operators.
- Equipment import concentration:Advanced LED systems and environmental sensors rely heavily on specialized foreign suppliers, exposing procurement to currency and logistics friction.
- Arable land scarcity:Japan's mountainous topography limits viable greenhouse sites near major consumption centers, inflating land-acquisition costs in peri-urban zones.
Strategic Opportunities
- Kyushu underpenetration:Fukuoka and Kagoshima prefectures maintain lower glasshouse density despite favorable winter light conditions, offering first-mover expansion potential.
- Ceremonial flower direct channels:Funeral and wedding markets accept premium pricing for rare cultivars, rewarding operators who bypass wholesale intermediaries.
- Sensor-LED convergence:Integration of spectral-tunable lighting with real-time crop monitoring enables dynamic photosynthetic optimization previously requiring manual intervention.
Industry Challenges
- Agronomic technician shortage:Rural prefectures face acute scarcity of operators trained in hydroponic nutrient management and integrated pest management protocols.
- JIS certification timelines:Agricultural machinery approvals delay deployment of imported automation equipment, compressing effective growing seasons for retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Greenhouse Horticulture Market |
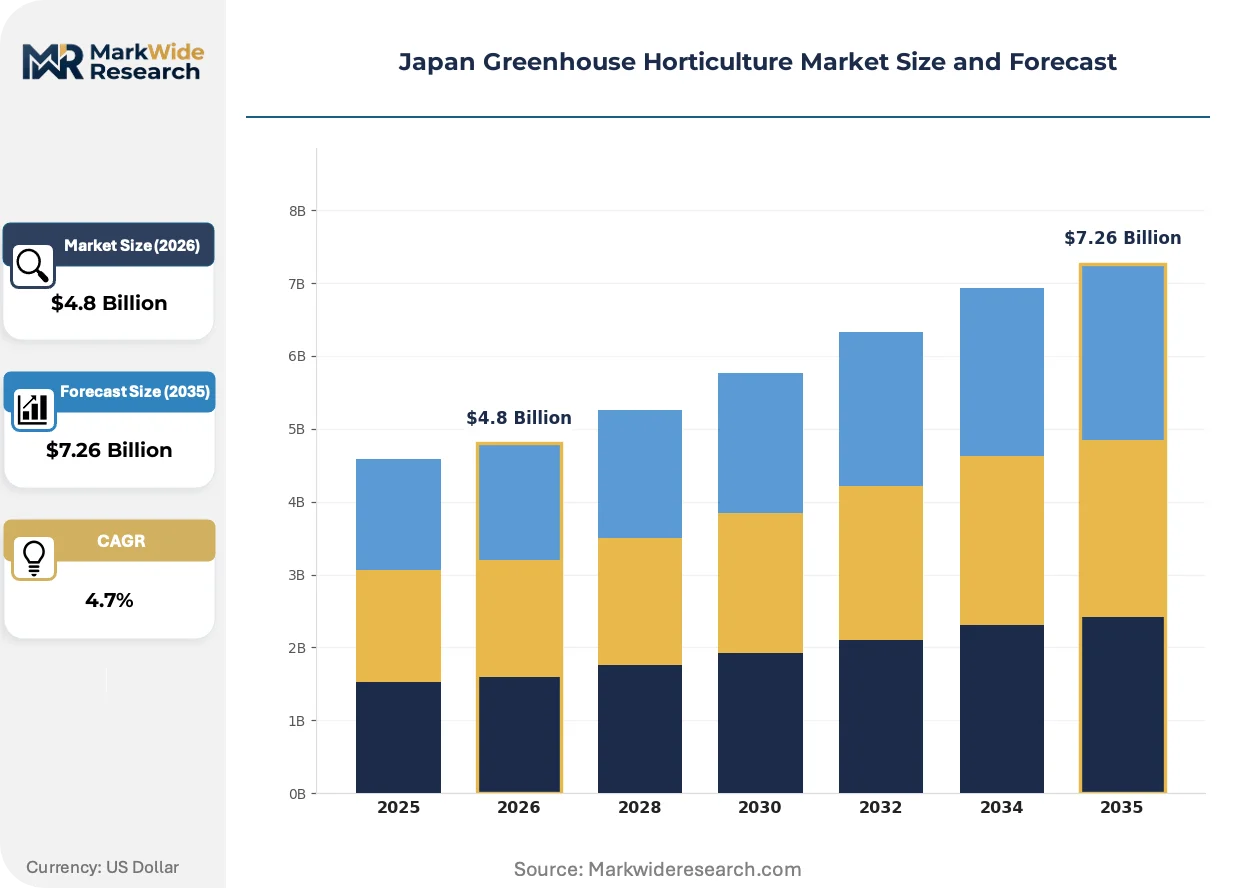
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Flowers, Herbs Technology: Hydroponics, Aeroponics, Soil-Based, Aquaponics End User: Retailers, Restaurants, Wholesalers, Home Gardeners Delivery Mode: Direct Sales, E-Commerce, Local Markets, Export |
| Companies Covered | Japan Greenhouse Horticulture Association, Greenase, DENSO Corporation, Kumiai Chemical Industry Co. Ltd, GRA&GREEN, Signify Co. Ltd., Plants Laboratory, OAT Agrio Co. Ltd, Nexus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Greenhouse Horticulture Market Trends and Innovations
Automation architectures are penetrating deeper into crop-level operations, shifting competitive advantage from scale economies toward precision-control capabilities and data-driven cultivation protocols.
Multispectral imaging systems for early-stage disease detection and yield forecasting are miniaturizing from drone-mounted units to fixed greenhouse installations. Aichi-based tomato and cucumber operators are deploying these sensors at sub-1000 square meter facilities previously priced out of precision agriculture. The technology is miniaturizing hardware cost structures while expanding addressable operator segments beyond industrial-scale glasshouses.
METI's 2024 revision to energy-conservation standards for agricultural facilities mandates minimum efficacy thresholds for supplemental lighting and thermal envelope performance. Operators must now document carbon intensity metrics to qualify for MAFF smart-agriculture grants. Vegetable producers in Shizuoka are responding by accelerating LED retrofit schedules and consolidating heating systems to meet compliance windows.
Direct-to-restaurant procurement is displacing traditional wholesale auction channels for premium greenhouse vegetables. Tokyo-based fine-dining groups now contract specific cultivars and harvest windows, transferring inventory risk upstream to growers. This pattern concentrates most visibly in the Kanto corridor where chef-operated establishments cluster and logistics infrastructure supports just-in-time harvest delivery.
Japan Greenhouse Horticulture Market Segmentation
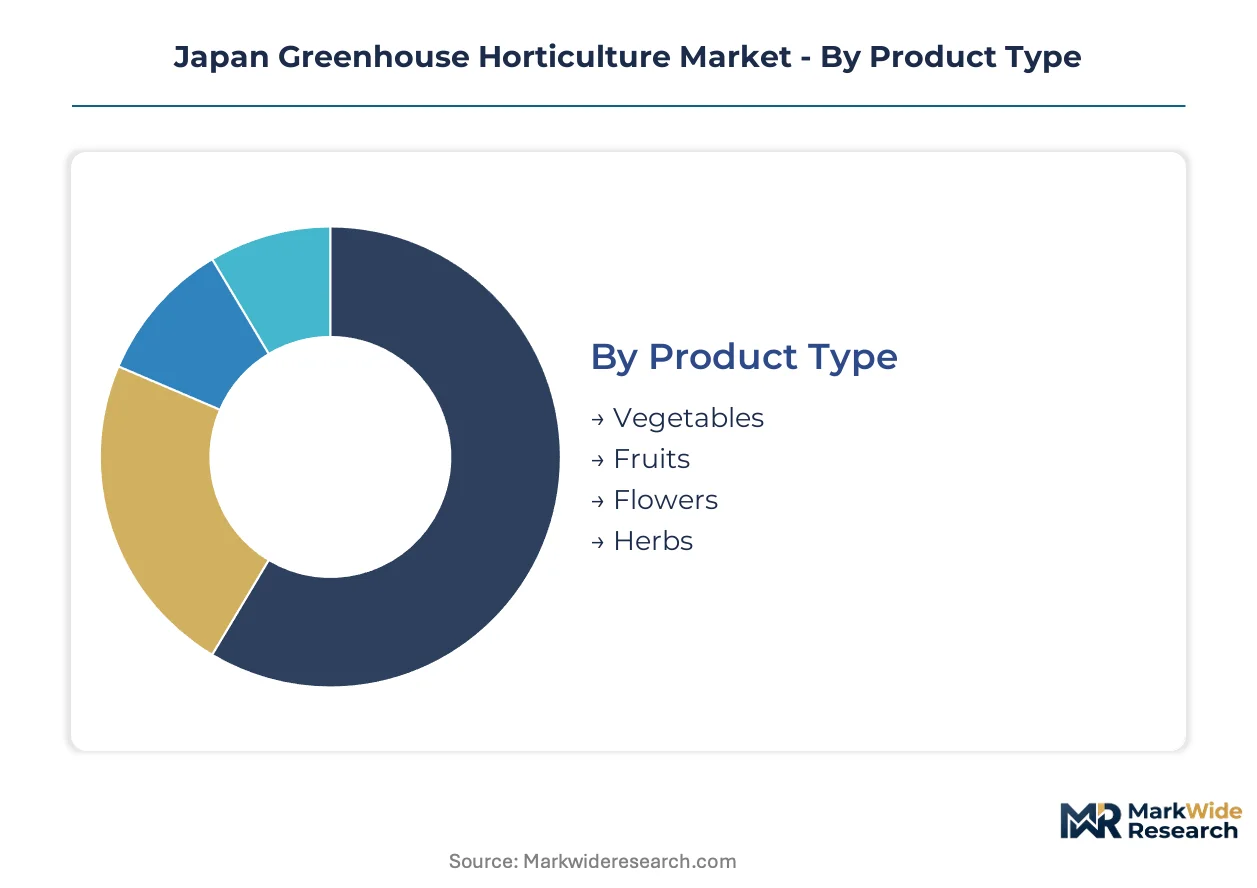
Segmentation reveals how margin pools concentrate across Japan's protected-culture sector. Product type and technology choices determine capital intensity and regulatory exposure, while end-user and delivery-mode selections shape working-capital requirements and price realization.
Product Type:
Margin pools concentrate in flowers and premium vegetables where direct-channel pricing power offsets energy costs.
- Vegetables:Tomatoes, cucumbers, and leafy greens dominate tonnage output across Aichi and Shizuoka glasshouse clusters. Tokyo restaurant chains contract specific harvest windows, transferring inventory risk upstream while securing supply consistency.
- Flowers:Premium cultivars for funeral and wedding ceremonies command disproportionate margins through direct sales channels. Rare varieties bypass wholesale intermediaries entirely, with pricing power anchored in ceremonial occasion rigidity.
- Fruits:Strawberries and melons occupy niche glasshouse acreage where controlled environments enable off-season premium positioning.
- Herbs:Soil-based systems retain share among growers prioritizing terroir-linked flavor profiles for culinary and medicinal applications.
The dominant share belongs to Vegetables, while Flowers is closing the gap fastest through ceremonial market premiumization.
Technology:
Cost tiers separate water-intensive from substrate-dependent systems, with energy efficiency mandates compressing deployment timelines.
- Hydroponics:Water-use efficiency and compatibility with Japan's limited arable land base drive adoption across Chubu vegetable operations. METI energy standards favor recirculating nutrient systems that minimize thermal load.
- Soil-Based:Herb growers and traditional operators maintain share where flavor differentiation justifies higher land and labor inputs per unit output.
- Aeroponics:Mist-based root delivery reduces water consumption further but requires precise environmental control infrastructure concentrated at research-forward facilities.
- Aquaponics:Integrated fish-vegetable systems remain experimental, with operational complexity limiting commercial scale despite circular-economy appeal.
Hydroponics holds the installed base advantage, though Aeroponics is expanding most quickly in new greenhouse construction.
End User:
Customer type determines contract structure stability and payment-term risk exposure across the value chain.
- Restaurants:Fine-dining groups in Tokyo and Osaka lock in long-term procurement agreements for specific cultivars, de-risking grower revenue streams while demanding just-in-time harvest delivery.
- Retailers:Supermarket chains concentrate volume procurement through centralized distribution centers, squeezing margin through scale leverage and quality consistency requirements.
- Wholesalers:Traditional auction channels retain share for commodity-grade output but face displacement as direct contracting expands.
- Home Gardeners:Hobby-scale equipment and seedling sales generate ancillary revenue for suppliers with retail distribution reach.
Restaurants anchor premium pricing, while Retailers capture volume concentration.
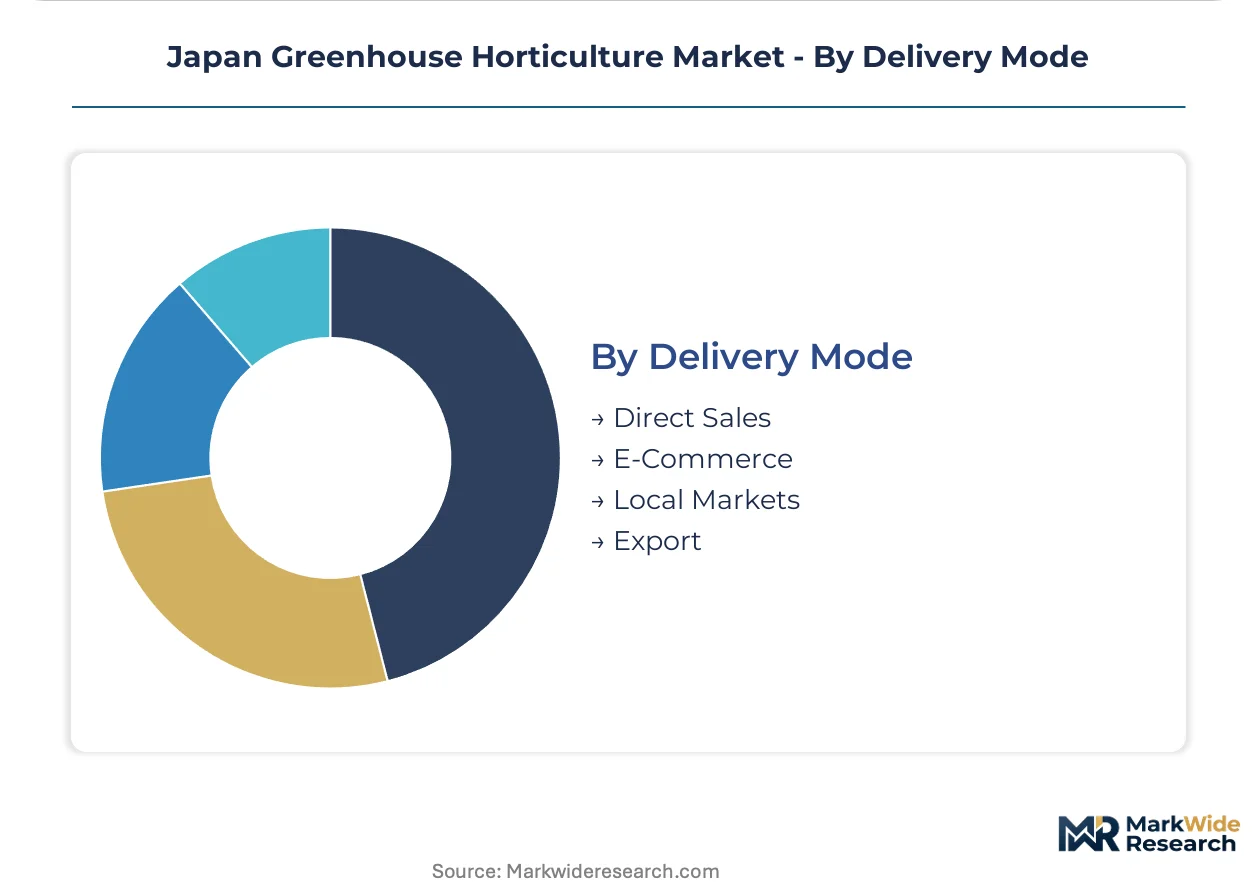
Delivery Mode:
Channel selection shapes logistics infrastructure requirements and customer relationship intimacy.
- Direct Sales:Funeral and wedding flower markets accept premium pricing for rare cultivars, rewarding operators who bypass wholesale intermediaries entirely.
- E-Commerce:Subscription vegetable boxes and specialty seedling orders expand addressable geography beyond Kanto corridor logistics reach.
- Local Markets:Prefectural agricultural cooperatives maintain presence for commodity-grade output with shorter shelf-life requirements.
- Export:High-value flowers and premium vegetables target Asian markets with Japanese quality association, though phytosanitary certification adds procedural friction.
Direct Sales commands margin leadership, while E-Commerce is gaining share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chubu prefectures consume greenhouse produce through industrial-scale vegetable contracts, while Kanto channels output toward fine-dining procurement networks with distinct logistics requirements.
Chubu Region
Aichi and Shizuoka prefectures concentrate Japan's densest glasshouse vegetable operations, with tomato and cucumber clusters generating knowledge spillovers across supplier ecosystems. METI energy-efficiency mandates are compressing capital-deployment timelines for LED retrofits and climate-control upgrades across this corridor. Nagoya anchors specialized equipment procurement networks serving regional operators.
Kanto Region
Tokyo restaurant chains are expanding contracted procurement of greenhouse-grown produce, transferring inventory risk upstream to growers while demanding just-in-time harvest delivery. MAFF smart-agriculture subsidies reduce operational carbon intensity for operators adopting sensor-integrated environmental controls. Saitama and Chiba prefectures host peri-urban glasshouse development facing land-acquisition cost pressures from urban encroachment.
Kansai Region
Osaka-based fine-dining groups are locking in long-term supply agreements for specific cultivars and harvest windows. The country's national agricultural administration administers infrastructure grants that shape investment patterns across Hyogo and Kyoto prefectures. Kobe and Osaka metropolitan zones concentrate demand for premium greenhouse vegetables bypassing traditional wholesale channels.
Kyushu Region
Fukuoka and Kagoshima prefectures maintain lower glasshouse density despite favorable winter light conditions, offering first-mover expansion potential for operators seeking lower land costs. Prefectural ordinances on agricultural land conversion and water-use permits require monitoring as competition intensifies for production sites. Kitakyushu is emerging as a logistics hub connecting Kyushu output to mainland consumption centers.
Hokkaido
Cooler summer temperatures reduce cooling loads for greenhouse operations, though heating costs during extended winters challenge margin structures. The country's national agricultural administration channels subsidy programs toward smart-agriculture infrastructure in northern prefectures. Sapporo metropolitan demand concentrates around high-value flower cultivars for ceremonial markets.
Japan Greenhouse Horticulture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with automotive-heritage conglomerates and lighting multinationals occupying positions alongside grafting-technology pure-plays and agricultural-chemical incumbents. The competitive terrain separates sensor-integrated environmental control providers from crop-biology specialists and input-materials suppliers. Two dominant competitive moves are shaping positioning: technology licensing partnerships bridging automotive sensor expertise into precision agriculture, and vertical consolidation of LED hardware with spectral-tuning software capabilities.
Within the precision-control tier, DENSO Corporation exemplifies the automotive-to-agriculture technology transfer archetype, while Signify Co. Ltd. anchors the horticultural lighting segment through Philips-branded systems. GRA&GREEN occupies a specialist position in grafting technology for humid greenhouse conditions. These three entities represent distinct competitive vectors—industrial automation heritage, lighting-systems scale, and crop-biology specialization—rather than overlapping directly in product-market space.
| Leading Market Players |
|---|
| Japan Greenhouse Horticulture Association |
| Greenase |
| DENSO Corporation |
| Kumiai Chemical Industry Co. Ltd |
| GRA&GREEN |
| Signify Co. Ltd. |
| Plants Laboratory |
| OAT Agrio Co. Ltd |
| Nexus Corporation |
| Others |
Pricing and Supply Chain Analysis
Glasshouse capacity utilization above eighty percent in Aichi and Shizuoka prefectures compresses marginal production costs and establishes regional price floors that smaller operators in peripheral prefectures struggle to undercut. This scale concentration reinforces contract-based procurement dominance as Tokyo and Osaka restaurant chains leverage volume commitments to lock in supply security.
Pricing Analysis
Long-term offtake agreements between Chubu glasshouse operators and Kanto restaurant chains dominate transaction structures, transferring inventory risk upstream while securing harvest-window specificity. Price differentiation rests on cultivar rarity and METI energy-efficiency certification tiers, with premium tiers commanding substantial markups for ceremonial flower markets. Cost compression in mid-tier vegetable segments intensifies as LED retrofit capital costs amortize across shorter depreciation schedules. Retail procurement teams exhibit highest price sensitivity, while funeral market buyers demonstrate near-inelastic demand for designated rare cultivars.
Supply Chain Analysis
Just-in-time harvest delivery preferences among Tokyo fine-dining groups compress field-to-kitchen timelines below twenty-four hours, eliminating strategic stockpiling from downstream operations. Geographic supply concentration centers on Japan's Chubu corridor for finished produce, with critical LED and sensor hardware drawing from Netherlands, China, and South Korea manufacturing bases. Raw material dependencies span semiconductor-grade substrates, phosphor compounds for spectral tuning, and climate-control aluminum extrusions. Single-source vulnerability in specialized horticultural LED chipsets exposes operators to logistics chokepoint risk. Distribution runs through prefectural agricultural cooperatives for commodity tiers and dedicated cold-chain logistics for premium direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's 2024 energy-conservation standards revision constitutes a regulatory inflection accelerating capital-deployment timelines and reshaping competitive viability thresholds across Japan's protected-culture sector.
For Market Incumbents: Fortify market position through backward integration into LED hardware assembly and captive nutrient formulation production, reducing exposure to currency volatility in imported input costs. Prioritize JIS certification pre-approval for next-generation environmental control equipment to compress deployment lead times ahead of competitor retrofits. For New Entrants and Emerging Players: Anchor in Kyushu's underpenetrated Fukuoka and Kagoshima prefectures where land costs trail Chubu benchmarks and winter light conditions favor year-round production economics. Target ceremonial flower direct channels where wholesale bypass enables margin capture unavailable in commoditized vegetable segments. Pursue equipment-leasing partnerships with sensor-LED convergence specialists to minimize upfront capital barriers. For Investors and Strategic Acquirers: Precision environmental control software developers with demonstrated MAFF subsidy qualification track records represent the most defensible acquisition archetype for portfolio exposure to Japanese smart-agriculture infrastructure buildout. Monitor METI enforcement action intensity against non-compliant glasshouse operators as signal for consolidation acceleration timing.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Acceleration | METI compliance deadlines force simultaneous climate-control upgrades across Aichi and Shizuoka glasshouse clusters. |
| Direct Procurement Partnership | Tokyo restaurant chains lock in supply security while transferring inventory risk upstream to growers. |
| Sensor-LED Convergence Integration | Real-time crop monitoring enables dynamic photosynthetic optimization previously requiring manual intervention. |
| Kyushu Geographic Expansion | Fukuoka and Kagoshima prefectures offer first-mover land-cost advantages despite lower current glasshouse density. |
| Ceremonial Flower Channel Control | Bypassing wholesale intermediaries captures premium pricing from funeral and wedding market rigidity. |
Research Methodology
A spread of perspectives from glasshouse operators, agricultural equipment procurement managers, MAFF subsidy program administrators, and restaurant supply chain directors converged on the working assumptions underlying demand and investment trajectory assessments. Primary fieldwork combined structured interviews with secondary validation through MAFF smart-agriculture grant disbursement records, METI energy-efficiency compliance filings, prefectural agricultural cooperative shipment data, and JIS certification timelines. Bottom-up facility-level capacity estimates triangulated against top-down regional production value aggregates.
Segmentation dimensions modeled span product type, cultivation technology, end-user category, and delivery mode across the projection horizon. CAGRs derived from regression analysis against historical MAFF infrastructure investment cycles and METI regulatory phase-in patterns. Industry-specific forecast inputs incorporated utility tariff trajectory assumptions and LED efficacy improvement curves from horticultural lighting R&D disclosures.
Material uncertainties — utility tariff volatility, JIS certification delays for imported automation equipment, and prefectural land-use ordinance evolution — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as METI enforcement intensity and MAFF subsidy allocation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dried Peas Market
Vegetables
Asparagus Market
Vegetables
Greenhouse Produce Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Yam Products Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Dry Onion Market
Vegetables
Fresh Mushroom Market
Vegetables
Global Indoor Plant Market
Vegetables
Butternut Squash Market
Vegetables
Canada Microgreens Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Field Peas Market
Vegetables
United States Microgreens Market
Vegetables
Global Mushroom Market
Vegetables
Europe Flowers and Ornamental Plants Market