
 Chelated Iron Agriculture Micronutrient Market | 2026-2036
Chelated Iron Agriculture Micronutrient Market Size, Share, and Industry Trends Forecast 2026-2036
Chelated Iron Agriculture Micronutrient Market Outlook
REACH compliance is broadening the cost-of-entry calculus for chelated iron manufacturers targeting European agricultural markets. BASF SE leverages its integrated ethylenediamine supply chain to sustain cost advantages in EDDHA production. Yara International anchors its position through controlled-release formulation expertise across Nordic and Latin American markets. Nutrien competes via its retail agronomy network that pushes micronutrient bundles directly to North American row-crop operators.
Chelated iron agriculture micronutrient denotes iron ions bound to organic ligands such as EDTA, DTPA, or EDDHA to prevent precipitation in alkaline soils and ensure plant bioavailability through root uptake or foliar absorption. The primary commercial purpose centers on correcting iron chlorosis in high-pH calcareous soils where free iron salts become insoluble and unavailable to crops. Iron EDDHA commands the premium tier due to superior stability across pH ranges above 7.5, while foliar application methods represent the fastest-growing delivery channel as precision agriculture platforms enable variable-rate aerial spraying. Soil application retains volume leadership in broadacre contexts where fertigation infrastructure remains limited.
The EPA governs chelated iron tolerances and residue limits under the Federal Insecticide, Fungicide, and Rodenticide Act framework, while the EU Fertilizing Products Regulation mandates CE conformity for all fertilizing products placed on the European market. Brazil's national agricultural regulator enforces ANVISA-aligned import protocols that delay market access for unregistered chelated formulations. Stakeholders must monitor evolving heavy-metal thresholds and digital traceability mandates that will determine which formulation chemistries retain multi-region commercial viability.
Market Dynamics
Alkaline soil expansion across major agricultural belts is forcing chelated iron adoption as the default correction strategy for iron chlorosis, with pH-stability requirements now dictating formulation chemistry selection over price alone.
Growth Catalysts
- Brazil's Cerrado Expansion:Soybean operators in this high-pH belt require consistent EDDHA procurement to sustain yields, creating durable demand pull from the world's largest oilseed export region.
- EU Fertilizing Products Regulation:CE conformity mandates for heavy-metal thresholds accelerate premium formulation uptake across member states as legacy products face market withdrawal.
- Fertigation Infrastructure:Drip irrigation proliferation in California almond orchards and Spanish citrus groves enables precise chelated iron delivery that foliar spraying cannot match for efficiency.
Market Restraints
- Ethylenediamine Supply Concentration:Three integrated chemical producers control EDDHA precursor availability, exposing formulators to input volatility and allocation risk during plant turnarounds.
- REACH Registration Burden:European manufacturers face six-figure dossier costs for novel chelating agents, freezing innovation pipelines for mid-tier compounders without captive toxicology resources.
- Free Iron Salt Substitution:Acidic soil growers in the US Southeast and Southeast Asia continue deploying ferrous sulfate at one-fifth the chelated cost, capping price elasticity in pH-neutral zones.
Strategic Opportunities
- Controlled-Release Convergence:Polymer-coated chelated iron blends with nitrogen stabilizers offer bundled micronutrient programs that command 40-60% application-labor savings in broadacre corn and wheat.
- ANVISA Registration Arbitrage:First-mover advantage awaits suppliers completing Brazil's import protocol validation for novel EDDHSA formulations ahead of domestic capacity expansion.
- Drone-Based Foliar Platforms:Variable-rate aerial spraying systems in Australia's Murray-Darling Basin and France's Champagne region enable site-specific iron correction that soil application cannot achieve.
Industry Challenges
- Analytical Chemist Shortage:Complexometric titration expertise for chelate stability verification remains scarce outside Basel, Ludwigshafen, and São Paulo technical centers, delaying batch release timelines.
- Legacy ERP Integration:Fertilizer blenders retrofitting chelated iron into existing NPK formulation software encounter unit-conversion errors that disrupt inventory accuracy and order fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelated Iron Agriculture Micronutrient Market |
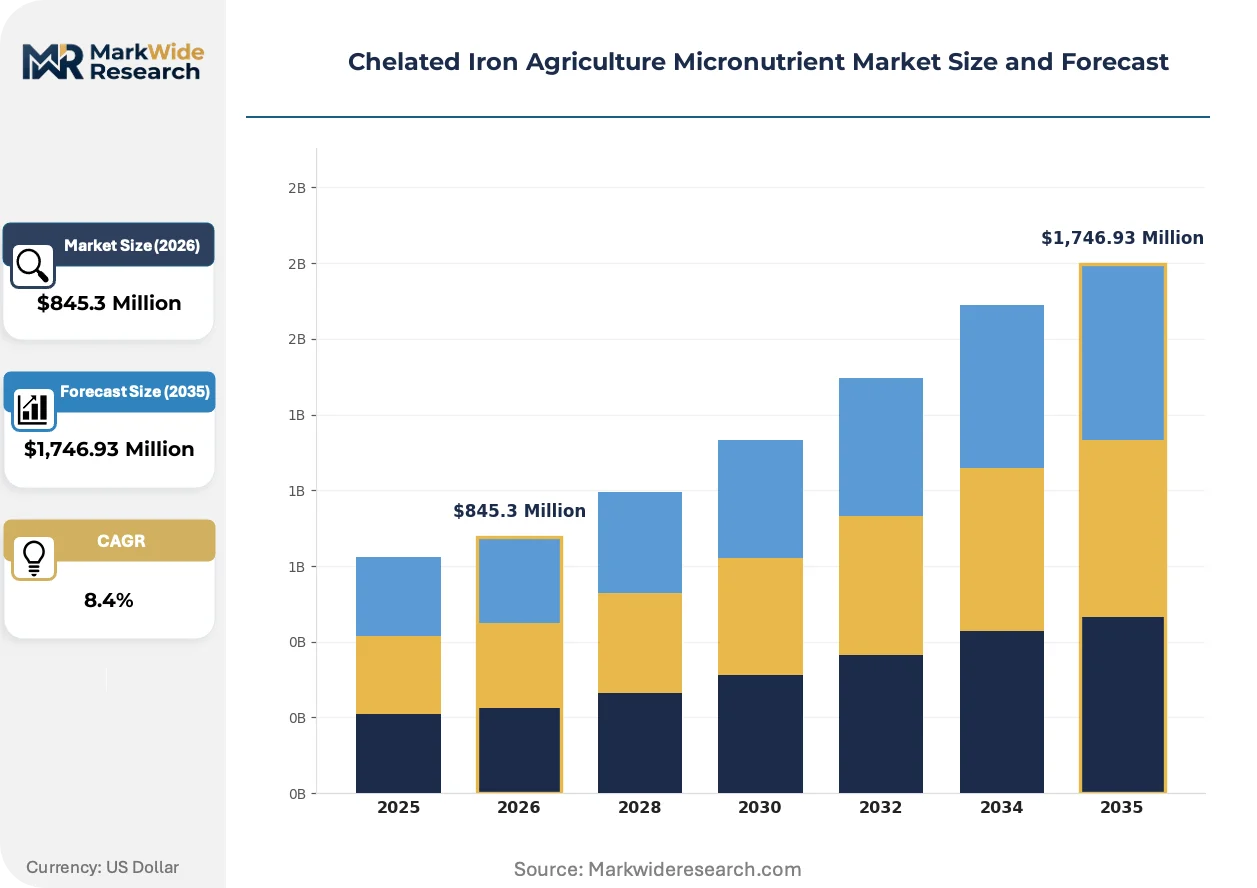
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $1,746.93 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron EDTA, Iron DTPA, Iron EDDHA, Iron Gluconate End Use Industry: Crops, Fruits, Vegetables, Turf Application Method: Soil Application, Foliar Application, Fertigation, Seed Treatment Packaging Type: Granules, Powders, Liquid, Others |
| Companies Covered | BASF SE, Yara International, Nutrien, ICL Specialty Fertilizers, Haifa Group, AkzoNobel, Bayer CropScience, The Mosaic Company, Nouryon Chemicals Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelated Iron Agriculture Micronutrient Market Strategic Shifts
Precision agriculture platforms are compressing application windows and demanding chelated iron products compatible with real-time sensor feedback, forcing reformulation around spray tank compatibility and residue profiles rather than standalone agronomic efficacy.
Sensor-guided variable-rate application technology is automating chelated iron distribution decisions across California's Central Valley almond operations. Growers with capacitance-based soil mapping systems now trigger foliar interventions at 50-meter resolution, replacing calendar-based spraying. This capability is automating procurement patterns toward pre-mixed, drone-compatible concentrates that eliminate on-farm tank-mixing errors.
REACH authorization timelines for novel chelating agents now stretch 18-24 months beyond previous windows, compressing European manufacturers' product pipeline velocity. ECHA's expanded data requirements for biodegradation endpoints force reformulators toward EDDHSA and HBED chemistries with superior environmental fate profiles. Specialty crop segments in Italy's Po Valley and Spain's Almería greenhouse belt absorb these cost premiums most readily given their output value density.
Direct-to-farm digital channels are displacing traditional cooperative distribution for micronutrient procurement in North American row-crop segments. Agronomy platforms like Farmers Business Network and Indigo Ag enable price transparency and bundled financing that legacy dealer networks cannot match. This shift concentrates most visibly in Iowa and Illinois corn-soy operations where input cost scrutiny intensified following 2023 fertilizer price volatility.
Chelated Iron Agriculture Micronutrient Market Segmentation
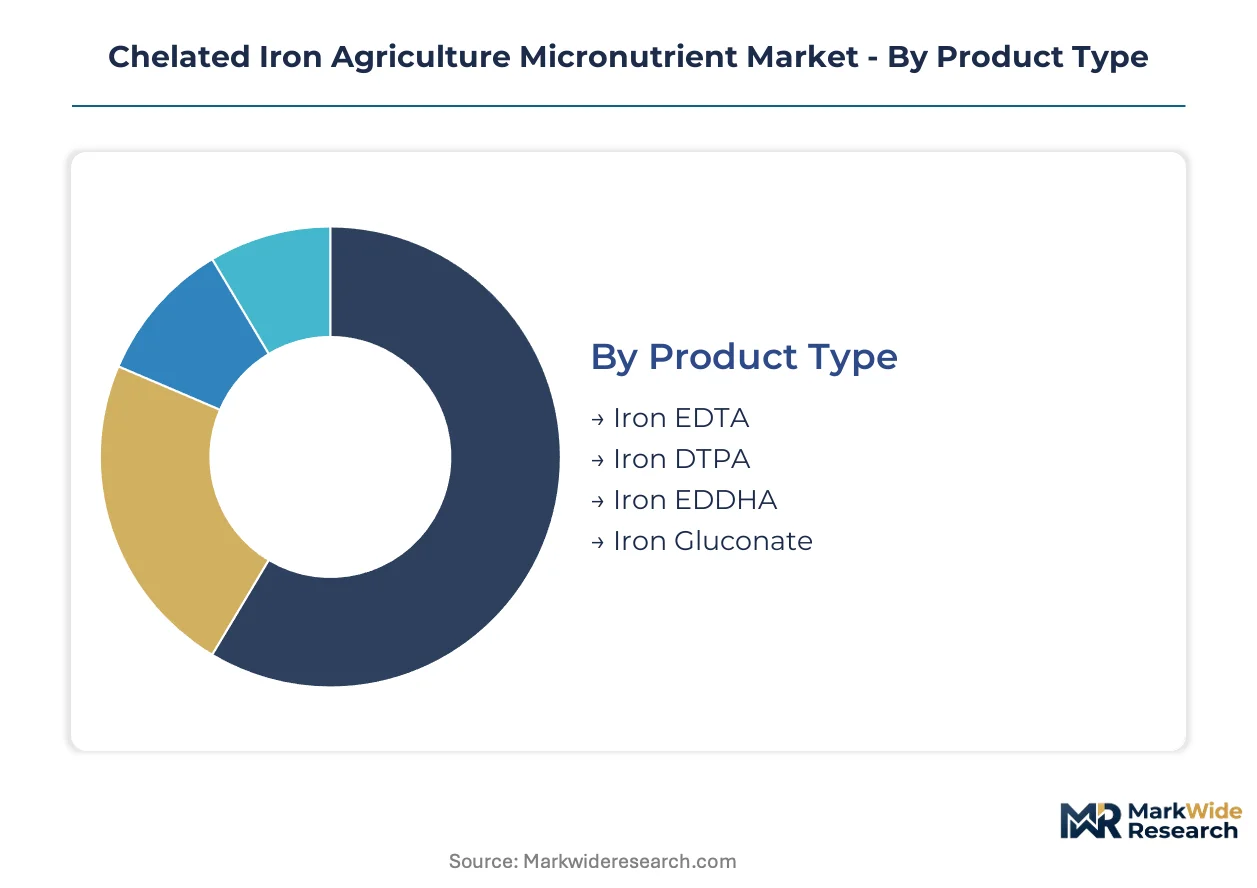
Chelated iron formulations diverge sharply in agronomic performance across pH gradients, driving distinct procurement patterns among specialty crop operators versus broadacre row-crop growers. Segmentation by chelating agent chemistry, application modality, and physical form determines pricing tiers, regulatory compliance burdens, and distribution channel selection.
Product Type:
Stability constants and pH buffering capacity separate commercial chelating agents into distinct performance tiers for alkaline soil correction.
- Iron EDDHA:The ortho-ortho isomer configuration delivers chelate stability across pH ranges exceeding 8.0, making it indispensable for Brazil's Cerrado soybean belt and Spain's calcareous citrus groves. California almond growers absorb 40-60% price premiums over EDTA alternatives to ensure season-long iron availability in high-bicarbonate irrigation water.
- Iron EDTA:Cost-effective chelation suits acidic to neutral soils where pH remains below 6.5, dominating Southeast Asian rice paddy applications and US Southeast cotton operations. Ferrous sulfate substitution pressure caps pricing power in these zones despite EDTA's superior tank-mix compatibility.
- Iron DTPA:Intermediate stability profile targets pH 6.5-7.5 band applications in Midwestern US corn-soy rotations where marginal calcareous layers demand more robust chelation than EDTA provides.
- Iron Gluconate:Organic-compliant status serves Italy's Po Valley organic vegetable producers and French biodynamic wine regions facing ECOCERT and Demeter certification requirements.
Mature deployment sits with Iron EDTA in established acidic soil markets. Newer deployment is concentrated in Iron EDDHA as alkaline soil expansion accelerates across major agricultural belts.
End Use Industry:
Output value density and chlorosis sensitivity dictate chelated iron specification intensity across crop categories.
- Crops:Soybean, corn, and wheat operations in Brazil and the US Midwest drive volume procurement of EDDHA and DTPA formulations through cooperative distribution channels. Yield penalties from iron deficiency in high-pH Cerrado soils sustain consistent demand pull regardless of commodity price cycles.
- Fruits:Citrus in Spain's Valencia region and stone fruit in California's Central Valley require precision foliar programs with drone-compatible concentrates. Sensor-guided variable-rate application is expanding most quickly in this segment.
- Vegetables:Greenhouse tomato and pepper operations in the Netherlands and Mexico's Sinaloa state favor fertigation-compatible liquid formulations with controlled-release characteristics.
- Turf:Golf course maintenance in Florida and the UAE deploys chelated iron for aesthetic color correction without growth flush, prioritizing spray tank compatibility with fungicide programs.
High-value permanent crops command specification premiums. Annual broadacre rotations remain price-sensitive to ferrous sulfate alternatives.
Application Method:
Infrastructure availability and labor cost structures determine modality selection across farming systems.
- Fertigation:Drip irrigation proliferation in California almond orchards and Israeli desert agriculture enables precise root-zone delivery that foliar spraying cannot match for efficiency. Polymer-coated formulations are climbing the fastest in this channel.
- Foliar Application:Drone-based platforms in Australia's Murray-Darling Basin and France's Champagne region enable site-specific intervention at 50-meter resolution, displacing calendar-based spraying.
- Soil Application:Granular EDDHA broadcast remains dominant in Brazilian soybean operations lacking drip infrastructure, with incorporation timing critical to prevent photodegradation.
- Seed Treatment:Emerging modality for early-stage iron availability in German sugar beet and Canadian canola, though compatibility with fungicide seed treatments requires formulation refinement.
Soil application retains volume leadership in broadacre contexts. Fertigation is gaining share fastest where irrigation infrastructure permits.
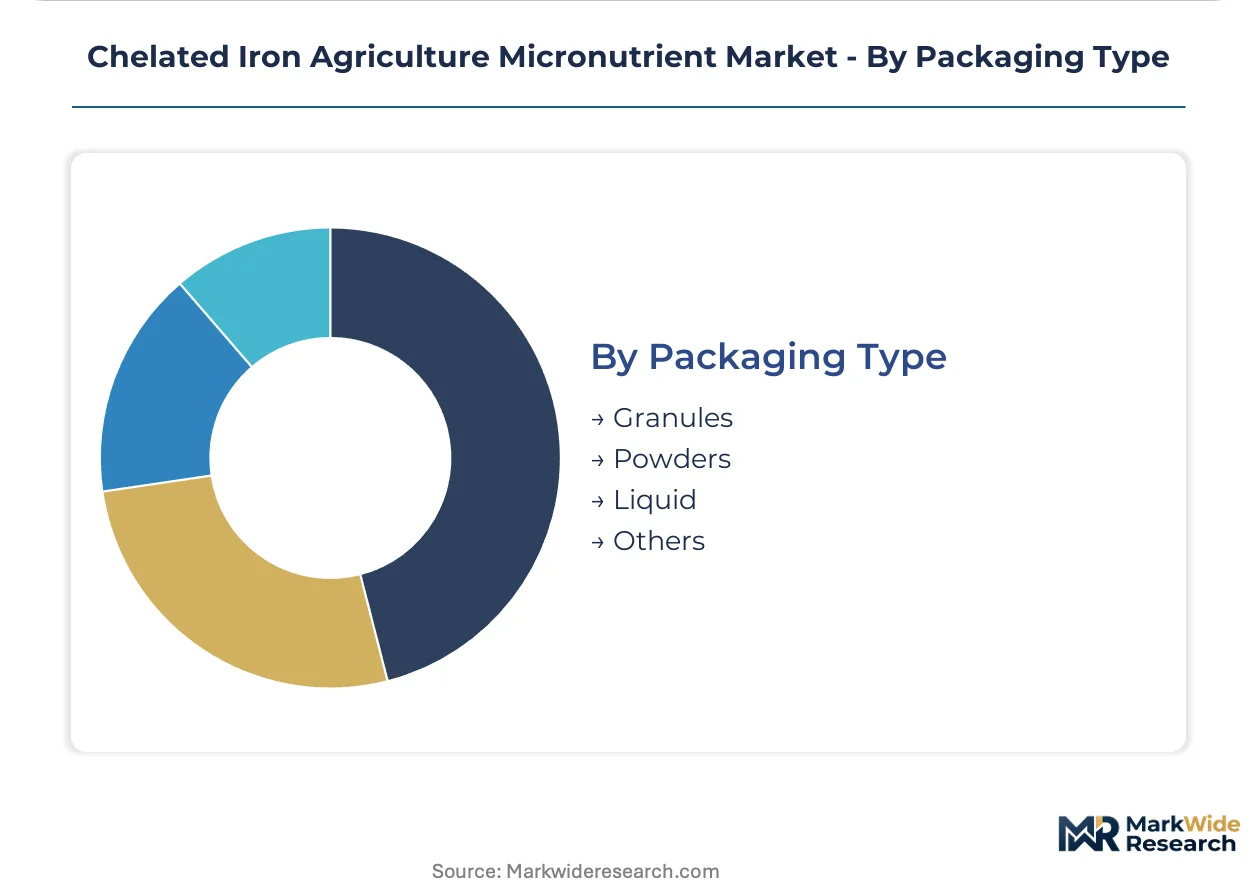
Packaging Type:
Physical form factors align with application equipment compatibility and storage stability requirements.
- Liquid:Dominates fertigation and drone-spray concentrate markets with superior tank-mix solubility, commanding premium positioning in California and Spain.
- Granules:Standard for soil broadcast applications in Brazil and the US Midwest, with dust-free handling properties preferred by cooperative blending facilities.
- Powders:Cost-minimized option for on-farm tank mixing in Southeast Asia and Eastern Europe, though caking susceptibility limits shelf life.
- Others:Water-soluble bags and micro-granule formats for precision horticulture in Japan and South Korea.
Liquid formats anchor premium channel development. Powdered alternatives defend share in price-sensitive developing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado Development Agency tax incentives concentrate EDDHA manufacturing investments near Rondonópolis. Alkaline soil expansion across agricultural belts is redirecting procurement flows toward pH-stable formulation hubs.
United States
California almond growers in the Central Valley drive premium liquid formulation demand for fertigation systems. EPA FIFRA residue limits govern chelated iron tolerances for export-bound produce. Precision agriculture clusters around Fresno and Bakersfield deploy sensor-guided variable-rate application at 50-meter resolution.
Brazil
Soybean operators in Mato Grosso's high-pH Cerrado soils sustain consistent EDDHA procurement regardless of commodity cycles. ANVISA import protocols delay market access for unregistered formulations, favoring early registrants. Domestic blending capacity concentrates in Rondonópolis and São Paulo state to serve the oilseed belt.
Germany
REACH authorization timelines stretching 18-24 months compress product pipeline velocity for novel chelating agents. ECHA expanded biodegradation data requirements force reformulation toward EDDHSA and HBED chemistries. Manufacturing expertise clusters in Ludwigshafen and Leverkusen around integrated ethylenediamine supply chains.
Spain
Valencia citrus groves and Almería greenhouse operations absorb premium formulation costs under EU Fertilizing Products Regulation CE conformity mandates. Heavy-metal threshold tightening accelerates withdrawal of legacy products from member state markets. Drone-compatible concentrate development concentrates in Murcia for export to French Champagne region.
China
Domestic EDDHA production capacity expansion targets export substitution for Brazil and Southeast Asia. GB standards alignment with CODEX residue limits enables processed food export compliance. Manufacturing gravity centers on Shandong Peninsula and Yangtze River Delta for precursor chemical integration.
Chelated Iron Agriculture Micronutrient Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry tiers. Three integrated chemical producers control EDDHA precursor availability, exposing mid-tier compounders to input volatility. Strategic archetypes span backward-integrated petrochemical majors, cooperative-linked fertilizer blenders, and controlled-release technology specialists. Dominant competitive moves include capacity expansion in Brazil's Cerrado corridor and strategic partnerships for ANVISA registration acceleration.
Among diversified chemical conglomerates, BASF SE anchors the premium formulation tier through captive ethylenediamine supply. Yara International exemplifies the cooperative-linked archetype with controlled-release expertise across Nordic and Latin American markets. Nutrien occupies a position bridging retail agronomy networks with direct-to-farm digital channels in North American row-crop segments.
| Leading Market Players |
|---|
| BASF SE |
| Yara International |
| Nutrien |
| ICL Specialty Fertilizers |
| Haifa Group |
| AkzoNobel |
| Bayer CropScience |
| The Mosaic Company |
| Nouryon Chemicals Holdings |
| Others |
Value Chain & Pricing Dynamics
California almond cooperatives and Brazil's Cerrado soybean operators anchor procurement volumes, forcing formulators toward contract-based long-term offtake structures that stabilize ethylenediamine input costs against spot volatility.
Pricing Analysis
Short lead-time premiums of 15-25% apply to EDDHA orders requiring sub-30-day delivery from Ludwigshafen or Rondonópolis production hubs. Three-tier pricing structure across premium, standard, and economy levels separates ortho-ortho EDDHA isomers from technical-grade EDTA and unchelated ferrous sulfate alternatives. Cost compression in the EDTA tier is intensifying because Southeast Asian rice growers substitute free iron salts at one-fifth the chelated cost. Broadacre corn-soy operators in the US Midwest exhibit highest price sensitivity, while California permanent crop growers absorb 40-60% premiums for pH-stable formulations.
Supply Chain Analysis
Brazil's ANVISA domestic-content mandates for fertilizer registration are reshaping sourcing patterns, forcing European formulators to establish local blending capacity in Mato Grosso and São Paulo state. Manufacturing gravity centers on Germany's Ludwigshafen chemical corridor, Brazil's Rondonópolis hub, and China's Shandong Peninsula for precursor integration. Supply chains draw from ethylenediamine, chloroacetic acid, and phenolic precursor feedstocks. Single-source vulnerability concentrates in EDDHA precursor availability controlled by three integrated chemical producers. Distribution runs through cooperative blending facilities in Brazil, retail agronomy networks in North America, and direct-to-farm digital platforms in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
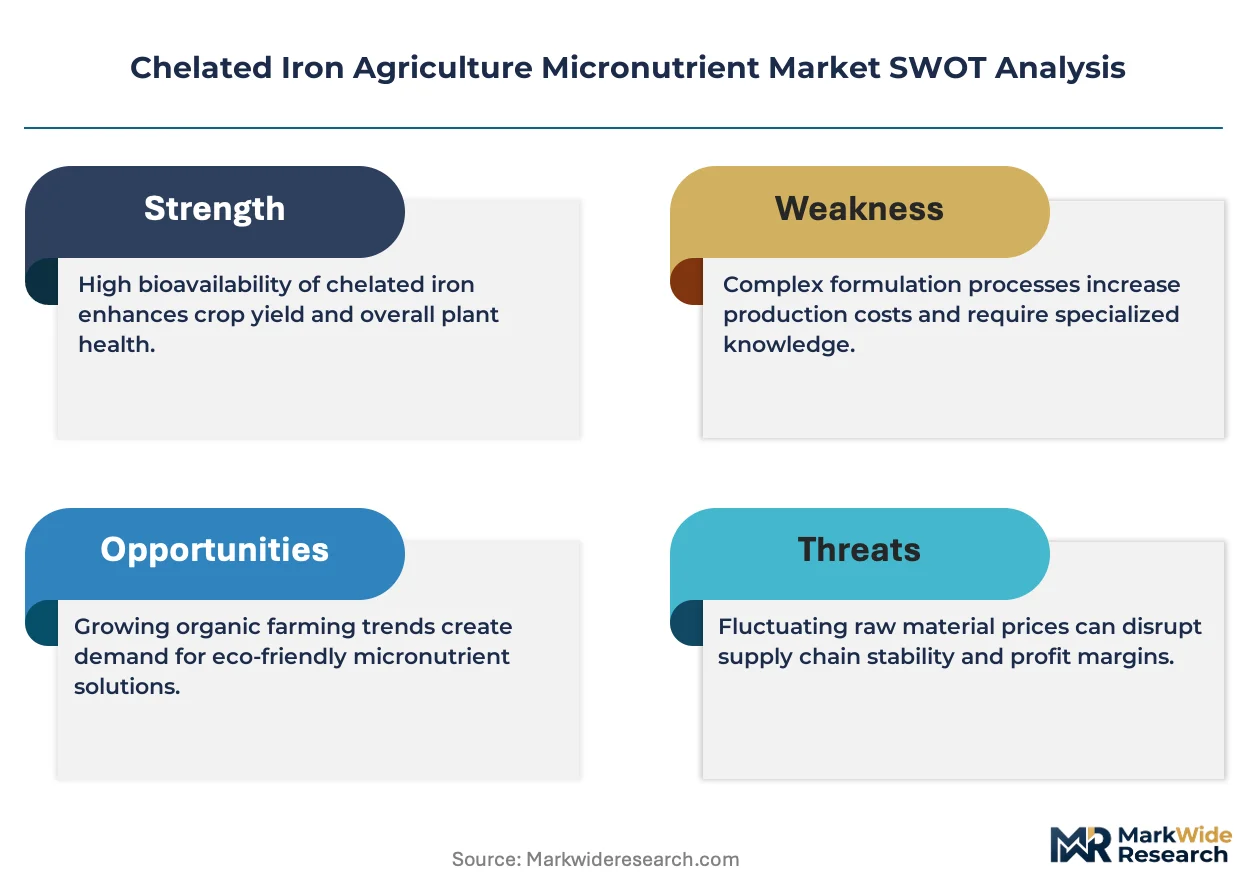
The EU Fertilizing Products Regulation's CE conformity mandates and heavy-metal threshold tightening erect a cost-of-compliance barrier that freezes mid-tier compounders without REACH dossier resources, entrenching diversified chemical conglomerates with captive toxicology capabilities.
For Market Incumbents: Hedge ethylenediamine supply exposure through long-term offtake agreements with Ludwigshafen and Leverkusen producers, insulating against allocation risk during plant turnarounds. Accelerate controlled-release formulation R&D to capture 40-60% application-labor savings in broadacre corn and wheat. Defend margin position against ferrous sulfate substitution pressure in acidic soil zones by bundling micronutrient programs with nitrogen stabilizers.
For New Entrants and Emerging Players: Organic vegetable producers in Italy's Po Valley and French biodynamic wine regions represent an underserved buyer archetype with ECOCERT and Demeter certification requirements that legacy formulators address inadequately. ANVISA registration arbitrage for novel EDDHSA formulations offers first-mover advantage ahead of domestic Brazilian capacity expansion. Pursue drone-compatible concentrate development for Australia's Murray-Darling Basin sensor-guided variable-rate platforms.
For Investors and Strategic Acquirers: The window for entry favors controlled-release technology specialists with polymer-coating expertise applicable to chelated iron-nitrogen stabilizer bundles. Long-term viability hinges on formulation chemistries satisfying REACH biodegradation endpoints and Brazil's evolving import protocols. Monitor ECHA authorization timeline compression for novel chelating agents as the inflection indicator for European manufacturing competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylenediamine | BASF SE's captive supply chain sustains cost advantages in EDDHA production against input volatility. |
| Controlled-Release Formulation Development | Yara International's polymer-coating expertise commands 40-60% labor savings in Nordic and Latin American markets. |
| ANVISA Registration Acceleration | Early registrants for EDDHSA formulations secure market access ahead of Brazilian domestic capacity expansion. |
| Drone-Compatible Concentrate Launch | Variable-rate aerial spraying platforms in Australia's Murray-Darling Basin displace calendar-based foliar applications. |
| Direct-to-Farm Digital Channel Expansion | Nutrien's retail agronomy network enables bundled micronutrient financing that legacy dealer structures cannot match. |
Study Parameters
Trade association filings, customs export records, and REACH registration databases formed the secondary backbone, cross-referenced against primary interviews with plant managers at European and Brazilian formulation facilities, procurement leads at California almond cooperatives, distribution channel partners in the US Midwest, and technical R&D directors specializing in chelate stability verification. Bottom-up volume modeling triangulated with top-down value estimates derived from input cost structures and pricing tier analysis.
Bottom-up segmentation modeling tracked chelating agent chemistry, application modality, and physical form dimensions across the projection horizon. CAGRs were derived from demand elasticity analysis against alkaline soil expansion trends and fertigation infrastructure deployment rates. Industry-specific forecast inputs included ANVISA registration pipeline velocity, ECHA authorization timeline compression, and drone-based foliar platform adoption curves in Australia's Murray-Darling Basin and France's Champagne region.
Revisions become necessary when REACH authorization timelines extend beyond modeled windows, ethylenediamine supply disruptions trigger allocation protocols, or ferrous sulfate substitution accelerates in acidic soil zones beyond baseline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market