
 Malaysia NPK Fertilizer Market | 2026-2036
Malaysia NPK Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia NPK Fertilizer Market Foresight
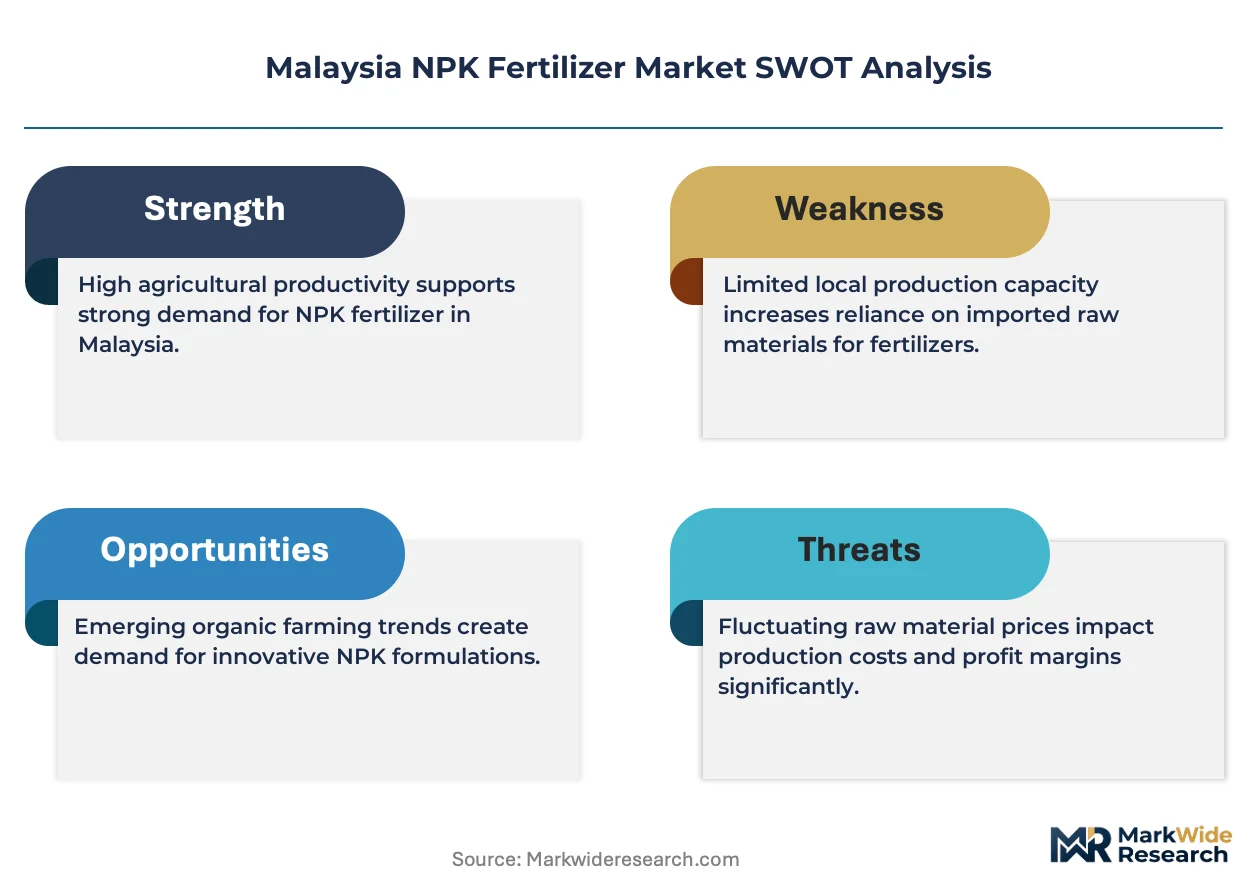
The gap between premium compound blends and commodity-grade NPK is consolidating as plantation groups demand site-specific formulations with micronutrient packages. EuroChem Group leverages its Russian phosphate access to sustain cost-competitive granular supply into Port Klang. Twin Arrow Fertilizer anchors its position through backward integration into local blending facilities serving Peninsular Malaysia's central belt. Yara International differentiates via controlled-release coatings that command price premiums from precision-minded horticultural exporters.
Malaysia NPK fertilizer denotes a multi-nutrient compound containing nitrogen, phosphorus, and potassium in ratios calibrated to soil chemistry and crop uptake curves, typically manufactured through ammoniation-granulation or bulk blending processes that achieve homogeneous particle distribution for mechanized spreading. The product type split shows granular formulations dominating volume through estate channel contracts, while water-soluble grades capture expanding margin pools from protected vegetable cultivation in Cameron Highlands. Application demand tilts heavily toward crops, with oil palm and rubber estates absorbing bulk tonnage, though horticulture segments generate superior per-kilogram returns through specialty micronutrient inclusion.
The Malaysian Department of Agriculture and the Department of Standards Malaysia (under MS standards framework) govern fertilizer registration, labeling, and import quality protocols, with BIS-equivalent conformity assessment shaping which foreign suppliers secure market access. The Department of Environment enforces effluent and ammonia emission thresholds that pressure blenders toward cleaner production technologies. Stakeholders must weigh subsidy reform timelines against estate consolidation trends to calibrate channel investments between direct estate sales and retail cooperative networks.
Market Dynamics
Malaysia's fertilizer subsidy rationalization program is compressing procurement timelines and forcing estate operators toward bulk compound formulations that qualify for tiered support payments.
Growth Catalysts
- MS Standards Framework:The Department of Standards Malaysia mandates micronutrient disclosure on all NPK labels, pushing blenders toward higher-margin specialty formulations that command premium positioning.
- Oil Palm Transition:Large plantation groups are abandoning straight fertilizer programs for calibrated NPK blends that reduce application labor costs and improve nutrient use efficiency.
- Cameron Highlands Horticulture:Protected vegetable cultivation clusters are demanding water-soluble NPK grades with chelated trace elements, creating a parallel premium channel distinct from estate bulk contracts.
Market Restraints
- Phosphate Import Concentration:Malaysian blenders depend heavily on Russian and Moroccan phosphate rock shipments, exposing margin structures to freight volatility and currency fluctuation.
- Subsidy Eligibility Complexity:The Department of Agriculture's evolving qualification criteria create administrative friction that delays product registration and locks out smaller compounders.
- Controlled-Release Substitution:Polymer-coated urea and stabilized nitrogen products from specialty chemical suppliers are capturing share in high-value vegetable segments.
Strategic Opportunities
- Johor Precision Agriculture Corridors:Estate consolidation in southern Peninsular Malaysia creates demand for site-specific NPK prescriptions tied to soil grid sampling and variable-rate application.
- Department of Environment Compliance:Ammonia emission thresholds are accelerating capital deployment toward closed-loop granulation systems that qualify for cleaner production incentives.
- Retail Cooperative Digitalization:Federated farmer cooperatives are adopting e-procurement platforms that bypass traditional distributor markups and enable direct blender relationships.
Industry Challenges
- Agronomic Formulation Expertise:Blending facilities struggle to recruit soil chemists capable of calibrating NPK ratios against Malaysian Agricultural Research and Development Institute yield response data.
- Legacy Equipment Retrofit Costs:Converting bulk blending plants to ammoniation-granulation lines requires capital outlays that strain mid-tier compounders already squeezed by input cost volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia NPK Fertilizer Market |
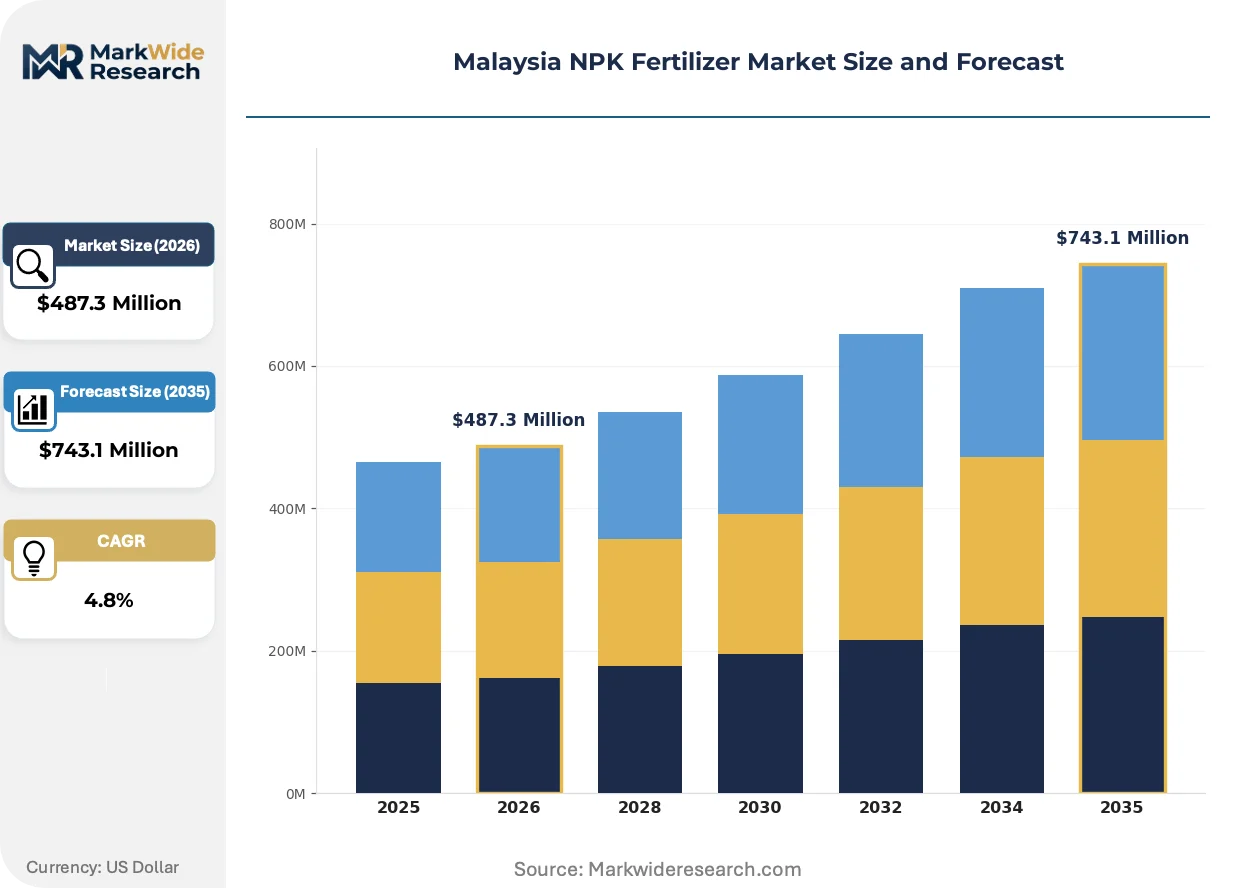
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Water-Soluble, Slow-Release Application: Crops, Horticulture, Turf, Landscaping End User: Agricultural Producers, Farmers, Cooperatives, Retailers Distribution Channel: Direct Sales, Wholesalers, Online, Garden Centers |
| Companies Covered | Nutrien, EuroChem Group, Twin Arrow Fertilizer, ICL Group, OCP Group, AGKaizen, The Mosaic Company, Cropmate Fertilizers, Yara International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia NPK Fertilizer Market Shifts & Advancements
Digital soil mapping and variable-rate application hardware are transforming how Malaysian estates specify and procure compound fertilizers.
Controlled-release polymer coatings are electrifying the premium NPK segment by enabling single-application programs that reduce labor mobilization costs. Large plantation operators in Pahang are piloting coated formulations on ten-thousand-hectare blocks, compressing the traditional three-pass application cycle into one timed release that spans the full growing season.
The Department of Environment's ammonia emission thresholds are forcing granulation plant retrofits across Peninsular Malaysia. Blenders must install scrubber systems and closed-loop cooling infrastructure to maintain operating licenses, with compliance timelines favoring capital-rich integrated suppliers over independent compounders.
Estate procurement offices are consolidating annual NPK contracts into multi-year framework agreements with indexed pricing clauses. Direct blender relationships are displacing traditional distributor networks in Johor and Pahang, where plantation groups leverage volume concentration to secure formulation customization and dedicated production slots.
Malaysia NPK Fertilizer Market Segmentation
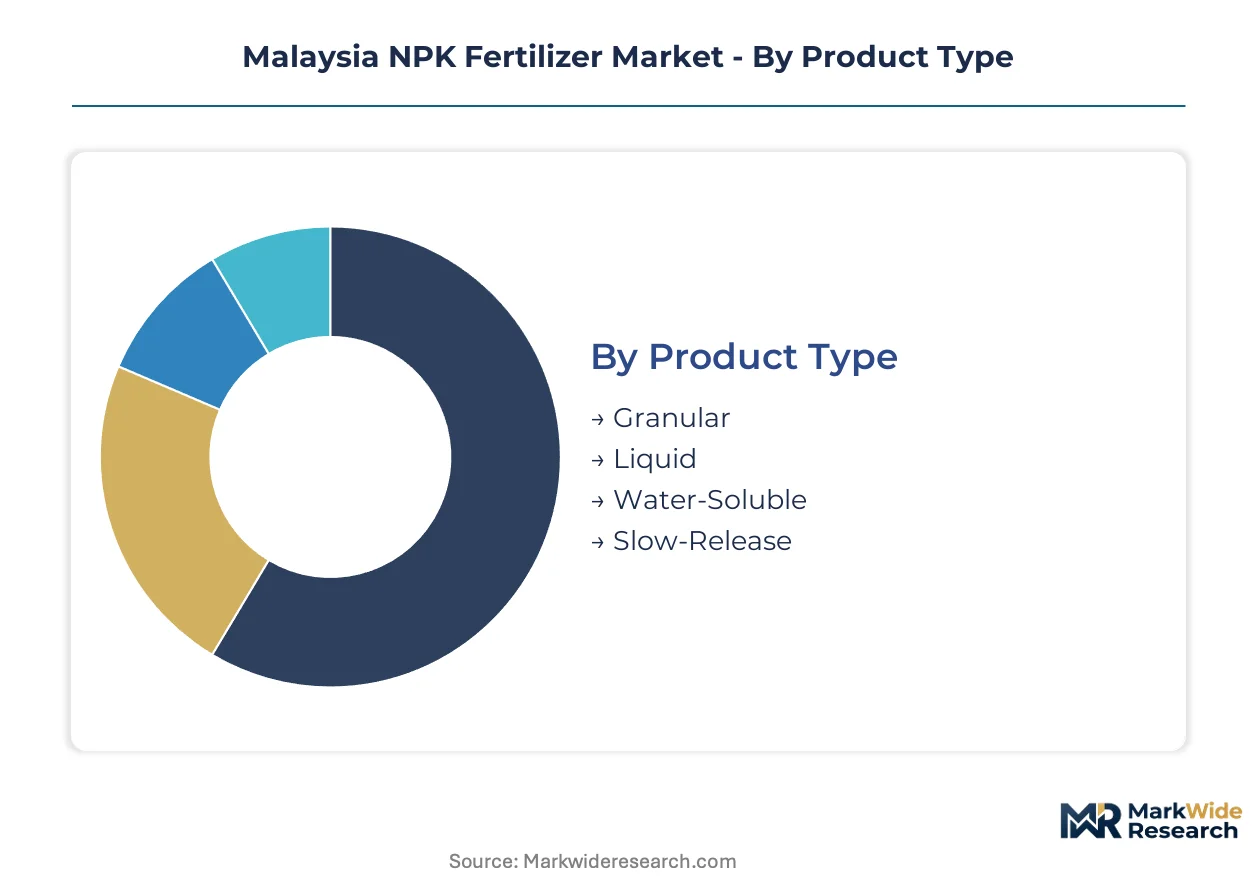
Malaysia NPK fertilizer segmentation reflects divergent regulatory burdens across product categories. Department of Agriculture registration protocols vary sharply between bulk estate formulations and specialty horticultural grades.
Product Type:
MS standards compliance intensity escalates from commodity bulk blends to coated specialty grades, with ammoniation-granulation plants facing stricter Department of Environment ammonia thresholds than simple bulk blending facilities.
- Granular:Homogeneous particle formulations manufactured through ammoniation-granulation achieve uniform nutrient distribution for mechanized estate spreading. Sime Darby and FGV Holdings anchor procurement volumes in Johor and Pahang through multi-year supply contracts indexed to phosphate import costs.
- Water-Soluble:Fully soluble crystalline grades dissolve completely for drip irrigation and foliar feeding systems. Cameron Highlands vegetable exporters drive specification demands for chelated micronutrient inclusion that satisfies EU residue protocols.
- Liquid:Suspension concentrates enable precision fertigation in controlled-environment agriculture. Fertilizer blending facilities in Selangor and Perak distribute tanker loads to estate mixing stations.
- Slow-Release:Polymer-coated or sulfur-coated formulations extend nutrient availability across single growing seasons. Premium pricing depends on Malaysian Agricultural Research and Development Institute yield validation trials.
Leading the category by volume: Granular. Growing fastest: Water-Soluble.
Application:
End-use segmentation tracks the subsidy eligibility boundaries set by the Department of Agriculture's rationalization program, with estate-scale oil palm and rubber operations accessing tiered support unavailable to ornamental or recreational users.
- Crops:Oil palm estates absorb bulk NPK tonnage through calibrated blends matched to frond analysis results. Felda settlers and independent smallholders in Pahang access subsidized compound formulations through cooperative procurement pools.
- Horticulture:Protected vegetable cultivation in Cameron Highlands and Genting Highlands demands water-soluble grades with precise NPK ratios and complete trace element packages. Export-oriented chili and tomato growers pay premiums for controlled-release coatings that reduce labor mobilization.
- Turf:Golf course maintenance and sports field management in Kuala Lumpur and Selangor specify homogeneous granular spreads for visual uniformity. Seasonal application windows concentrate procurement into pre-monsoon periods.
- Landscaping:Municipal parks and commercial property maintenance in Penang and Johor Bahru source blended formulations through garden center retail channels without subsidy access.
Dominant by tonnage: Crops. Expanding most quickly: Horticulture.
End User:
Customer scale determines procurement channel access, with estate consolidation concentrating volume into direct blender relationships while fragmented smallholder bases persist through cooperative intermediaries.
- Agricultural Producers:Integrated plantation groups operate dedicated procurement offices that negotiate annual framework agreements. IOI Corporation and Kuala Lumpur Kepong specify site-specific formulations tied to soil grid sampling programs.
- Farmers:Independent smallholders below estate scale access subsidized NPK through registered retail cooperatives. Administrative friction from evolving Department of Agriculture eligibility criteria delays product registration for smaller compounders.
- Cooperatives:Federated farmer organizations aggregate demand to bypass traditional distributor markups. Digital procurement platforms enable direct blender relationships for members in Peninsular Malaysia's central belt.
- Retailers:Garden centers and agricultural supply shops serve unsubsidized landscaping and hobby farming segments. Inventory carrying costs pressure working capital during phosphate price volatility.
Volume concentration: Agricultural Producers. Fastest channel shift: Cooperatives.
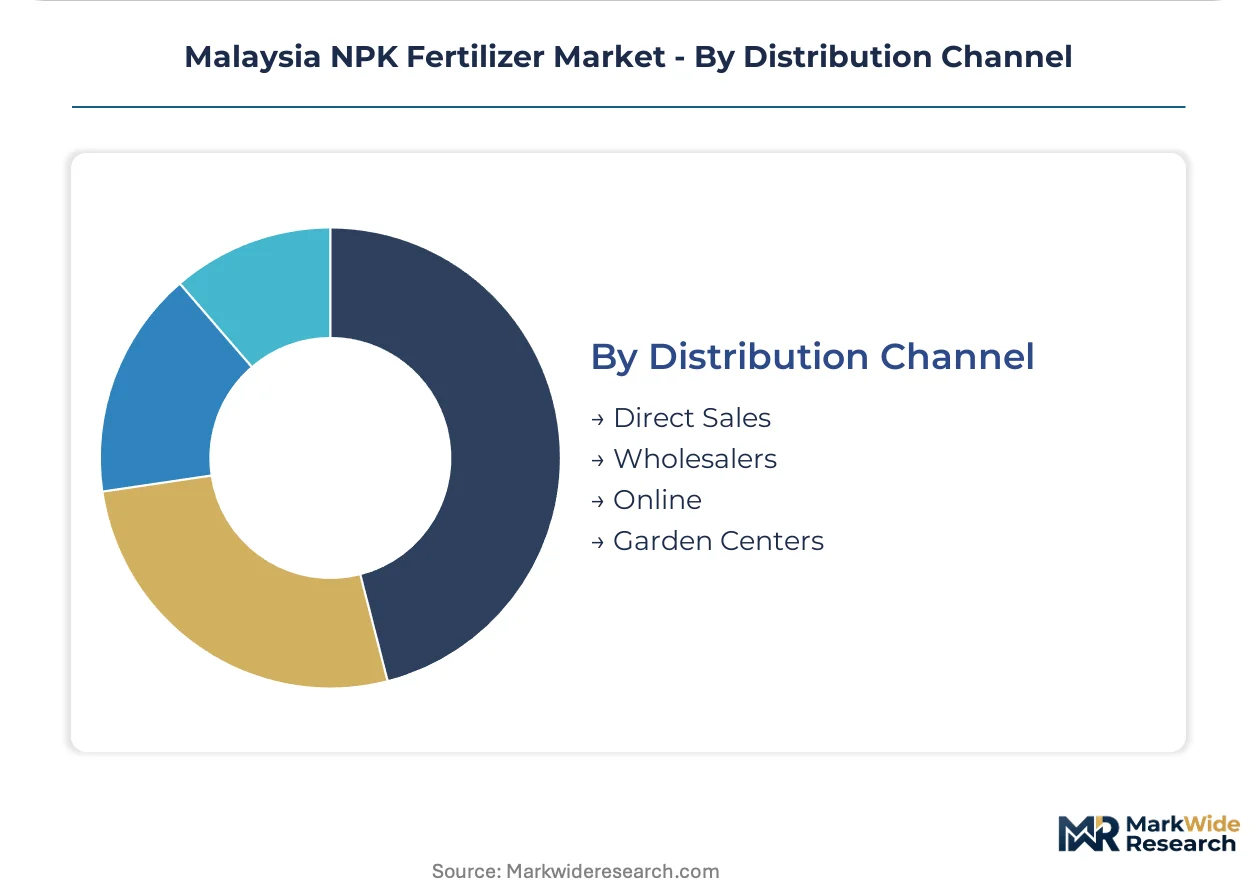
Distribution Channel:
Channel structure mirrors estate consolidation geography, with direct sales penetrating Johor and Pahang while wholesaler networks persist in fragmented northern and eastern peninsula markets.
- Direct Sales:Blender-to-estate relationships eliminate distributor margins for volume commitments above threshold tonnages. Twin Arrow Fertilizer and Yara International operate dedicated account teams for plantation group procurement offices.
- Wholesalers:Regional distributors maintain buffer stocks for smallholder cooperative delivery in Kedah, Kelantan, and Terengganu. Credit terms and technical advisory services differentiate competing intermediaries.
- Online:E-procurement platforms enable cooperative aggregation and price transparency. Mobile ordering applications penetrate younger farmer demographics in Selangor and Perak.
- Garden Centers:Retail outlets serve urban horticulture and landscaping demand in Kuala Lumpur, Penang, and Johor Bahru metropolitan areas. Product knowledge and micronutrient advisory support premium positioning.
Channel leader by volume: Direct Sales. Steepest expansion trajectory: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johor Bahru and the southern plantation belt concentrate Malaysia's NPK procurement gravity, with estate consolidation driving formulation standardization across Peninsular Malaysia's central agricultural corridor.
Johor
Sime Darby and IOI Corporation estates absorb granular NPK through multi-year framework agreements indexed to phosphate import costs. The Department of Agriculture's subsidy rationalization program compresses procurement timelines for Felda settlers in the Muar and Segamat districts. Precision agriculture corridors in Kota Tinggi and Kulai are piloting site-specific NPK prescriptions tied to soil grid sampling.
Pahang
FGV Holdings and Kuala Lumpur Kepong anchor bulk compound demand across the east coast plantation belt. The Department of Environment enforces ammonia emission thresholds that pressure granulation plant retrofits in Kuantan industrial zones. Estate operators in Jerantut and Raub are consolidating annual contracts into multi-year agreements with indexed pricing clauses.
Selangor
Blending facilities in Shah Alam and Port Klang distribute liquid suspension concentrates to estate mixing stations throughout the Klang Valley. The Department of Standards Malaysia mandates micronutrient disclosure on all NPK labels, pushing local compounders toward specialty formulations. Digital procurement platforms are penetrating cooperative networks in Hulu Selangor and Kuala Selangor.
Perak
Independent smallholders in the central belt access subsidized NPK through registered retail cooperatives in Ipoh and Taiping. Administrative friction from evolving Department of Agriculture eligibility criteria delays product registration for smaller compounders. Mobile ordering applications are gaining traction among younger farmer demographics in Batang Padang and Kampar.
Cameron Highlands
Protected vegetable cultivation clusters demand water-soluble NPK grades with chelated trace elements for export-oriented chili and tomato growers. Malaysian Agricultural Research and Development Institute yield validation trials determine premium pricing for controlled-release coatings. Horticultural exporters in Tanah Rata and Brinchang pay premiums for formulations satisfying EU residue protocols.
Malaysia NPK Fertilizer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and micronutrient inclusion depth. The vendor base clusters around three strategic archetypes: integrated plantation suppliers with captive blending capacity, international traders leveraging phosphate rock access, and specialty coating specialists commanding precision-agriculture premiums. Competitive moves center on backward integration into local granulation assets and multi-year framework agreements that lock in estate volume concentration.
Within the integrated supplier tier, Twin Arrow Fertilizer exemplifies backward integration through Peninsular Malaysia blending facilities serving the central estate belt. EuroChem Group anchors the phosphate-access archetype, sustaining cost-competitive granular supply into Port Klang through Russian rock sourcing. Yara International occupies the specialty-coating position, differentiating via controlled-release formulations that command price premiums from precision-minded horticultural exporters in Cameron Highlands.
| Leading Market Players |
|---|
| Nutrien |
| EuroChem Group |
| Twin Arrow Fertilizer |
| ICL Group |
| OCP Group |
| AGKaizen |
| The Mosaic Company |
| Cropmate Fertilizers |
| Yara International |
| Others |
Supply & Pricing Matrix
Phosphate rock import costs from Russian and Moroccan suppliers cascade through Malaysian NPK value chains, stratifying pricing power between integrated blenders with captive mineral access and independent compounders exposed to currency-adjusted spot purchasing. The Department of Agriculture's subsidy rationalization program compresses procurement timelines and forces estate operators toward bulk compound formulations that qualify for tiered support payments, tightening margins for distributors caught between fixed subsidy ceilings and volatile input costs.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for controlled-release coatings validated by Malaysian Agricultural Research and Development Institute trials. Three-tier pricing structure across premium, standard, and economy levels separates polymer-coated specialty grades from ammoniation-granulation bulk blends and simple bulk-blended commodity formulations. Cost compression in the standard tier is intensifying because phosphate freight volatility and ringgit-dollar exchange movements erode blender margins. Independent smallholders accessing subsidized NPK through cooperative networks exhibit highest price sensitivity, while integrated plantation groups with direct blender relationships prioritize formulation customization over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Russian and Moroccan phosphate rock suppliers that feed Malaysian granulation plants through Port Klang bulk terminals. Raw material dependencies center on ammonia, sulfur, and potash imports drawn from Middle Eastern and Southeast Asian production hubs. Tariff exposure on phosphate shipments creates margin volatility for blenders without long-term offtake agreements. Distribution runs through direct blender-to-estate relationships in Johor and Pahang, with wholesaler networks persisting for smallholder cooperative delivery in northern peninsula states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's NPK fertilizer market is consolidating around capital-rich integrated suppliers as Department of Environment ammonia emission compliance costs force independent compounders toward exit or acquisition. Estate consolidation and subsidy eligibility complexity are accelerating this structural pressure.
For Market Incumbents: Anticipate controlled-release substitution threats from polymer-coated urea specialists by deepening backward integration into local granulation assets with scrubber-equipped closed-loop systems. Secure multi-year framework agreements with indexed pricing clauses against FGV Holdings and Sime Darby procurement offices to lock in volume concentration before estate digitalization platforms enable cooperative bypass of traditional distributor networks. For New Entrants and Emerging Players: The Department of Standards Malaysia's micronutrient disclosure mandate opens a window for specialty formulation plays targeting Cameron Highlands horticultural exporters with chelated trace element packages satisfying EU residue protocols. White-space opportunities concentrate in water-soluble grades for protected vegetable cultivation and liquid suspension concentrates for precision fertigation in Selangor controlled-environment agriculture. A direct-to-cooperative digital procurement platform bypassing traditional distributor markups offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Estate procurement offices consolidating annual contracts into multi-year framework agreements is the leading indicator that volume concentration will favor integrated suppliers with captive blending capacity over fragmented compounders. Long-term viability over the projection horizon rests on acquiring mid-tier blenders with ammoniation-granulation assets in Peninsular Malaysia's central belt, particularly those with existing Department of Agriculture registration and Port Klang logistics access. Monitor Department of Environment compliance timelines as the critical inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Blending Facilities | Twin Arrow Fertilizer's captive production assets eliminate distributor markups and secure formulation control for estate direct sales. |
| Long-term Supply Agreement with Phosphate Rock Suppliers | EuroChem Group's Russian mineral access insulates margin structures against freight volatility and currency fluctuation exposure. |
| Green Manufacturing Transition to Closed-loop Granulation | Scrubber-equipped ammoniation plants qualify for Department of Environment cleaner production incentives while maintaining operating licenses. |
| Joint Venture with Estate Digitalization Platforms | Cooperative e-procurement partnerships enable direct blender relationships that bypass traditional distributor networks in Selangor and Perak. |
| Capacity Expansion in Johor Precision Agriculture Corridors | Site-specific NPK prescription capabilities tied to soil grid sampling programs capture estate consolidation volume in southern Peninsular Malaysia. |
Research Methodology
Trade statistics from the Malaysian Department of Agriculture, customs import records for phosphate rock and ammonia shipments, and Department of Standards Malaysia registration databases formed the secondary backbone for this analysis. Primary fieldwork encompassed interviews with blending facility plant managers, procurement leads at FGV Holdings and IOI Corporation, distribution channel partners in the central belt cooperative network, and technical R&D directors at controlled-release coating specialists. Bottom-up volume estimates from estate-level consumption patterns were triangulated against top-down trade flow analysis to calibrate market sizing.
Historical trendline analysis tracked NPK procurement volumes across product type, application, and end user segments throughout the forecast period. Segmentation dimensions modeled include formulation grade tier, crop-specific application, customer scale archetype, and regional production hub concentration. CAGRs were derived from regression analysis against plantation hectarage expansion, subsidy program evolution, and controlled-release adoption curves. Industry-specific forecast inputs incorporated Malaysian Agricultural Research and Development Institute yield response data and Department of Environment compliance timeline assumptions.
Caveats apply where phosphate price volatility, ringgit exchange rate movements, or abrupt subsidy program revisions could materially shift the outlook. Forecasts reflect documented assumptions about estate consolidation velocity and controlled-release technology adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
India Urea Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Nano Fertilizer Market