
 Substation Battery Market | 2026-2036
Substation Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Substation Battery Market Analysis
China's battery manufacturing corridor is reconfiguring competitive dynamics for substation energy storage. CATL leverages its integrated cathode-to-pack production to dominate lithium-ion systems for grid applications. GS Yuasa Corp. anchors the Asia-Pacific supply base with deep specialization in valve-regulated lead-acid designs for utility backup. EnerSys competes through its North American service network and captive recycling infrastructure.
Substation batteries are electrochemical storage systems engineered for stationary installation at electrical substations, typically delivering DC power at 48V to 240V with cycle life ratings exceeding 1,500 deep-discharge cycles for grid stabilization and protective relay operation. Their primary commercial purpose is ensuring uninterrupted protection, control, and communication during grid disturbances or blackstart sequences. Lithium-ion technology leads in new capacity additions due to superior energy density and declining cell costs, while lead-acid chemistry retains share in retrofit installations where capital constraints govern procurement. Flow batteries occupy a nascent but technically distinct position for long-duration frequency regulation applications requiring 4–8 hour discharge profiles.
The U.S. EPA and NHTSA indirectly shape demand through emissions rules affecting backup generator alternatives, while India's CEA mandates battery-backed protection standards for substations above 33kV. The EU F-Gas Regulation and REACH compliance frameworks constrain electrolyte chemistry choices for European deployments. Stakeholders must monitor how evolving grid codes in multiple jurisdictions redefine depth-of-discharge requirements and warranty terms for utility procurement tenders.
Market Dynamics
Grid modernization timelines are compressing procurement cycles for substation batteries, with utilities now requiring 48-hour delivery windows for emergency replacements and 15-year performance guarantees that reshape vendor qualification criteria.
Growth Catalysts
- India's CEA Mandates:Battery-backed protection standards for substations above 33kV are creating mandatory replacement cycles across state electricity boards.
- Flow Battery Advancement:Vanadium redox systems are capturing long-duration frequency regulation contracts previously served by pumped hydro.
- Rural Electrification:India's SAUBHAGYA scheme is driving distributed substation deployments requiring localized DC backup systems.
Market Restraints
- Lithium Carbonate Volatility:Cathode material costs swing 40-60% annually, compressing margins for system integrators locked into fixed-price utility contracts.
- China Supply Concentration:Over 70% of processed lithium and refined cobalt originates from Chinese chemical processing corridors, creating single-source vulnerability.
- EU F-Gas Constraints:Fluorinated electrolyte restrictions limit thermal management options for European deployments, forcing costlier alternatives.
Strategic Opportunities
- Second-Life EV Packs:Automotive battery retirement streams offer 60-70% residual capacity for substation duty cycles at 30% of new lithium-ion cost.
- US IRA Manufacturing Credits:Domestic cell production incentives are enabling captive supply chains for North American utility procurements.
- Hybrid AC-DC Architectures:Solid-state transformer integration creates demand for batteries serving dual power quality and backup functions.
Industry Challenges
- Battery Management System Expertise:Utilities lack in-house firmware engineering capacity to optimize multi-chemistry fleet performance.
- IEC 62619 Certification Timelines:Safety testing for lithium-ion substation applications extends 14-18 months, delaying project commissioning.
- Legacy SCADA Integration:1990s-era control systems require protocol converters that introduce latency in protective relay coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substation Battery Market |
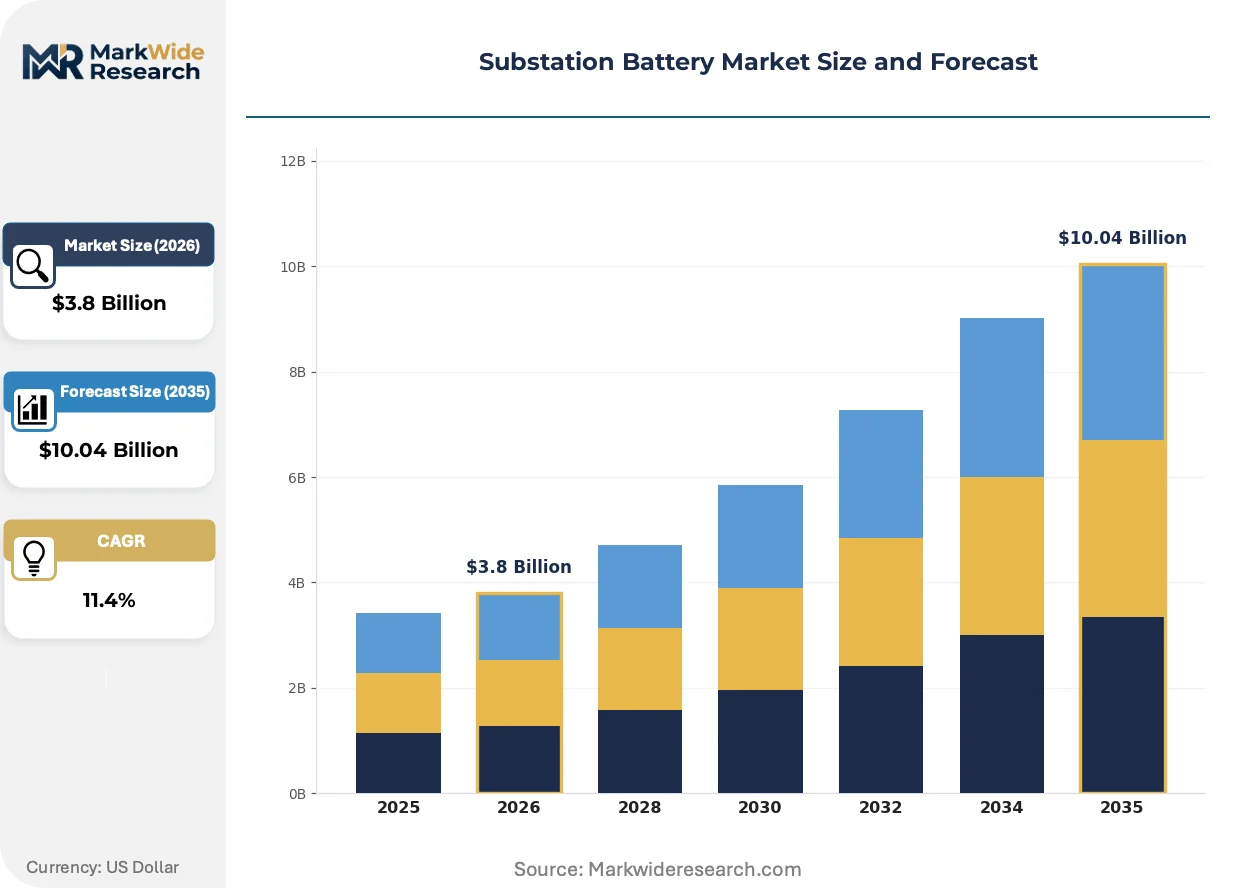
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lead Acid, Lithium Ion, Nickel Cadmium, Flow Batteries End User: Utilities, Renewable Energy Providers, Industrial, Data Centers Application: Energy Storage, Backup Power, Frequency Regulation, Grid Stabilization Installation Type: On-grid, Off-grid, Hybrid, Stationary |
| Companies Covered | Contemporary Amperex Technology Co Ltd. (CATL), LG Energy Solution Ltd., GS Yuasa Corp., EnerSys, Exide Technologies, Saft, East Penn Manufacturing, Amara Raja Batteries, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substation Battery Market Emerging Trajectories
Digital twin architectures are redefining how asset managers predict battery degradation, shifting maintenance from calendar-based schedules to condition-driven interventions that extend operational life.
Solid-state electrolyte formulations are virtualizing thermal management requirements for lithium-ion substation installations. Japanese utilities are piloting sulfide-based cells for 220kV switching stations. This chemistry is virtualizing the need for active cooling infrastructure, compressing site preparation costs by eliminating HVAC redundancy.
REACH chemical registration deadlines are forcing electrolyte reformulation across European supply chains. Manufacturers must substitute boron-based additives with phosphate alternatives by 2025. German TSOs are absorbing 8-12% cost premiums to maintain EU market access, diverting procurement volumes from Asian competitors lacking SVHC compliance documentation.
Performance-based service agreements are displacing capital purchase models for grid-scale battery fleets. Nordic utilities now contract availability guarantees rather than owning cell assets. This shift concentrates risk with OEMs and is most visible in Denmark, where Energinet's tender structure mandates 98.5% uptime penalties paid in liquidated damages.
Substation Battery Market Segmentation
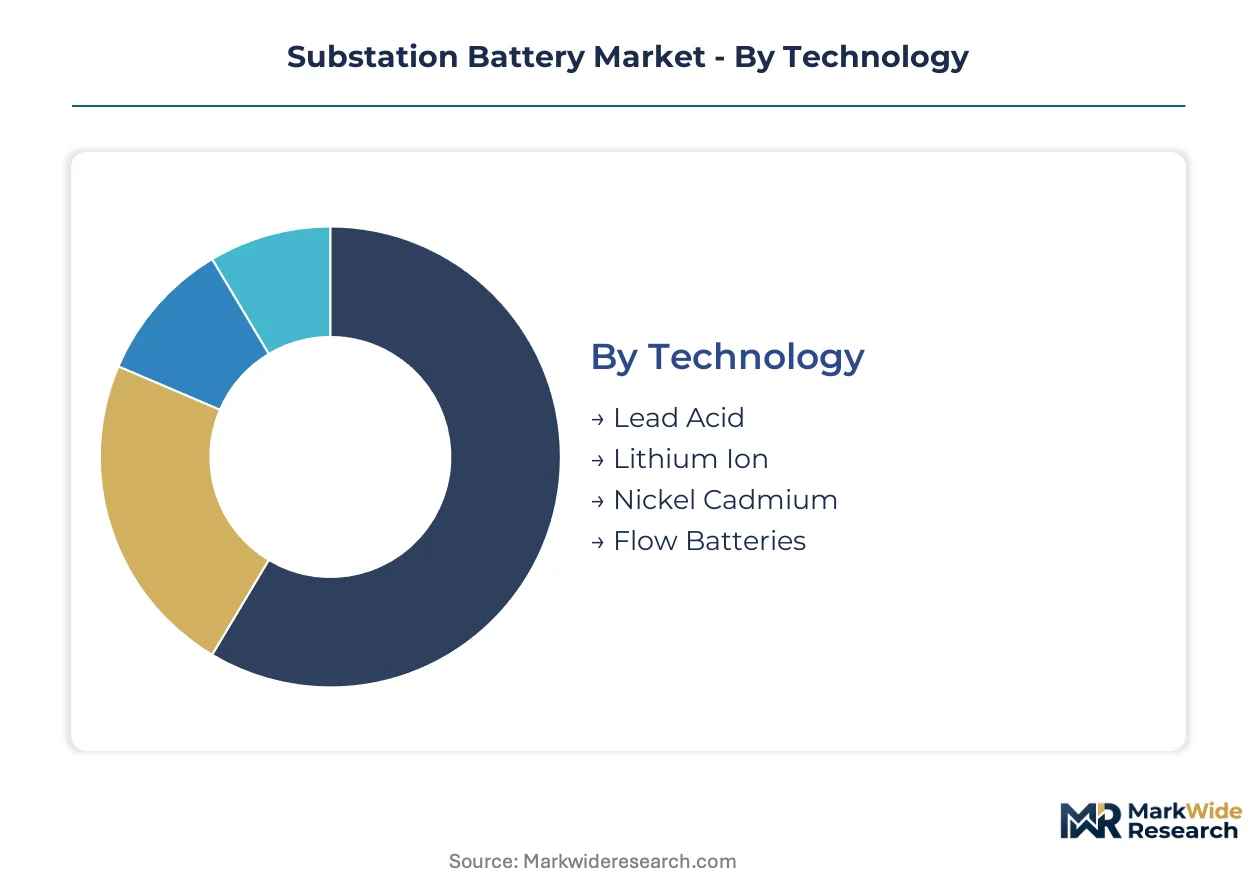
Substation battery procurement patterns diverge sharply across chemistry, end-use, and deployment architecture. Understanding these fault lines reveals where capital is concentrating and which technical specifications dominate competitive tenders.
Technology:
Cost tier positions each chemistry for distinct procurement scenarios across utility fleets.
- Lead Acid:Valve-regulated designs with 5-15 year service life dominate retrofit installations where capital constraints govern procurement. India's state electricity boards specify lead-acid for rural substations below 66kV under CEA mandates.
- Lithium Ion:NMC and LFP chemistries deliver 150-200 Wh/kg energy density with cycle life exceeding 3,000 cycles. U.S. utilities favor lithium-ion for urban substations where space constraints and 15-year performance guarantees drive selection.
- Nickel Cadmium:Sintered plate construction tolerates extreme temperature swings from -40°C to 50°C. Arctic and desert substations specify nickel-cadmium where thermal cycling degrades other chemistries prematurely.
- Flow Batteries:Vanadium redox systems decouple power and energy ratings, enabling 4-8 hour discharge profiles. Long-duration frequency regulation contracts in Denmark and Germany are rotating toward flow battery deployments.
Lead Acid holds installed capacity across legacy fleets. Lithium Ion is rotating up the share rankings in new capacity additions.
End User:
Application maturity varies by customer type and their tolerance for operational risk.
- Utilities:Transmission and distribution operators mandate IEC 62619 certification and 98.5% availability guarantees. FERC Order 2222 compliance requirements are reshaping utility procurement specifications for distributed energy resources.
- Renewable Energy Providers:Solar and wind farm developers require blackstart capability and ramp-rate control for grid code compliance. India's renewable purchase obligations are accelerating substation battery deployments at solar parks in Rajasthan and Gujarat.
- Industrial:Petrochemical and semiconductor fabs demand sub-4 millisecond transfer times for critical process loads. Japanese automotive manufacturers specify nickel-cadmium for foundry substations where voltage sag tolerance is paramount.
- Data Centers:Hyperscale operators contract 15-minute ride-through capacity to bridge diesel generator startup. Northern Virginia's data center corridor is concentrating lithium-ion procurement for 48V DC bus architectures.
Utilities anchor procurement volume. Data Centers are expanding most quickly as cloud infrastructure scales.
Application:
Margin concentration tracks the technical complexity of each use case and its integration with grid control systems.
- Energy Storage:Bulk shifting of renewable generation requires 2-4 hour discharge duration and bi-directional inverters. California IOUs specify energy storage for substations serving high solar penetration zones.
- Backup Power:Protective relay and SCADA continuity during grid disturbances demands instantaneous response. European TSOs mandate backup power for all transmission substations above 110kV under network codes.
- Frequency Regulation:Fast frequency response contracts require 1-second ramp rates and sustained 15-minute output. PJM's RegD market has standardized lithium-ion specifications for frequency regulation assets.
- Grid Stabilization:Voltage support and reactive power injection integrate batteries with synchronous condensers. Australian network operators deploy grid stabilization batteries at weak grid connection points for mining loads.
Backup Power commands the largest installed base. Frequency Regulation is climbing the fastest as ancillary service markets deepen.
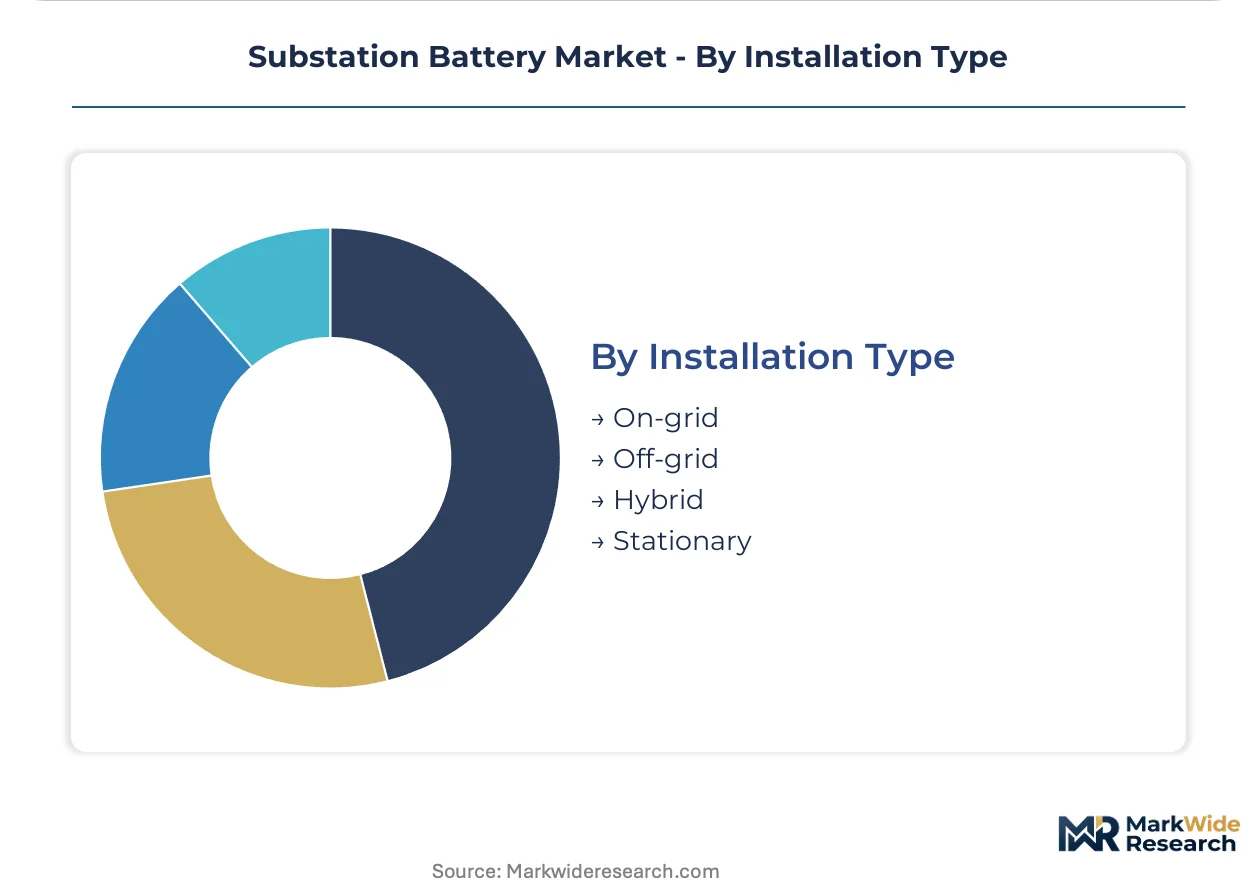
Installation Type:
Supply concentration and site preparation costs diverge across deployment architectures.
- On-grid:Grid-tied installations leverage existing protection infrastructure and metering systems. German distribution system operators favor on-grid configurations for urban substation retrofits where land availability is constrained.
- Off-grid:Islanded operation requires integrated inverters and autonomous control systems. Remote mining operations in Western Australia specify off-grid substation batteries for haul truck electrification corridors.
- Hybrid:Dual-mode systems switch between grid-tied and islanded operation based on disturbance detection. Microgrid developers in Texas deploy hybrid architectures for critical facility resilience following winter storm Uri.
- Stationary:Fixed installations with passive thermal management dominate utility-scale deployments. Chinese state grid procurement standards specify stationary enclosures with IP54 ingress protection for coastal substations.
Stationary configurations hold the majority of deployed capacity. Hybrid installations are gaining share fastest as resilience requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 compliance requirements and IRA manufacturing credits are reshaping procurement patterns across North American utilities. State-level renewable mandates and transmission investment programs are driving regional deployment variations.
United States
Texas utilities are deploying hybrid substation batteries for critical facility resilience following winter storm Uri. FERC's Order 2222 compliance deadlines are accelerating distributed energy resource procurements across ERCOT and PJM territories. Northern Virginia's data center corridor is concentrating lithium-ion procurement for 48V DC bus architectures serving cloud infrastructure.
China
State Grid procurement standards specify stationary enclosures with IP54 ingress protection for coastal substations. MIIT dual carbon goals are mandating energy storage integration at 220kV switching stations. The Yangtze River Delta battery manufacturing corridor supplies cathode-to-pack production for domestic grid-scale deployments.
Germany
Distribution system operators favor on-grid configurations for urban substation retrofits where land availability is constrained. EU F-Gas Regulation and REACH compliance frameworks are forcing electrolyte reformulation with 8-12% cost premiums absorbed by transmission system operators. The country's national energy regulator mandates backup power standards for transmission substations above 110kV.
India
SAUBHAGYA rural electrification is driving distributed substation deployments requiring localized DC backup systems. CEA mandates battery-backed protection standards for substations above 33kV, creating mandatory replacement cycles across state electricity boards. Rajasthan and Gujarat solar parks are accelerating substation battery deployments under renewable purchase obligations.
Japan
METI pilot programs are testing sulfide-based solid-state cells for 220kV switching stations. Japanese automotive manufacturers specify nickel-cadmium for foundry substations where voltage sag tolerance is paramount. The Kanto region's utility procurement favors long-cycle-life chemistries for grid stabilization applications.
Substation Battery Market Vendor Landscape
Integrated cathode producers and specialized valve-regulated lead-acid fabricators split the market along chemistry lines. The structure concentrates around three strategic archetypes: integrated battery manufacturers with captive material processing, regional specialists with deep utility service networks, and industrial conglomerates with diversified electrochemical portfolios. Capacity expansion and backward integration into refined material supply represent the dominant competitive moves.
Within the integrated manufacturing tier, Contemporary Amperex Technology Co Ltd. exemplifies cathode-to-pack production scale, while LG Energy Solution Ltd. occupies a position among Korean conglomerate-backed suppliers. GS Yuasa Corp. anchors the Asia-Pacific specialist segment with Japanese precision manufacturing heritage. These three represent distinct strategic positions rather than direct comparables.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co Ltd. (CATL) |
| LG Energy Solution Ltd. |
| GS Yuasa Corp. |
| EnerSys |
| Exide Technologies |
| Saft |
| East Penn Manufacturing |
| Amara Raja Batteries |
| Johnson Controls |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta battery manufacturing corridor concentrates cathode-to-pack production capacity, granting Chinese integrated producers outsized leverage in utility procurement negotiations across Asia-Pacific and European markets. This geographic concentration compresses margin capture for non-integrated system integrators locked into fixed-price tenders.
Pricing Analysis
Price spreads between Asian and European delivery points widen during lithium carbonate volatility cycles, with German transmission system operators absorbing 8-12% premiums for REACH-compliant electrolyte formulations. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with IEC 62619-certified lithium-ion systems commanding top tier. Cost compression in lead-acid retrofit segments is intensifying because India's state electricity boards consolidate procurement through central tendering. Data center operators in Northern Virginia demonstrate lowest price sensitivity due to resilience premiums, while rural electrification programs in India face acute capital constraints.
Supply Chain Analysis
US export controls on advanced battery manufacturing equipment constrain technology transfer to non-allied production corridors, fragmenting equipment sourcing pathways. Cathode active material production concentrates in China, South Korea, and Japan, with processed lithium and refined cobalt drawing from Chinese chemical processing hubs. Cell assembly rests on separator membranes, electrolyte salts, and thermal management components predominantly sourced from East Asian suppliers. Single-source vulnerability in Chinese lithium refining creates structural exposure to supply disruption. Distribution runs through utility EPC contractors and specialized energy storage integrators rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among transmission system operators consolidating fleet procurement through multi-year framework agreements, compressing vendor margins and favoring integrated manufacturers with captive material supply.
For Market Incumbents: Harden qualification barriers by securing IEC 62619 certification ahead of 14-18 month testing windows, locking out second-tier competitors from utility tenders. Deepen backward integration into cathode active material production to offset lithium carbonate volatility exposure. Threat substitution from second-life EV packs demands preemptive cost positioning through captive recycling infrastructure. For New Entrants and Emerging Players: Mid-market commercial and industrial microgrids in Southeast Asia represent the most penetrable entry point, bypassing utility qualification barriers that favor established vendors. India's distributed rural substation deployments under SAUBHAGYA offer white-space access through localized DC backup specialization. Target hybrid AC-DC architecture integration with solid-state transformer manufacturers as go-to-market channel. For Investors and Strategic Acquirers: Long-term, this sits as a utility infrastructure replacement cycle play because grid modernization mandates and renewable integration requirements institutionalize recurring procurement demand. Acquisition target archetype: regional specialists with deep utility service networks and captive recycling capabilities. Signal to watch is FERC Order 2222 implementation pace across US independent system operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium carbonate processing insulates margin compression from spot market volatility. |
| Second-Life EV Pack Recycling Infrastructure | Automotive battery retirement streams feed substation duty cycles at reduced cost basis. |
| Hybrid AC-DC Architecture Certification | Solid-state transformer integration opens dual-function revenue streams for grid stabilization. |
| Long-Term Utility Framework Agreements | Multi-year procurement locks secure capacity allocation against competitor encroachment. |
| REACH-Compliant Electrolyte Reformulation | EU market access preservation justifies 8-12% cost premium absorption by German TSOs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and utility procurement databases through structured interviews with utility planning officers, battery system integrators, EPC contractors, and grid operators across Asia-Pacific, Europe, and North America. Primary intelligence combines bottom-up installation tracking with top-down capacity announcements from cathode producers and cell manufacturers. Secondary validation draws from FERC filings, EIA grid investment data, CEA mandate documentation, and MIIT policy releases.
Forecast inputs span chemistry type, end-use segment, installation architecture, and regional regulatory framework across the analysis window. Segmentation dimensions model technology tier, customer type, application function, and deployment mode. CAGRs derive from installation run-rate analysis against policy-mandated replacement schedules and renewable integration targets. Specific inputs include lithium-ion cell cost curves, lead-acid retrofit cycle timing, and flow battery duration economics for frequency regulation contracts.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting utility capital expenditure programs or lithium commodity price trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding policy continuity for India's CEA mandates and US IRA manufacturing credits. Material shifts in export control regimes affecting equipment transfer or electrolyte chemistry restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market