
 Battery-As-A-Service Market | 2026-2036
Battery-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-As-A-Service Market Intelligence
China's NEV mandate is consolidating the cost-of-entry calculus for battery-swapping networks, forcing infrastructure providers to achieve fleet-scale density before unit economics turn positive. NIO leverages its proprietary Power Swap stations to anchor premium passenger-vehicle loyalty across China's tier-one cities. Gogoro competes through scooter-swapping dominance in Taiwan's dense urban corridors. CATL sustains cell-supply leverage by extending standardized battery pack architectures to multiple OEM partners.
Battery-as-a-Service separates battery asset ownership from vehicle ownership, enabling users to pay for energy capacity through subscription or per-use contracts while providers retain responsibility for cell health, thermal management, and cycle-life optimization. The model eliminates upfront battery costs that often represent 30-40% of electric vehicle purchase price, accelerating fleet electrification where capital constraints block adoption. Subscription delivery models currently dominate revenue flow due to predictable recurring income and lower customer acquisition friction, though Pay-As-You-Go structures are gaining traction in last-mile logistics where route variability makes fixed fees uneconomical. Lithium-Ion battery types occupy the installed base but solid-state chemistry positions for premium tiers as energy density thresholds improve.
China's MIIT enforces battery traceability standards through national monitoring platforms, while the EU's Battery Regulation mandates carbon-footprint disclosure and recycled-content quotas for cells sold in Europe. India's BIS certification and PLI scheme for advanced chemistry cells shape local market access rules for foreign pack-assemblers. Stakeholders must decide whether to build captive swapping networks or supply standardized packs to third-party operators before regional interoperability standards crystallize.
Market Dynamics
China's MIIT battery traceability mandates and NEV subsidy phase-outs are compressing ownership economics, forcing infrastructure providers to achieve fleet-scale density before unit economics stabilize. Asset-light subscription models now dominate capital deployment decisions across passenger and commercial vehicle segments.
Growth Catalysts
- NEV Mandate Compression:China's dual carbon goals and phased purchase-tax exemptions accelerate fleet electrification where upfront battery costs previously blocked adoption.
- Last-Mile Logistics Density:Urban freight operators in Shanghai and Shenzhen deploy swappable electric vans to eliminate charging downtime during multi-drop delivery windows.
- Standardized Pack Architectures:Modular battery designs reduce per-vehicle engineering costs and enable cross-OEM interoperability at swapping stations.
Market Restraints
- Lithium Price Volatility:Cell chemistry input costs fluctuate with South American brine and Australian spodumene concentrate supply disruptions.
- Station Capex Intensity:Automated swapping infrastructure requires precision robotics and thermal management systems that strain operator balance sheets.
- Interoperability Friction:Absent unified connector and communication protocols, proprietary networks lock users into single-provider ecosystems.
Strategic Opportunities
- India's PLI Chemistry Incentives:The government's production-linked incentive scheme for advanced cells attracts pack-assemblers to Gujarat and Tamil Nadu manufacturing corridors.
- Pay-As-You-Go Logistics:Route-variable last-mile operators in Jakarta and Bangkok prefer per-kilometer billing over fixed monthly subscriptions.
- Solid-State Premium Tiering:Higher energy-density cells enable longer-range passenger vehicle segments once manufacturing scales beyond pilot volumes.
Industry Challenges
- Battery Health Certification:Cycle-life verification and thermal runaway testing protocols extend pack onboarding timelines at third-party swapping networks.
- Legacy Fleet Integration:Retrofitting internal combustion vehicle depots with automated battery handling equipment demands facility redesigns and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-As-A-Service Market |
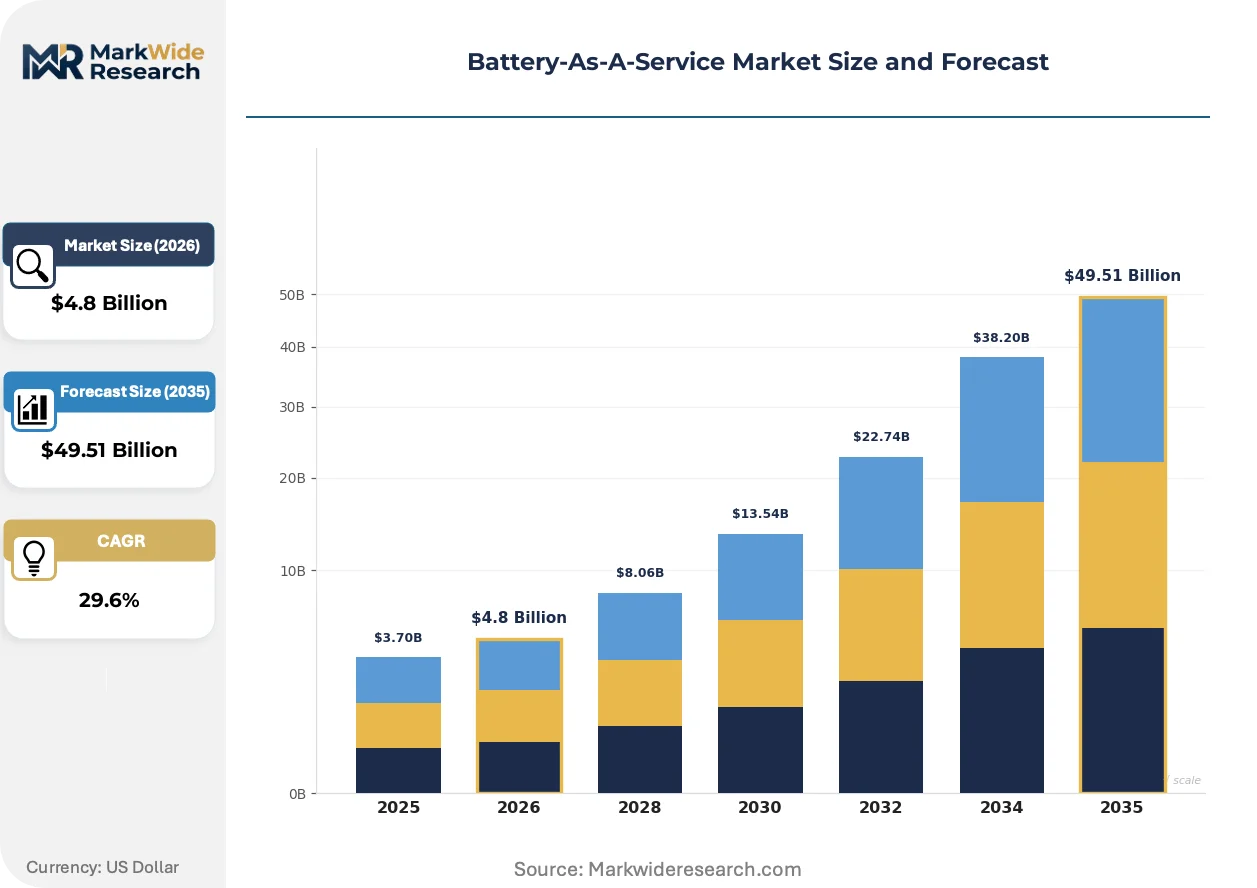
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $49.51 Billion |
| CAGR (2026 – 2036) | 29.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Subscription, Pay-As-You-Go, Lease, Purchase End User: Automotive, Industrial, Energy Storage, Consumer Electronics Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Technology: Smart Grid, IoT Integration, Charging Stations, Battery Management Systems |
| Companies Covered | NIO, Gogoro, Sun Mobility, Ample, CATL, XPENG, SAIC Motor, Bounce Infinity, Immotor Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-As-A-Service Market Strategic Shifts & Innovations
Asset unbundling and chemistry diversification are rewriting competitive rules. Providers now compete on network density and pack lifecycle management rather than vehicle integration alone.
Solid-state battery technology is expanding into premium passenger vehicle tiers as energy density thresholds improve. Early deployments target luxury sedans in China's tier-one cities where range anxiety and charging time sensitivity peak. The technology is expanding into fleet operator consideration sets once manufacturing costs compress below lithium-ion parity.
The EU Battery Regulation mandates carbon-footprint disclosure and recycled-content quotas for cells sold in Europe. Industrial consequence: pack-assemblers must reconfigure supply chains to source certified green lithium and establish EU-based recycling partnerships. Premium passenger and commercial vehicle segments face the steepest compliance cost curves, accelerating vertical integration into cell production.
Last-mile logistics buyers now unbundle vehicle acquisition from energy service contracts. Fixed-fee subscriptions lose ground to consumption-based billing in Southeast Asian urban freight corridors where daily route distances vary significantly. Jakarta and Bangkok operators lead this shift, pressuring providers to develop dynamic pricing algorithms tied to actual kilometers traveled.
Battery-As-A-Service Market Segmentation
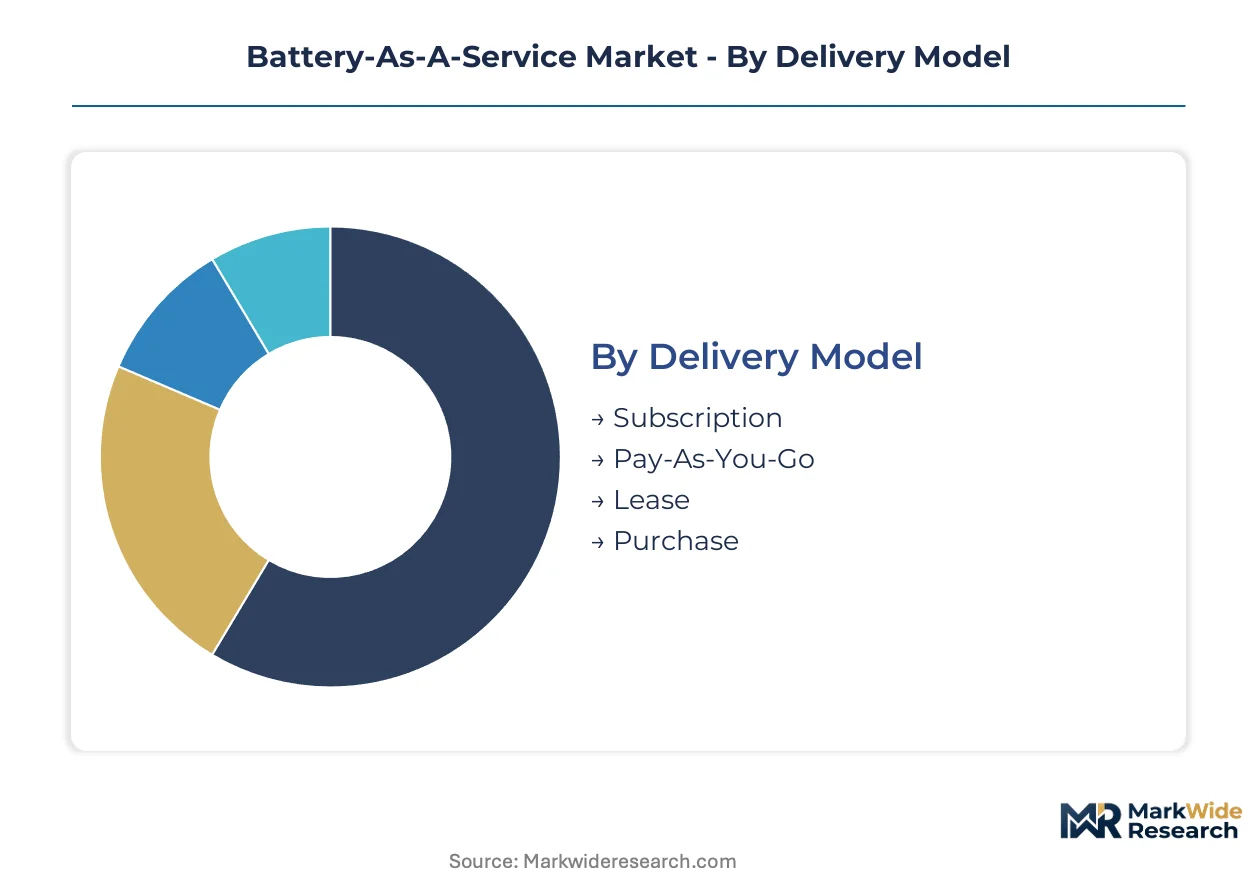
Battery-as-a-Service segmentation separates capital deployment models from technology choices, revealing where providers concentrate infrastructure investment versus where users prefer operational flexibility. Understanding these splits clarifies why swapping networks achieve profitability in dense logistics corridors but struggle in dispersed passenger markets.
Delivery Model:
Capital intensity varies dramatically across these structures, with infrastructure-heavy models demanding station networks before revenue materializes while asset-light alternatives shift balance-sheet burden to users.
- Subscription:Fixed monthly fees cover battery access, maintenance, and replacement cycles, locking in predictable recurring revenue for providers. Fleet operators in China's Yangtze River Delta manufacturing cluster favor this structure for electric van deployments where route regularity justifies flat-rate budgeting. The model requires providers to carry full battery depreciation risk.
- Pay-As-You-Go:Per-kilometer or per-swap billing aligns costs with actual energy consumption, eliminating overpayment for idle capacity. Last-mile operators in Jakarta and Bangkok prefer this structure where daily route distances fluctuate significantly based on order density. Dynamic pricing algorithms tie fees to real-time utilization data.
- Lease:Long-term contracts with defined residual value obligations split ownership economics between provider and user. Commercial vehicle fleets in India's Gujarat manufacturing corridor utilize lease structures to preserve debt capacity for core logistics assets.
- Purchase:Direct battery acquisition with optional service attachments appeals to capital-rich operators seeking full asset control. Energy storage installations at industrial facilities in Germany's Ruhr Valley favor purchase models paired with separate maintenance agreements.
Subscription absorbs the bulk of installed capacity; Pay-As-You-Go is expanding most quickly.
End User:
Application-specific duty cycles determine pack durability requirements and swapping frequency economics.
- Automotive:Passenger and commercial vehicles with standardized pack footprints enable interoperability across swapping networks. NIO's proprietary Power Swap stations anchor premium passenger loyalty across China's tier-one cities. High utilization rates in taxi and ride-hail fleets compress payback periods for station infrastructure.
- Industrial:Forklifts, port equipment, and mining vehicles operate in controlled environments where centralized swapping depots replace distributed charging. Manufacturing clusters around Shanghai and Ningbo deploy industrial BaaS to eliminate production-line downtime from battery maintenance.
- Energy Storage:Grid-scale and behind-the-meter installations require thermal management and cycle-life optimization services separate from vehicle integration. Utility-scale operators in California's Central Valley subscribe to capacity services rather than owning degrading assets.
- Consumer Electronics:Portable power stations and high-drain devices utilize small-format swap networks with limited infrastructure requirements. Taiwan's dense urban corridors host scooter-swapping dominance targeting two-wheeler commuters.
Automotive commands the dominant revenue share; Industrial applications are climbing the fastest as fleet electrification accelerates.
Battery Type:
Chemistry selection drives energy density, thermal stability, and recycling pathway economics.
- Lithium-Ion:NMC and LFP chemistries dominate current installed base with established supply chains and proven cycle-life performance. CATL extends standardized pack architectures to multiple OEM partners, leveraging cell-supply leverage across passenger and commercial segments. The chemistry faces carbon-footprint scrutiny under EU Battery Regulation mandates.
- Solid-State:Higher energy-density cells with improved thermal stability target premium tiers as manufacturing scales beyond pilot volumes. Early deployments focus on luxury sedans in China's tier-one cities where range anxiety peaks. Solid-state chemistry positions for premium passenger vehicle segments once cost thresholds improve.
- Lead-Acid:Mature chemistry with established recycling infrastructure serves price-sensitive industrial applications with moderate cycle requirements. Backup power installations in India's Tamil Nadu manufacturing corridor utilize lead-acid BaaS for cost containment.
- Nickel-Metal Hydride:Intermediate energy density with proven safety profiles persists in hybrid vehicle applications and specific industrial niches. Japanese automotive suppliers maintain NiMH service networks for legacy hybrid fleets.
Lithium-Ion carries the overwhelming installed base; Solid-State is gaining share fastest in premium passenger segments.
Technology:
Digital and physical infrastructure layers determine network interoperability and operational efficiency.
- Smart Grid:Bidirectional power flow and demand-response integration enable batteries to serve grid stabilization functions beyond vehicle propulsion. Vehicle-to-grid pilots in the Netherlands aggregate swapped packs as distributed storage assets.
- IoT Integration:Real-time telemetry on cell health, temperature, and location optimizes swap scheduling and predictive maintenance. Gogoro's network in Taiwan leverages IoT density for dynamic station stocking.
- Charging Stations:Fixed infrastructure complements swapping by addressing overnight and long-duration charging needs. China's MIIT traceability mandates apply equally to charging and swapping assets.
- Battery Management Systems:Cell-level monitoring and thermal control software preserves cycle life and enables health certification for third-party network admission. BIS certification in India shapes local market access rules for foreign BMS providers.
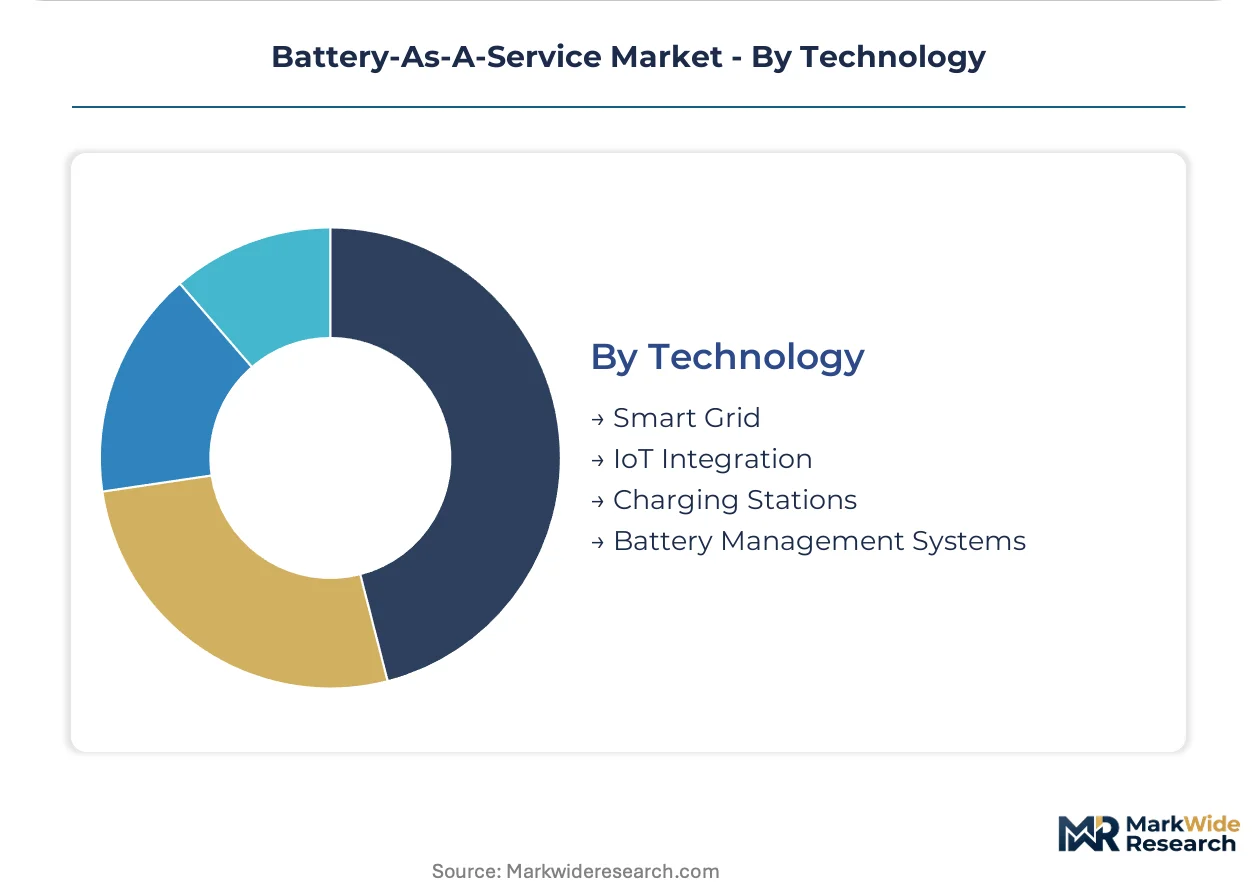
Battery Management Systems anchor provider differentiation; Smart Grid integration is expanding most quickly as grid operators seek flexible capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing cluster concentrates the highest density of battery-swapping deployments, with fleet operators in Shanghai and Ningbo driving subscription model adoption for electric commercial vehicles.
China
MIIT battery traceability mandates and dual carbon goals compress ownership economics for passenger and commercial fleets. NEV purchase-tax exemptions accelerate electrification across tier-one cities where upfront battery costs previously blocked adoption. NIO anchors premium passenger loyalty through proprietary Power Swap stations concentrated in Beijing, Shanghai, and Shenzhen.
India
BIS certification requirements and the PLI scheme for advanced chemistry cells attract pack-assemblers to Gujarat and Tamil Nadu manufacturing corridors. Last-mile logistics operators in Delhi-NCR and Bengaluru prefer lease structures to preserve debt capacity for core fleet assets. Sun Mobility and Bounce Infinity deploy swapping networks targeting two-wheeler and three-wheeler commercial segments.
United States
IRA clean vehicle tax credits alter fleet electrification calculus for commercial operators in California's Central Valley and Texas logistics corridors. EPA emissions standards for medium- and heavy-duty vehicles tighten compliance timelines for last-mile delivery fleets. Ample positions automated swapping technology for depot-based commercial vehicle applications in dense urban freight markets.
Germany
EU Battery Regulation mandates carbon-footprint disclosure and recycled-content quotas for cells sold across member states. Industrial operators in the Ruhr Valley and Bavarian manufacturing belts favor purchase models paired with separate maintenance agreements for energy storage installations. CATL extends standardized pack architectures to German OEM partners seeking supply chain diversification.
Taiwan
Dense urban corridors in Taipei and Kaohsiung sustain scooter-swapping network economics through high daily utilization rates. Gogoro leverages IoT integration for dynamic station stocking across the island's metropolitan cores. The model eliminates charging downtime for two-wheeler commuters navigating congested city centers.
Battery-As-A-Service Market Key Industry Players
Chinese producers anchor one tier; Taiwan and India specialists hold differentiated positions in two-wheeler and last-mile logistics segments. The vendor base clusters around three strategic archetypes: captive verticalists controlling station and pack technology, modular suppliers licensing standardized architectures to multiple OEMs, and asset-light operators focusing on network density without cell manufacturing. Competitive moves concentrate on strategic partnerships for station deployment and portfolio diversification into adjacent energy storage services.
Within the captive verticalist tier, NIO and Gogoro exemplify divergent geographic specializations—NIO represents premium passenger vehicle swapping concentrated in Chinese tier-one cities, while Gogoro anchors two-wheeler network density across Taiwan's urban corridors. CATL occupies a position as the modular supplier archetype, extending cell and pack architectures to multiple automotive OEMs without operating end-user swapping networks. These three companies illustrate how competitive positioning splits between network operators and component suppliers.
| Leading Market Players |
|---|
| NIO |
| Gogoro |
| Sun Mobility |
| Ample |
| CATL |
| XPENG |
| SAIC Motor |
| Bounce Infinity |
| Immotor Technology |
| Others |
Cost & Logistics Intelligence
Captive vertical integration into cell manufacturing anchors both supply security and pricing power for infrastructure providers operating battery-swapping networks. China's MIIT traceability mandates and the EU's carbon-footprint disclosure requirements force pack-assemblers to absorb compliance costs that reshape competitive economics across subscription and Pay-As-You-Go tiers.
Pricing Analysis
Volume-heavy subscription models trade margin for network density while per-kilometer Pay-As-You-Go structures preserve flexibility premiums. Price differentiation rests on certification tier under China's national monitoring platforms and after-sales thermal management bundling. Cost compression in standard Lithium-Ion tiers intensifies as CATL extends standardized architectures to multiple OEM partners. Fleet operators in last-mile logistics exhibit highest price sensitivity; premium passenger segments in China's tier-one cities show lowest elasticity.
Supply Chain Analysis
Freight costs from South American brine and Australian spodumene concentrate operations amplify input volatility for cell manufacturers. Supply concentrates in China, South Korea, and Japan for cathode active materials and precision robotics components. The network draws from Chilean lithium carbonate, Indonesian nickel matte, and Chinese electrolyte formulations. Single-source vulnerability persists in automated swapping station robotics. Distribution runs through OEM-integrated captive networks and third-party infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-Service markets sit in a technology-transition phase where solid-state chemistry displaces Lithium-Ion in premium passenger tiers while standardized pack architectures compress costs in commercial segments.
For Market Incumbents: Anchor network density in China's Yangtze River Delta manufacturing cluster before unit economics stabilize under NEV mandate compression. Invest in BMS certification for third-party network admission to defend against modular suppliers licensing standardized architectures. Pursue backward integration into cell production to secure supply against South American brine disruption. For New Entrants and Emerging Players: Begin with Pay-As-You-Go deployment in Jakarta and Bangkok last-mile corridors where route variability blocks subscription adoption. Target India's Gujarat and Tamil Nadu manufacturing corridors where PLI chemistry incentives attract pack-assemblers. Lead with dynamic pricing algorithms tied to real-time IoT utilization data. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive OEMs seeking captive swapping infrastructure. Long-term viability favors providers achieving fleet-scale density before regional interoperability standards crystallize. Watch for EU Battery Regulation recycled-content quota enforcement as inflection signal for vertical integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Standardized Pack Architecture Deployment | CATL's multi-OEM licensing reduces per-vehicle engineering costs across China's tier-one cities. |
| Backward Integration into Cell Production | Captive cathode supply secures margin against Australian spodumene concentrate price volatility. |
| IoT-Enabled Dynamic Pricing Launch | Gogoro's real-time telemetry optimizes swap scheduling in Taipei's dense urban corridors. |
| Third-Party Network Certification Program | BIS-compliant BMS providers unlock India's Gujarat and Tamil Nadu manufacturing access. |
| Solid-State Pilot Manufacturing Scale-Up | Early luxury sedan deployments in Shanghai and Shenzhen establish premium tier positioning. |
Research Approach
Document review covered SEC filings from battery and automotive OEMs, MIIT traceability platform disclosures, EU Battery Regulation implementation guidance, and IEA energy storage deployment databases, complemented by interviews with swapping network operations directors, fleet procurement managers at last-mile logistics operators, BMS software engineers, and lithium supply contract specialists. Secondary validation drew from customs trade data, vehicle production registries, and national NEV subsidy records. Bottom-up station deployment counts triangulated against top-down market sizing from subscription revenue disclosures.
Installed base projections and revenue forecasts across the analysis window applied segmentation by delivery model, end-user application, battery chemistry, and technology layer. CAGRs derived from logistic growth curves fitted to fleet electrification penetration rates and station network density thresholds. Industry-specific inputs included China's dual carbon goal compliance timelines, EU recycled-content quota phase-ins, and lithium carbonate spot price volatility bands.
Underlying measurement precision varies by segment; subscription revenue flows carry tighter precision than emerging Pay-As-You-Go logistics deployments. Forecasts reflect assumptions about NEV mandate enforcement consistency, solid-state manufacturing cost compression trajectories, and regional interoperability standard adoption timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Maintenance Service Market