
 ASEAN Countries Electric Vehicle Battery Separator Market | 2026-2036
ASEAN Countries Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Countries Electric Vehicle Battery Separator Market Insights
The capital-intensity divergence between wet-process and dry-process separator specialists is collapsing as ASEAN governments tie battery subsidies to local manufacturing footprints. Toray Industries Inc. leverages its biaxially-oriented polypropylene film heritage to anchor supply relationships with Thai-based cell producers. SK Innovation Co. Ltd competes through integrated separator-electrolyte positioning that extends from its Korean base into Indonesian joint ventures. Asahi Kasei Corporation dominates the coated separator tier through ceramic-layer R&D partnerships with Japanese automotive OEMs expanding ASEAN assembly capacity.
Electric vehicle battery separators are microporous membranes, typically 12-30 micrometers thick, manufactured through wet or dry stretching of polyolefin substrates to enable ion transport while preventing internal short circuits between anode and cathode. Polypropylene separators sustain the largest volume position across ASEAN markets due to cost compatibility with nickel-manganese-cobalt cell chemistries favored by regional EV programs. Coated separator variants, particularly ceramic-coated architectures, represent the fastest-growing product category as thermal runaway standards tighten for tropical climate operation. Solid-state technology segments occupy early-stage positioning, with pilot-scale separator development concentrated in Singapore-based materials research consortia.
Thailand's Board of Investment, Indonesia's Ministry of Industry, and Singapore's Economic Development Board each administer EV battery localization frameworks that directly condition separator import tariffs against domestic production commitments. BIS-equivalent standards adoption across Vietnam and Malaysia is forcing separator suppliers to certify puncture strength and shutdown temperature performance through accredited regional laboratories. Stakeholders must monitor how Indonesia's nickel processing dominance integrates with downstream separator specification requirements as cell factories advance from planning to commissioning phases.
Market Dynamics
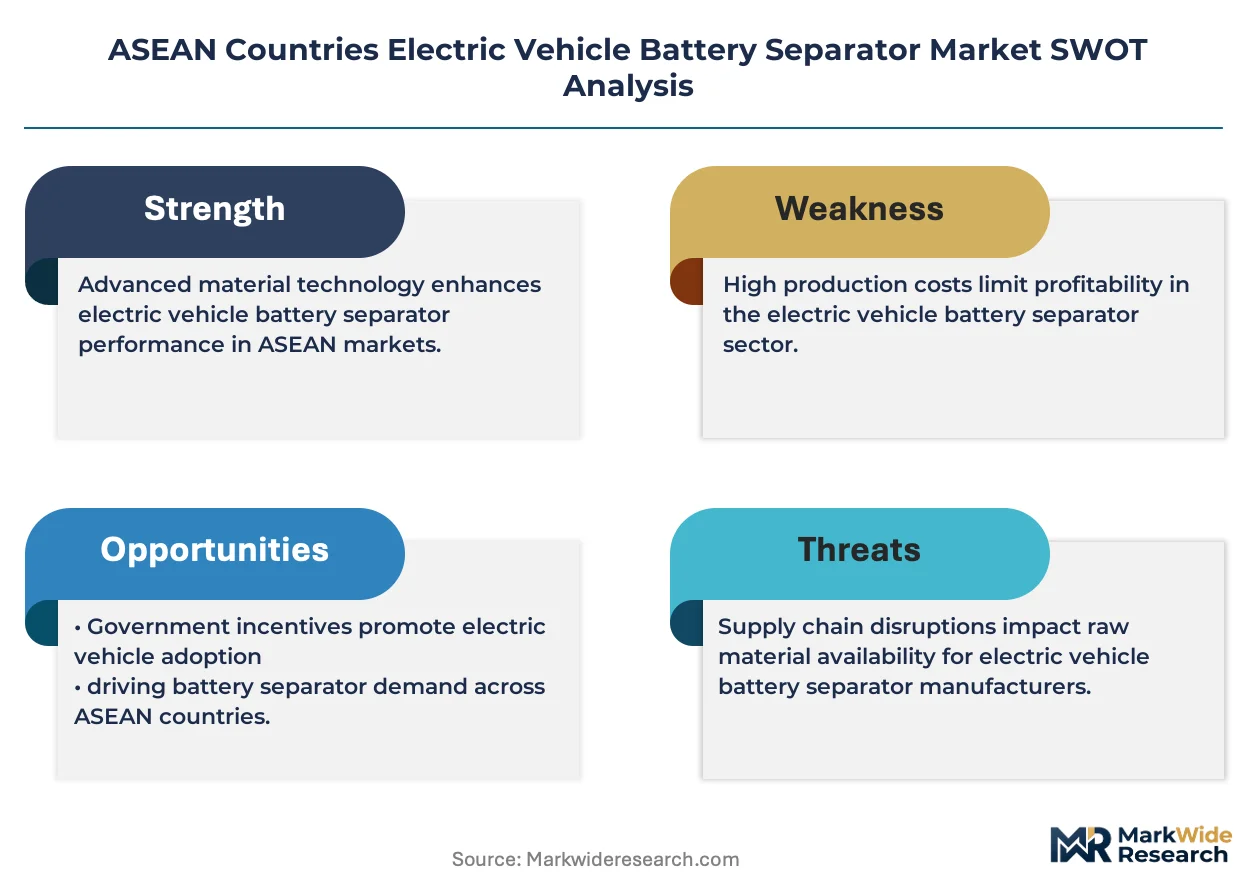
Thailand's Board of Investment incentive packages are forcing separator suppliers to establish domestic manufacturing footprints or face punitive import tariffs, collapsing the historical cost advantage of imported wet-process membranes and redrawing competitive qualification criteria across the ASEAN supply base.
Growth Catalysts
- Thailand BOI Localization Mandates:Battery cell producers must source 40% of separator volume from domestic facilities to qualify for full EV subsidy tiers, accelerating greenfield investments in Rayong and Chonburi provinces.
- Nickel-Manganese-Cobalt Chemistry Dominance:Regional OEMs favor NMC cell architectures that pair cost-effectively with polypropylene separators, sustaining procurement volumes as production scales across Indonesian and Thai assembly plants.
- Ceramic-Coated Separator Adoption:Thermal runaway protection requirements for tropical climate operation are pulling coated separator variants into standard specifications for premium passenger EV platforms.
Market Restraints
- Ultra-High Molecular Weight Polyethylene Feedstock Concentration:Separator producers depend on specialized UHMWPE resin supplies concentrated among Korean and Japanese petrochemical suppliers, exposing margins to input cost volatility and allocation constraints.
- Dry-Process Technical Limitations:Dry-stretched polypropylene separators exhibit inferior puncture resistance and electrolyte wettability versus wet-process alternatives, restricting their application to lower-energy-density cell designs.
- Import Tariff Friction:Indonesia's Ministry of Industry applies graduated duties on uncoated separator imports that lack domestic production commitments, elevating landed costs for non-integrated suppliers.
Strategic Opportunities
- Vietnam Underpenetration:VinFast's expanding Haiphong battery complex lacks qualified local separator sources, creating first-mover positioning for suppliers achieving BIS-equivalent certification through accredited regional laboratories.
- Integrated Separator-Electrolyte Positioning:Cell producers are consolidating procurement around suppliers offering matched separator and electrolyte formulations, rewarding technical integration investments.
- Singapore Solid-State R&D Consortia:Pilot-scale ceramic and polymer-ceramic composite separator development for next-generation solid-state architectures offers technology licensing pathways ahead of commercialization.
Industry Challenges
- Biaxial Stretching Equipment Lead Times:Specialized film orientation machinery from German and Japanese suppliers carries 18-24 month delivery cycles, compressing project execution timelines for capacity expansions.
- Multi-Jurisdiction Certification Complexity:Suppliers must sequentially certify puncture strength, shutdown temperature, and dimensional stability across Thailand's TISI framework, Indonesia's SNI adoption, and Malaysia's Standards Malaysia requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Countries Electric Vehicle Battery Separator Market |
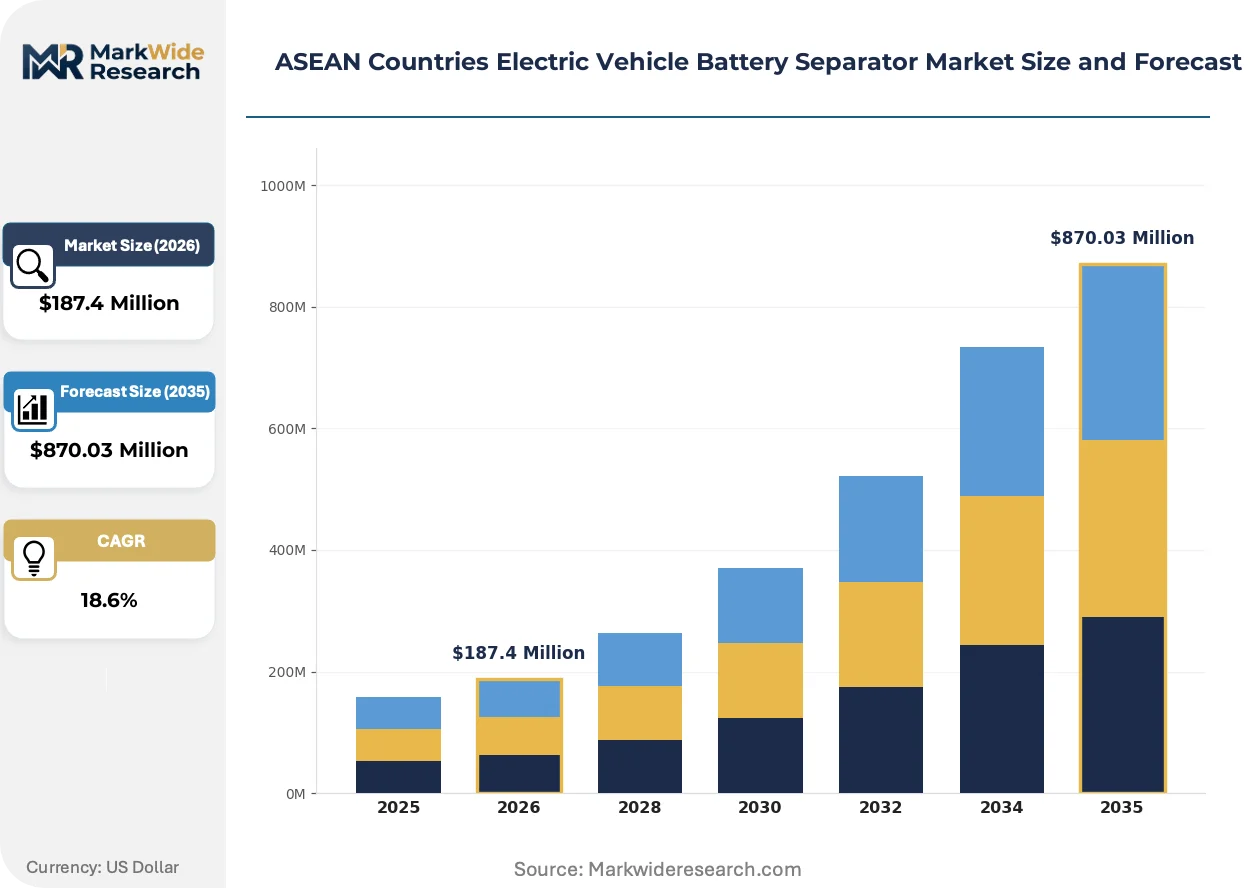
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Coated Separator, Celgard, Others Technology: Li-ion, Lead Acid, Solid State, Flow Battery End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Hybrid Vehicles |
| Companies Covered | Mitsubishi Chemical Group Corporation, Toray Industries Inc., Hitachi Chemical Company Ltd, Sumitomo Chemical Co. Ltd, Teijin Ltd, SK Innovation Co. Ltd, Sembcorp Industries Ltd, Senior plc, Asahi Kasei Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Countries Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology trajectories across ASEAN are converging on thermal safety enhancement and local manufacturing compliance, with coating architectures and process innovations displacing legacy commodity specifications.
Ceramic-coated polyolefin separators are displacing uncoated wet-process membranes in premium EV applications. Regional cell producers specify alumina or boehmite ceramic layers to meet 150°C thermal shrinkage thresholds mandated by tropical climate safety protocols. This displacement is compressing price premiums for coated variants while elevating technical qualification barriers for commodity suppliers.
Thailand's Board of Investment EV incentive packages now condition full subsidy eligibility on verified local content ratios for battery components. Cell producers must document domestic separator sourcing to access tax holidays and import duty exemptions, redirecting procurement relationships toward qualified Thai-based manufacturers. Indonesian and Vietnamese regulators are studying parallel frameworks, suggesting regional policy convergence.
Cell producers are consolidating supplier relationships around integrated material sets rather than discrete component procurement. Buyers increasingly specify matched separator-electrolyte combinations to optimize interfacial stability and manufacturing yield, compressing the vendor base toward technically integrated suppliers. This pattern concentrates procurement decisions in Thailand's Eastern Economic Corridor battery cluster, where regional OEMs localize supply chains for ASEAN-market vehicle programs.
ASEAN Countries Electric Vehicle Battery Separator Market Segmentation
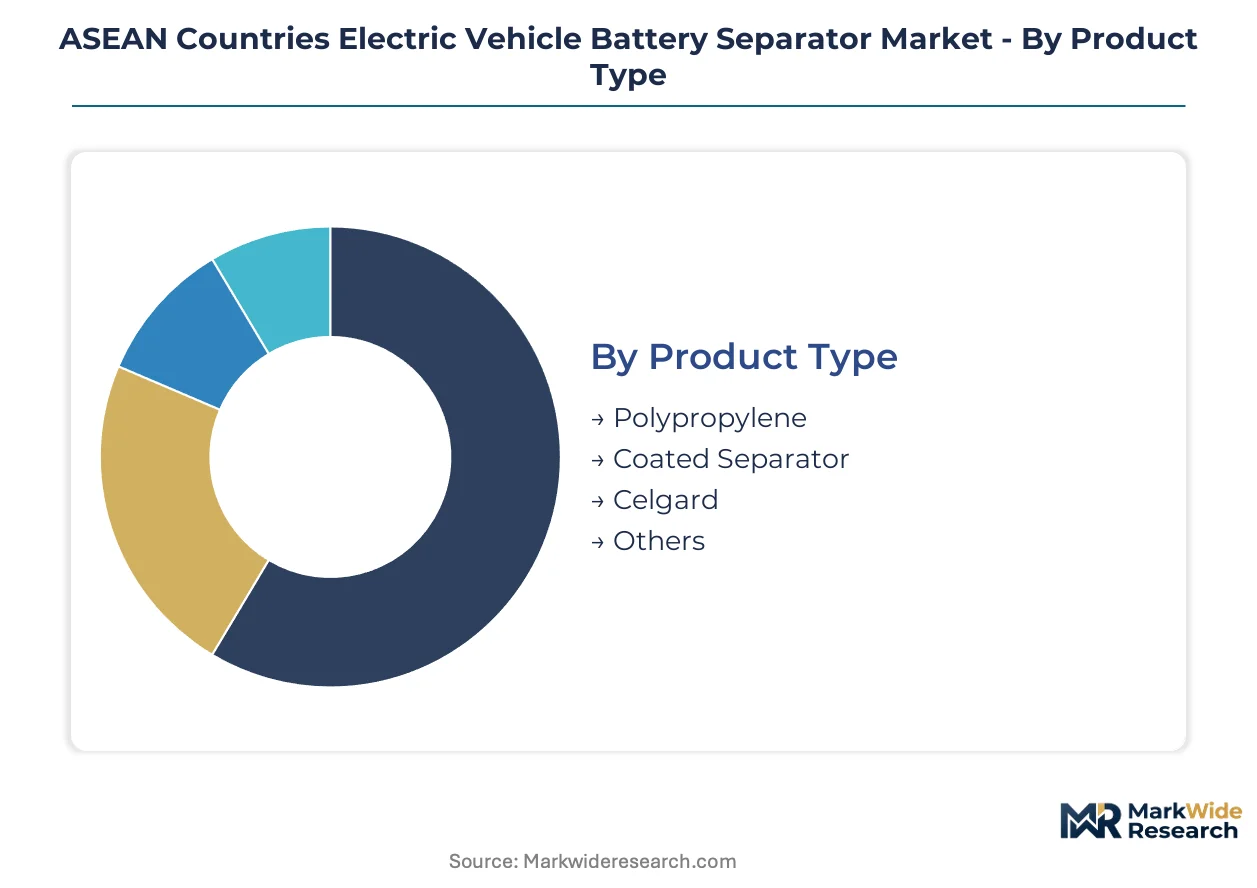
Separator procurement across ASEAN battery clusters fragments along chemistry compatibility, thermal performance tiers, and local content compliance thresholds. Understanding segment boundaries clarifies where Thai and Indonesian cell producers concentrate qualification efforts.
Product Type:
Margin pools concentrate in coated architectures where ceramic-layer specifications command qualification premiums from tropical-climate safety protocols.
- Polypropylene:Microporous membranes manufactured through biaxial stretching of polyolefin substrates deliver cost-compatible ion transport for nickel-manganese-cobalt cell chemistries. Thai-based cell producers in Rayong and Chonburi provinces anchor procurement volumes here to meet Board of Investment local content ratios.
- Coated Separator:Alumina or boehmite ceramic layers deposited on polyolefin substrates achieve 150°C thermal shrinkage thresholds mandated for premium passenger EV platforms. Demand is climbing fastest as regional OEMs tighten thermal runaway standards for tropical operation.
- Celgard:Dry-process polypropylene heritage products from established membrane specialists retain positioning in lower-energy-density cell designs where puncture resistance requirements moderate.
- Others:Polyethylene-polypropylene composite and trilayer architectures serve niche high-voltage applications with specialized shutdown temperature specifications.
Polypropylene holds installed capacity across Thai separator fabrication lines. Coated separator is rotating up the share rankings as cell producers revise specifications for climate-adjusted safety margins.
Technology:
Volume concentration tracks lithium-ion cell factory commissioning schedules across Indonesia's nickel processing corridor and Thailand's Eastern Economic Corridor.
- Li-ion:Dominant technology segment powering NMC and LFP cell architectures across ASEAN EV assembly plants. Separator specifications here determine procurement relationships with Korean and Japanese material suppliers establishing Thai manufacturing footprints.
- Lead Acid:Mature technology with separator requirements concentrated in automotive starter battery and industrial backup power applications. Vietnamese and Malaysian producers maintain regional supply for this declining segment.
- Solid State:Pilot-scale ceramic and polymer-ceramic composite separator development concentrated in Singapore-based materials research consortia. Commercial deployment remains pre-revenue as cell producers evaluate manufacturing scalability.
- Flow Battery:Vanadium redox and zinc-bromine systems deploy microporous separators in stationary energy storage configurations. Grid-scale deployment in Thai and Indonesian utility pilots drives limited procurement volumes.
Li-ion technology anchors separator demand across ASEAN battery clusters. Solid state is expanding most quickly in R&D expenditure though production volumes remain negligible.
End User:
Procurement authority concentrates with integrated cell producers rather than discrete component distributors across ASEAN supply chains.
- OEMs:Automotive original equipment manufacturers with in-house cell production or joint venture structures—BYD, Wuling, and regional Thai assemblers—directly specify separator grades and coating architectures.
- Aftermarket Providers:Independent battery replacement and refurbishment operations serving legacy vehicle fleets. Separator procurement here follows commodity specifications with minimal coating requirements.
- Vehicle Assemblers:Contract manufacturers without captive cell production rely on pack integrators for separator specification, compressing their direct procurement role.
- Fleet Operators:Commercial and logistics vehicle operators with centralized procurement negotiate separator-containing battery pack supply agreements rather than direct material sourcing.
OEMs hold installed capacity for direct separator qualification. Aftermarket providers are rotating up the share rankings as early EV cohorts exit warranty periods and require replacement cell sourcing.
Application:
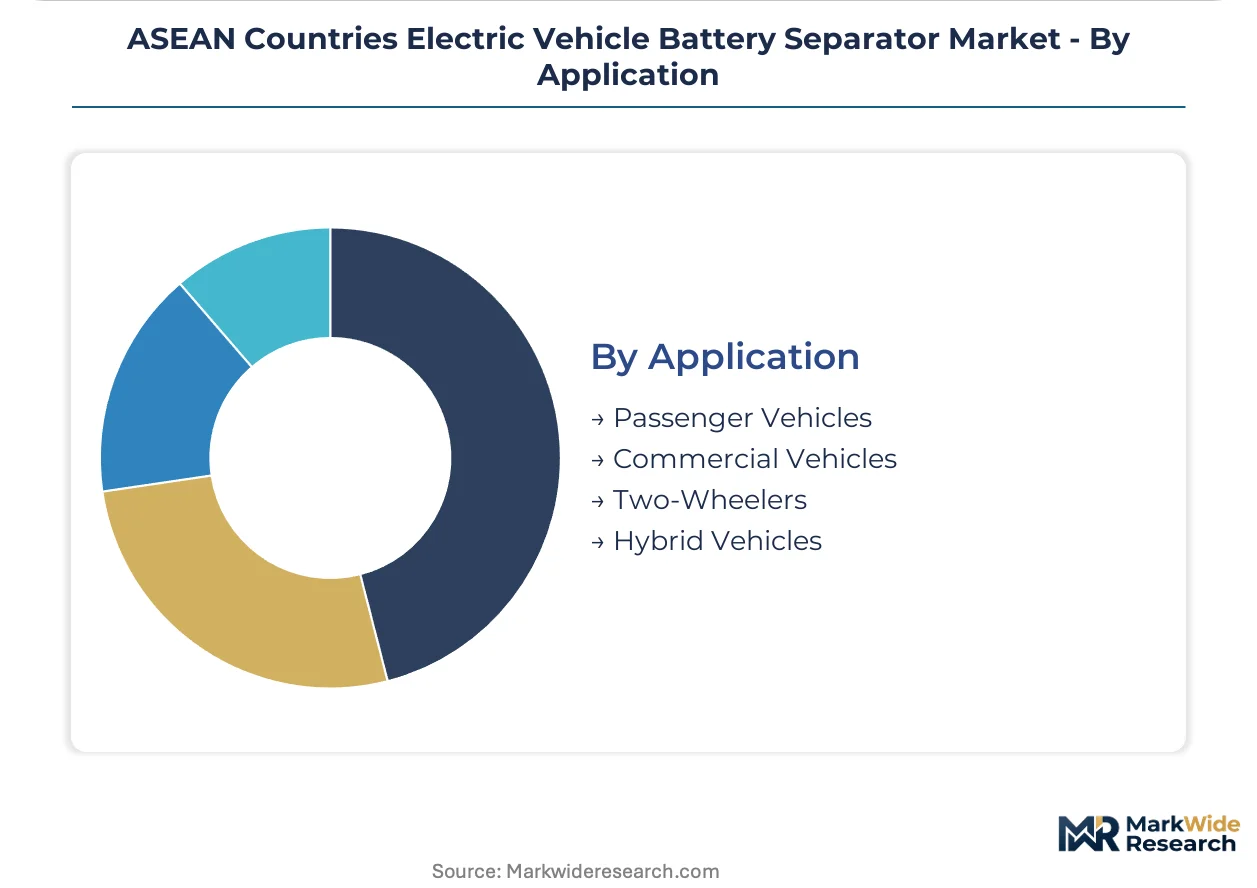
Passenger vehicle platforms concentrate procurement volumes while commercial vehicle electrification creates specification divergence for heavy-duty thermal management.
- Passenger Vehicles:Premium sedan and SUV platforms drive coated separator adoption with ceramic-layer requirements for 150°C thermal stability. Thai and Indonesian assembly plants localize supply chains for ASEAN-market vehicle programs here.
- Commercial Vehicles:Bus and truck electrification demands thicker separator configurations—20-30 micrometers versus 12-16 micrometers for passenger applications—to sustain cycle life under high-C-rate operation.
- Two-Wheelers:Motorcycle and scooter electrification across Vietnam, Indonesia, and Thailand deploys thinner polypropylene separators in cost-optimized cell designs with reduced coating penetration.
- Hybrid Vehicles:Plug-in and full-hybrid architectures balance power density with cycle life requirements, sustaining intermediate separator specifications between pure electric and combustion-engine starter battery tiers.
Passenger vehicles hold installed capacity across Thai cell production lines. Commercial vehicles are climbing the fastest as fleet electrification programs in Jakarta and Bangkok advance procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Separator buyers in Indonesia and Thailand exhibit lowest price sensitivity due to BOI-linked subsidy access, while Vietnamese and Malaysian assemblers face sharper procurement cost pressures from fragmented incentive frameworks.
Thailand
Rayong and Chonburi provinces host the densest cell production corridors, with BOI incentive packages mandating 40% domestic separator sourcing for full EV subsidy tiers. The Eastern Economic Corridor battery cluster concentrates procurement authority among Korean and Japanese material suppliers establishing Thai manufacturing footprints.
Indonesia
Nickel processing dominance in Sulawesi and Halmahera underpins downstream cell factory investments, with the Ministry of Industry applying graduated import duties on uncoated separators lacking domestic production commitments. Joint ventures between Korean cell producers and Indonesian state enterprises are advancing separator qualification timelines.
Vietnam
VinFast's Haiphong battery complex drives concentrated demand, yet qualified local separator sources remain scarce. BIS-equivalent certification requirements through accredited regional laboratories are forcing extended supplier validation cycles.
Singapore
Solid-state separator R&D consortia concentrate pilot-scale ceramic and polymer-ceramic composite development, with the Economic Development Board administering grants tied to commercialization timelines. Technology licensing pathways are emerging ahead of production-scale deployment.
Malaysia
Standards Malaysia certification frameworks for puncture strength and shutdown temperature performance are elevating technical barriers for commodity suppliers. Penang and Selangor industrial zones attract pack integrators serving regional OEM assembly programs.
ASEAN Countries Electric Vehicle Battery Separator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with coated separator specialists commanding qualification premiums while commodity polypropylene fabricators compete on volume scale. The market structures around three tiers: integrated material sets suppliers, regional manufacturing licensees, and R&D-stage technology licensors. Dominant competitive moves include backward integration into UHMWPE feedstock and strategic partnerships with cell producers for matched separator-electrolyte formulations.
Among Japanese chemical conglomerates, Mitsubishi Chemical Group Corporation, Toray Industries Inc., and Asahi Kasei Corporation exemplify distinct competitive positioning archetypes. Mitsubishi Chemical Group Corporation represents the diversified materials portfolio approach. Toray Industries Inc. anchors biaxially-oriented polypropylene film heritage positioning. Asahi Kasei Corporation occupies the coated separator tier through ceramic-layer specialization. Korean suppliers including SK Innovation Co. Ltd compete through integrated separator-electrolyte positioning extending from established manufacturing bases.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group Corporation |
| Toray Industries Inc. |
| Hitachi Chemical Company Ltd |
| Sumitomo Chemical Co. Ltd |
| Teijin Ltd |
| SK Innovation Co. Ltd |
| Sembcorp Industries Ltd |
| Senior plc |
| Asahi Kasei Corporation |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month lead times for German and Japanese biaxial stretching equipment compress project timelines and concentrate pricing power with incumbent separator fabricators holding installed capacity across Thailand's Eastern Economic Corridor. This equipment scarcity elevates capital barriers for new entrants while locking cell producers into long-term offtake relationships with qualified local suppliers.
Pricing Analysis
After-sales service revenue from technical support and formulation optimization drives lifetime value for integrated separator-electrolyte suppliers. Three-tier pricing structure across ceramic-coated premium, wet-process standard, and dry-process economy levels reflects certification grade and thermal performance tier differentiation. Pricing pressure stems from Indonesia's graduated import duties on uncoated separators lacking domestic production commitments. Vietnamese and Malaysian assemblers exhibit highest price sensitivity due to fragmented incentive frameworks, while Thai and Indonesian cell producers prioritize local content compliance over unit cost.
Supply Chain Analysis
Japan and South Korea anchor polyolefin substrate and UHMWPE resin supply, with Korean petrochemical suppliers controlling specialized feedstock allocation. Separator fabrication draws from biaxial stretching equipment concentrated among German and Japanese machinery builders, ceramic coating materials from alumina and boehmite processors, and electrolyte formulations from Korean chemical conglomerates. Single-source vulnerability runs through UHMWPE resin concentration among Korean and Japanese suppliers. Distribution runs through direct procurement relationships between cell producers and qualified separator fabricators, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified biaxial stretching technicians and ceramic-layer deposition specialists remain scarce across ASEAN manufacturing zones, constraining capacity expansion timelines and elevating acquisition premiums for firms holding certified technical teams.
For Market Incumbents: Fortify backward integration into UHMWPE feedstock through offtake agreements with Korean petrochemical suppliers or captive resin production investments. Expand ceramic-coating capacity in Rayong and Chonburi provinces ahead of Indonesian regulatory convergence on local content mandates. Lock in multi-year supply agreements with VinFast and regional Thai assemblers before European and Chinese separator specialists establish Thai manufacturing footprints. For New Entrants and Emerging Players: Lead with BIS-equivalent certification achievement through accredited Vietnamese laboratories to capture VinFast's unmet Haiphong demand. Target Indonesia's nickel processing corridor where joint venture structures between Korean cell producers and state enterprises are advancing separator qualification timelines. Position around integrated separator-electrolyte formulations rather than commodity membrane supply to bypass incumbent volume advantages. For Investors and Strategic Acquirers: Long-term, this sits as a localization-premium play because ASEAN governments are hard-wiring domestic production requirements into EV subsidy eligibility. Acquisition targets should demonstrate certified technical teams and established relationships with Thai Board of Investment qualification pathways. Watch for Indonesian Ministry of Industry announcements on parallel local content frameworks as the signal for regional policy convergence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UHMWPE Feedstock | Captive resin supply insulates margins from Korean petrochemical allocation constraints. |
| Ceramic-Coating Capacity Expansion | Rayong and Chonburi fabrication lines capture premium tier demand from tropical climate safety protocols. |
| Integrated Separator-Electrolyte Formulation Development | Matched material sets optimize interfacial stability for NMC cell architectures favored by regional OEMs. |
| BIS-Equivalent Certification Achievement | Accredited Vietnamese laboratory validation opens VinFast procurement channels lacking qualified local sources. |
| Joint Venture Structuring with Indonesian State Enterprises | Partnerships with Korean cell producers accelerate separator qualification in Sulawesi nickel processing corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, Board of Investment incentive filings, and Korean and Japanese supplier SEC disclosures through structured interviews with cell producer procurement directors, separator fabrication plant managers, and ceramic coating technology specialists. Bottom-up volume estimates from Thai and Indonesian cell factory commissioning schedules triangulate against top-down market sizing from ASEAN automotive production databases and EV penetration trajectories.
Segmentation dimensions modeled span product type, coating architecture, cell chemistry compatibility, end-user procurement authority, and application thermal requirements across the analysis window. CAGRs derive from installed capacity buildout timelines, local content mandate enforcement schedules, and technology substitution curves for ceramic-coated versus uncoated membrane specifications. Forecast inputs incorporate biaxial stretching equipment delivery cycles and Indonesian nickel processing downstream integration pace.
The analysis sits within stated boundaries; outcomes outside sustained EV subsidy enforcement, stable UHMWPE resin supply allocation, or accelerated solid-state technology disruption would require recalibration. Forecasts reflect documented assumptions on local content ratio verification procedures and ceramic-layer specification adoption curves. Recalibration cycles align with material shifts in Thai Board of Investment incentive tiers and Indonesian Ministry of Industry tariff enforcement announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market