
 Battery Lug Market | 2026-2036
Battery Lug Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Lug Market Insights
UL 486A-486B certification is rotating the competitive set as unqualified suppliers exit North American utility and EV battery projects. TE Connectivity Ltd. leverages deep crimping tool ecosystems to anchor its position in high-voltage battery assembly lines. Panduit Corporation sustains channel control through distributor partnerships that stock heat-shrink lug SKUs for marine and industrial contractors. Weidmüller Interface GmbH & Co. KG specializes in tin-plated copper lugs that meet IEC 61215-1 standards for solar inverter terminations.
A battery lug is an electrical connector that terminates cable conductors to battery posts, busbars, or terminal blocks, typically manufactured from electrolytic copper or aluminum alloy with tin, nickel, or silver plating to resist galvanic corrosion and maintain contact resistance below 0.05 milliohms. Copper material grades dominate margin pools because OEMs specify oxygen-free copper for EV traction battery packs where thermal cycling exceeds 10,000 lifetime events. Heat shrink lugs represent the fastest-growing product type as marine and renewable energy installers prioritize integrated environmental sealing over separate shrink tubing. The renewable energy application segment leads volume in utility-scale battery energy storage systems where lug ampacity must match 4/0 AWG or larger conductor sizes.
FDA oversight of medical device batteries and EPA restrictions on hexavalent chromium plating processes shape material selection and finishing chemistry across U.S. manufacturing. ECHA REACH Annex XVII limits on lead content force European suppliers to certify RoHS-compliant plating baths for automotive terminal exports. China's SAMR enforces GB/T 20234 EV charging interface standards that specify lug torque retention after 500 insertion cycles. Stakeholders must monitor how NHTSA proposed battery safety rules for electric vehicles propagate into terminal hardware qualification protocols.
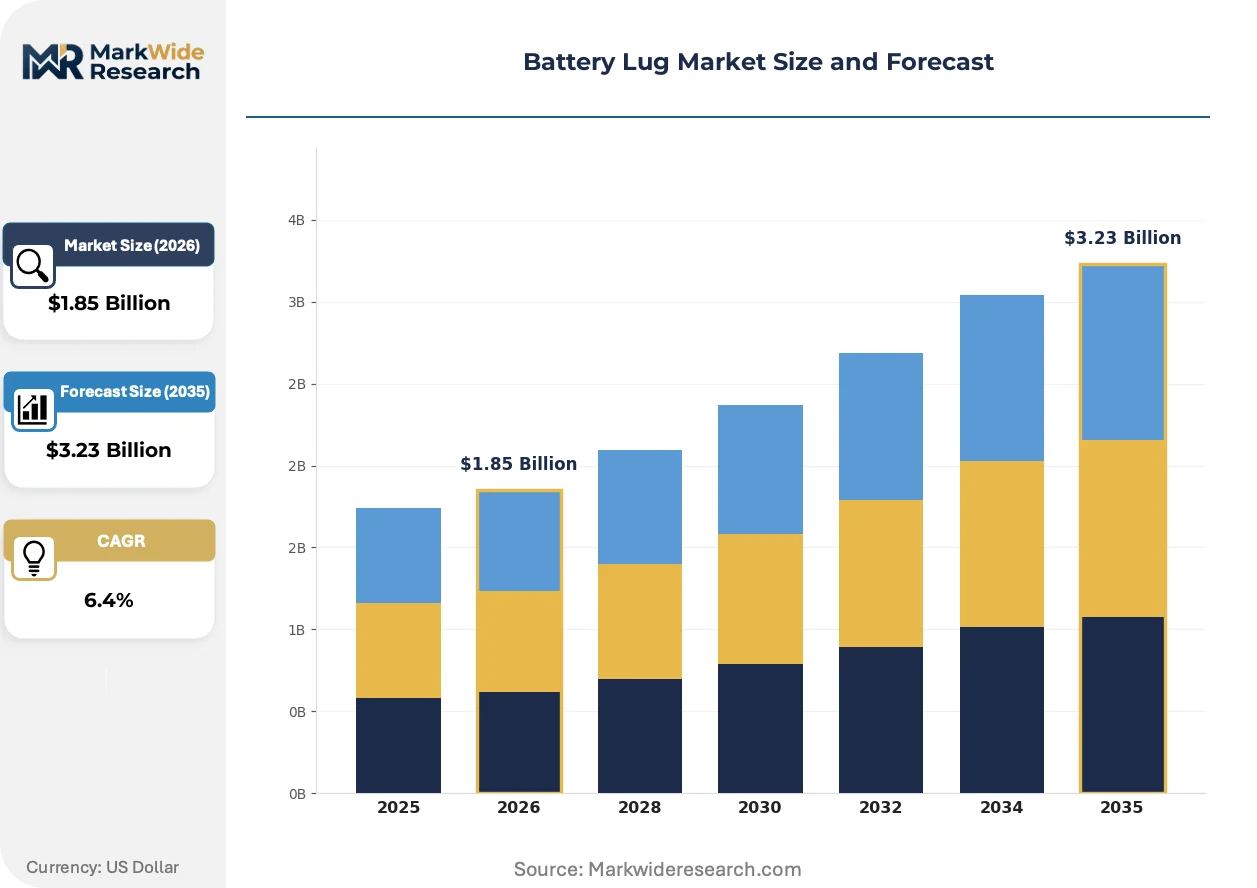
Market Dynamics
Electric vehicle battery pack assembly lines are expanding procurement of certified copper lugs as OEMs impose torque retention and thermal cycling specifications that disqualify commodity-grade suppliers.
Growth Catalysts
- REACH Annex XVII lead limits:ECHA restrictions on lead content force European suppliers to certify RoHS-compliant plating baths for automotive terminal exports, creating competitive moats for certified producers.
- Utility-scale battery energy storage:Renewable energy installers prioritize integrated environmental sealing, accelerating specification of heat shrink lugs over separate shrink tubing assemblies.
- GB/T 20234 EV charging standards:China's SAMR enforces lug torque retention requirements after 500 insertion cycles, mandating upgraded metallurgy in domestic supply chains.
Market Restraints
- Electrolytic copper price volatility:Oxygen-free copper grades specified for EV traction batteries expose margins to London Metal Exchange price swings and concentrate supply risk with Chilean and Peruvian mining operations.
- Hexavalent chromium plating phase-out:EPA restrictions on chromium(VI) processes force U.S. manufacturers to retool finishing chemistry toward trivalent alternatives with higher capital intensity.
- UL 486A-486B certification barriers:North American utility and EV battery projects now require third-party validation, accelerating supplier exits and reducing qualified vendor pools.
Strategic Opportunities
- Solar inverter terminations:IEC 61215-1 compliance requirements for tin-plated copper lugs open specialized margin pools as photovoltaic installation accelerates in Germany and Spain.
- Marine contractor channels:Distributor partnerships stocking heat-shrink lug SKUs for saltwater environments capture replacement demand from offshore wind service vessels.
- Medical device batteries:FDA oversight of implantable power systems creates qualification pathways for nickel-plated lugs meeting biocompatibility and corrosion resistance protocols.
Industry Challenges
- Crimping tool ecosystem integration:Battery pack assemblers require validated die sets and compression force monitoring, forcing lug suppliers to coordinate calibration protocols with TE Connectivity and Panduit tool platforms.
- Multi-standard certification timelines:Simultaneous pursuit of UL, IEC, and GB approvals extends product launch cycles and strains engineering bandwidth at mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Lug Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lugs, Heat Shrink Lugs, Ring Terminals, Spade Terminals Material: Copper, Aluminum, Stainless Steel, Brass Application: Automotive, Marine, Industrial Equipment, Renewable Energy End User: Manufacturers, Distributors, Contractors, DIY Enthusiasts |
| Companies Covered | 3M Company, ABB Ltd., Schneider Electric SE, Eaton Corporation, Panduit Corporation, Hubbell Incorporated, TE Connectivity Ltd., Legrand SA, Weidmüller Interface GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Lug Market Trends and Innovations
Material purity requirements and integrated sealing technologies are compressing the competitive set as unqualified suppliers exit major procurement channels.
Heat shrink lug construction is bifurcating the product architecture. Marine and renewable energy installers now specify factory-integrated adhesive-lined sleeves that eliminate field assembly steps. Offshore wind contractors in the North Sea and Baltic markets are driving this transition fastest. The technology is bifurcating procurement specifications between integrated premium SKUs and commodity unsealed alternatives.
ECHA REACH compliance is tightening material traceability requirements. Annex XVII restrictions on lead, cadmium, and hexavalent chromium force plating bath chemistry audits across European automotive supply chains. German OEM terminal suppliers now require mill certificates documenting oxygen-free copper provenance and electroplating bath composition. Tier-2 lug manufacturers without in-house analytical laboratories face accelerated disqualification.
Certification-driven specification is consolidating buyer decision criteria. EV battery pack engineers now prioritize UL 486A-486B validation over unit cost in supplier scorecards. Procurement teams at U.S. utility-scale storage developers are compressing approved vendor lists to three qualified sources per conductor size. This behavioral shift concentrates volume with vertically integrated manufacturers maintaining captive testing facilities.
Battery Lug Market Segmentation
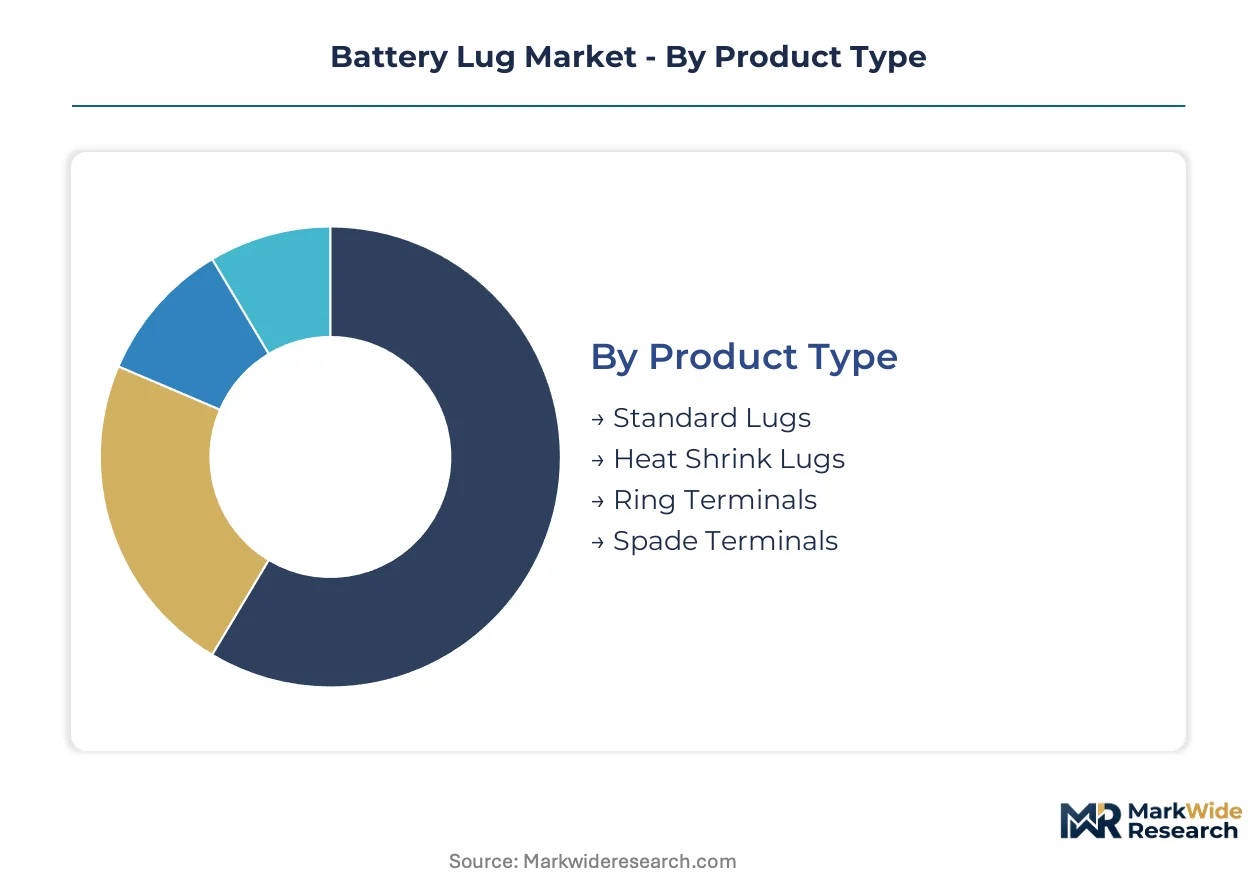
Segmentation in the battery lug market reveals how certification requirements and application environments fragment procurement specifications. Material purity standards and integrated sealing technologies now override unit cost in supplier selection across major end-use channels.
Product Type:
Substitution pressure from crimping tool ecosystems and integrated cable assembly solutions threatens standalone lug categories differently, with unsealed formats facing the strongest displacement risk from factory-terminated harnesses.
- Standard Lugs:Unsealed copper or aluminum connectors requiring separate insulation and environmental protection in field installation. Demand concentrates in industrial maintenance operations across Germany and the United States where legacy equipment specifications resist design changes and replacement cycles favor interchangeable components.
- Heat Shrink Lugs:Factory-integrated adhesive-lined sleeves that combine electrical termination with environmental sealing in a single SKU. Marine contractors in the North Sea and Baltic markets specify these for offshore wind service vessels where saltwater exposure demands zero-field-assembly reliability.
- Ring Terminals:Circular eyelet connectors for bolted busbar attachment in battery pack assembly lines.
- Spade Terminals:Forked connectors enabling quick-disconnect functionality in automotive auxiliary circuits.
Standard lugs anchor the volume base in replacement markets while heat shrink lugs gain share at the steepest rate through renewable energy procurement channels.
Material:
Cost tier stratification separates oxygen-free copper grades specified for EV traction batteries from commodity aluminum alternatives in stationary storage applications.
- Copper:Electrolytic and oxygen-free grades dominate EV battery pack procurement where thermal cycling specifications exceed 10,000 lifetime events and contact resistance must remain below 0.05 milliohms. German automotive OEMs now require mill certificates documenting provenance and plating bath composition.
- Aluminum:Lightweight alloy terminals gaining specification in utility-scale battery energy storage systems where conductor sizes reach 4/0 AWG or larger and weight reduction improves shipping economics.
- Stainless Steel:Corrosion-resistant terminals for extreme chemical environments in industrial process equipment.
- Brass:Cost-optimized alloy for low-current consumer electronics and DIY applications with minimal environmental exposure.
Copper commands the premium tier through certification requirements while aluminum expands most quickly in utility-scale installations.
Application:
Customer type concentration varies sharply, with automotive OEM supply chains demanding validated tool ecosystems and marine contractors prioritizing distributor inventory availability.
- Automotive:EV battery pack assembly lines impose torque retention and thermal cycling specifications that disqualify commodity-grade suppliers. China's SAMR enforces GB/T 20234 standards mandating lug performance after 500 insertion cycles.
- Marine:Saltwater environments drive specification of tin-plated copper with integrated heat shrink sealing for offshore wind service vessels and commercial shipping.
- Industrial Equipment:Maintenance-driven replacement demand across manufacturing facilities favors standard lug formats with broad tool compatibility.
- Renewable Energy:Utility-scale battery energy storage systems require ampacity matching for large conductor sizes and long-term corrosion resistance in outdoor installations.
Automotive anchors revenue concentration through OEM qualification protocols while renewable energy climbs the fastest on storage deployment acceleration.
End User:
Supply concentration among validated manufacturers creates tiered access, with certified producers capturing OEM direct procurement and distributors serving fragmented contractor demand.
- Manufacturers:Battery pack assemblers and automotive Tier-1 suppliers requiring UL 486A-486B validation and coordinated die set calibration with TE Connectivity and Panduit tool platforms.
- Distributors:Channel partners stocking heat-shrink lug SKUs for marine and industrial contractors, with Panduit sustaining control through inventory partnerships.
- Contractors:Field installation crews prioritizing SKU availability and same-day pickup from local electrical supply houses.
- DIY Enthusiasts:Price-sensitive consumers in automotive restoration and recreational marine applications with minimal certification requirements.
Manufacturers capture the margin pool through qualification barriers while distributors expand reach across fragmented contractor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams concentrate demand in Germany, China, and the United States, where EV battery pack assembly lines impose identical torque retention and thermal cycling specifications across supplier scorecards.
United States
Utility-scale battery energy storage developers in Texas and California compress approved vendor lists to three qualified sources per conductor size. NHTSA proposed battery safety rules propagate into terminal hardware qualification protocols. Michigan-based EV battery pack assemblers coordinate die set calibration with crimping tool platforms.
Germany
Automotive Tier-1 terminal suppliers require mill certificates documenting oxygen-free copper provenance and electroplating bath composition. ECHA REACH Annex XVII restrictions on lead, cadmium, and hexavalent chromium force plating chemistry audits. Bavarian OEM supply chains disqualify Tier-2 manufacturers without in-house analytical laboratories.
China
Domestic EV charging infrastructure expansion drives specification of lugs meeting GB/T 20234 torque retention after 500 insertion cycles. SAMR enforcement tightens material purity requirements for lead-free contact surfaces. Yangtze River Delta battery pack assembly lines anchor procurement volume.
Japan
Industrial equipment maintenance operations favor standard lug formats with broad tool compatibility. METI industrial standards shape connector specifications for factory automation systems. Nagoya manufacturing clusters sustain replacement demand from legacy machinery fleets.
South Korea
Battery cell manufacturers specify oxygen-free copper grades for traction battery packs where thermal cycling exceeds 10,000 lifetime events. Seoul Capital Area EV supply chains impose contact resistance thresholds below 0.05 milliohms. Busan-Ulsan industrial zones concentrate marine contractor demand for saltwater-resistant terminations.
Battery Lug Market Competitive Landscape
Player mix skews toward diversified electrical component conglomerates with captive testing facilities and mid-cap specialists with deep crimping tool ecosystem integration. Market structure concentrates volume among vertically integrated manufacturers maintaining UL, IEC, and GB approval portfolios. Three archetypes dominate: premium-tier certification holders, distributor-channel specialists, and tool-platform-integrated assemblers. Competitive moves center on M&A to acquire testing laboratory capabilities and strategic partnerships to anchor die set calibration protocols.
Within the diversified conglomerate tier, 3M Company and ABB Ltd. exemplify scale-driven positions spanning multiple electrical termination categories. Schneider Electric SE occupies a channel-anchored position through distributor inventory partnerships. Among specialists with explicit tool-platform integration, TE Connectivity Ltd. and Panduit Corporation represent the dominant competitive vector. Weidmüller Interface GmbH & Co. KG sits within the certification-specialist archetype for industrial automation applications.
| Leading Market Players |
|---|
| 3M Company |
| ABB Ltd. |
| Schneider Electric SE |
| Eaton Corporation |
| Panduit Corporation |
| Hubbell Incorporated |
| TE Connectivity Ltd. |
| Legrand SA |
| Weidmüller Interface GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory buffers at German automotive Tier-1 suppliers signal how oxygen-free copper procurement cycles concentrate pricing power with Chilean mining consortiums and accredited European plating houses. This lead-time band compresses margin flexibility for mid-cap lug manufacturers while validating premium pricing for certified producers holding UL 486A-486B and IEC 61215-1 portfolios.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper pricing dominate procurement between battery pack assemblers and raw material suppliers. Price differentiation rests on certification tier—UL-validated lugs command substantial premiums over unqualified alternatives—and oxygen-free copper grade provenance with mill certificate documentation. Pricing pressure stems from electrolytic copper volatility as Chilean and Peruvian supply disruptions ripple through contract renegotiations. Automotive OEMs exhibit lowest price sensitivity due to torque retention specifications, while industrial maintenance contractors prioritize unit cost over certification pedigree.
Supply Chain Analysis
Just-in-time inventory strategies prevail among U.S. utility-scale storage developers compressing approved vendor lists, while European automotive suppliers maintain strategic stockpiles of certified copper feedstock. Supply concentrates in Germany, China, and South Korea for finished lug manufacturing, with raw material extraction anchored in Chile and Peru. The chain draws from electrolytic copper cathodes, tin-nickel plating chemistries, and adhesive-lined heat-shrink polymers. Single-source vulnerability runs through oxygen-free copper refining capacity. Distribution runs through authorized distributor networks stocking TE Connectivity and Panduit die-compatible SKUs for marine and industrial contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV battery pack assembly line expansion represents an early-cycle penetration story as OEMs disqualify commodity-grade suppliers through thermal cycling specifications exceeding 10,000 lifetime events.
For Market Incumbents: Compound certification moats by acquiring captive UL and IEC testing laboratory capabilities before REACH Annex XVII enforcement tightens. Defend position against aluminum lug substitution in utility-scale storage by embedding oxygen-free copper specifications into OEM technical standards. Prioritize backward integration into oxygen-free copper sourcing to offset London Metal Exchange volatility. For New Entrants and Emerging Players: Anchor in marine contractor channels for offshore wind service vessels where heat-shrink lug demand outpaces qualified supplier capacity. Target saltwater-resistant tin-plated copper specifications for Baltic and North Sea markets. Pursue distributor partnerships with electrical supply houses stocking same-day pickup SKUs rather than direct OEM qualification pathways. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical component conglomerates with underutilized plating bath capacity and dormant UL certification portfolios. Long-term viability hinges on exposure to EV traction battery thermal cycling specifications rather than commodity industrial replacement cycles. Monitor GB/T 20234 enforcement intensity in China's Yangtze River Delta as inflection indicator for domestic supply chain qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Acquisition | Captive UL 486A-486B testing eliminates third-party validation bottlenecks for EV battery projects. |
| Plating Chemistry Transition | Trivalent chromium conversion addresses EPA hexavalent phase-out while maintaining automotive OEM qualification. |
| Die Set Calibration Partnership | TE Connectivity and Panduit tool ecosystem integration locks in battery pack assembler procurement specifications. |
| Heat-Shrink Lug Capacity Expansion | Factory-integrated adhesive-lined sleeve production captures offshore wind marine contractor demand. |
| Copper Provenance Documentation | Mill certificate traceability satisfies ECHA REACH Annex XVII audits for German automotive Tier-1 supply chains. |
Research Methodology
Operator-level perspectives from battery pack assembly engineers, automotive Tier-1 procurement directors, marine electrical contractors, and distributor inventory managers anchored the qualitative base. Secondary validation drew from NHTSA proposed rulemaking dockets, ECHA REACH Annex XVII restriction updates, SAMR GB/T standard enforcement notices, and customs trade data for electrolytic copper and plated connector imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness against copper price volatility bands and certification timeline delays. The analytical framework modeled volume and value across product type, material grade, application environment, and end-user channel dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and OEM capacity buildout schedules, with EV battery thermal cycling specifications and utility-scale storage deployment pipelines as primary demand drivers.
Decision-makers should treat outputs as directional under stable copper supply assumptions and continued REACH enforcement trajectory; material deviation would warrant model refresh. Revision becomes warranted when electrolytic copper price swings exceed historical volatility bands or when NHTSA finalizes battery safety rules propagating into terminal hardware protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market