
 Lithium-Ion Battery Filling Machine Market | 2026-2036
Lithium-Ion Battery Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Filling Machine Market Insights
The EU Battery Regulation is realigning equipment procurement standards across European cell plants. Panasonic Holdings Corporation leverages its decades of electrolyte handling expertise to sustain premium positioning in precision filling systems. Contemporary Amperex Technology Co., Limited anchors the largest installed base of high-speed filling lines across its Chinese gigafactory network. BYD Company Ltd. competes through in-house equipment integration, reducing reliance on third-party machinery suppliers.
Lithium-ion battery filling machines dispense electrolyte solutions into sealed cell housings with tolerances often below 0.5% volume deviation, ensuring electrochemical stability and cycle life performance. Automatic filling machines dominate capital expenditure budgets due to throughput requirements exceeding 300 cells per minute in automotive-scale plants. Gravimetric filling technology captures the fastest-growing technology segment as manufacturers prioritize mass-based precision over volumetric methods for high-nickel chemistries. Electric vehicles command the largest application share, though grid storage applications are expanding equipment orders as utility-scale projects proliferate.
FDA guidelines for pharmaceutical-grade electrolyte handling and EPA hazardous material containment standards shape equipment design specifications in North American facilities. China's GB standards and MIIT battery industry regulations mandate traceability systems integrated into filling line control architecture. South Korea's MFDS enforces quality system requirements that extend to electrolyte contamination protocols. Stakeholders must monitor how evolving solid-state battery chemistries alter liquid electrolyte filling demand and equipment retrofit requirements.
Market Dynamics
Electrolyte chemistry transitions toward high-nickel and silicon-anode formulations are forcing filling equipment makers to recalibrate precision tolerances and contamination controls across their installed base.
Growth Catalysts
- EU Battery Regulation recycled content mandates:European cell manufacturers are retrofitting filling lines with closed-loop electrolyte recovery systems to meet binding thresholds for recovered lithium and cobalt.
- Automotive-scale throughput requirements:Electric vehicle battery plants exceeding 100 GWh annual capacity are specifying filling machines capable of 300+ cells per minute with gravimetric verification.
- China's gigafactory cluster concentration:The Yangtze River Delta and Pearl River Delta regions host over 60% of global cell production, concentrating demand for high-speed automated filling systems.
Market Restraints
- Fluorinated electrolyte solvent cost volatility:LiPF6 and LiFSI salt prices fluctuate with phosphorus and fluorine feedstock availability, compressing equipment ROI timelines for mid-scale producers.
- Precision component supply concentration:Corrosion-resistant ceramic pumps and mass flow controllers rely heavily on German and Japanese specialty suppliers, creating single-source vulnerabilities.
- Legacy volumetric filling technology lock-in:Existing plants face stranded asset risk as gravimetric methods become standard for high-nickel chemistries requiring sub-0.5% deviation control.
Strategic Opportunities
- Solid-state battery electrolyte handling:Semi-solid and sulfide-based chemistries are opening demand for modified filling equipment capable of viscous slurry dispensing at elevated temperatures.
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are attracting filling machine vendors to establish local assembly and service infrastructure.
- Grid-scale storage procurement expansion:Utility battery projects are diversifying beyond automotive customers, creating secondary demand for mid-speed filling lines with flexible cell format compatibility.
Industry Challenges
- Electrolyte contamination control expertise scarcity:Operators capable of maintaining Class 1000 cleanroom protocols during high-speed filling operations command premium wages and limited availability.
- Multi-chemistry line changeover complexity:Plants serving both NCM and LFP customers face extended validation cycles when switching between incompatible electrolyte formulations and filling parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Filling Machine Market |
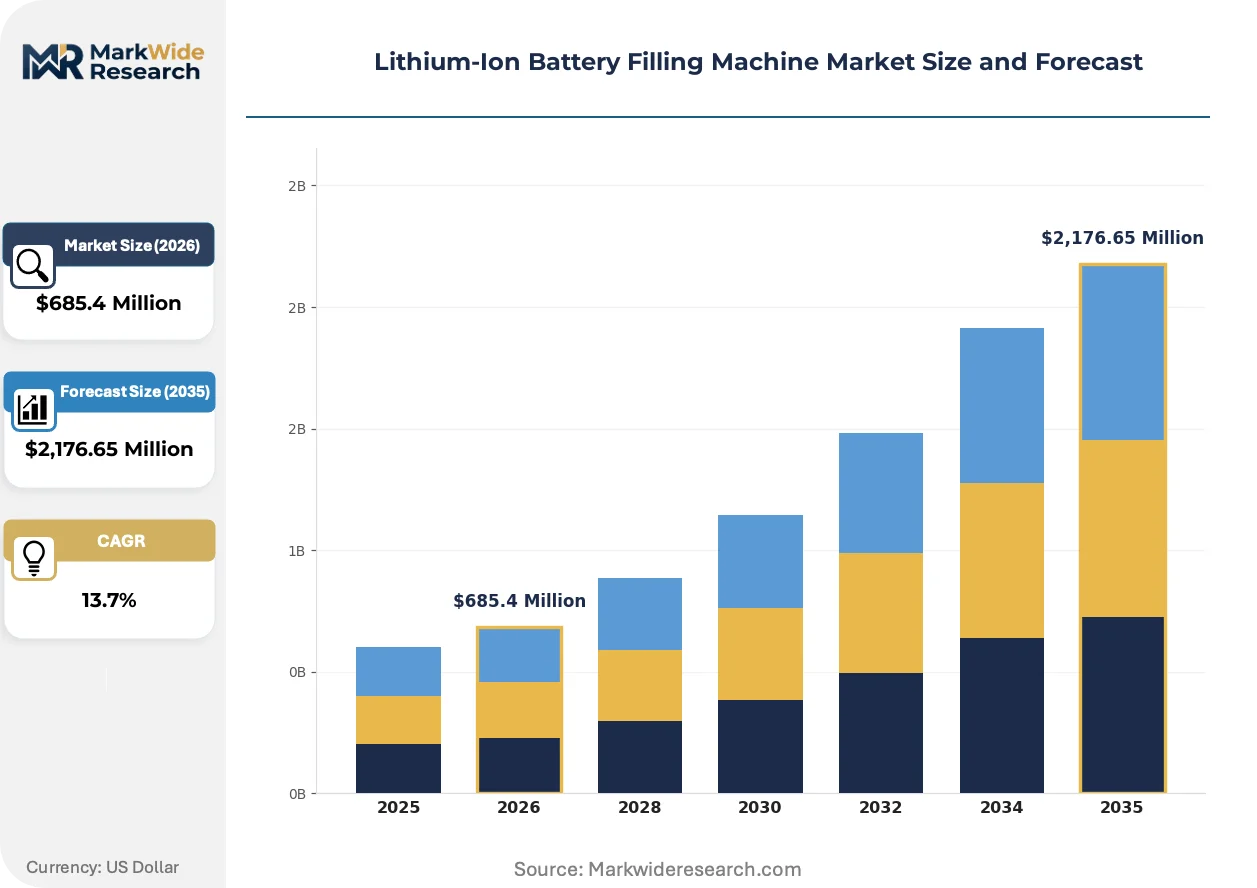
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Filling Machines, Semi-Automatic Filling Systems, Manual Filling Equipment, Integrated Filling Lines Technology: Volumetric Filling, Gravimetric Filling, Piston Filling, Peristaltic Filling, Time Pressure Filling Application: Electric Vehicles, Consumer Electronics, Grid Storage, Aerospace, Telecommunications End User: Battery Manufacturers, Electronics Assemblers, Energy Storage Providers, Aerospace OEMs |
| Companies Covered | Liontech, Morrow, Panasonic Holdings Corporation, Contemporary Amperex Technology Co., Limited., Envision AESC Limited, BYD Company Ltd., LG Chem Ltd., Samsung SDI, Tianjin Lishen Battery Joint-Stock Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Filling Machine Market Trends and Innovations
Gravimetric precision systems are displacing legacy volumetric methods as cell chemistry complexity intensifies, while regulatory traceability mandates and buyer consolidation are restructuring equipment procurement patterns across major producing regions.
Gravimetric filling technology with real-time mass flow correction is electrifying the competitive landscape for high-nickel cylindrical and prismatic cells. Automotive battery plants in Germany and South Korea are adopting these systems to achieve the sub-0.3% volume deviation required for silicon-anode compatibility. The technology is electrifying equipment upgrade cycles that previously spanned seven to ten years, compressing replacement timelines to four to five years for premium automotive suppliers.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing electrolyte formulators to develop alternative additives, which in turn requires filling equipment makers to validate material compatibility with new solvent blends. The regulation is accelerating R&D partnerships between machine builders and chemical suppliers to pre-certify wetted component materials. European cell plants are responding by specifying equipment with modular fluid contact surfaces that can be reconfigured without full line replacement.
Cell manufacturers are consolidating their supplier bases from five to seven filling machine vendors per plant to two to three strategic partners with full lifecycle service capabilities. This concentration is displacing spot-buying of spare parts and ad-hoc maintenance contracts with multi-year performance-based agreements. The shift is most pronounced in China's top-tier gigafactories, where CATL and BYD have established captive equipment integration teams that bypass traditional third-party procurement channels for core filling line investments.
Lithium-Ion Battery Filling Machine Market Segmentation
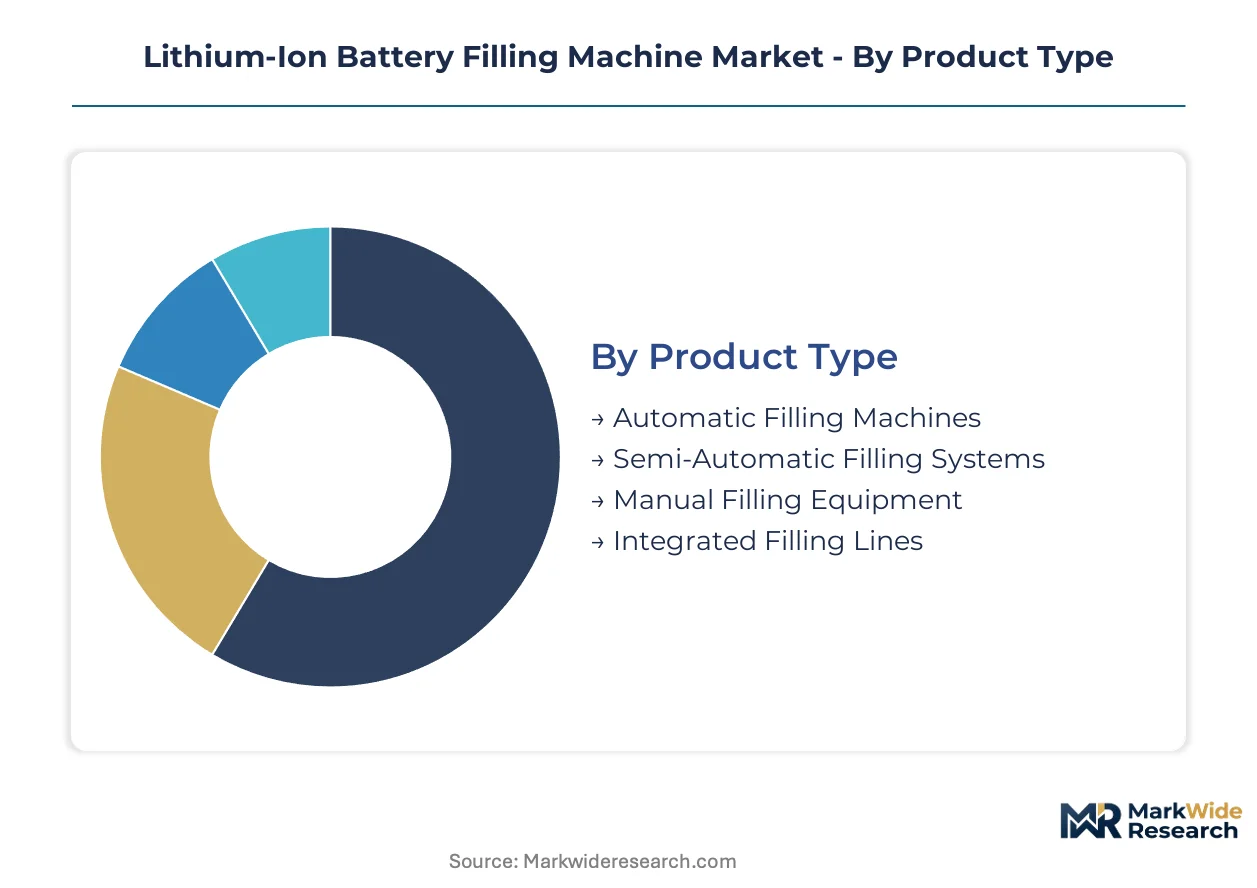
Segmentation in the lithium-ion battery filling machine market reveals how equipment specifications diverge across production scales and chemistry requirements. Understanding these divisions helps suppliers align development roadmaps with the diverging needs of gigafactory operators versus specialty cell producers.
Product Type:
Standalone filling units serve pilot lines and R&D facilities, while integrated configurations dominate automotive-scale deployments where electrolyte handling merges with formation and aging processes.
- Automatic Filling Machines:These systems achieve throughput rates exceeding 300 cells per minute with closed-loop gravimetric verification. Demand concentrates in China's Yangtze River Delta gigafactory cluster, where CATL and BYD specify equipment with integrated traceability systems mandated by MIIT regulations.
- Semi-Automatic Filling Systems:Operators retain manual load-unload functions while automated stages handle precision dispensing. European mid-scale producers favor these configurations for NCM-to-LFP changeover flexibility required by EU Battery Regulation carbon footprint accounting.
- Manual Filling Equipment:Laboratory-scale units support electrolyte formulation development at BASF and Solvant research centers.
- Integrated Filling Lines:Complete process sequences combine electrolyte dispensing with vacuum degassing and seal integrity testing in single continuous flows.
Volume placements concentrate in Automatic Filling Machines; the faster expansion belongs to Integrated Filling Lines.
Technology:
Cost tiers separate legacy volumetric methods from premium gravimetric systems, with the price gap widening as precision tolerances tighten for silicon-anode compatibility.
- Volumetric Filling:Displacement-based measurement using precision-machined pump chambers delivers adequate accuracy for standard LFP chemistries. Korean cell plants retain these systems for legacy cylindrical formats where deviation tolerances remain above 1%.
- Gravimetric Filling:Real-time mass flow correction with Coriolis sensors achieves sub-0.3% deviation control essential for high-nickel NCM and silicon-anode cells. German automotive battery plants specify these systems to meet BMW and Volkswagen qualification protocols.
- Piston Filling:Ceramic-lined positive displacement pumps handle abrasive electrolyte additives at elevated viscosities.
- Peristaltic Filling:Tubing-based isolation prevents cross-contamination during multi-campaign operations at contract manufacturers.
- Time Pressure Filling:Pressurized reservoir systems with calibrated orifice timing suit low-viscosity electrolyte formulations in consumer electronics cells.
Gravimetric Filling commands the premium tier; Volumetric Filling retains the largest installed base.
Application:
Customer maturity varies sharply across applications, with automotive buyers demanding full lifecycle service contracts while grid storage purchasers prioritize format flexibility.
- Electric Vehicles:Automotive OEMs specify equipment qualified for specific cell formats with validation protocols spanning 24-month approval cycles. Chinese, German, and South Korean battery plants drive procurement volume for 4680 cylindrical and prismatic configurations.
- Grid Storage:Utility-scale projects require filling systems accommodating diverse cell sizes from multiple suppliers. North American independent power producers favor equipment with rapid format changeover to hedge against supplier concentration risk.
- Consumer Electronics:Smartphone and laptop battery plants in Vietnam and India specify compact filling modules for pouch cell geometries.
- Aerospace:Satellite and aviation battery producers require vacuum-compatible filling for ultra-low moisture protocols.
- Telecommunications:Backup power systems for 5G infrastructure use standardized cylindrical formats with simplified handling requirements.
Electric Vehicles anchor current procurement; Grid Storage is climbing the fastest.
End User:
Supply concentration differs by buyer type, with captive equipment integration teams at major battery manufacturers bypassing traditional vendor relationships.
- Battery Manufacturers:Cell producers with annual capacities exceeding 10 GWh operate dedicated engineering groups that customize filling line architectures. These buyers specify direct procurement from subsystem suppliers rather than turnkey integrators.
- Electronics Assemblers:Contract manufacturers serving multiple battery brands require rapid changeover capabilities and standardized maintenance protocols.
- Energy Storage Providers:Utility-facing integrators prioritize equipment traceability documentation for project finance compliance.
- Aerospace OEMs:Aviation battery producers demand AS9100-certified quality systems with full material pedigree records.
Procurement volumes cluster with Battery Manufacturers; Energy Storage Providers are expanding orders most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of lithium-ion cells yet European and North American markets are accelerating localized filling equipment procurement to reduce supply chain exposure. Production capacity expansion outpaces domestic equipment supply in multiple geographies.
China
CATL and BYD operate gigafactories in the Yangtze River Delta and Pearl River Delta demanding precision electrolyte filling at automotive scale. MIIT battery industry regulations mandate traceability systems integrated into filling line control architecture. Shenzhen and Ningbo host concentrated equipment procurement for high-speed automated systems exceeding 300 cells per minute.
Germany
BMW and Volkswagen qualification protocols drive specification of gravimetric filling systems achieving sub-0.3% deviation control. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations for batteries sold in Europe. Bavaria and North Rhine-Westphalia anchor European cell plant investments requiring closed-loop electrolyte recovery retrofits.
South Korea
MFDS quality system requirements extend to electrolyte contamination protocols at Samsung SDI and LG Chem facilities. Korean cell plants retain volumetric systems for legacy cylindrical formats while adopting gravimetric methods for silicon-anode compatibility. Ulsan and Gumi industrial clusters concentrate precision component demand for ceramic pumps and mass flow controllers.
United States
FDA guidelines for pharmaceutical-grade electrolyte handling and EPA hazardous material containment standards shape equipment design specifications. IRA manufacturing incentives are attracting filling machine vendors to establish North American assembly infrastructure. Michigan and Texas battery plant investments are specifying equipment with modular fluid contact surfaces for chemistry flexibility.
India
The PLI scheme for advanced chemistry cells is stimulating domestic manufacturing capacity requiring localized filling equipment service infrastructure. BIS standards and CEA regulations govern battery quality and grid integration specifications. Gujarat and Tamil Nadu are emerging as cell production hubs with mid-speed filling line requirements for flexible cell format compatibility.
Lithium-Ion Battery Filling Machine Market Competitive Landscape
The competitive structure tilts toward integrated equipment providers with captive engineering capabilities. Panasonic Holdings Corporation and Contemporary Amperex Technology Co., Limited anchor opposite ends of the vendor spectrum—precision machinery specialists versus in-house equipment integrators. Three archetypes dominate: Japanese precision component specialists, Chinese scale-driven system integrators, and Korean chemistry-agnostic platform builders. M&A activity concentrates on ceramic pump and Coriolis sensor suppliers, while strategic partnerships between machine builders and electrolyte formulators accelerate material compatibility pre-certification.
Within the integrated equipment tier, BYD Company Ltd. exemplifies backward integration into captive filling line production, reducing third-party procurement exposure. Panasonic Holdings Corporation occupies a position as a precision machinery specialist leveraging decades of electrolyte handling expertise. Contemporary Amperex Technology Co., Limited anchors the Chinese scale-driven archetype with dedicated engineering groups customizing filling architectures for gigafactory deployment. These three represent the structural divergence between in-house integration and external equipment sourcing that is reshaping vendor relationships across major producing regions.
| Leading Market Players |
|---|
| Liontech |
| Morrow |
| Panasonic Holdings Corporation |
| Contemporary Amperex Technology Co., Limited. |
| Envision AESC Limited |
| BYD Company Ltd. |
| LG Chem Ltd. |
| Samsung SDI |
| Tianjin Lishen Battery Joint-Stock Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Corrosion-resistant ceramic pump assemblies from German and Japanese specialty suppliers cascade through three pricing tiers as they reach automotive-scale battery plants in China, Germany, and South Korea. Buyers with captive integration teams at CATL and BYD bypass standard procurement channels, compressing margins for third-party machinery vendors while elevating premium positioning for precision component specialists.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for gravimetric filling systems serving silicon-anode cell production. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified systems with sub-0.3% deviation control from mid-tier volumetric equipment and laboratory-scale manual units. Cost compression in standard-tier volumetric systems is intensifying because legacy cylindrical format demand is plateauing while high-nickel chemistry requirements escalate. Grid storage providers exhibit highest price sensitivity due to project finance constraints, whereas automotive OEMs prioritize qualification protocols over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for mass flow controllers and ceramic-lined positive displacement pumps are mandating multi-supplier qualification at Samsung SDI and LG Chem facilities. Precision component manufacturing concentrates in Germany, Japan, and South Korea, while final system assembly draws from China, South Korea, and expanding operations in the United States. Single-source vulnerability for Coriolis sensors creates exposure to phosphorus and fluorine feedstock volatility. Distribution runs through direct procurement channels for gigafactory operators and regional integrators for mid-scale European and Indian producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's recycled content thresholds and carbon footprint declarations erect a compliance moat that favors incumbent equipment providers with pre-certified modular fluid contact surfaces and closed-loop electrolyte recovery capabilities.
For Market Incumbents: Anticipate solid-state battery chemistry transitions by pre-validating viscous slurry dispensing equipment at elevated temperatures before sulfide-based formulations reach commercial scale. Defend against in-house equipment integration at CATL and BYD by deepening service-based revenue through multi-year performance agreements with full lifecycle coverage. Prioritize certification investment for REACH substance restriction compliance on per- and polyfluoroalkyl substance alternatives.
For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cells opens a window for establishing local assembly and service infrastructure before domestic gigafactory capacity solidifies around established vendor relationships. Target mid-speed filling lines for grid storage applications where format flexibility requirements have not yet consolidated around incumbent specifications. Pursue joint development partnerships with electrolyte formulators to accelerate material compatibility pre-certification for alternative solvent blends.
For Investors and Strategic Acquirers: Gravimetric system adoption rates exceeding replacement timelines of four to five years at premium automotive suppliers are the leading indicator that equipment upgrade cycles have structurally compressed from historical seven-to-ten-year patterns. Position for acquisition of ceramic pump and Coriolis sensor specialists with established German or Japanese manufacturing footprints. Monitor Class 1000 cleanroom protocol operator wage inflation as a signal of contamination control expertise scarcity constraining capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Gravimetric Technology Migration | Sub-0.3% deviation control at BMW and Volkswagen plants displaces legacy volumetric installed base. |
| Closed-Loop Electrolyte Recovery Retrofit | EU Battery Regulation mandates drive retrofit demand at Bavarian and North Rhine-Westphalia cell facilities. |
| Modular Fluid Contact Surface Redesign | REACH substance restrictions require reconfigurable wetted components without full line replacement. |
| Captive Equipment Integration Expansion | BYD and CATL engineering groups reduce third-party procurement exposure for core filling architectures. |
| India Local Assembly Establishment | PLI scheme incentives attract service infrastructure investment to Gujarat and Tamil Nadu production hubs. |
Research Methodology
SEC filings, MIIT battery industry regulatory disclosures, and customs trade data formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with filling line engineering directors at gigafactory operators, procurement leads at Tier 1 battery manufacturers, ceramic pump specialists, and electrolyte formulation R&D heads combined with secondary validation to triangulate demand forecasts. Bottom-up cell production capacity builds across the Yangtze River Delta, Pearl River Delta, Bavaria, and Michigan were cross-referenced against top-down equipment intensity ratios per GWh of installed capacity.
Historical trendline analysis of filling machine deployment patterns tracked technology transitions from volumetric to gravimetric methods and compression of replacement cycles. The forecast framework models product type, technology, application, and end user segmentation dimensions across the projection horizon. CAGRs were derived from equipment intensity coefficients applied to battery production capacity expansion schedules, with sensitivity testing for solid-state battery commercialization timelines and electrolyte chemistry transition rates.
The model assumes a particular technology adoption path; alternative pathways for semi-solid and sulfide-based electrolyte handling would alter the outlook for liquid filling equipment demand. Forecasts reflect assumptions regarding EU Battery Regulation enforcement timing, IRA manufacturing incentive durability, and China gigafactory utilization rates. Deviation in solid-state battery commercialization schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Advance Battery Technologies Market