
 EV Battery Sealant Market | 2026-2036
EV Battery Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Sealant Market Insights
Passenger EV platform engineering is decoupling from internal combustion heritage, forcing sealant specifications toward higher thermal cycling resistance and dielectric stability. Henkel AG & Co. KGaA leverages its adhesives portfolio to anchor European OEM supply chains for cell-to-pack modules. Dow Inc. sustains silicone chemistry leadership through in-house siloxane production. Sika AG competes on construction-to-mobility technology transfer, applying structural bonding expertise to battery enclosure sealing.
EV battery sealant denotes formulated polymeric materials engineered to maintain environmental isolation, thermal management, and electrical insulation across lithium-ion cell assemblies, typically operating between minus 40 degrees Celsius and 150 degrees Celsius with flame-retardant ratings such as UL 94 V-0. These materials prevent electrolyte leakage, suppress thermal runaway propagation, and protect sensitive electronics from moisture ingress in high-vibration automotive environments. Silicone sealants dominate current OEM specifications for their thermal stability and long service life, while polyurethane sealants occupy faster-growing niches in cost-sensitive module designs where processing speed outweighs extreme temperature performance. Battery manufacturers represent the most concentrated demand pool, as cell-to-pack integration eliminates intermediate module sealing steps and concentrates procurement at the cell producer level.
The EU's Battery Regulation and REACH framework mandate recycled content thresholds and restricted substance declarations, directly influencing sealant formulation chemistry and supplier qualification timelines. China's NMPA enforces GB standards for battery system safety testing, including thermal propagation resistance that depends critically on inter-cell barrier and sealant performance. Germany's KBA type-approval process incorporates these standards into homologation requirements for vehicles sold across the European market. Stakeholders must monitor how solid-state cell architectures eliminate liquid electrolyte sealing needs while introducing new interfaces around ceramic electrolyte membranes and lithium metal anodes.
Market Dynamics
Cell-to-pack architectures are eliminating module-level sealing interfaces, concentrating procurement decisions at fewer battery producers and forcing sealant suppliers to reformulate for direct cell-to-housing adhesion with enhanced thermal runaway suppression properties.
Growth Catalysts
- EU Battery Regulation:Mandated recycled content thresholds and carbon footprint declarations are accelerating qualification of bio-based sealant chemistries among European cell producers seeking compliance-ready supply chains.
- Silicone thermal stability:Operating temperature ranges spanning minus 40 to 150 degrees Celsius with UL 94 V-0 flame retardancy are meeting OEM specifications for fast-charging battery platforms where heat dissipation is critical.
- China's NMPA enforcement:GB standards for thermal propagation resistance are requiring upgraded inter-cell barrier sealants, pulling advanced formulation demand toward domestic battery manufacturers.
Market Restraints
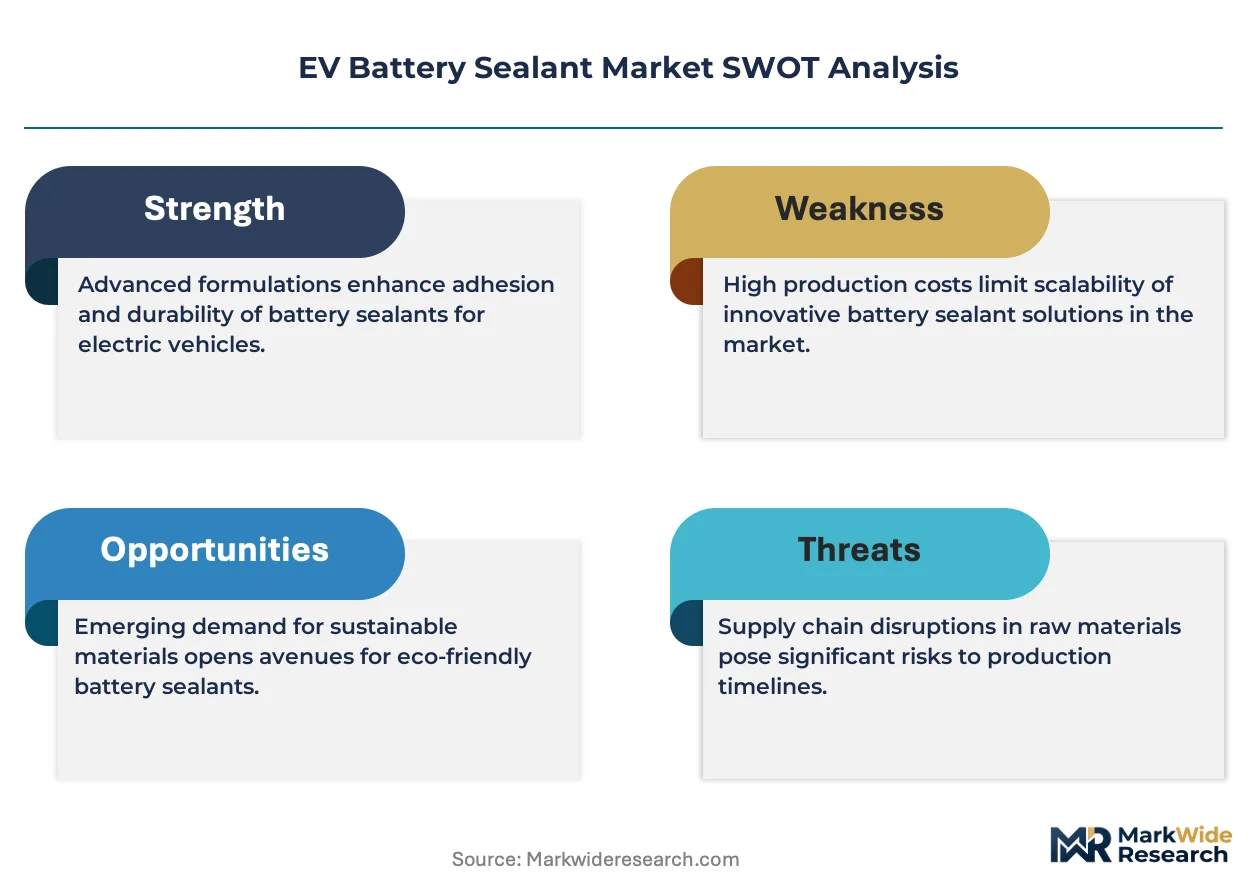
- Siloxane feedstock concentration:Specialized silicone precursor supply chains cluster in East Asian chemical corridors, exposing European and North American formulators to input cost volatility and logistics bottlenecks.
- REACH compliance timelines:Extended substance authorization periods for novel flame-retardant additives are delaying new product launches by 18-36 months, compressing formulation innovation windows.
- Polyurethane substitution:Lower-cost two-component polyurethane systems are capturing module-level applications where extreme temperature performance is secondary to processing speed and material cost.
Strategic Opportunities
- Solid-state interface sealing:Ceramic electrolyte membranes and lithium metal anodes in next-generation cells require novel compressive sealant solutions for dry electrode assembly environments.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting sealant suppliers to establish localized compounding operations serving domestic battery giga-factories.
- Direct OEM contracting:Bypassing traditional tier-one module integrators to supply cell-to-pack sealants directly to Volkswagen, BMW, and Mercedes-Benz platform engineering teams.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in dielectric stability and thermal cycling resistance for automotive lithium-ion applications commands premium compensation and extended recruitment cycles.
- Dual certification burden:Simultaneous pursuit of Chinese GB standards, EU REACH compliance, and US UL recognition is fragmenting R&D resources and extending product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Sealant Market |
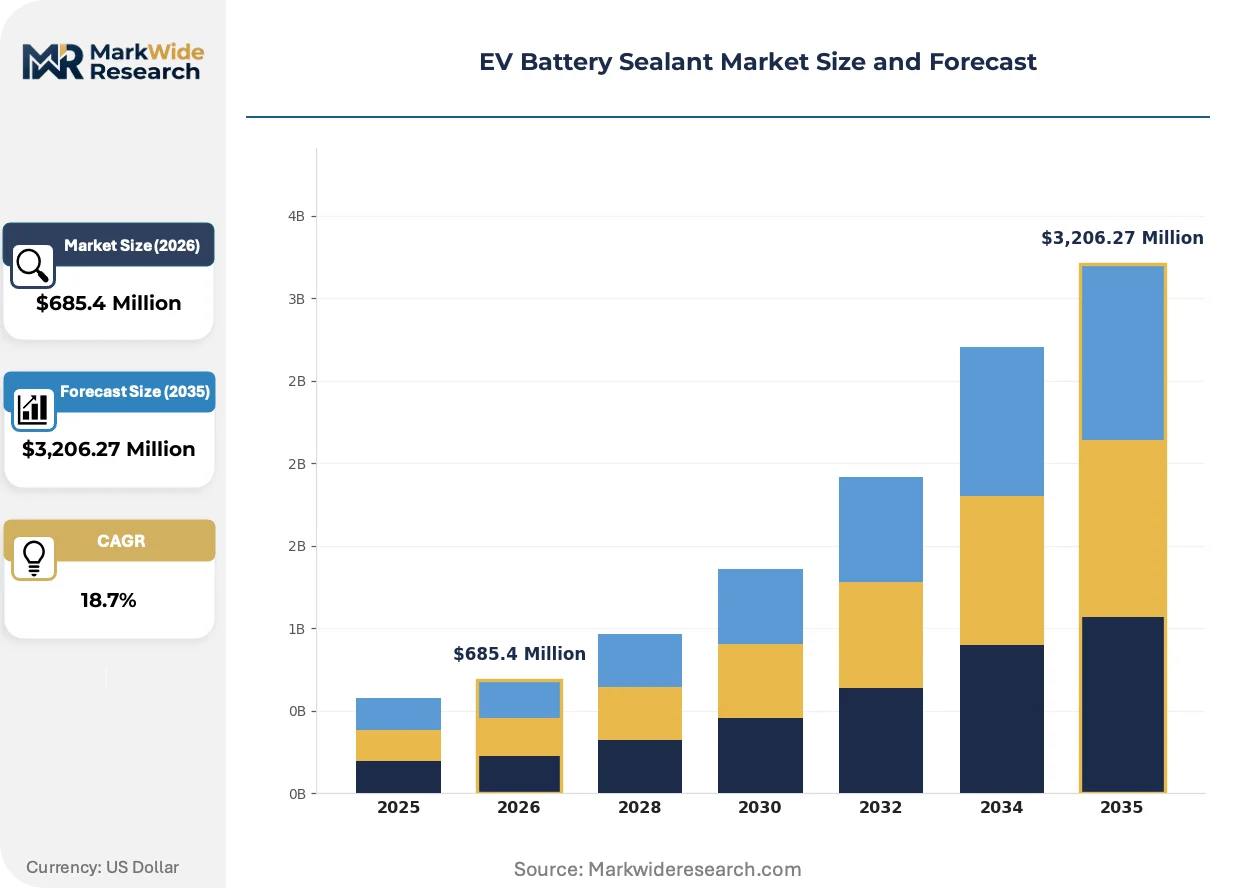
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealants, Polyurethane Sealants, Epoxy Sealants, Acrylic Sealants End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, Battery Manufacturers Application: Sealing, Adhesion, Insulation, Protection Material: Thermoplastics, Polymer Blends, Composites, Others |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, Dow Inc., Wacker Chemie AG, Bostik, Shin-Etsu Chemical Co., Ltd., ITW Performance Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Sealant Market Trends and Innovations
Formulation chemistry is pivoting toward multifunctional materials that combine environmental sealing with active thermal management, compressing what were separate material layers into single-application solutions.
Thermally conductive silicone formulations are consolidating previously discrete thermal interface and sealing functions into unified materials. Battery producers adopting cell-to-pack designs are specifying these hybrid sealants to reduce assembly steps and material count. The structural consequence is compressing supplier tiers as thermal management specialists and sealant formulators compete for the same specification slots.
REACH authorization requirements for persistent organic pollutants are restricting legacy flame-retardant chemistries in European supply chains. Formulators are accelerating phosphorous-nitrogen synergist systems and mineral filler alternatives to maintain UL 94 V-0 ratings without restricted halogenated additives. German automotive OEMs are most affected, driving qualification programs with accelerated timelines to meet 2027 fleet compliance deadlines.
Buyer concentration at the cell producer level is shortening qualification cycles and demanding application engineering support earlier in platform development. Sealant suppliers are embedding technical service teams within customer R&D facilities, displacing traditional distributor-led specification processes. This pattern is most visible in Germany's automotive corridor, where direct supplier-cell producer relationships now dominate procurement for new EV platforms.
EV Battery Sealant Market Segmentation
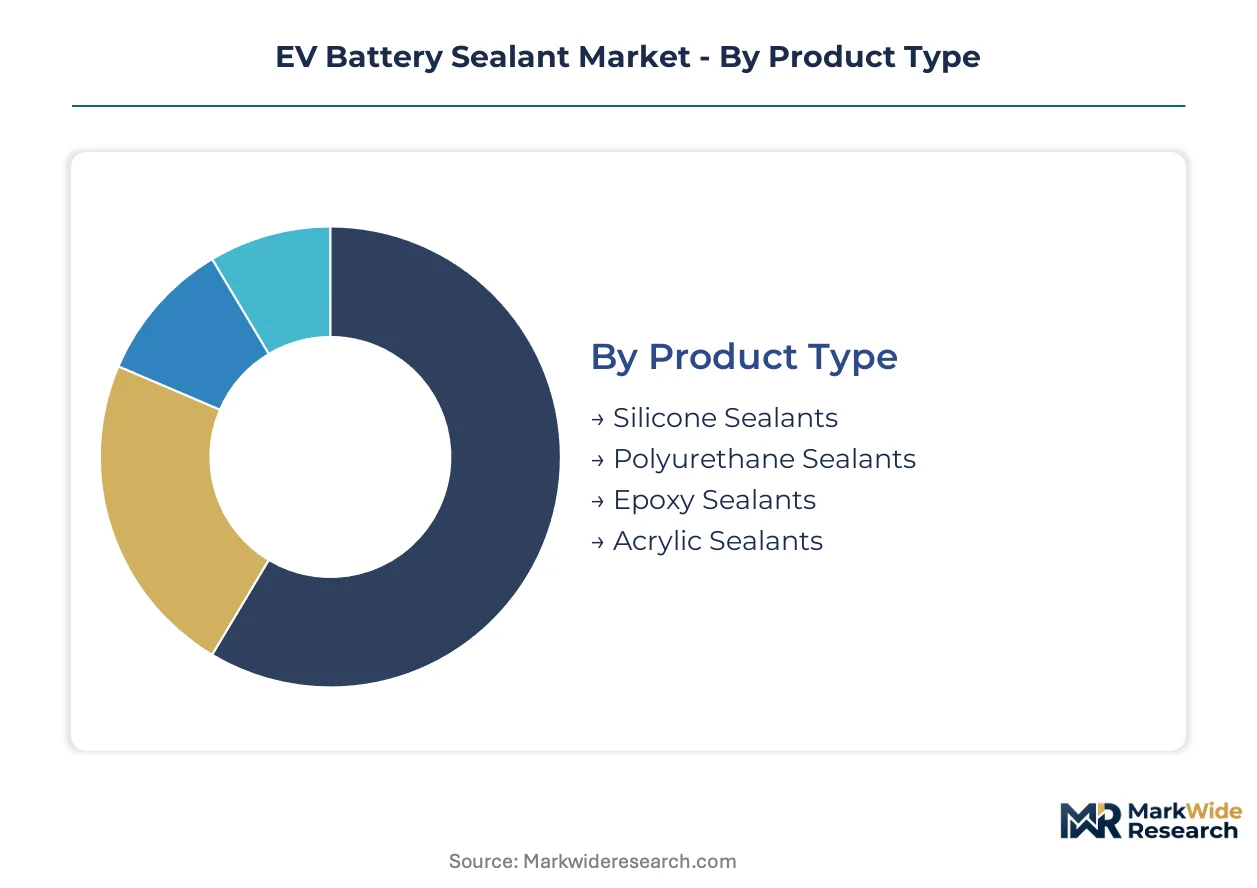
Sealant procurement patterns diverge sharply across product chemistries and customer tiers, with cell-to-pack integration collapsing traditional module-level specification layers into concentrated battery producer decisions. Understanding these segment boundaries reveals where formulation investments align with volume concentration versus where niche applications sustain premium pricing.
Product Type:
Customization intensity spans from commodity two-component systems to highly specified thermal-cycling formulations, with standardization pressure strongest in cost-sensitive module applications.
- Silicone Sealants:Formulated from siloxane polymers delivering thermal stability across minus 40 to 150 degrees Celsius with UL 94 V-0 flame retardancy. Demand concentrates in German automotive corridor OEMs specifying cell-to-pack architectures where heat dissipation and long service life override material cost. REACH authorization timelines for novel additives compress formulation refresh cycles for European suppliers.
- Polyurethane Sealants:Two-component systems curing through isocyanate-polyol reactions, favored where processing speed and material cost outweigh extreme temperature performance. Chinese battery manufacturers deploying cost-optimized module designs represent the fastest-expanding demand pool, pulled by NMPA GB standards enforcement requiring upgraded thermal propagation resistance.
- Epoxy Sealants:Rigid thermoset systems offering superior chemical resistance and structural adhesion for specific enclosure interfaces.
- Acrylic Sealants:UV-curable or moisture-cure formulations occupying niche applications requiring rapid processing and moderate thermal exposure.
Most installed capacity flows through silicone formulations. Expansion is steepest in polyurethane systems.
End User:
Customer concentration follows the dismantling of module-tier procurement, with specification authority migrating upstream to cell producers and downstream to platform engineering teams.
- Battery Manufacturers:CATL, BYD, and LG Energy Solution now dominate sealant procurement decisions as cell-to-pack integration eliminates intermediate module integrators. These producers specify direct cell-to-housing adhesion with enhanced thermal runaway suppression, demanding embedded technical service teams from sealant suppliers.
- Automakers:Volkswagen, BMW, and Mercedes-Benz platform engineering teams increasingly contract sealants directly for proprietary cell-to-pack designs, bypassing traditional tier-one relationships. German OEMs drive qualification programs with accelerated timelines to meet fleet compliance deadlines under EU Battery Regulation recycled content mandates.
- Tier-1 Suppliers:Module integrators seeing specification authority erode as battery producers internalize procurement for integrated pack designs.
- Aftermarket Providers:Service and repair channels for battery refurbishment and second-life applications, currently limited by sealed pack designs limiting field access.
Procurement volume concentrates at battery manufacturers. Direct OEM contracting is gaining share fastest.
Application:
Functional boundaries blur as multifunctional formulations consolidate previously discrete material layers, with hybrid specifications displacing single-function procurement.
- Sealing:Environmental isolation preventing moisture ingress and electrolyte leakage across cell-to-housing interfaces, specified with IP67+ ratings for high-vibration automotive environments.
- Thermal Management:Thermally conductive silicone formulations consolidating thermal interface and sealing functions into unified materials, compressing supplier tiers as thermal management specialists and sealant formulators compete for identical specification slots in cell-to-pack designs.
- Adhesion:Structural bonding of cells to pack housing replacing mechanical fasteners, specified for crashworthiness and manufacturing automation compatibility.
- Insulation:Dielectric stability maintenance across high-voltage cell assemblies, critical for fast-charging platforms where heat dissipation and electrical isolation must coexist.
Sealing commands the largest specification volume. Thermal management applications are expanding most quickly as hybrid formulations penetrate cell-to-pack designs.
Material:
Feedstock selection tracks the tension between thermal performance requirements and circular economy mandates, with recycled content thresholds forcing reformulation investments.
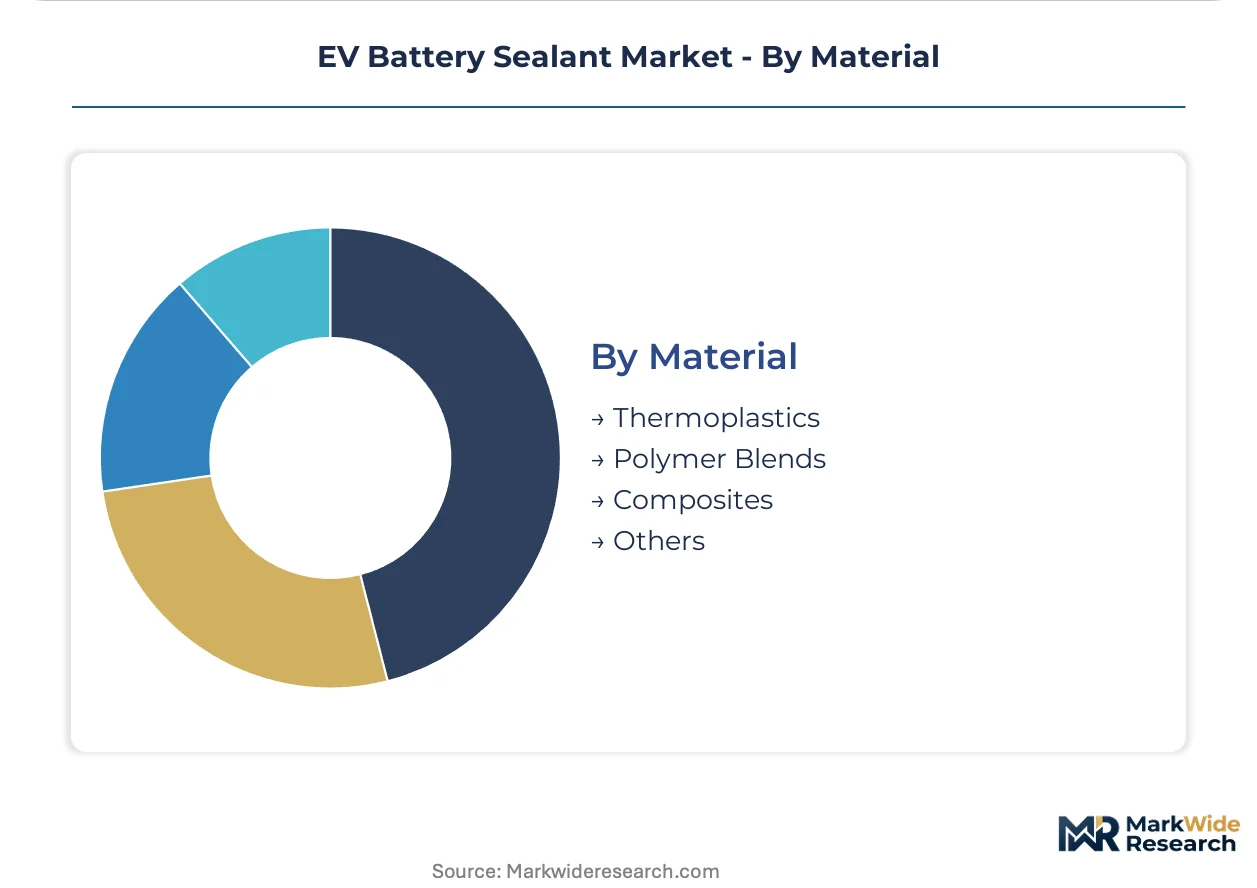
- Polymer Blends:Engineered combinations of silicone, polyurethane, and specialty additives achieving property profiles unobtainable from single-chemistry systems. German automotive OEMs drive qualification of bio-based blend components to satisfy EU Battery Regulation carbon footprint declarations.
- Thermoplastics:Melt-processable systems offering manufacturing efficiency for high-volume applications where thermal cycling demands are moderate.
- Composites:Mineral-filled or fiber-reinforced formulations enhancing mechanical properties and flame retardancy without restricted halogenated additives.
- Others:Emerging ceramic-polymer hybrids and solid-state interface materials for next-generation cell architectures.
Polymer blends carry the heaviest specification load. Composite formulations are climbing the fastest as REACH restrictions on legacy flame-retardant chemistries accelerate mineral filler adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor concentrates the most advanced cell-to-pack sealant specifications, with OEM platform engineering teams driving qualification programs for thermal runaway suppression materials.
China
CATL and BYD anchor domestic procurement decisions as cell-to-pack integration concentrates demand at the cell producer level. NMPA enforcement of GB standards for thermal propagation resistance pulls advanced formulation demand toward battery manufacturers. Shenzhen and Ningbo house the densest clusters of sealant technical service teams embedded within customer R&D facilities.
Germany
Volkswagen, BMW, and Mercedes-Benz platform engineering teams increasingly contract sealants directly for proprietary designs. KBA type-approval processes incorporate EU Battery Regulation recycled content thresholds into homologation requirements. Stuttgart and Munich host the primary supplier qualification centers where REACH-compliant bio-based chemistries undergo accelerated validation.
United States
Domestic battery giga-factories concentrate procurement for integrated pack designs requiring UL 94 V-0 flame retardancy. EPA and OSHA frameworks govern workplace chemical exposure during sealant compounding operations. Michigan and Tennessee manufacturing corridors attract technical service investments from European and Asian formulators seeking direct OEM relationships.
South Korea
LG Energy Solution and Samsung SDI drive specification authority upstream as module-tier procurement erodes. MFDS chemical safety assessments and KATS standards for automotive materials govern sealant import and use. Gyeonggi Province battery manufacturing complexes concentrate demand for silicone formulations with fast-charging thermal management properties.
India
Reliance and Ola Electric anchor emerging demand as PLI scheme incentives attract advanced chemistry cell manufacturing. BIS certification requirements for automotive materials create qualification barriers for imported formulations. Gujarat and Tamil Nadu giga-factory developments pull sealant suppliers toward localized compounding operations.
EV Battery Sealant Market Competitive Landscape
Direct OEM contracting dominates the current landscape as battery producers and automotive platform engineering teams bypass traditional tier-one module integrators. The supplier base stratifies between integrated chemical conglomerates with captive siloxane production and specialized formulators competing on application engineering proximity. Three archetypes prevail: thermal management specialists pivoting into hybrid sealant specifications, construction-adhesive players transferring structural bonding expertise, and regional compounders serving cost-optimized module designs. Capacity expansion and backward integration into siloxane feedstocks represent the primary competitive vectors.
Among German chemical conglomerates, Henkel AG & Co. KGaA and Wacker Chemie AG exemplify the integrated-formulator archetype with European OEM supply chain anchoring. Dow Inc. represents North American silicone chemistry leadership through in-house siloxane production control. Japanese specialists including Shin-Etsu Chemical Co., Ltd. occupy positions defined by materials science heritage and thermal stability formulation expertise. Sika AG and H.B. Fuller Company illustrate the construction-to-mobility transfer pattern, applying structural bonding capabilities to battery enclosure sealing specifications. These named entities serve as reference points for understanding competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Dow Inc. |
| Wacker Chemie AG |
| Bostik |
| Shin-Etsu Chemical Co., Ltd. |
| ITW Performance Polymers |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between UL 94 V-0 silicone formulations and commodity polyurethane systems manifests in both pricing power and supply chain configuration, with German OEMs paying premiums for REACH-compliant thermal cycling formulations while Chinese module producers optimize around NMPA GB standard thresholds.
Pricing Analysis
Siloxane feedstock volatility passes through directly to silicone sealant quotations, compressing margins for European formulators without captive precursor production. Three-tier pricing structure across premium, standard, and economy levels separates thermal-cycling-certified formulations from fast-cure polyurethanes and basic enclosure sealants. Pricing pressure stems from polyurethane substitution in cost-optimized module designs. Battery manufacturers exhibit highest price sensitivity, while direct OEM contracting teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight costs from East Asian siloxane corridors to European compounding facilities add 12-18% landed cost premiums versus regional sourcing. Manufacturing concentrates in China, Germany, and South Korea. Formulation chemistry draws from siloxane polymers, isocyanate systems, and phosphorous-nitrogen flame retardants. Single-source vulnerability sits with specialized silicone precursor supply chains clustered in East Asia. Distribution runs through direct technical service relationships with battery producers and OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's NMPA-accelerated qualification timelines and Europe's REACH compliance delays creates cost and speed differentials for sealant suppliers willing to dual-source R&D across regulatory jurisdictions.
For Market Incumbents: Deploy backward integration into siloxane feedstocks to defend margin position against East Asian precursor volatility. Establish embedded technical service teams within Stuttgart and Munich OEM R&D facilities to lock cell-to-pack specifications before platform finalization. Counter polyurethane substitution threat by accelerating multifunctional thermal-conductive formulation launches.
For New Entrants and Emerging Players: The 40-60% price-point gap between German OEM silicone specifications and Chinese module polyurethane systems opens entry paths for mid-tier hybrid formulations. Target India's PLI scheme giga-factory developments in Gujarat and Tamil Nadu, where localized compounding requirements outpace established supplier technical service deployment. Lead with fast-cure thermal management sealants certified to BIS standards.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing captive siloxane supply and existing automotive OEM relationships. Five-to-ten-year viability hinges on solid-state interface sealing capability development. Monitor qualification velocity at CATL and BYD for inflection signals on next-generation cell architecture sealant specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Captive precursor supply insulates European formulators from East Asian logistics bottlenecks and cost volatility. |
| Embedded Technical Service Deployment | Supplier teams co-located with BMW and Mercedes-Benz platform engineering accelerate cell-to-pack specification capture. |
| Multifunctional Thermal-Conductive Formulation Launch | Hybrid sealants consolidating thermal interface and sealing functions compress assembly steps for battery producers. |
| Localized Compounding in India | Domestic production serving Reliance and Ola Electric giga-factories satisfies PLI scheme local content requirements. |
| Solid-State Interface Sealing R&D Program | Ceramic electrolyte membrane and lithium metal anode compatibility positions suppliers for next-generation cell architectures. |
Research Methodology
Coverage spans China, Germany, the United States, South Korea, and India, with primary inputs from each market. The analysis combines structured interviews with battery manufacturer procurement directors, OEM platform engineers, sealant formulation chemists, and tier-one module integrators with secondary validation from NMPA GB standard filings, REACH authorization databases, customs trade records, and SEC 10-K disclosures. Bottom-up volume modeling triangulates against top-down market sizing across chemistry types and end-use segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across silicone, polyurethane, epoxy, and acrylic chemistries; battery manufacturer, automaker, tier-one, and aftermarket end users; sealing, thermal management, adhesion, and insulation applications; and polymer blend, thermoplastic, composite, and emerging material substrates. CAGRs derive from regression analysis of historical procurement patterns against cell-to-pack adoption curves and regulatory compliance timelines.
Caveats apply where NMPA enforcement intensity, REACH authorization delays, or solid-state cell commercialization timelines could materially shift the outlook. Forecasts reflect assumptions about thermal runaway suppression requirements and recycled content thresholds without certainty of regulatory finalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market