
 Substation Market | 2026-2036
Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Substation Market Intelligence
Modular substation packaging is broadening buyer choice across utility and industrial segments. ABB Ltd leverages its automation portfolio to compete in digitally integrated substation projects. Siemens Energy AG anchors European demand through its gas-insulated switchgear specialization. General Electric Company differentiates via protection relay systems and grid software integration.
A substation is an assembly of switchgear, transformers, busbars, and control systems operating at voltages from 11 kV to 765 kV, designed to transform voltage levels and distribute electrical power across transmission and distribution networks. Gas-insulated substations command premium positioning due to compact footprint requirements in dense urban corridors, while modular substations represent the fastest-growing configuration as utilities seek factory-tested, rapid-deploy solutions for renewable energy integration. Monitoring solutions within the technology dimension are deepening margin pools as predictive maintenance contracts extend equipment lifecycles.
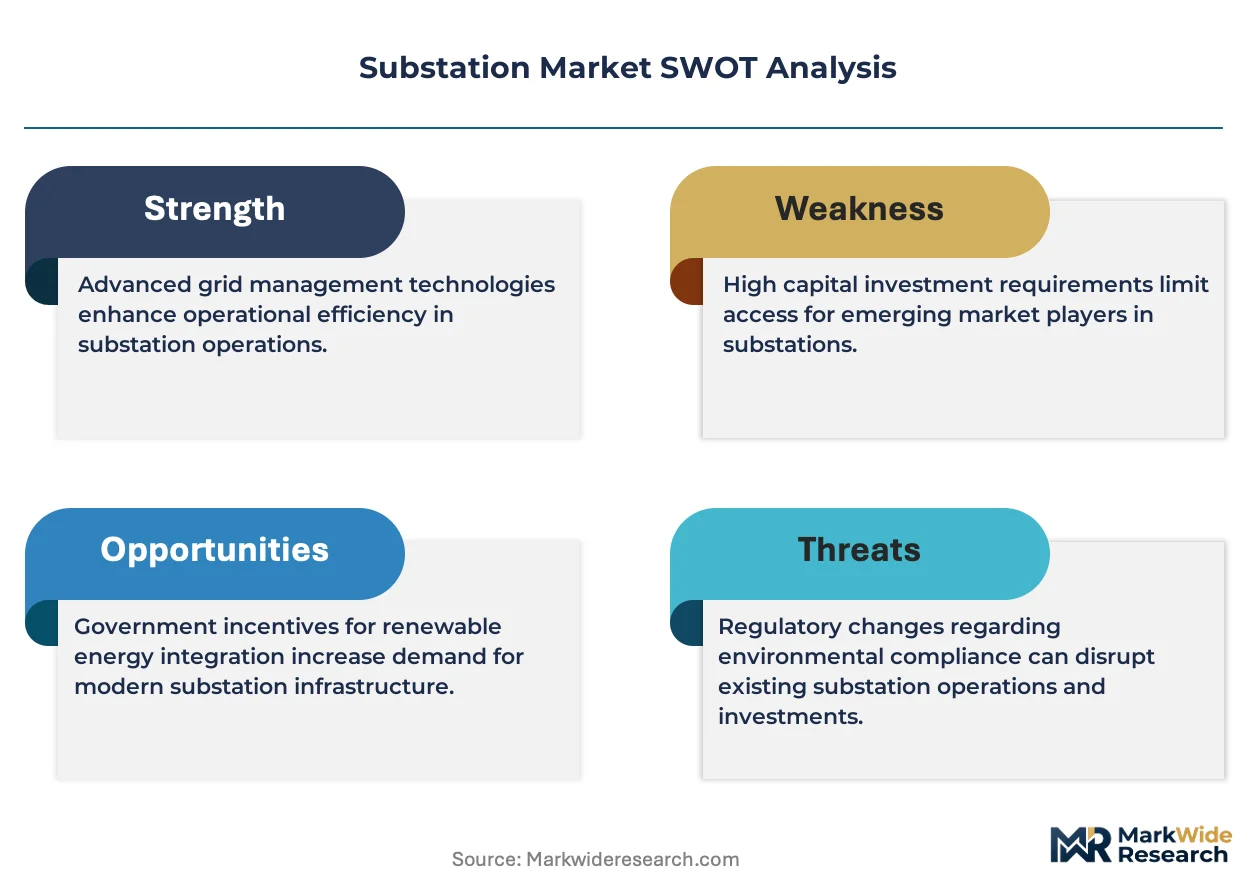
FERC Order 2222 in the United States and the EU Green Deal framework are reshaping substation procurement by mandating distributed energy resource interoperability and carbon footprint disclosure in equipment supply chains. India's CEA grid codes and China's GB standards for ultra-high voltage transmission are accelerating domestic manufacturing scale. Stakeholders must weigh standardization against customization as regulatory divergence across jurisdictions complicates platform economics for multinational suppliers.
Market Dynamics
Grid-edge digitalization is forcing utilities to reengineer substation architectures around distributed energy resource interoperability rather than centralized hub-and-spoke topologies. This structural pivot compresses traditional equipment procurement cycles while elevating software-integrated platforms.
Growth Catalysts
- FERC Order 2222:This US mandate requires wholesale market participation from distributed energy aggregators, compelling utilities to deploy interoperable substation automation systems capable of bidirectional power flow management.
- Data center electrification:Hyperscale computing clusters in Northern Virginia, Frankfurt, and Singapore are driving 765 kV transmission expansion that demands compact gas-insulated switchgear with sub-50ms fault clearance.
- EU Green Deal carbon border adjustments:Equipment manufacturers face embedded emissions disclosure requirements that favor suppliers with low-carbon steel transformer cores and SF6-free insulation alternatives.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer core material costs fluctuate with mining output constraints in Chile and Indonesia, compressing OEM margins on fixed-price utility contracts.
- SF6 gas phase-down timelines:The EU F-Gas Regulation mandates 67% reduction in fluorinated gas use by 2030, stranding capital in conventional gas-insulated switchgear production lines.
- Ultra-high voltage ceramic insulator concentration:Manufacturing of 800 kV+ bushings concentrates among Japanese and German specialists, creating single-source vulnerabilities for emerging market utilities.
Strategic Opportunities
- India's transmission buildout:The country's Green Energy Corridors program requires 66 kV and 220 kV modular substations for solar park evacuation, favoring factory-integrated solutions over site-built alternatives.
- Digital twin convergence:Integration of physics-based asset modeling with SCADA telemetry enables predictive maintenance contracts that extend equipment lifecycles beyond traditional 30-year depreciation schedules.
- Direct procurement by renewable developers:Wind and solar IPPs are bypassing utility intermediaries to source containerized substations through EPC contractors, opening channel alternatives to traditional distribution.
Industry Challenges
- Protection engineer scarcity:Specialized expertise in IEC 61850 protocol configuration and relay coordination is concentrating among aging utility workforces in Germany and Japan.
- Legacy electromechanical system integration:Utilities in the United States and Italy face technical debt from 1970s-vintage substations that resist retrofit with modern IEC-compliant automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Substation Market |
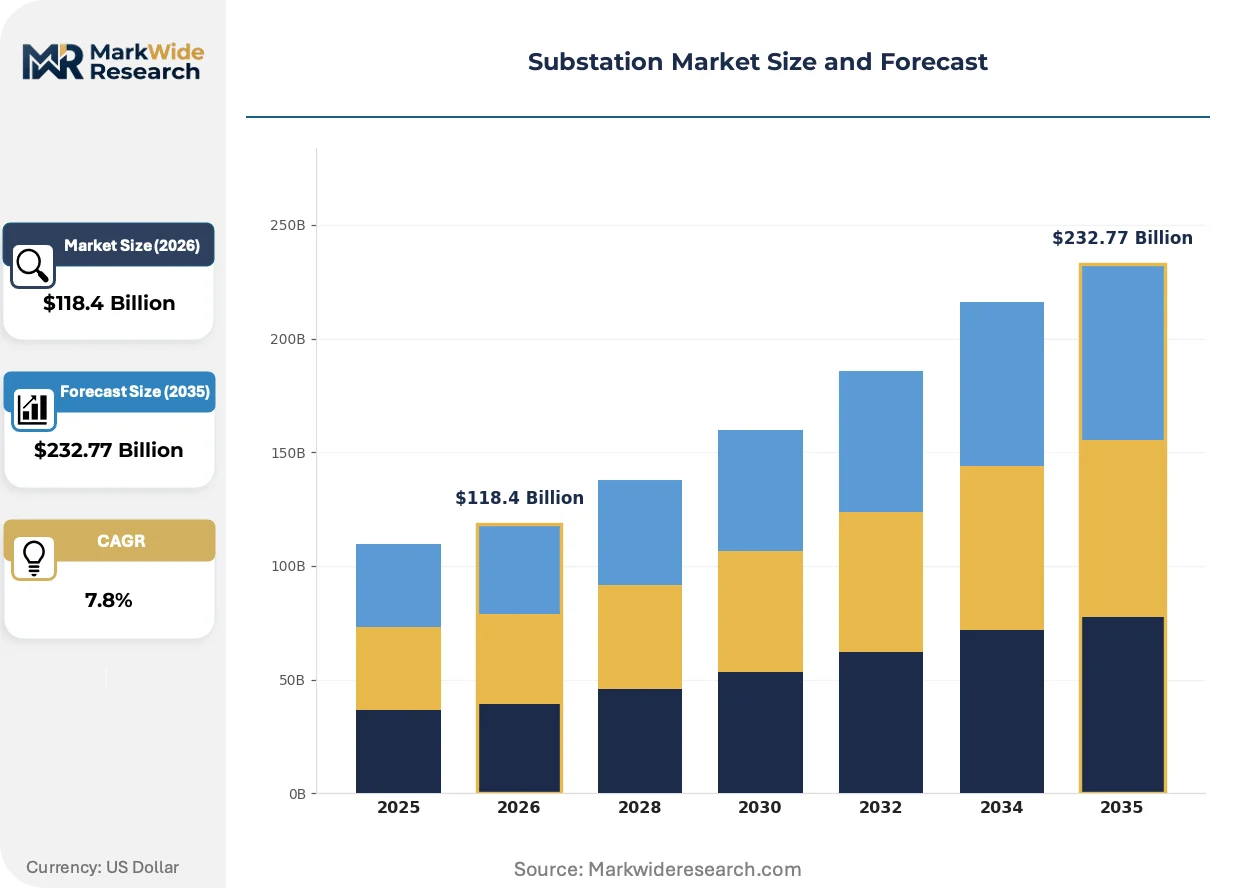
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Insulated Substation, Air-Insulated Substation, Hybrid Substation, Modular Substation Technology: Automation Technology, Protection Relay Systems, Control Systems, Monitoring Solutions End User: Utilities, Industrial Users, Renewable Energy Companies, Government Agencies Application: Power Distribution, Voltage Regulation, Grid Integration, Renewable Energy Integration |
| Companies Covered | General Electric Company, Toshiba Energy Systems & Solutions Corporation, ABB Ltd, Eaton Corporation plc, Mitsubishi Electric Corporation, Siemens Energy AG, Hitachi Energy Ltd, Hyosung Heavy Industries Corporation, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Substation Market Strategic Shifts & Innovations
Substation technology is pivoting from passive hardware assemblies to software-defined grid nodes capable of autonomous voltage regulation and fault isolation. This transformation elevates digital architecture decisions above traditional equipment specifications in procurement evaluations.
Digital substation platforms built on IEC 61850-9-2LE process bus architectures are decentralizing protection and control functions from centralized relay houses to intelligent electronic devices distributed throughout the yard. European transmission operators in Germany and Denmark are deploying these systems at 400 kV levels with 4ms sample rates. The shift is compressing copper control cable runs by 80% while enabling centralized substation engineering from remote design centers.
The EU F-Gas Regulation and US EPA voluntary partnership programs are accelerating SF6-free insulation technology transitions toward fluoronitrile and vacuum interrupter alternatives. Industrial consequence includes recertification of entire product lines and retraining field service technicians on new gas handling protocols. GIS manufacturers in Switzerland and Germany are responding with modular platform designs that accommodate both legacy and next-generation insulation media within common enclosures.
Utility procurement departments are unbundling equipment supply from engineering-procurement-construction contracts, creating direct vendor relationships for transformers and switchgear that bypass traditional EPC intermediaries. This disintermediation is most visible in Australia's renewable zone developments and Texas ERCOT interconnection queues, where developers seek factory-tested modular solutions with compressed delivery timelines independent of turnkey contractor schedules.
Substation Market Segmentation
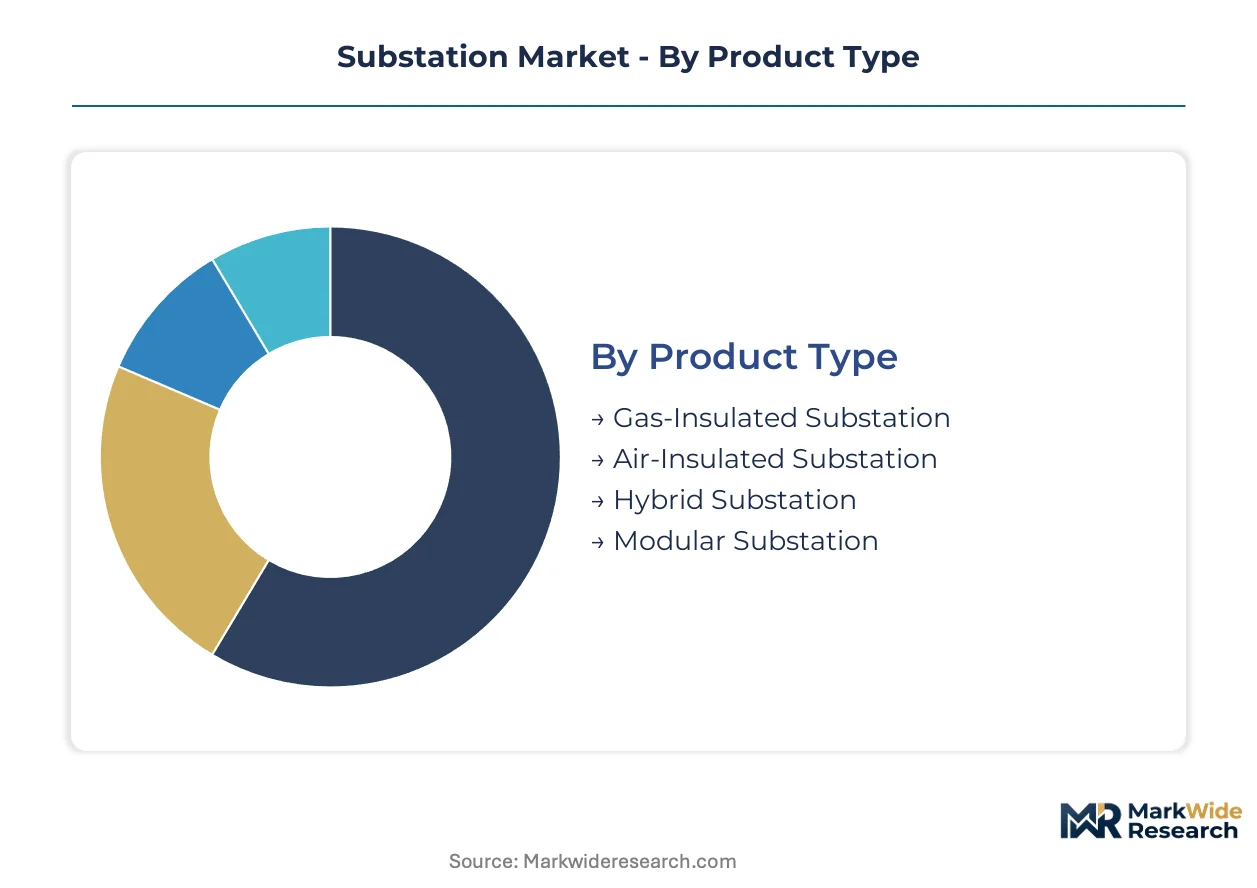
Substation procurement patterns diverge sharply between utilities seeking integrated turnkey systems and industrial buyers prioritizing standalone modularity. Understanding these integration-depth distinctions enables suppliers to align factory configurations with divergent customer engineering workflows.
Product Type:
Integration depth varies from fully embedded gas-insulated systems requiring minimal site civil works to standalone modular packages that function as independent grid nodes.
- Gas-Insulated Substation:SF6 or fluoronitrile-filled switchgear assemblies achieve 80% footprint reduction versus air-insulated equivalents through compact phase encapsulation. Demand concentrates in Singapore, Frankfurt, and Northern Virginia where urban land scarcity and 765 kV data center interconnection requirements command premium positioning despite higher capital cost.
- Modular Substation:Factory-integrated transformer-switchgear-control packages ship as containerized or skid-mounted units enabling 12-week deployment versus 18-month site-built schedules. India's Green Energy Corridors program and Texas ERCOT interconnection queues are absorbing containerized 66 kV and 220 kV configurations for solar park evacuation.
- Air-Insulated Substation:Conventional open-yard designs with porcelain insulators and bare conductor buswork dominate rural transmission expansion in lower-density markets where land availability offsets footprint disadvantages.
- Hybrid Substation:Mixed technology configurations combine gas-insulated switchgear bays with air-insulated bus sections, balancing urban footprint constraints against capital budget limitations in secondary cities.
Air-insulated substations lead volumes today; modular substations are gaining share fastest.
Technology:
Cost stratification separates high-margin software-defined platforms from commodity hardware components, with automation commanding 3-4x hardware pricing multiples.
- Automation Technology:IEC 61850-compliant process bus architectures decentralize protection functions to intelligent electronic devices, enabling remote engineering centers to configure 400 kV substations without site presence. German and Danish transmission operators are deploying these systems with 4ms sample rates, compressing copper control cable runs by 80%.
- Monitoring Solutions:Predictive maintenance platforms integrating dissolved gas analysis, thermal imaging, and partial discharge detection extend transformer lifecycles beyond 30-year depreciation schedules. These systems generate recurring revenue streams through SaaS telemetry contracts that deepen supplier margin pools.
- Protection Relay Systems:Microprocessor-based fault detection and isolation devices coordinate with SCADA for sub-50ms clearance times required by hyperscale data center interconnection standards.
- Control Systems:Human-machine interface platforms and bay controllers manage local operations, representing mature technology with limited differentiation beyond cybersecurity certification levels.
Protection relay systems anchor current procurement volumes; monitoring solutions are expanding most quickly.
End User:
Customer type determines specification authority, with utilities retaining centralized engineering standards while renewable developers exercise direct procurement autonomy.
- Utilities:Vertically integrated transmission and distribution operators in India, China, and the United States specify equipment through centralized procurement frameworks that emphasize 40-year asset lifecycles and interoperability with legacy SCADA infrastructure.
- Renewable Energy Companies:Wind and solar independent power producers bypass utility intermediaries to source containerized substations through EPC contractors, compressing delivery timelines and favoring factory-tested modular solutions over site-built alternatives.
- Industrial Users:Mining, petrochemical, and manufacturing facilities procure dedicated substations for captive power quality management, prioritizing arc flash containment and harmonic filtering over grid-scale voltage transformation.
- Government Agencies:Public infrastructure and defense installations specify hardened substations with electromagnetic pulse protection and physical security features exceeding commercial utility standards.
Utilities dominate absolute volumes; renewable energy companies are climbing the fastest.
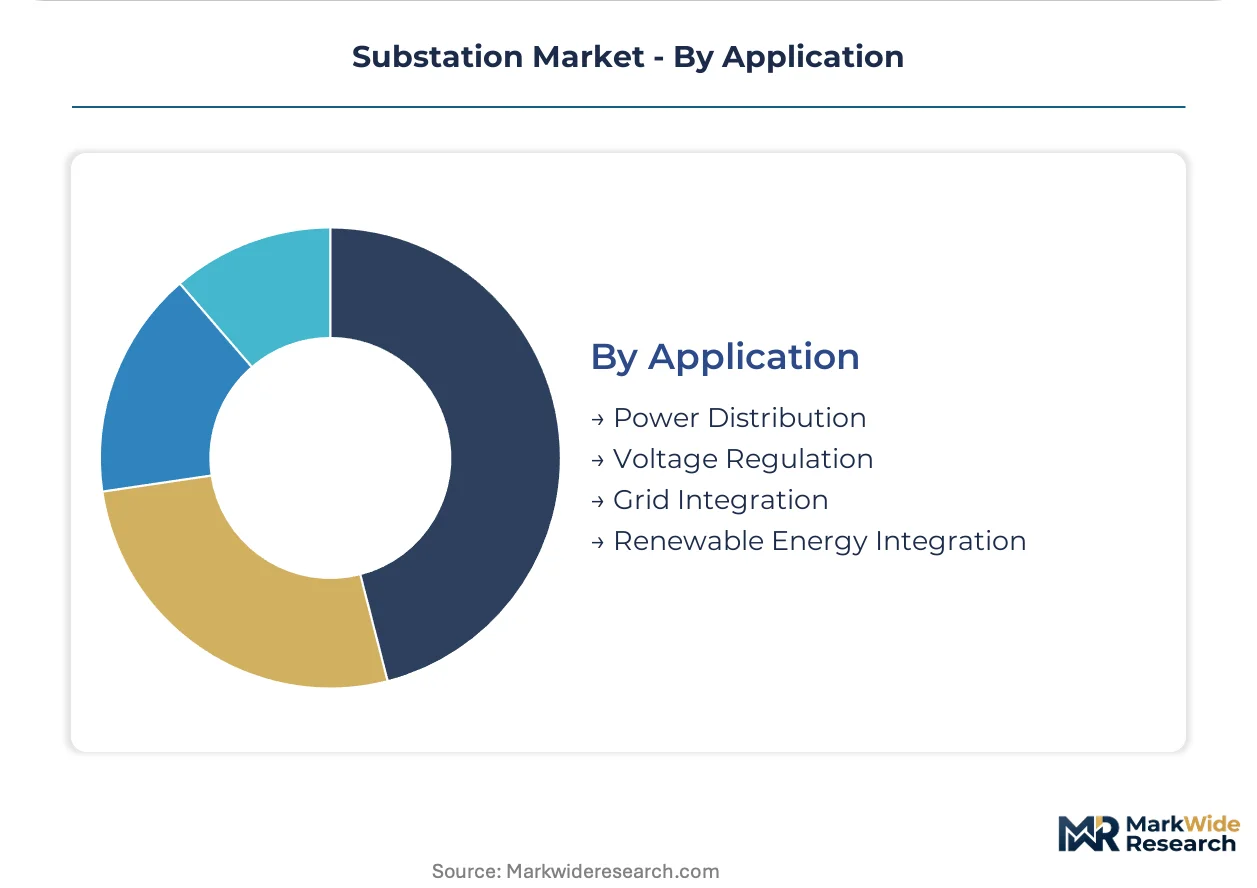
Application:
Maturity gradients separate established power distribution functions from emerging grid integration requirements shaped by distributed energy resource penetration.
- Renewable Energy Integration:Bidirectional power flow management and voltage ride-through capabilities accommodate solar and wind variability, requiring substation automation systems compliant with FERC Order 2222 interoperability mandates. These applications command engineering intensity premiums as utilities reconfigure architectures around distributed rather than centralized generation.
- Grid Integration:Interconnection of distributed energy aggregators and storage systems demands real-time telemetry and autonomous voltage regulation, representing the steepest expansion trajectory as electrification accelerates across transport and heating sectors.
- Power Distribution:Conventional load serving through radial or looped feeders remains the foundational application, with specifications standardizing around IEC and IEEE frameworks.
- Voltage Regulation:On-load tap changer control and reactive power compensation maintain power quality within statutory limits, functioning as embedded capabilities within broader substation platforms rather than standalone procurement categories.
Power distribution leads installed base; renewable energy integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substation engineering originated in Germany and Switzerland during the early high-voltage transmission era of the 1920s. Today's procurement geography reflects that technical lineage while expanding into high-growth electrification corridors across Asia and North America.
United States
FERC Order 2222 mandates wholesale market participation from distributed energy aggregators, forcing utilities to deploy interoperable automation systems for bidirectional power flow. The EPA maintains voluntary partnership programs encouraging SF6-free insulation transitions. Northern Virginia's hyperscale data center clusters drive 765 kV transmission expansion requiring compact gas-insulated switchgear with sub-50ms fault clearance.
China
State Grid Corporation's ultra-high voltage transmission buildout under GB standards accelerates domestic manufacturing scale for 800 kV+ equipment. The dual carbon goals framework imposes emissions intensity benchmarks on transformer production. The Yangtze River Delta manufacturing belt concentrates ceramic insulator and bushing fabrication for export markets.
India
Green Energy Corridors program procurement targets 66 kV and 220 kV modular substations for solar park evacuation, favoring factory-integrated solutions. CEA grid codes mandate interoperability standards for renewable interconnection that reshape equipment specifications. Gujarat's renewable energy zones absorb containerized substations through direct developer procurement bypassing traditional utility channels.
Germany
The EU F-Gas Regulation mandates 67% reduction in fluorinated gas use by 2030, stranding capital in conventional gas-insulated switchgear lines and accelerating SF6-free transitions. Siemens Energy AG anchors European demand through gas-insulated switchgear specialization. The Ruhr industrial corridor hosts retrofit projects integrating digital twin platforms with legacy 400 kV infrastructure.
Japan
METI's grid modernization directives emphasize earthquake-resilient substation designs for critical infrastructure. Manufacturing of 800 kV+ ceramic bushings concentrates among domestic specialists, creating supply vulnerabilities for emerging market utilities. The Kansai region's industrial belt maintains precision fabrication capacity for ultra-high voltage insulators serving global transmission projects.
Substation Market Key Industry Players
Premium-margin players sit above commodity-margin players across the digital integration and factory-tested modular packaging dimensions. The vendor base organizes into three tiers: integrated automation-platform providers, gas-insulated switchgear specialists, and modular packaging fabricators. Strategic archetypes include full-spectrum platform vendors, component specialists with deep insulation expertise, and rapid-deployment modular integrators. Dominant competitive moves encompass portfolio diversification into predictive maintenance software and geographic expansion through regional EPC partnerships.
Within the integrated automation tier, ABB Ltd leverages its automation portfolio to compete in digitally integrated substation projects. Siemens Energy AG anchors European demand through its gas-insulated switchgear specialization. General Electric Company differentiates via protection relay systems and grid software integration, representing the North American platform vendor archetype.
| Leading Market Players |
|---|
| General Electric Company |
| Toshiba Energy Systems & Solutions Corporation |
| ABB Ltd |
| Eaton Corporation plc |
| Mitsubishi Electric Corporation |
| Siemens Energy AG |
| Hitachi Energy Ltd |
| Hyosung Heavy Industries Corporation |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Captive production of grain-oriented electrical steel cores anchors both supply security and pricing power for transformer manufacturers serving fixed-price utility contracts. Copper winding procurement and SF6 gas handling capabilities concentrate among vertically integrated European and Japanese specialists, compressing margins for second-tier fabricators exposed to commodity volatility.
Pricing Analysis
Project-based long-term contracting dominates substation procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by IEC 61850 compliance grade and factory integration depth. Cost compression in standard air-insulated configurations is intensifying because Chinese and Indian domestic manufacturers scale 220 kV production. Renewable developers exhibit highest price sensitivity, while data center operators absorb premium positioning for sub-50ms fault clearance specifications.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for 800 kV+ ceramic bushings and gas-insulated switchgear modules. Manufacturing draws from Chilean copper cathode, Indonesian nickel for stainless transformer tanks, and German grain-oriented silicon steel. Single-source vulnerability concentrates in ultra-high voltage insulator fabrication. Distribution runs through EPC contractor networks and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance software attach rates and SF6-free insulation transitions that command engineering premiums. Factory integration depth separates profitable from commoditized positioning.
For Market Incumbents: Acquire predictive analytics platforms to deepen recurring revenue from transformer monitoring contracts. Siemens Energy AG and ABB Ltd should accelerate SF6-free product line recertification before EU F-Gas Regulation deadlines strand conventional gas-insulated switchgear capacity. Backward integration into low-carbon steel transformer core supply insulates margins from mining output constraints in Chile and Indonesia.
For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for IEC 61850-compliant automation specialists to bypass incumbent hardware relationships through software-first positioning. India's Green Energy Corridors program offers the most penetrable geography for containerized modular substation fabricators. Target direct procurement relationships with renewable IPPs in Gujarat and Rajasthan through EPC contractor partnerships.
For Investors and Strategic Acquirers: Roll-up economics work for digital substation software specialists because protection engineering expertise concentrates among aging utility workforces in Germany and Japan. Five-to-ten year viability hinges on automation platform consolidation. Monitor IEC 61850 deployment velocity at 400 kV levels as inflection indicator for software-defined grid node adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Insulation Transition | EU F-Gas Regulation mandates 67% fluorinated gas reduction, favoring fluoronitrile and vacuum interrupter alternatives. |
| Predictive Maintenance Platform Launch | Dissolved gas analysis and thermal imaging SaaS contracts extend transformer lifecycles beyond depreciation schedules. |
| Modular Factory Integration | Containerized 66 kV and 220 kV configurations compress deployment from 18 months to 12 weeks for solar evacuation. |
| Digital Twin Convergence | Physics-based asset modeling with SCADA telemetry enables remote engineering centers to configure substations without site presence. |
| Direct IPP Procurement Channel | Wind and solar developers bypass utility intermediaries, opening alternative distribution to traditional EPC networks. |
Research Approach
Direct dialogue with utility planning officers, renewable IPP project developers, EPC procurement leads, and grid automation engineers grounded the qualitative foundation. Secondary validation drew from FERC filings, EIA transmission project databases, IEA electrification outlooks, and CEA Green Energy Corridor procurement records. Bottom-up equipment shipment tallies triangulated against top-down transmission investment forecasts across the analysis window.
Segmented outputs by product type, technology tier, end-user category, and application domain calibrated the projection framework. CAGRs derived from regression analysis of historical procurement volumes against regulatory mandate timelines and data center buildout schedules. Modeled inputs included copper and grain-oriented electrical steel price trajectories, plus SF6 phase-down compliance costs.
Revisions become necessary when commodity price volatility exceeds modeled bands or when EU F-Gas Regulation enforcement accelerates beyond baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Europe Electric Radiators Market