
 Seawater Condensers Market | 2026-2036
Seawater Condensers Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Condensers Market Analytics
Modular skid-mounted configurations is recalibrating buyer choice in the seawater condensers space, as project developers seek factory-tested units that slash on-site welding and commissioning cycles. Alfa Laval leverages its Baltic Sea manufacturing footprint to dominate European retrofit demand for coastal power stations. GEA Group anchors its position through specialized titanium-clad tube bundles that withstand Red Sea salinity extremes. Siemens Energy competes on integrated thermal-electric hybrid architectures that trim auxiliary power draw in Middle Eastern installations.
Seawater condensers are heat-exchange devices engineered to reject thermal energy into marine environments, typically constructed from corrosion-resistant alloys such as titanium, super-austenitic stainless steels, or copper-nickel alloys with 70-30 composition to endure chloride-induced pitting at flow velocities exceeding 2.5 m/s. Their primary industrial purpose centers on condensing exhaust steam from turbine cycles in coastal power generation and driving multi-effect distillation in thermal desalination trains. Shell and tube configurations occupy the largest installed base due to decades of operational precedent in baseload plants, though plate-type designs are capturing share in space-constrained offshore platforms where footprint reduction commands premium pricing. Hybrid thermal-electric technology segments are expanding fastest as operators seek load-flexible systems that arbitrage between electricity export and freshwater production.
EPA cooling water intake regulations under Section 316(b) of the Clean Water Act compel US coastal facilities to retrofit with closed-cycle condenser circuits or risk operational curtailment. EMA corrosion protection standards and REACH material compliance frameworks govern alloy selection and coating chemistries for European marine heat exchange equipment. Saudi Arabia's SFDA and its national water regulator enforce material traceability protocols for desalination condensers that feed municipal supply networks. Stakeholders must monitor how tightening marine environmental protections in the Red Sea and Gulf regions reshape material specifications and retrofit timelines for existing installed capacity.
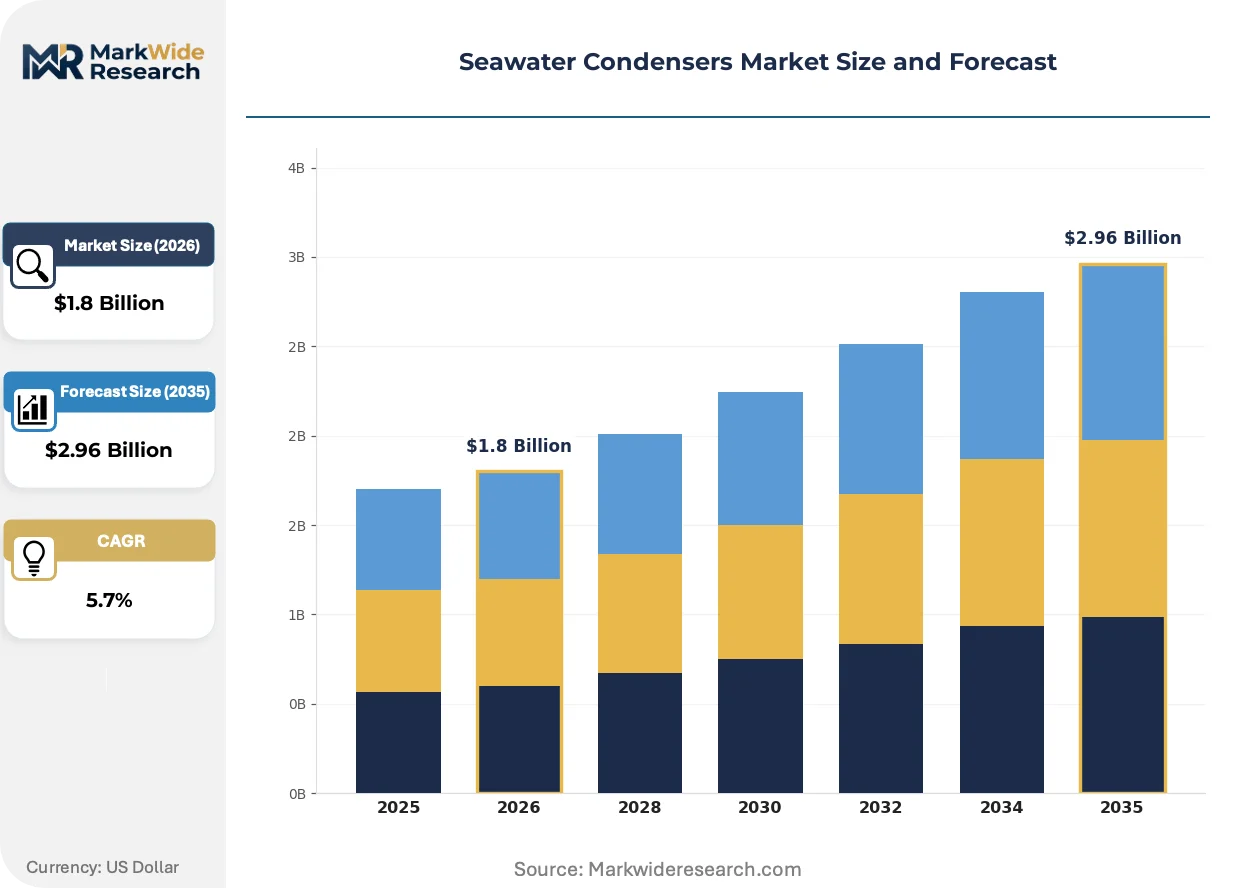
Market Dynamics
Modular skid-mounted configurations are recalibrating procurement patterns across coastal power and desalination sectors, compressing commissioning timelines and shifting supplier selection criteria toward factory-tested integration capabilities.
Growth Catalysts
- Gigascale desalination buildouts:Saudi Arabia's national water regulator is mandating corrosion-resistant condenser fleets for municipal supply networks, pulling titanium-clad tube demand.
- EU Green Deal industrial decarbonization:The framework is reshaping equipment procurement standards for marine thermal systems across European coastal installations.
- Hybrid thermal-electric architectures:These systems enable load-flexible operation that arbitrages between electricity export and freshwater production in Middle Eastern facilities.
Market Restraints
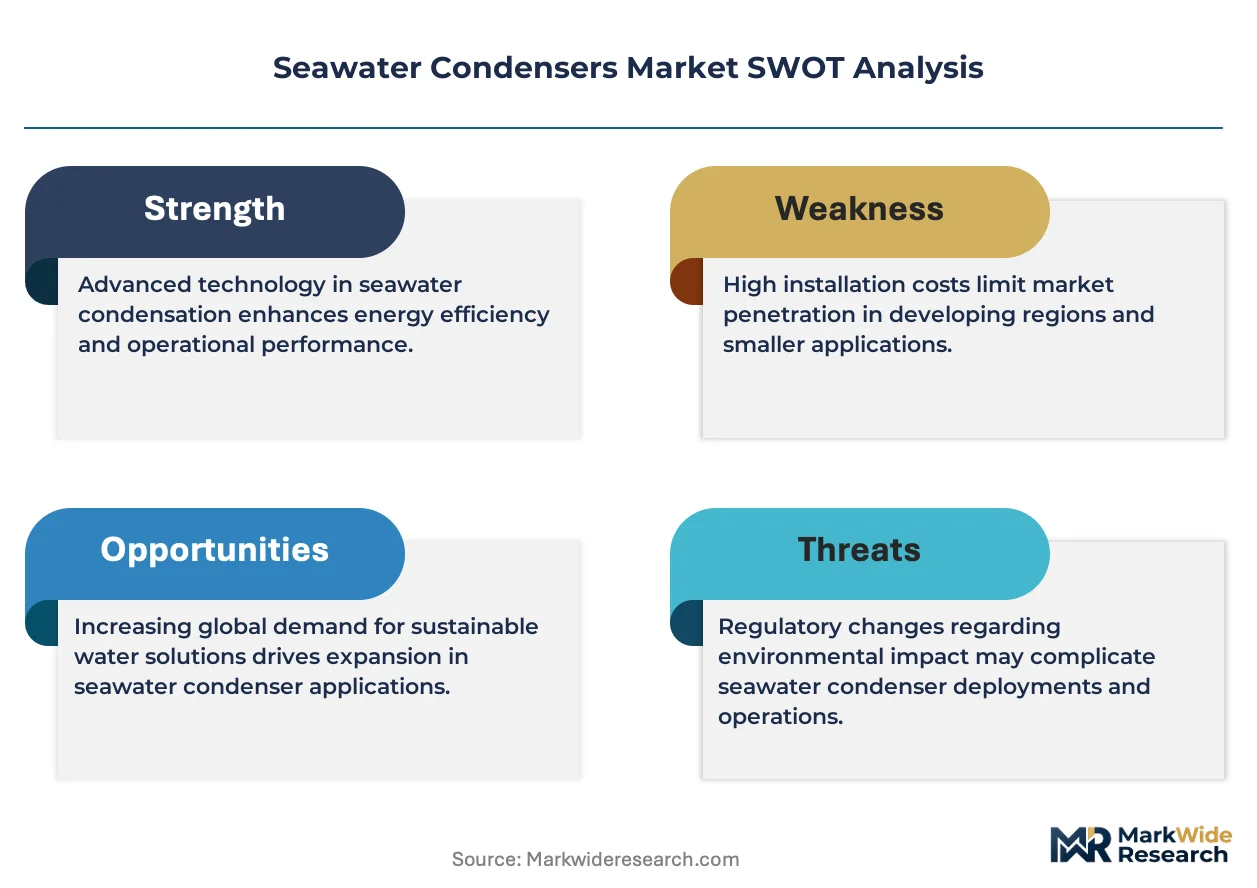
- Titanium price volatility:Super-austenitic stainless steel and copper-nickel alloy feedstock costs fluctuate with mining supply disruptions from Southeast Asian concentrate producers.
- Specialized fabricator concentration:Baltic Sea and Red Sea manufacturing clusters control critical tube bundle production capacity, creating geographic supply risk.
- EPA Section 316(b) compliance friction:US coastal facilities face retrofit capital burdens or operational curtailment risks from closed-cycle condenser circuit mandates.
Strategic Opportunities
- Offshore platform footprint reduction:Plate-type designs command premium pricing in space-constrained North Sea installations where weight and volume constraints dominate.
- EMA corrosion protection standardization:REACH material compliance frameworks are creating certified-supplier preference windows for European marine heat exchange equipment.
- Red Sea environmental protection tightening:Marine ecosystem safeguards are accelerating replacement cycles for existing installed capacity across Egyptian and Saudi coastal zones.
Industry Challenges
- Clad tube welding certification:ASME Section IX qualified welders for titanium-steel dissimilar metal joints remain scarce in Atlantic basin fabricator networks.
- Legacy shell-and-tube integration:Baseload plant operators face thermal performance mismatches when retrofitting hybrid architectures into decades-old steam turbine trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Condensers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air-Cooled, Double Pipe Technology: Thermal Energy, Electrical Energy, Mechanical Energy, Hybrid Systems End User: Power Plants, Desalination Plants, Marine Operations, HVAC Systems Installation Method: Onshore, Offshore, Fixed, Modular |
| Companies Covered | Alfa Laval, SPX Corporation, GEA Group, Siemens Energy, Mitsubishi Heavy Industries, Andritz AG, General Electric, KSB SE & Co. KGaA, Doosan Heavy Industries & Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Condensers Market Evolving Landscape
Factory-integrated condenser modules are compressing project delivery schedules while digital twin commissioning tools reshape acceptance protocols for marine heat exchange assets.
Additive-manufactured tube sheet geometries with optimized flow distribution patterns are unifying thermal performance and mechanical reliability in high-velocity seawater applications. Desalination plant developers in the Persian Gulf are specifying these configurations for newbuild trains. The technology is unifying previously separate design-for-manufacturing and design-for-operations workflows into single digital thread deliveries.
REACH authorization requirements for chromium(VI) coatings in marine environments are forcing alloy substitution toward super-austenitic grades in European coastal power stations. The restriction compounds existing supply tightness for corrosion-resistant materials. Shell-and-tube fabricators serving North Sea markets are accelerating plasma-sprayed ceramic coating qualification programs to maintain coating chemistries within compliance boundaries.
Lifecycle service contracting is displacing transactional spare parts purchasing among Middle Eastern independent water and power producers. Operators in the UAE and Saudi Arabia are bundling twenty-year tube replacement and retubing commitments into original equipment procurement. This model concentrates vendor selection power with integrated service-capable suppliers and compresses pure equipment margins for non-integrated competitors.
Seawater Condensers Market Segmentation
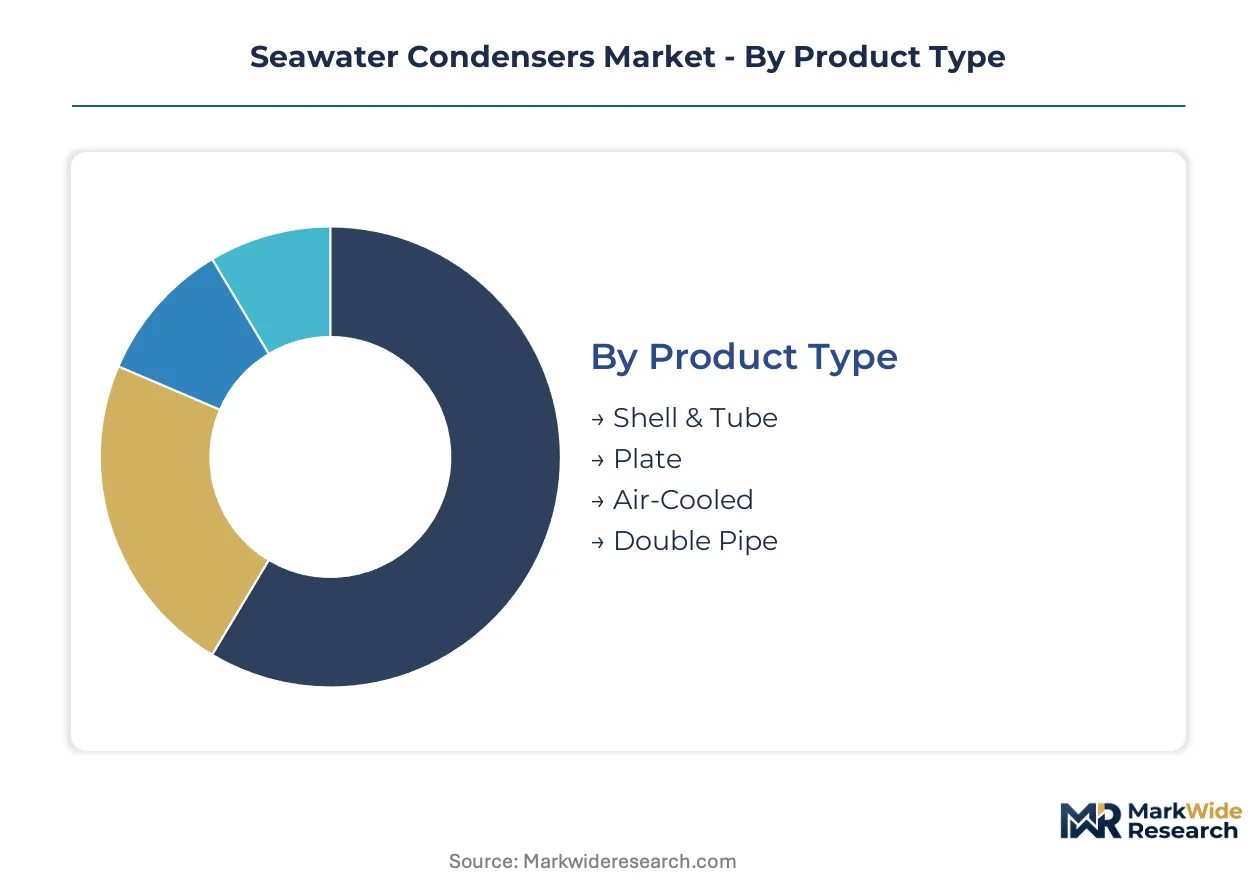
Seawater condenser procurement patterns diverge sharply between baseload infrastructure operators seeking decades-long reliability and project developers prioritizing deployment velocity. Alloy selection, configuration geometry, and integration architecture each command distinct supplier ecosystems and certification pathways.
Product Type:
Customization intensity spans from fully bespoke tube bundle geometries for legacy turbine retrofits to standardized plate packs for offshore platform skids.
- Shell & Tube:Cylindrical pressure vessels containing tube bundles arranged for counter-current heat exchange, typically fabricated from titanium or copper-nickel alloys. Demand concentrates in Saudi Arabian gigascale desalination projects where corrosion resistance under extreme chloride exposure determines fleet procurement. The configuration dominates installed capacity due to operational precedent in coastal power generation.
- Plate:Stacked corrugated metal plates forming alternating flow channels, delivering footprint reductions up to 75% versus shell-tube equivalents. North Sea offshore platforms specify these units where deck space and weight constraints override capital cost premiums. Demand is climbing fastest among floating production operators.
- Air-Cooled:Finned-tube arrays eliminating direct seawater contact, deployed where marine environmental regulations prohibit open-loop cooling. Coastal California power stations facing EPA Section 316(b) mandates represent primary uptake.
- Double Pipe:Concentric tube-in-tube construction for low-flow auxiliary cooling circuits. Chemical tankers and small-scale marine HVAC applications constitute the addressable base.
Leading the category by volume: Shell & Tube. Expanding most quickly: Plate configurations.
Technology:
Energy conversion modality determines whether condensers function as passive heat rejection surfaces or active thermal-electric arbitrage nodes.
- Thermal Energy:Conventional steam-condensing operation driven by turbine exhaust enthalpy. Baseload plants across Egypt and Saudi Arabia anchor replacement demand as aging tube bundles approach end-of-design-life.
- Electrical Energy:Motor-driven auxiliary cooling with integrated variable frequency drives for load matching. UAE independent water and power producers specify these for dispatch flexibility in grid-connected desalination.
- Mechanical Energy:Direct-drive configurations coupling turbine shafts to cooling water pumps without electrical conversion losses. Retrofit complexity limits adoption to greenfield installations.
- Hybrid Systems:Integrated thermal-electric architectures enabling real-time switching between electricity export and freshwater production modes. Persian Gulf developers are specifying these for load-following independent power projects.
Dominant by installed base: Thermal Energy. Steepest expansion trajectory: Hybrid Systems.
End User:
Customer technical sophistication ranges from multinational utilities with in-house welding certification programs to municipal water authorities outsourcing complete lifecycle service.
- Power Plants:Coastal steam turbine installations requiring continuous heat rejection at condensing pressures below 0.1 bar. European operators under EU Green Deal decarbonization timelines are accelerating retrofit procurement.
- Desalination Plants:Multi-effect distillation and multi-stage flash trains where condenser performance directly determines freshwater yield. Saudi Arabia's national water regulator mandates material traceability for all municipal supply network equipment.
- Marine Operations:Propulsion system cooling and cargo temperature control aboard tankers and LNG carriers. Classification society rules from Lloyd's Register and DNV govern fabrication standards.
- HVAC Systems:District cooling networks in coastal cities where seawater serves as heat sink for absorption chillers. Singapore and Dubai installations represent concentrated demand pockets.
Largest procurement volume: Power Plants. Gaining share fastest: Desalination Plants.
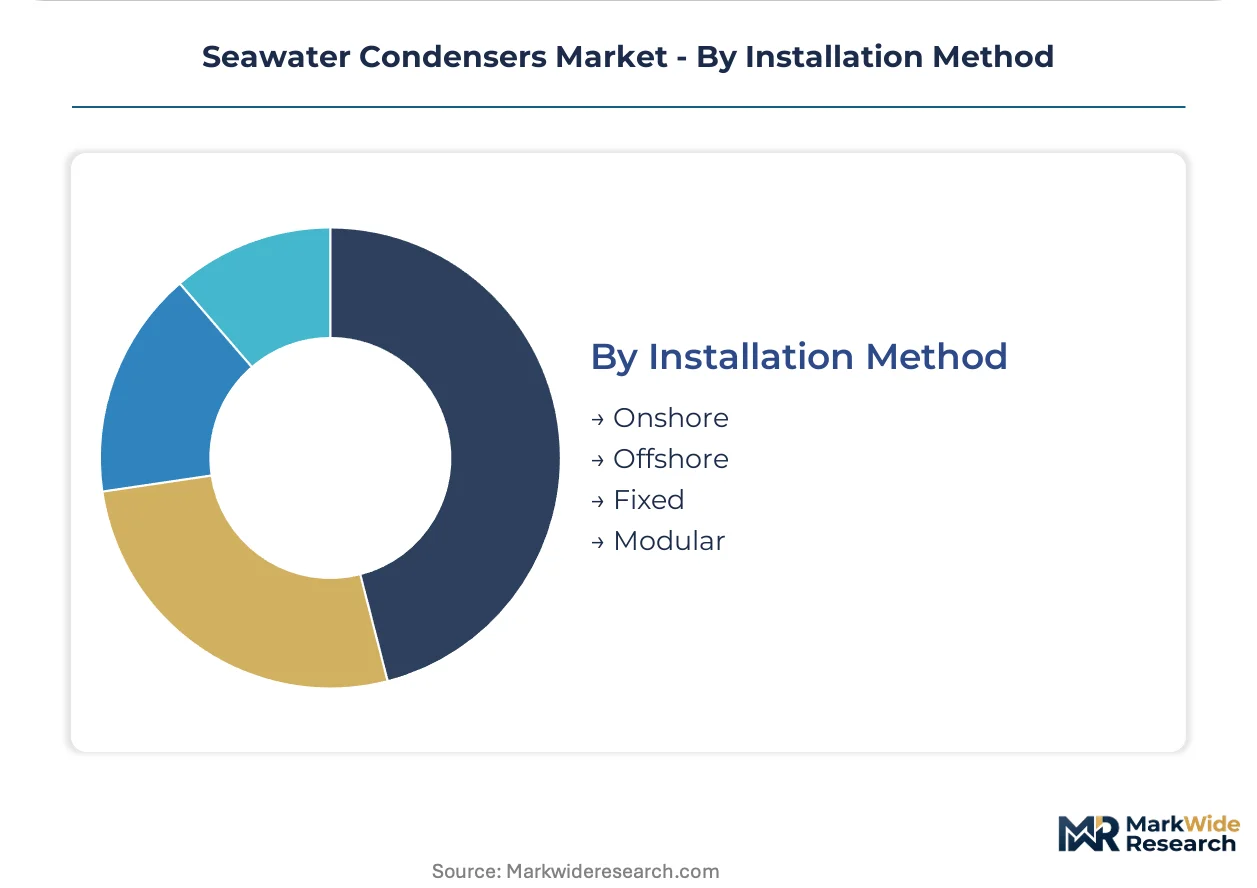
Installation Method:
Site assembly requirements create a procurement bifurcation between stick-built field construction and factory-integrated modular delivery.
- Onshore:Permanent civil-integrated foundations with direct land-seawater intake infrastructure. Egyptian Red Sea coastal zones are seeing concentrated greenfield deployment.
- Offshore:Platform-mounted or floating configurations with flexible riser connections to deepwater cooling sources. North Sea oil and gas decommissioning timelines are compressing replacement windows.
- Fixed:Welded structural attachments requiring dive-assisted inspection and maintenance access. Legacy installations predominate in 1980s-era coastal power stations.
- Modular:Skid-mounted factory-tested units with compressed commissioning cycles. Saudi Arabian gigaproject developers are mandating this approach to accelerate train startup schedules.
Highest shipment volume: Onshore. Climbing fastest: Modular configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seawater condenser fabrication clusters concentrate in Baltic Sea and Red Sea manufacturing zones, while consumption tilts toward Middle Eastern desalination corridors and European coastal power retrofits.
Saudi Arabia
Gigascale desalination projects in Jubail and Ras Al-Khair drive titanium-clad tube demand. The national water regulator mandates material traceability protocols for all municipal supply network equipment. Eastern Province industrial cities host concentrated procurement activity for corrosion-resistant condenser fleets.
Germany
Coastal power stations along the North and Baltic Seas accelerate retrofit timelines under EU Green Deal decarbonization mandates. EMA corrosion protection standards and REACH material compliance frameworks govern alloy selection for marine heat exchange equipment. Hamburg and Bremen harbor zones anchor specialized fabricator networks serving European retrofit demand.
United States
Coastal power facilities face EPA Section 316(b) cooling water intake regulations compelling closed-cycle condenser circuit retrofits. California and Florida installations represent concentrated compliance-driven procurement. Gulf Coast petrochemical corridors generate secondary demand for corrosion-resistant auxiliary cooling systems.
United Arab Emirates
Independent water and power producers specify hybrid thermal-electric architectures for load-following dispatch flexibility. MOHAP and federal water authorities enforce certification standards for desalination equipment feeding municipal networks. Dubai and Abu Dhabi industrial zones concentrate lifecycle service contracting adoption.
Egypt
Red Sea coastal development zones drive greenfield condenser deployment for tourism and industrial infrastructure. Marine environmental protection tightening accelerates replacement cycles for existing installed capacity. Hurghada and Safaga corridors represent concentrated demand pockets for newbuild thermal systems.
Seawater Condensers Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive heat exchange divisions. Shell-and-tube fabrication retains dominance through operational precedent in baseload plants, while plate-type specialists capture premium pricing in offshore applications. Three archetypes populate the vendor landscape: integrated thermal systems providers, specialized marine fabricators, and diversified pump-valve manufacturers with condenser adjacencies. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek to secure titanium feedstock access and welding certification capabilities.
Among European-based fabricators, Alfa Laval and GEA Group exemplify the integrated thermal systems archetype through Baltic Sea manufacturing footprints and specialized corrosion-resistant alloy capabilities. Siemens Energy occupies a position spanning hybrid architecture integration and electrical systems coupling. These three anchors demonstrate how geographic clustering near demand corridors and material compliance expertise create defensive positioning against Atlantic basin competitors facing ASME Section IX welder scarcity.
| Leading Market Players |
|---|
| Alfa Laval |
| SPX Corporation |
| GEA Group |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Andritz AG |
| General Electric |
| KSB SE & Co. KGaA |
| Doosan Heavy Industries & Construction |
| Others |
Value Network & Pricing Analysis
Titanium sponge price indices cascading from Southeast Asian concentrate producers stratify procurement costs across corrosion-resistant condenser tiers, compressing margins for fabricators without captive alloy supply while amplifying pricing power for Baltic Sea and Red Sea manufacturing clusters with backward-integrated titanium sourcing.
Pricing Analysis
Margin tightening in standard-grade shell-and-tube configurations reflects titanium feedstock volatility and welder certification scarcity. Three-tier pricing structure across titanium-clad premium, super-austenitic standard, and copper-nickel economy levels differentiates procurement tiers. Cost-down pressure on economy grades accelerates because Middle Eastern gigaproject developers bundle long-term service contracts into original equipment awards. Municipal water authorities in Saudi Arabia exhibit lowest price sensitivity due to material traceability mandates, while North Sea offshore operators prioritize footprint reduction over capital cost.
Supply Chain Analysis
Refurbishment flows for end-of-design-life tube bundles from Egyptian Red Sea coastal zones and 1980s-era European power stations feed remanufacturing networks in Germany and Saudi Arabia. Supply concentrates in Finland, Sweden, and Saudi Arabia for specialized fabrication; China and Japan for titanium sponge and super-austenitic steel feedstock. Raw material dependencies center on titanium concentrates from Southeast Asia, copper-nickel alloy from Chile and Indonesia, and specialized welding consumables. Single-source vulnerability around ASME Section IX qualified welders for titanium-steel dissimilar metal joints concentrates risk. Distribution runs through EPC contractor-led project procurement with direct OEM relationships for gigascale desalination fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EPA Section 316(b) mandates and EU REACH authorization requirements for chromium(VI) coatings erect capital-intensive certification barriers that shelter compliant incumbents from price-only competition.
For Market Incumbents: To counter welder certification scarcity and titanium price volatility, secure captive supply through backward integration into Southeast Asian titanium concentrate offtake agreements, and expand Baltic Sea capacity to capture European Green Deal retrofit timelines before Atlantic basin competitors qualify alternative fabrication networks. For New Entrants and Emerging Players: Enter via modular skid-mounted configuration specialization for Saudi Arabian gigaproject developers compressing commissioning schedules, targeting Egyptian Red Sea coastal zones where marine environmental tightening accelerates replacement cycles, and leveraging digital twin commissioning tools as differentiated acceptance protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor plate-type specialists with North Sea offshore platform relationships and plasma-sprayed ceramic coating qualification programs, positioned in Germany and Sweden, where EMA corrosion protection standardization creates certified-supplier preference windows. Monitor titanium sponge price stabilization and ASME Section IX welder pipeline expansion as inflection indicators for margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Feedstock | Captive concentrate supply from Southeast Asian producers insulates margins against spot price volatility. |
| ASME Section IX Welder Certification Programs | Qualified fabrication capacity for titanium-steel joints commands premium pricing in Atlantic basin procurement. |
| Modular Skid-Mounted Factory Integration | Compressed commissioning cycles align with Saudi gigaproject developer train startup schedules. |
| Plasma-Sprayed Ceramic Coating Qualification | REACH-compliant alternatives to chromium(VI) capture European Green Deal retrofit demand. |
| Twenty-Year Lifecycle Service Contracting | Tube replacement bundling concentrates vendor selection power with integrated suppliers in UAE and Saudi Arabia. |
Research Methodology
Trade flow databases, EU ETS emissions registries, and desalination project procurement records formed the secondary backbone, cross-referenced with primary interviews involving EPC contractor procurement directors, coastal power plant maintenance engineers, titanium alloy technical sales leads, and national water regulator certification officers. Bottom-up unit shipment tallies by configuration type and alloy grade triangulated against top-down capital expenditure flows into marine thermal infrastructure across the analysis window.
Historical trendline analysis of installed capacity replacement cycles and gigaproject announcement pipelines informed the projection framework. Segmentation dimensions modeled encompass product type, energy conversion modality, end-use sector, and installation method. CAGRs derived from alloy-specific demand elasticity and regulatory compliance timeline acceleration. Forecast inputs incorporated titanium price trajectory assumptions and welder certification pipeline constraints.
Revisions become necessary when EPA enforcement discretion shifts, EU REACH authorization timelines extend, or Red Sea marine protection designations expand beyond current Egyptian and Saudi coastal zones. Forecasts reflect documented assumptions regarding material substitution rates and fabrication capacity expansion. Practitioners should monitor titanium sponge inventory levels at Baltic Sea manufacturers and ASME Section IX welder graduation rates from Atlantic basin training programs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Thawing System Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Global Condensing Unit Market