
 North America Electric Vehicle Battery Separator Market | 2026-2036
North America Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Separator Market Insights
Market Context
OEM procurement consolidation is repositioning separator suppliers toward long-term offtake agreements with battery cell manufacturers. Asahi Kasei Corporation leverages its polyolefin expertise to anchor supply relationships with North American gigafactories. SK Innovation Co Ltd sustains vertical integration from separator film through cell assembly, while Entek International LLC dominates the regional wet-process segment through its Oregon manufacturing base.
Technical Definition and Segment Structure
Electric vehicle battery separators are microporous membranes, typically 7-25 micrometers thick, that electrically isolate the anode and cathode while permitting lithium-ion transport during charge and discharge cycles. Polyethylene separators lead the product type category due to their shutdown safety mechanism at elevated temperatures, though ceramic-coated composites represent the fastest-growing margin pool as OEMs demand enhanced thermal stability for 800V architectures. Wet-process technology occupies the dominant manufacturing position, while dry-process extrusion competes on cost for standard-range passenger vehicle applications.
Regulatory Framework
The Inflation Reduction Act and NHTSA safety standards shape separator demand by mandating domestic content thresholds and thermal runaway propagation resistance. EPA industrial emissions guidelines and OSHA workplace chemical exposure limits further constrain manufacturing process choices. Stakeholders must monitor evolving BIS-equivalent state-level battery recycling mandates and the trajectory of solid-state battery development timelines.
Market Dynamics
OEM consolidation around 800V battery architectures is compressing separator qualification timelines and concentrating purchasing power among three dominant cell manufacturers in Michigan, Tennessee, and Kentucky.
Growth Catalysts
- IRA Domestic Content Mandates:Battery cell producers must source separator films from qualified North American facilities to unlock federal tax credits, redirecting procurement from Asian suppliers toward regional wet-process capacity.
- 800V Platform Rollouts:Premium electric truck and SUV architectures from Detroit-based OEMs demand ceramic-coated polyethylene separators with enhanced puncture resistance, expanding addressable film specifications.
- Kentucky-Tennessee Cell Cluster:Gigafactory construction along the I-75 corridor is generating captive demand for separator supply within 500-mile logistics radii, reducing working capital requirements for just-in-time cell assembly.
Market Restraints
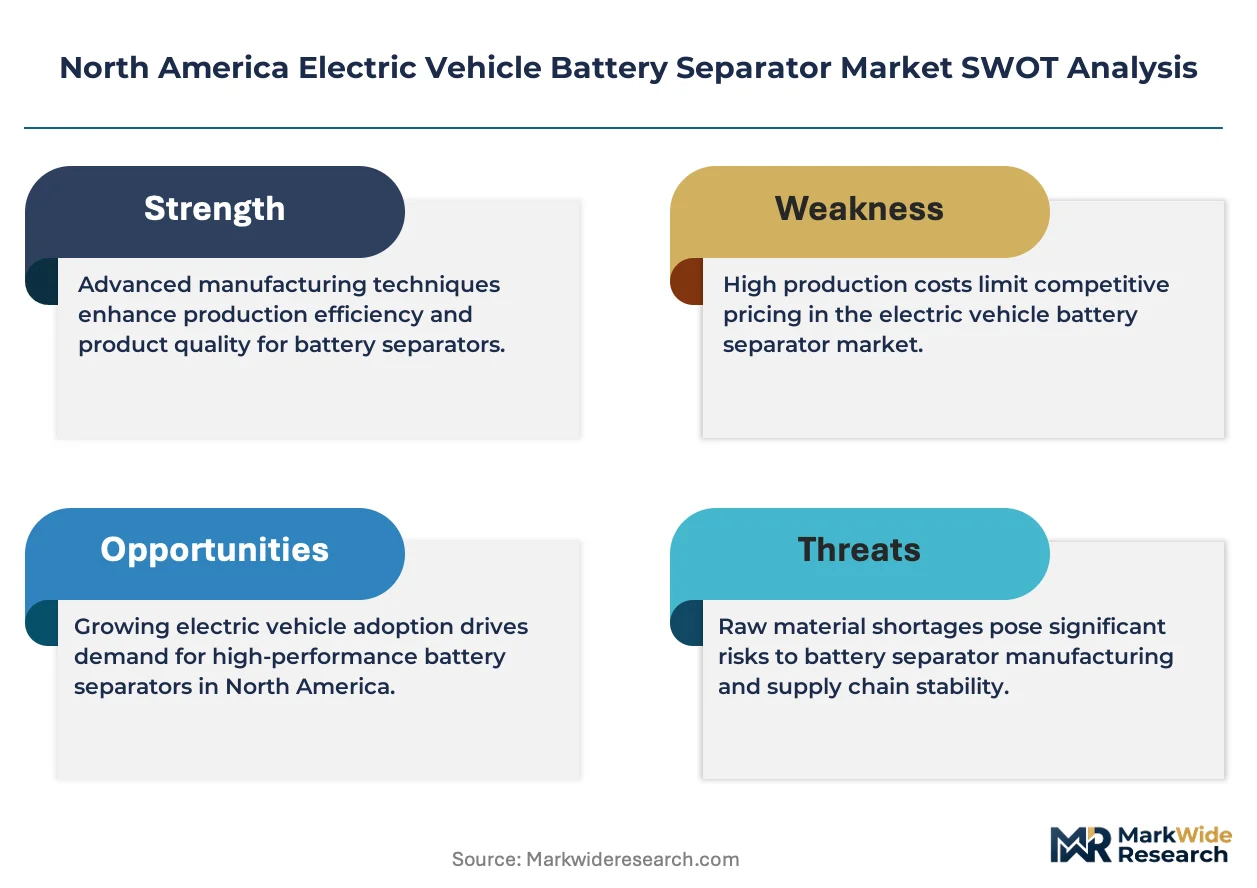
- Polyolefin Feedstock Volatility:Separator manufacturers face margin compression from ethylene and propylene price swings tied to Gulf Coast petrochemical capacity constraints.
- Asian Equipment Dependency:Stretching and extraction machinery for wet-process lines remains concentrated with Japanese and Korean vendors, creating 18-24 month lead time vulnerabilities.
- Solid-State Substitution Timeline:Toyota and QuantumScape development programs threaten long-term separator demand if ceramic electrolyte commercialization accelerates beyond 2032.
Strategic Opportunities
- Mexico Nearshoring Corridor:Separator film conversion facilities in Baja California and Querétaro can access USMCA tariff preferences while serving Texas and California cell plants.
- Recycled Content Differentiation:Oregon and Quebec regulatory frameworks are advancing post-consumer polyolefin certification standards that premium OEMs will embed in supplier scorecards.
- Dry-Process Cost Positioning:Entek International and emerging competitors can attack standard-range vehicle segments where thermal shutdown requirements are less stringent than 800V applications.
Industry Challenges
- Electrolyte Compatibility Certification:Each new lithium salt formulation from cell manufacturers requires 12-18 months of separator swelling and ionic conductivity validation.
- Thin-Film Manufacturing Yield:Sub-12 micrometer ceramic-coated production lines exhibit 15-20% defect rates that compress margins against thicker commodity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Separator Market |
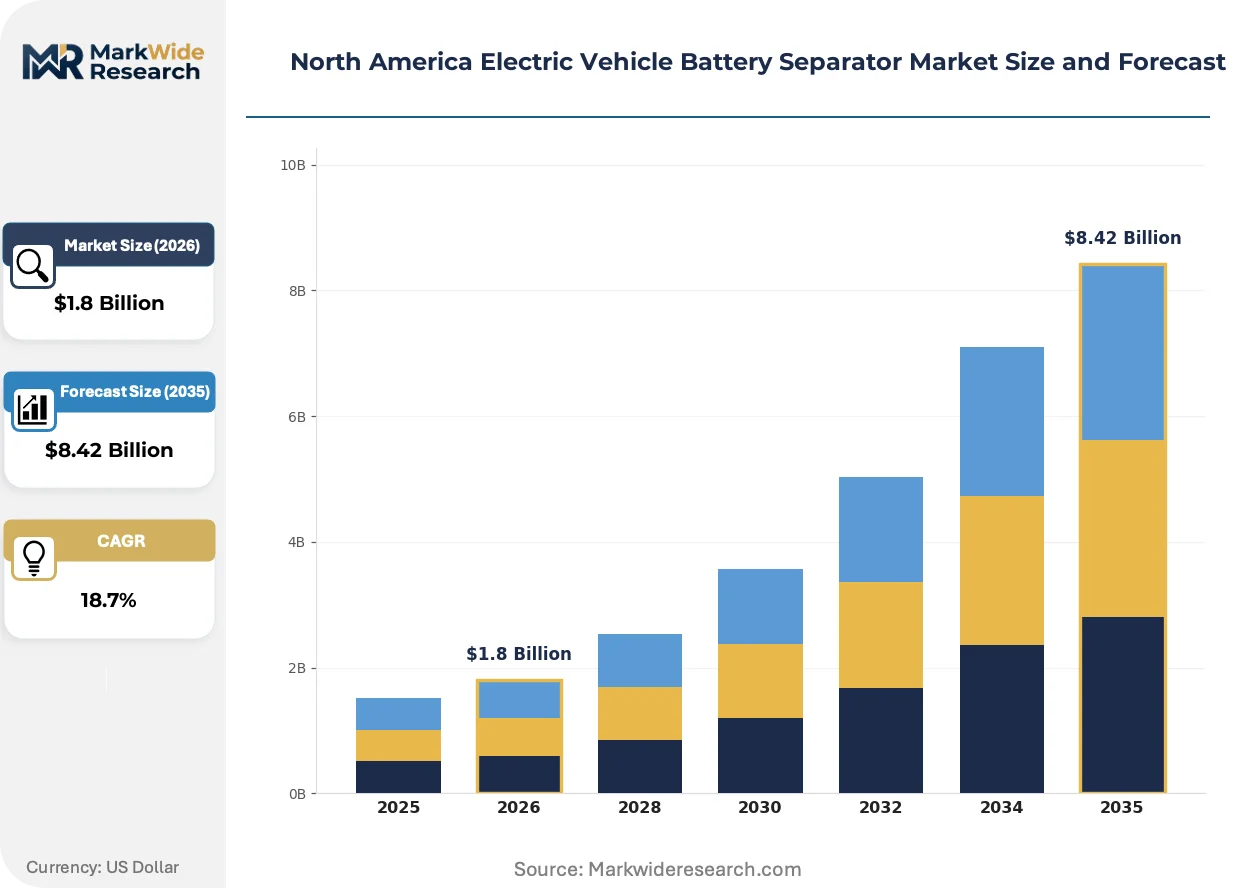
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ceramic, Composite End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers Technology: Dry Process, Wet Process, Coating Technology, Extrusion Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Specialty Vehicles |
| Companies Covered | Asahi Kasei Corporation, SK Innovation Co Ltd, Sumitomo Corporation, Entek International LLC, Toray Industries Inc, Coperion GmbH, Sumitomo Chemical Co., Ltd., SEMCORP Advanced Materials Group, W-SCOPE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology is bifurcating between premium ceramic-coated films for high-voltage architectures and cost-optimized dry-process alternatives for mass-market vehicles, with manufacturing automation determining competitive survival.
Ceramic-coating deposition systems are automating quality inspection through machine vision integration that detects pinhole defects at 50 meters per minute line speeds. SK Innovation and Asahi Kasei deployment of these systems in Georgia and Canada reduces manual inspection headcount while tightening thickness tolerance bands to plus-or-minus 0.5 micrometers. This automation is compressing the cost gap between North American and Asian separator production.
The Inflation Reduction Act's foreign entity of concern provisions are disqualifying Chinese-owned separator capacity from federal incentive eligibility. Cell manufacturers are responding by dual-sourcing from Japanese-Korean joint ventures in Mexico and US domestic wet-process specialists. Tennessee and Kentucky facilities face the steepest compliance recertification burdens given their proximity to IRA credit thresholds.
Battery cell makers are consolidating purchase orders into five-year offtake agreements with price-volume bands indexed to lithium carbonate fluctuations. Tier-2 separator distributors are being disintermediated as OEM procurement teams negotiate directly with film producers for annual cell cost targets. This concentration is most visible in Michigan where Ford and GM purchasing organizations have absorbed separator sourcing from their cell joint ventures.
North America Electric Vehicle Battery Separator Market Segmentation
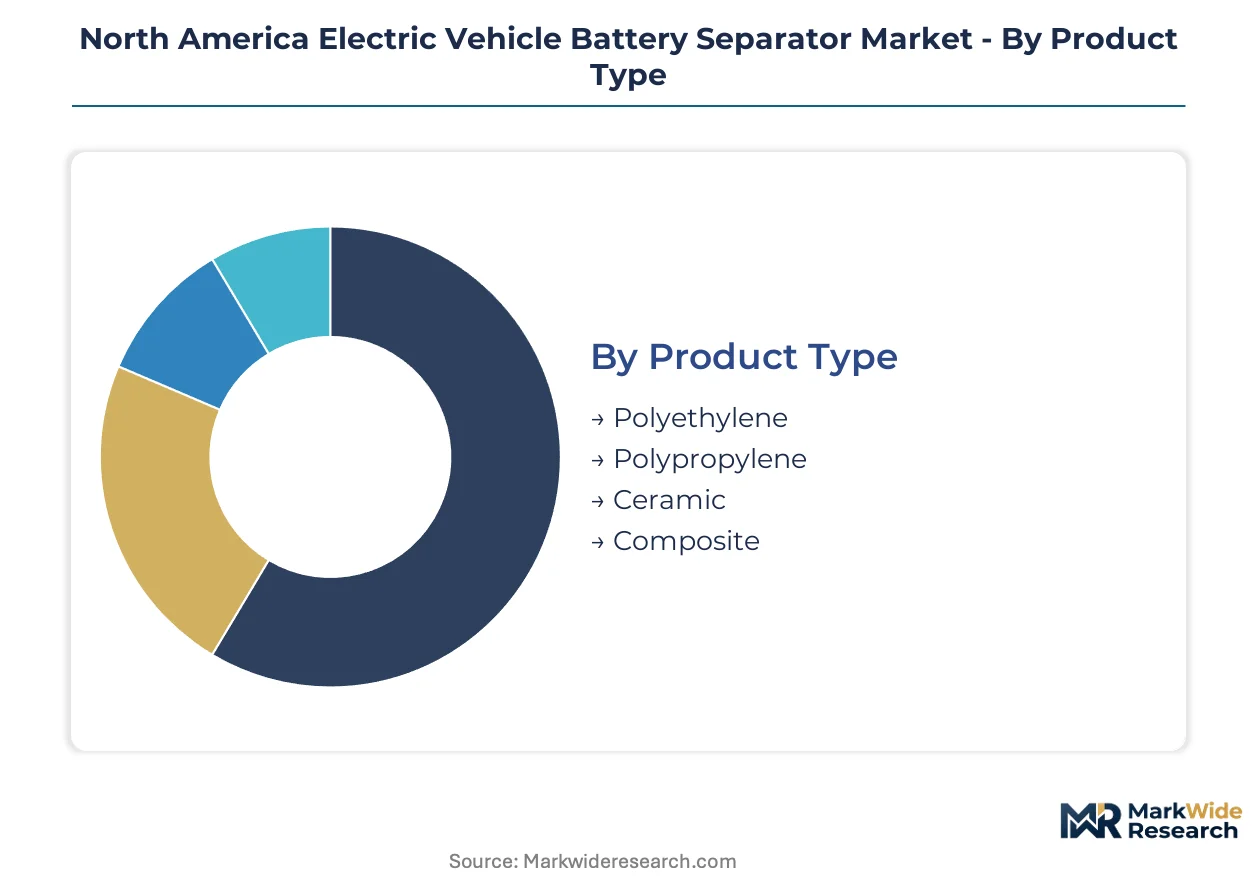
Separator procurement patterns diverge sharply between high-voltage premium platforms and cost-driven mass-market cell production, creating distinct specification tiers across every dimension. OEMs now mandate segment-specific qualification protocols that lock suppliers into multi-year alignment with particular battery architectures.
Product Type:
Material selection spans the customization-vs-standardization spectrum, from commodity polyolefins with established safety shutdown profiles to engineered ceramic composites demanding proprietary coating formulations.
- Polyethylene:Microporous membranes 7-16 micrometers thick deliver thermal shutdown at 130°C, the critical safety mechanism Detroit OEMs require for 800V truck platforms. Michigan and Kentucky gigafactories specify PE exclusively for premium passenger cell lines where propagation resistance is non-negotiable.
- Ceramic:Alumina or silica-coated films achieve 200°C dimensional stability, addressing puncture risks in prismatic cells for electric SUVs. Tennessee cell plants are qualifying these for next-generation 900V architectures where separator shrinkage must stay below 1% at extreme temperatures.
- Polypropylene:Lower melting point (165°C) suits standard-range vehicles with less aggressive thermal management, dominating cost-optimized cylindrical cell production.
- Composite:Multi-layer PE-PP laminates balance shutdown response with mechanical strength, finding niche adoption in hybrid vehicle applications.
Most installed capacity flows through Polyethylene. Expansion is steepest in Ceramic.
End User:
Customer concentration follows the cost tier, from integrated cell OEMs capturing margin through captive supply to fragmented aftermarket channels competing on logistics speed.
- OEMs:Ford, GM, and Stellantis procurement teams negotiate five-year offtake agreements directly with Asahi Kasei and SK Innovation, bypassing traditional distribution. IRA domestic content thresholds force these buyers to validate North American separator conversion facilities before contract execution.
- Battery Manufacturers:LG Energy Solution and Samsung SDI operations in Michigan and Georgia drive volume demand for wet-process PE films, with qualification timelines compressed to 12 months for 800V programs.
- Aftermarket Providers:Independent repair networks source separator-equivalent materials for battery refurbishment, constrained by warranty voiding risks from OEM technical service bulletins.
- Fleet Operators:Commercial vehicle leasing companies influence specification through total-cost-of-ownership modeling that prioritizes cycle life over upfront cell cost.
Contract volume concentrates with Battery Manufacturers. Procurement autonomy is expanding fastest among OEMs.
Technology:
Manufacturing process selection maps to application maturity, with wet-process dominance in high-performance segments and dry-process revival in emerging cost-optimized niches.
- Wet Process:Solvent-based extraction produces 40-60% porosity with narrow pore size distribution, the standard for automotive-grade separators. Entek International's Oregon lines and SK Innovation's Georgia capacity anchor North American supply, though stretching equipment lead times from Japanese vendors stretch to 24 months.
- Dry Process:Mechanical stretching of polypropylene avoids solvent recovery infrastructure, cutting capital intensity by 30% for entrants targeting standard-range vehicle contracts. Kentucky-based pilot lines are requalifying this technology for cylindrical cells.
- Coating Technology:Ceramic deposition systems integrate machine vision at 50 meters per minute, tightening thickness tolerance to ±0.5 micrometers for premium specifications.
- Extrusion:Base film production for downstream coating, with melt-blowing equipment constraints limiting regional capacity expansion.
Production gravity centers on Wet Process. Dry Process is gaining share fastest in cost-sensitive segments.
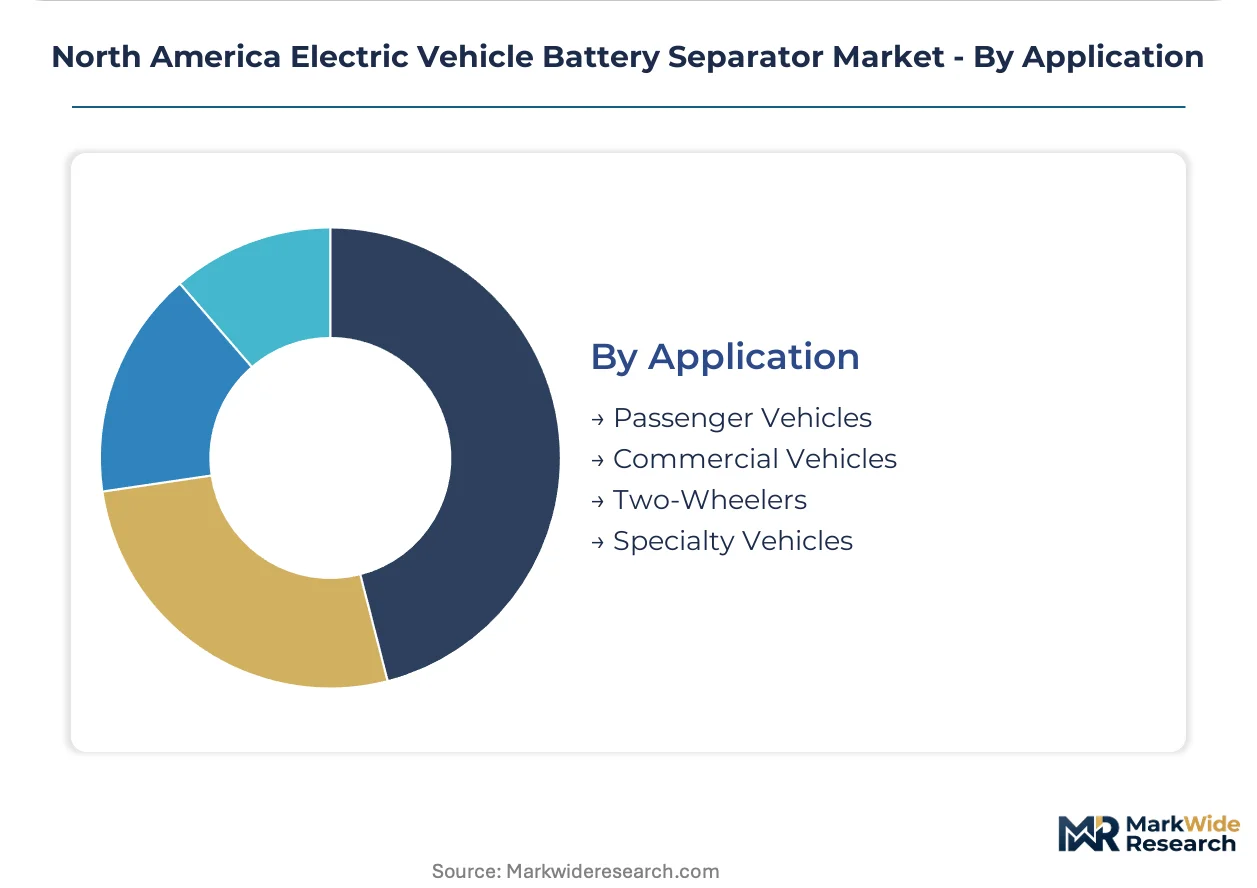
Application:
Vehicle category segmentation reflects divergent duty cycles, with passenger EVs demanding thin-film uniformity and commercial platforms prioritizing mechanical robustness over energy density.
- Passenger Vehicles:Sub-12 micrometer ceramic-coated separators dominate Michigan-designed sedan and SUV platforms, where pack volumetric efficiency drives specification. Defect rates of 15-20% on these thin films compress margins against thicker commodity grades.
- Commercial Vehicles:Electric delivery vans and regional haul trucks specify 16-25 micrometer films with enhanced puncture resistance, accepting weight penalties for durability in high-vibration environments. Tennessee-based cell plants serving this segment prioritize wet-process PE with ceramic reinforcement.
- Two-Wheelers:Micromobility applications tolerate dry-process PP separators, with minimal thermal management requirements enabling cost minimization.
- Specialty Vehicles:Mining and agricultural electrification demands heavy-duty separator specifications, though volumes remain constrained by equipment replacement cycles.
Cell output flows predominantly to Passenger Vehicles. Commercial Vehicle demand is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's separator conversion capacity lags the United States by a factor of eight, while Mexico's nearshoring corridor is capturing USMCA tariff advantages that Canadian facilities cannot match.
United States
Michigan's gigafactory cluster drives separator demand through Ford and GM procurement teams negotiating direct offtake agreements. NHTSA thermal runaway standards and IRA domestic content mandates force cell manufacturers to validate North American wet-process facilities before contract execution. Tennessee and Kentucky cell plants along the I-75 corridor generate captive demand within 500-mile logistics radii.
Canada
Quebec's regulatory frameworks advance post-consumer polyolefin certification standards that premium OEMs embed in supplier scorecards. The country's national environmental regulator enforces industrial emissions guidelines constraining manufacturing process choices. Ontario's proximity to Michigan cell plants positions the province as a secondary logistics hub rather than primary production base.
Mexico
Baja California and Querétaro separator film conversion facilities access USMCA tariff preferences while serving Texas and California cell plants. The Secretariat of Economy administers manufacturing incentives aligned with US IRA domestic content thresholds. Mexican facilities face compliance recertification burdens given their role in dual-sourcing strategies from Japanese-Korean joint ventures.
North America Electric Vehicle Battery Separator Market Competitive Landscape
Japanese and Korean producers anchor the premium ceramic-coated tier; US domestic specialists hold cost-optimized wet-process positions. Market structure concentrates around three strategic archetypes: polyolefin membrane specialists with backward integration into petrochemical feedstocks, vertically integrated cell manufacturers with captive separator lines, and regional conversion specialists serving logistics-constrained procurement. Dominant competitive moves include capacity expansion along the I-75 corridor and strategic partnerships securing five-year offtake agreements indexed to lithium carbonate fluctuations.
Within the polyolefin specialist tier, Asahi Kasei Corporation and Toray Industries Inc represent Japanese incumbents leveraging established coating expertise. SK Innovation Co Ltd exemplifies the vertically integrated archetype, occupying a position that spans separator film through cell assembly. Entek International LLC anchors the regional specialist category, with its Oregon manufacturing base serving as a reference point for domestic wet-process capacity.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| SK Innovation Co Ltd |
| Sumitomo Corporation |
| Entek International LLC |
| Toray Industries Inc |
| Coperion GmbH |
| Sumitomo Chemical Co., Ltd. |
| SEMCORP Advanced Materials Group |
| W-SCOPE Corporation |
| Others |
Pricing and Supply Chain Analysis
Polyolefin feedstock costs originating from Gulf Coast petrochemical complexes cascade through wet-process separator manufacturing into three distinct pricing tiers, with ceramic-coated specifications commanding premiums over commodity polyethylene films as IRA domestic content mandates redirect procurement toward North American conversion facilities.
Pricing Analysis
Capacity additions in Tennessee and Kentucky are reshaping price floors for automotive-grade wet-process films, displacing Asian import dependence. Pricing stratifies across ceramic-coated premium, standard wet-process, and dry-process economy tiers, with certification to NHTSA thermal runaway standards and IRA domestic content thresholds as the primary differentiation drivers. Cost compression in standard-range vehicle segments is intensifying because Entek International and emerging dry-process competitors attack cylindrical cell applications. Fleet operators and aftermarket providers exhibit the highest price sensitivity, while OEM procurement teams negotiating direct offtake agreements show the least.
Supply Chain Analysis
Workforce availability constraints in Oregon, Georgia, and the I-75 corridor states are tightening labor markets for specialized coating technicians and machine vision operators. Separator film production draws from Japanese and Korean stretching equipment vendors, US Gulf Coast ethylene and propylene feedstocks, and Canadian post-consumer polyolefin certification programs. Single-source vulnerability to Asian machinery suppliers with 18-24 month lead times represents the dominant structural risk. Distribution runs through direct long-term offtake agreements between film producers and cell manufacturers, disintermediating traditional tier-2 distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with OEM procurement consolidation around 800V architectures forcing separator qualification toward ceramic-coated specifications with enhanced thermal stability and puncture resistance.
For Market Incumbents: Extend coating automation investments to compress thickness tolerance bands below plus-or-minus 0.5 micrometers, defending against emerging dry-process cost competition in standard-range segments. Secure backward integration into polyolefin feedstocks or captive recycling streams to offset Gulf Coast petrochemical volatility. Solid-state battery development timelines from Toyota and QuantumScape threaten long-term demand displacement if ceramic electrolyte commercialization accelerates beyond the projection horizon. For New Entrants and Emerging Players: Capture the Mexico nearshoring corridor opportunity in Baja California and Querétaro, where USMCA tariff preferences and IRA domestic content alignment create procurement access to Texas and California cell plants. The dry-process revival in Kentucky-based cylindrical cell applications offers the most penetrable entry point, with minimal thermal management requirements enabling cost minimization. Lead with recycled content certification to differentiate in Oregon and Quebec regulatory frameworks advancing post-consumer polyolefin standards. For Investors and Strategic Acquirers: Consolidation pressure builds where wet-process capacity scarcity intersects with IRA credit threshold proximity, particularly for Tennessee and Kentucky facilities facing compliance recertification burdens. Acquisition targets should display regional conversion specialization with logistics-constrained procurement relationships and machine vision integration capabilities. Watch solid-state battery pilot production announcements as the critical inflection signal for separator demand displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Automation | Machine vision integration at 50 meters per minute tightens tolerance bands for 800V architectures. |
| IRA Domestic Content Compliance | North American conversion facility validation unlocks federal tax credit eligibility for cell manufacturers. |
| Mexico Nearshoring Footprint | Baja California and Querétaro facilities access USMCA preferences while serving southwestern cell plants. |
| Dry-Process Capacity Expansion | Kentucky pilot lines requalify mechanical stretching for cost-optimized cylindrical cell production. |
| Recycled Content Certification | Oregon and Quebec post-consumer polyolefin standards embed in premium OEM supplier scorecards. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each territory combined with secondary validation. Interviews with separator plant managers, OEM procurement leads at Ford and GM, battery cell manufacturer technical directors, and petrochemical feedstock specialists informed demand and supply-side assessments. Secondary sources include NHTSA regulatory filings, EPA industrial emissions databases, USMCA tariff schedules, SEC 10-K disclosures from listed materials companies, and IHS Markit vehicle production data. Bottom-up capacity modeling and top-down OEM procurement analysis were triangulated to reconcile volume estimates.
Granularity extends to product type, manufacturing technology, end-user category, and vehicle application, with state-level geographic disaggregation for Michigan, Tennessee, Kentucky, Oregon, Georgia, Quebec, Ontario, Baja California, and Querétaro. CAGRs were derived from fitted growth curves incorporating IRA incentive phase-in schedules and gigafactory construction timelines. Forecast inputs include polyolefin feedstock price indices, lithium carbonate contract pricing, and solid-state battery development milestone tracking.
Polyolefin feedstock volatility, Asian equipment lead time disruptions, and solid-state battery substitution acceleration are the dominant revision risks to the forecast framework. Material deviation in any of these triggers warrants pause and re-evaluation of capacity expansion assumptions and demand trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market