
 Oil Immersed Transformer and Dry Type Transformer Market | 2026-2036
Oil Immersed Transformer and Dry Type Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Immersed Transformer and Dry Type Transformer Market Insights
The EU Green Deal is consolidating transformer procurement priorities across European power utilities toward lower-emission dry-type alternatives. ABB Group leverages its regional manufacturing footprint to sustain leadership in eco-efficient designs. Siemens AG anchors its position through integrated digital monitoring platforms for utility-scale installations. General Electric Company competes on high-capacity oil-immersed systems for offshore wind interconnection projects.
Oil immersed transformers rely on mineral oil or ester-based dielectric fluid for insulation and cooling, typically operating at voltages from 11 kV to 765 kV for bulk power transmission and distribution. Dry type transformers use air and solid epoxy resin or cast coil insulation, eliminating liquid dielectrics for indoor commercial and industrial applications where fire safety governs selection. Product type segmentation shows dry-type units capturing share in urban substations and data center builds where indoor installation restrictions apply. End user patterns reveal renewable energy as the fastest-expanding category, with offshore wind and solar farms requiring specialized step-up capacity. Capacity segmentation above 20 MVA carries concentrated margin pools due to engineering complexity and limited qualified suppliers.
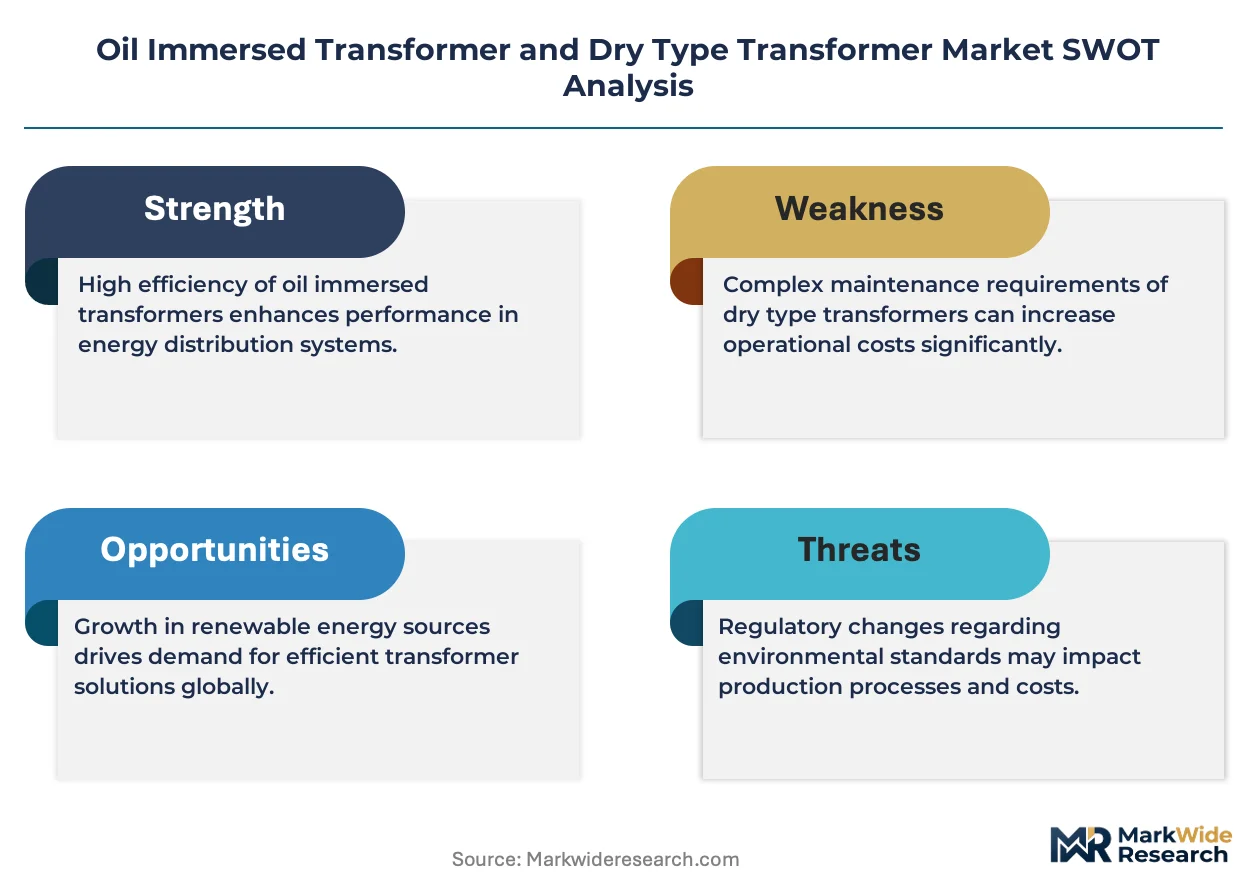
The EPA regulates polychlorinated biphenyl contamination in transformer oil under TSCA, compelling utilities to phase legacy equipment and modernize fleets. IEC 60076 standards govern thermal performance and short-circuit withstand for international product acceptance, while IEEE C57.12.00 shapes North American design and testing protocols. Stakeholders must monitor evolving fire-resistance classifications and local building codes as urban densification restricts oil-immersed deployment in commercial zones.

Market Dynamics
The EU F-Gas Regulation and India's PLI scheme are diverting capital toward dry-type manufacturing capacity while compressing margins on conventional oil-immersed units. Utilities now face dual pressure: decarbonization mandates upstream and renewable interconnection requirements downstream.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic transformer manufacturing are accelerating utility procurement of high-capacity units. State-level distribution reforms in Maharashtra and Gujarat are creating concentrated demand clusters.
- Offshore wind interconnection:North Sea and Baltic Sea projects require specialized step-up transformers for subsea cable landing points. EPC contractors are pre-qualifying suppliers with 400 kV+ oil-immersed experience.
- Ester-based dielectric fluids:Synthetic and natural ester alternatives to mineral oil are extending transformer lifespan in fire-sensitive installations. Data center operators in Frankfurt and Amsterdam are specifying these for indoor substations.
Market Restraints
- Grain-oriented electrical steel concentration:Cold-rolled core material supply concentrates in China and Japan, exposing transformer OEMs to alloy price volatility and export quota risks.
- Copper cathode cost structure:Winding material represents 35-45% of raw material cost for large power transformers. LME price swings compress quoted margins before contract execution.
- Fire-resistance classification friction:Local building codes in dense urban zones increasingly restrict oil-immersed equipment, forcing premature retirement of technically serviceable assets.
Strategic Opportunities
- Data center builds in Nordics:Hyperscale facilities in Sweden and Norway require dry-type units for indoor 132 kV step-down. Low ambient temperatures enable higher overload capacity.
- Digital twin convergence:Integration of thermal sensors with predictive analytics platforms creates recurring revenue streams for asset monitoring services.
- Brazilian transmission auctions:ANEEL's periodic capacity procurements favor bidders with local manufacturing presence. Greenfield dry-type facilities near São Paulo industrial corridor capture import substitution premiums.
Industry Challenges
- High-voltage test bay scarcity:Short-circuit withstand certification for units above 100 MVA requires specialized laboratory infrastructure. Queue times at KEMA and CESI facilities extend project timelines.
- Legacy PCB remediation:EPA TSCA compliance for contaminated mineral oil disposal adds unbudgeted costs to utility fleet renewal programs. Specialized hazardous waste handling extends site downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Immersed Transformer and Dry Type Transformer Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Immersed Transformer, Dry Type Transformer, Hybrid Transformer, Portable Transformer Installation: Indoor, Outdoor, Ground Mounted, Pole Mounted End User: Power Utilities, Industrial, Commercial, Renewable Energy Capacity: Up to 5 MVA, 5-10 MVA, 10-20 MVA, Above 20 MVA |
| Companies Covered | Eaton Corporation PLC, General Electric Company, ABB Group, Mitsubishi Electric Corporation, Toshiba Corporation, Siemens AG, Hitachi Ltd., TBEA Co., Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Immersed Transformer and Dry Type Transformer Market Trends and Innovations
Transformer technology is bifurcating between ultra-high-capacity oil-immersed systems for bulk power and compact dry-type designs for distributed generation integration. Material science advances and digitalization are compressing traditional equipment lifecycles.
Cast resin vacuum impregnation is consolidating market share in urban substation applications. The process eliminates voids in epoxy insulation, improving partial discharge performance for 36 kV+ dry-type units. Metro rail operators in London, Singapore, and Dubai are specifying these for tunnel installations where fire safety codes prohibit liquid dielectrics. The technology is consolidating procurement specifications across transit authorities, squeezing out conventional VPI (Vacuum Pressure Impregnation) alternatives.
Europe's F-Gas Regulation is tightening permissible global warming potential thresholds for industrial equipment. The framework indirectly accelerates dry-type transformer specification by raising compliance costs for oil-immersed systems with synthetic ester fluids. German utilities RWE and EnBW are rewriting technical standards to favor air-insulated designs for indoor 110 kV substations, forcing OEMs to expand cast coil production lines.
Utility procurement departments are unbundling transformer supply from installation and commissioning services. EPC contractors now compete separately from equipment vendors, compressing bundled margins. This pattern is most visible in India's UMPP (Ultra Mega Power Project) tenders, where NTPC and state gencos issue split contracts. Channel restructuring favors specialized installation firms with localized civil works expertise over integrated OEM-service offerings.
Oil Immersed Transformer and Dry Type Transformer Market Segmentation
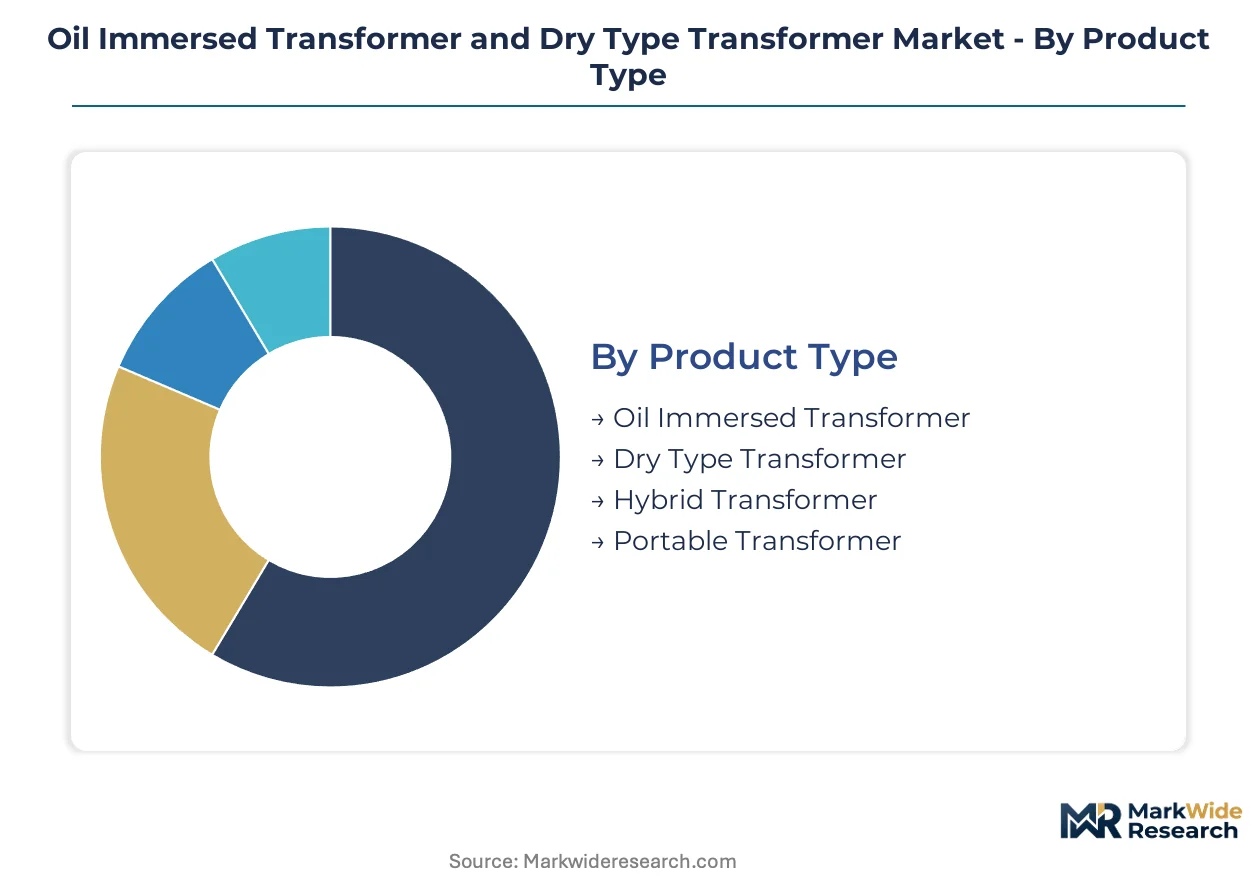
Transformer procurement splits along four critical dimensions: cooling technology, physical siting, buyer economics, and unit scale. Each axis carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Standardized designs dominate high-volume utility procurement while customized specifications concentrate in mission-critical installations.
- Oil Immersed Transformer:Mineral oil or ester-based dielectric fluid provides insulation and cooling for bulk power transmission. Offshore wind interconnection projects in the North Sea and Baltic Sea require 400 kV+ units with subsea cable compatibility. EPC contractors pre-qualify suppliers based on deepwater installation experience.
- Dry Type Transformer:Air and solid epoxy resin or cast coil insulation eliminates liquid dielectrics entirely. Data center operators in Frankfurt and Amsterdam specify these for indoor substations where EU F-Gas Regulation raises compliance costs for oil-based alternatives. Fire safety codes in dense urban zones accelerate displacement of liquid-cooled systems.
- Hybrid Transformer:Combines liquid and air cooling for transitional applications. Metro rail operators in London and Singapore evaluate these for tunnel installations with restricted ventilation.
- Portable Transformer:Mobile skid-mounted units for emergency grid restoration. Disaster response agencies in California and Texas maintain fleets for wildfire and storm recovery.
Leading the category by volume: Oil Immersed Transformer. Expanding most quickly: Dry Type Transformer.
Installation:
Siting constraints determine fire-resistance classifications and civil works intensity.
- Indoor:Cast resin vacuum impregnation dominates urban substation builds. German utilities RWE and EnBW rewrite technical standards to favor air-insulated designs for 110 kV indoor installations.
- Outdoor:Weatherproof enclosures and expanded clearances suit transmission grid expansion. India's state-level distribution reforms in Maharashtra and Gujarat concentrate procurement of ground-mounted units.
- Ground Mounted:Pad-mounted distribution transformers serve suburban load centers. Brazilian transmission auctions through ANEEL favor bidders with local manufacturing presence near São Paulo.
- Pole Mounted:Compact single-phase units for rural electrification. India's PLI scheme accelerates domestic production of high-capacity pole-mounted designs.
Ground Mounted leads deployment volume. Indoor installations gain share fastest as urban densification restricts oil-immersed equipment.
End User:
Buyer sophistication ranges from price-tender utilities to performance-specified industrial operators.
- Power Utilities:Grid-scale procurement governed by IEC 60076 thermal performance standards. India's NTPC and state gencos unbundle transformer supply from installation in UMPP tenders.
- Industrial:Manufacturing facilities demand fire-resistant designs for indoor plant substations. Ester-based dielectric fluids extend asset lifespan in fire-sensitive chemical processing environments.
- Commercial:Shopping complexes and office towers prioritize compact footprints. Building codes in dense Asian megacities increasingly prohibit liquid dielectrics in basement electrical rooms.
- Renewable Energy:Offshore wind and solar farms require specialized step-up capacity. North Sea projects demand 400 kV+ oil-immersed systems with subsea cable landing point compatibility.
Power Utilities anchor procurement volume. Renewable Energy climbs fastest on interconnection mandates.
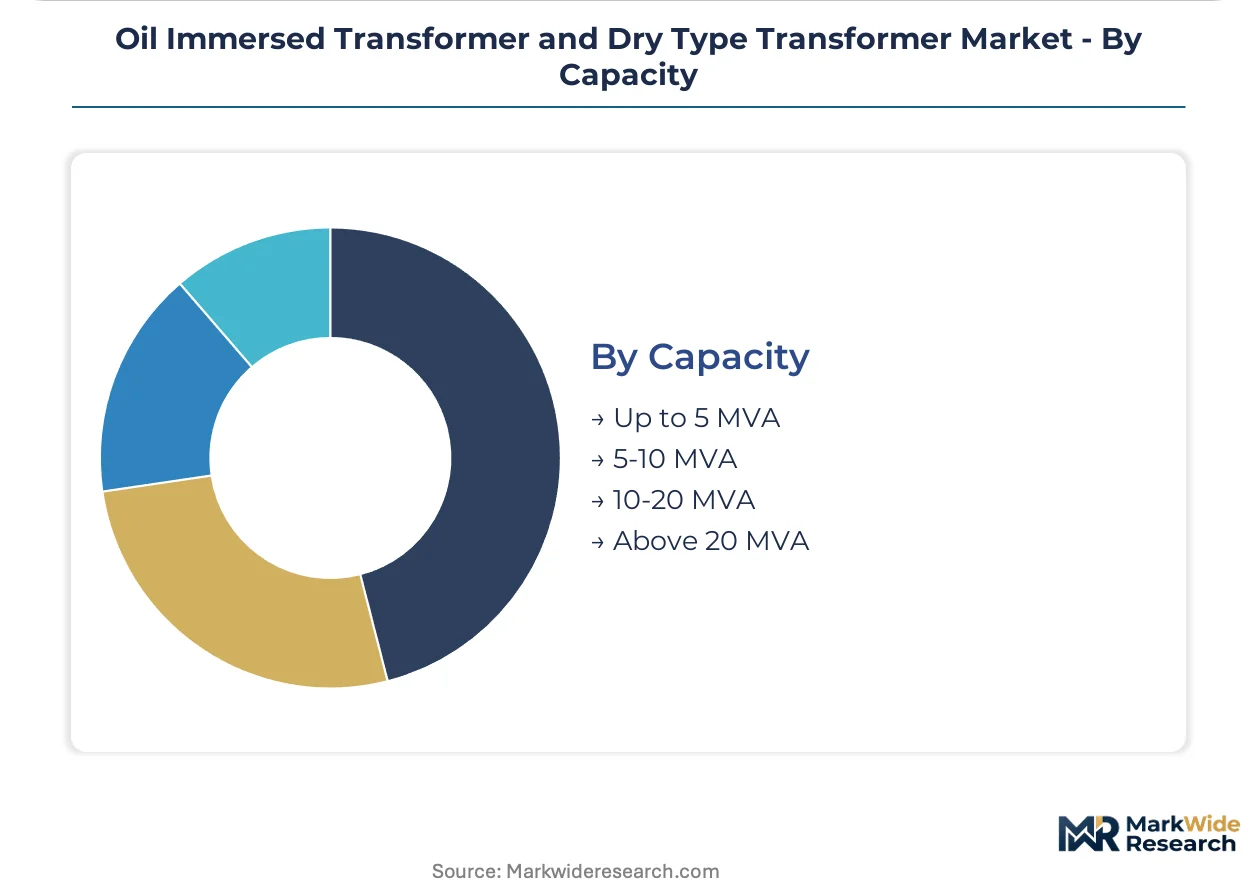
Capacity:
Engineering complexity and supplier qualification barriers concentrate margin pools at scale thresholds.
- Up to 5 MVA:Standardized distribution transformers with commodity pricing. Cold-rolled grain-oriented electrical steel supply concentration in China and Japan exposes OEMs to alloy price volatility.
- 5-10 MVA:Commercial and light industrial applications. Copper cathode winding material represents 35-45% of raw material cost, compressing quoted margins before contract execution.
- 10-20 MVA:Utility substation and large industrial feeds. Short-circuit withstand certification requires specialized laboratory infrastructure with extended queue times at KEMA and CESI facilities.
- Above 20 MVA:Bulk power transmission and offshore wind step-up. Limited qualified suppliers and high-voltage test bay scarcity create concentrated margin pools.
Above 20 MVA commands premium positioning. Up to 5 MVA delivers highest unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's financial district anchors transformer procurement intensity as Maharashtra's state distribution reforms accelerate grid modernization spending.
United States
Offshore wind interconnection projects along the Atlantic coast demand specialized step-up capacity for subsea cable landing points. The EPA regulates PCB contamination in legacy transformer oil under TSCA, compelling utilities to phase outdated equipment. EPC contractors in Texas and California pre-qualify suppliers based on wildfire-resistance specifications for emergency grid restoration fleets.
Germany
RWE and EnBW are rewriting technical standards to favor air-insulated dry-type designs for indoor 110 kV substations. The EU F-Gas Regulation tightens permissible global warming potential thresholds, raising compliance costs for oil-immersed alternatives. Industrial clusters in the Ruhr Valley and Bavaria concentrate procurement of cast coil units for manufacturing facility upgrades.
India
The PLI scheme accelerates domestic manufacturing of high-capacity transformers for utility-scale deployment. State-level distribution reforms in Gujarat and Tamil Nadu create concentrated demand clusters for ground-mounted substation equipment. NTPC unbundles transformer supply from installation services in Ultra Mega Power Project tenders, restructuring channel relationships.
China
Grid infrastructure expansion to accommodate renewable energy integration drives procurement of bulk power transmission equipment. The national dual carbon goals pressure utilities toward lower-emission transformer technologies. Manufacturing corridors in Jiangsu and Shandong provinces concentrate cold-rolled grain-oriented electrical steel production, exposing OEMs to alloy price volatility.
Brazil
ANEEL's periodic transmission auctions favor bidders with local manufacturing presence near São Paulo's industrial corridor. Greenfield dry-type facilities capture import substitution premiums as distribution network expansion accelerates. Hydropower interconnection projects in the Southeast region require specialized step-up capacity for long-distance transmission.
Oil Immersed Transformer and Dry Type Transformer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering complexity and certification capability. The market structures around three tiers: integrated electrical conglomerates with full-spectrum portfolios, specialized transformer OEMs with concentrated manufacturing expertise, and regional fabricators serving localized procurement. Consolidation pressure intensifies as utilities unbundle equipment supply from installation services, compressing bundled margins. Dominant competitive moves include capacity expansion into ester-based dielectric fluid production and strategic partnerships for digital twin platform integration.
Among integrated electrical conglomerates, ABB Group and Siemens AG occupy positions exemplifying the premium-tier archetype through regional manufacturing footprints and digital monitoring capabilities. General Electric Company anchors the high-capacity oil-immersed segment for specialized applications. These entities represent competitive positioning around eco-efficient design leadership, integrated platform offerings, and project-scale execution capability rather than commodity volume competition.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| General Electric Company |
| ABB Group |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Siemens AG |
| Hitachi Ltd. |
| TBEA Co., Ltd. |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between IEC 60076-compliant premium units and commodity-standard alternatives manifests in divergent pricing power and supply chain configurations. OEMs with KEMA and CESI test bay access command project-based premiums for above-20 MVA units, while standardized distribution transformers compete on copper cathode and grain-oriented electrical steel input costs.
Pricing Analysis
Short-circuit withstand certification anchors value-based pricing for high-capacity units, with EPC contractors paying throughput premiums for offshore wind interconnection reliability. Three-tier pricing structure across certified-premium, standard-utility, and commodity-distribution levels differentiates based on test bay validation and fire-resistance classification. Pricing pressure stems from copper LME volatility compressing quoted margins before contract execution. Price-sensitive municipal utilities in India's state distribution reforms drive commoditization at sub-10 MVA scale, while data center operators in Frankfurt and Amsterdam absorb dry-type premiums for indoor fire safety compliance.
Supply Chain Analysis
Grain-oriented electrical steel supply rests on cold-rolled production corridors in China and Japan, exposing transformer OEMs to alloy price swings and export quota volatility. Copper cathode sourcing concentrates in Chile and Peru, with winding material representing 35-45% of raw material cost for large power transformers. Single-source vulnerability in high-voltage test bay capacity at KEMA and CESI facilities extends certification queues. Distribution runs through unbundled EPC channels in India's UMPP tenders, compressing bundled OEM-service margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry-type cast resin technology is displacing mineral oil-immersed systems in urban substations and data center builds, compressing legacy equipment margins while opening premium positioning for fire-resistant designs.
For Market Incumbents: Anticipate margin compression in conventional oil-immersed distribution transformers as India's PLI scheme accelerates domestic manufacturing capacity. Defend positioning through backward integration into ester-based dielectric fluid production and captive high-voltage test bay investment. Channel control via digital twin platform integration creates recurring revenue insulation against unbundled EPC procurement trends. For New Entrants and Emerging Players: E-commerce procurement portals for standardized distribution transformers offer low-friction market entry below 5 MVA capacity. Target Brazilian transmission auction participation through greenfield dry-type facilities near São Paulo's industrial corridor. White-space concentration in Nordic hyperscale data center builds favors cast coil specialists with 132 kV indoor step-down experience. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated electrical conglomerates seeking test bay capacity and regional manufacturing footprint. Long-term viability favors OEMs with dual oil-immersed and dry-type portfolios spanning utility and industrial end-use. Monitor ANEEL auction participation rates and NTPC unbundling penetration as inflection signals for channel restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ester-based Dielectric Fluid Capacity Expansion | Captures fire-safety premium in Frankfurt and Amsterdam data center specifications. |
| Digital Twin Platform Integration | Creates recurring monitoring revenue streams for utility-scale transformer assets. |
| High-Voltage Test Bay Investment | Reduces certification queue dependency for above-100 MVA offshore wind projects. |
| Local Manufacturing Footprint in Brazil | Qualifies bidders for ANEEL transmission auction import substitution premiums. |
| Cast Coil Production Line Expansion | Addresses RWE and EnBW technical standard rewrites favoring air-insulated 110 kV designs. |
Research Methodology
Regulatory filings from EPA, IEC, and IEEE standards committees, trade data from customs authorities, and utility procurement databases formed the secondary backbone for transformer market sizing. Primary interviews with EPC contractors, utility planning officers, transformer OEM procurement leads, and data center facility managers validated demand assumptions across cooling technology segments. Bottom-up and top-down triangulation reconciled unit shipment estimates with raw material consumption patterns in grain-oriented electrical steel and copper cathode markets.
Bottom-up modeling anchored forecasts to named project pipelines in North Sea offshore wind, India's UMPP tenders, and Brazilian ANEEL auctions, while top-down validation cross-checked against grid investment disclosures from RWE, EnBW, and NTPC. Segmentation dimensions spanned cooling technology, installation siting, end-use category, and capacity tier across the analysis window. CAGRs were derived from utility capital expenditure trajectories and renewable interconnection mandates, with copper price elasticity and test bay capacity constraints incorporated as scenario variables.
Inputs from KEMA and CESI certification records were available through the study window; gaps in real-time EPC contractor backlog disclosure introduce uncertainty bands around project timing assumptions. Forecasts reflect documented utility procurement patterns and regulatory phase-in schedules, with EU F-Gas Regulation enforcement velocity and India's PLI scheme disbursement rates representing specific revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Current Transformer Market
Transformers
United States Large Power Transformer Market
Transformers
Asia-Pacific Transformer Market
Transformers
Smart Transformer Market
Transformers
Three Phase Transformer Market
Transformers
US Oil Filled Distribution Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
India Transformer Market
Transformers
Europe Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Single Phase Power Transformer Market
Transformers
United States Distribution Transformer Market
Transformers
Air Cooled Transformer Market
Transformers
Green Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market