
 Middle East and Africa Electric Vehicle Battery Separator Market | 2026-2036
Middle East and Africa Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Battery Separator Market Insights
EU Green Deal compliance requirements for battery supply chain traceability is shifting the cost-of-entry calculus for separator manufacturers serving Middle East and Africa markets. Entek International LLC leverages its North American manufacturing base to compete on ceramic-coated polymer exports into the region. Toray International Inc. anchors its position through sustained R&D intensity in thin-film extrusion technologies. SK IE Technology differentiates by controlling wet-process separator supply channels that OEMs in the region increasingly specify.
An electric vehicle battery separator is a microporous membrane, typically 5–25 micrometers thick, composed of polyolefin substrates or ceramic composites, manufactured through wet or dry extrusion processes; its primary function is to prevent electrical short circuits between anode and cathode while permitting ionic transport during charge and discharge cycles. Polymer separators occupy the dominant share due to established cost structures and manufacturing scalability, though ceramic-coated variants are gaining traction among OEMs prioritizing thermal runaway mitigation in high ambient temperatures. Passenger vehicles command the largest application volume, while commercial vehicles represent the fastest-expanding segment as logistics electrification accelerates across Gulf Cooperation Council corridors and East African trade routes.
South Africa's National Regulator for Compulsory Specifications enforces battery component safety benchmarks that directly shape product approval timelines for imported separators. Saudi Arabia's Saudi Standards, Metrology and Quality Organization and the UAE's Ministry of Industry and Advanced Technology are aligning EV component regulations with Gulf technical standards, creating a harmonized but stringent market access framework. Stakeholders must monitor how regional content requirements and carbon border adjustment preparations in adjacent European markets will reshape sourcing decisions for separator supply chains serving Middle East and Africa assembly plants.
Market Dynamics
Ceramic-coated separator adoption is compressing procurement timelines across Middle East and Africa EV supply chains as thermal runaway mitigation becomes non-negotiable for fleet operators in high-ambient-temperature corridors.
Growth Catalysts
- EU Green Deal supply chain traceability mandates:Exporters into Middle East and Africa assembly plants must document separator provenance, accelerating certification upgrades among regional distributors.
- Logistics electrification across Gulf Cooperation Council corridors:Electric truck procurement by fleet operators is pulling demand for high-temperature-stable separators into Saudi Arabia and UAE commercial vehicle specifications.
- Wet-process extrusion technology maturation:OEMs in the region increasingly specify wet-process channels for ionic transport consistency, concentrating supplier qualification efforts.
Market Restraints
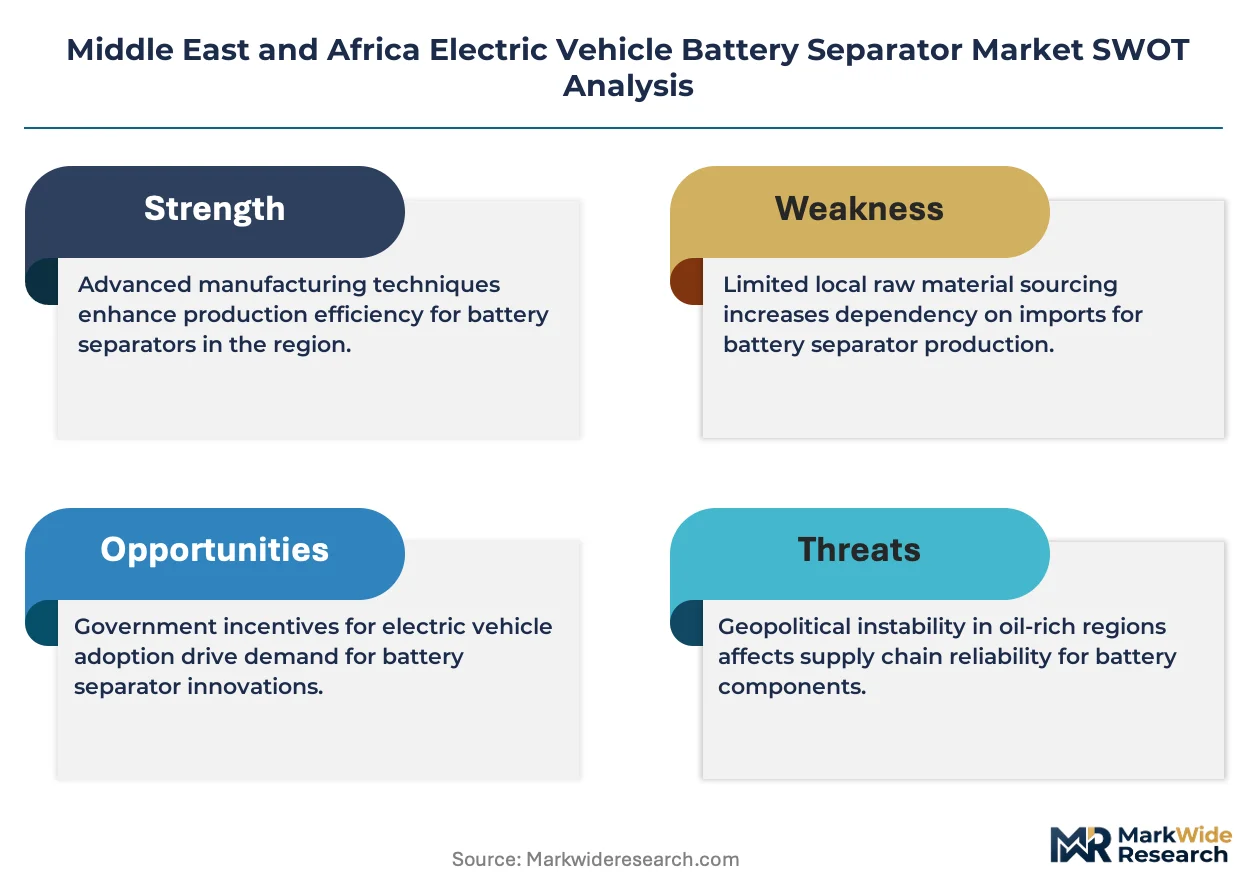
- Polyolefin feedstock price volatility:Separator manufacturers face margin compression when propylene and ethylene input costs spike, particularly affecting dry-process producers with thinner raw material buffers.
- Import dependency for ceramic coating precursors:Regional separator finishers rely on East Asian alumina and boehmite supply, creating concentration risk across Red Sea shipping lanes.
- Thickness-performance tradeoff in thin-film separators:Sub-12-micron membranes struggle with mechanical integrity during high-rate cycling, limiting adoption in performance-oriented EV platforms.
Strategic Opportunities
- East African trade route electrification:Kenya and Ethiopia logistics corridors present underpenetrated demand for commercial vehicle separators as battery swapping infrastructure expands.
- Saudi Standards, Metrology and Quality Organization EV component harmonization:Unified Gulf technical standards reduce compliance fragmentation, enabling single-qualification market access across six economies.
- Ceramic-polymer hybrid coating convergence:Combining atomic layer deposition with conventional coating lines offers OEMs tailored thermal shutdown profiles without full ceramic substrate cost.
Industry Challenges
- Electrolyte compatibility testing capacity:Regional labs lack accelerated aging protocols for new-generation high-voltage electrolyte formulations, stretching separator validation timelines.
- South Africa National Regulator for Compulsory Specifications approval bottlenecks:Battery component safety benchmarks create six-to-nine-month product approval windows that mismatch just-in-time assembly schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Battery Separator Market |
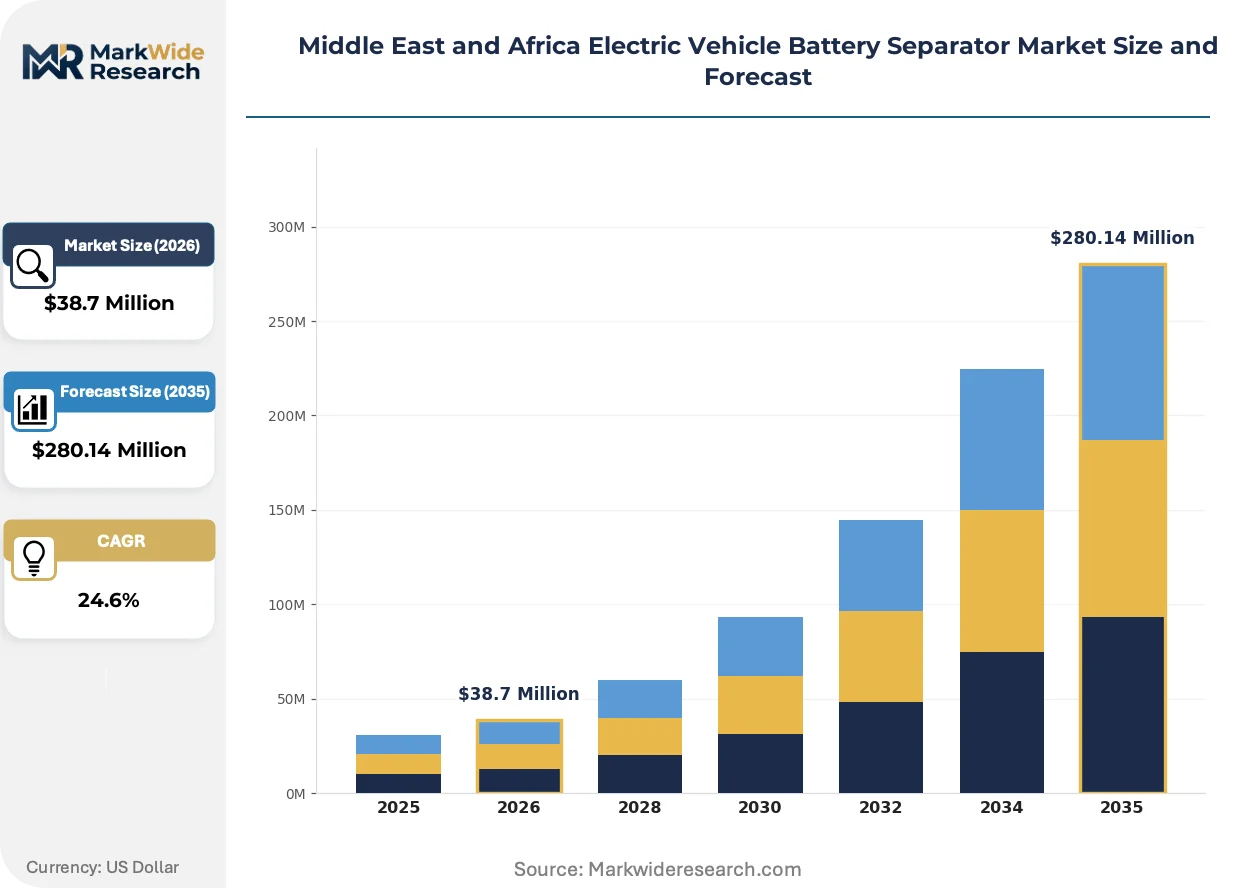
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $280.14 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Ceramic, Fiberglass, Composites End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electrospinning, Coating, Extrusion, Laminating Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles |
| Companies Covered | Entek International LLC, Toray International Inc., Sinoma Science & Technology Co., Ltd., UBE Corporation, Sumitomo Chemical Co., Ltd., Celgard, Asahi Kasei Corporation, SK IE Technology, SEMCO, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology trajectories in Middle East and Africa markets center on thermal resilience engineering, regulatory alignment with adjacent European markets, and procurement model compression as OEMs consolidate supplier bases.
Ceramic-coated polyolefin composites are absorbing the bulk of R&D investment from separator suppliers serving the region. Fleet operators in UAE and Saudi Arabia commercial vehicle programs specify these materials for their 150°C dimensional stability. The technology is absorbing share from uncoated polymer alternatives in premium EV platforms where thermal runaway propagation resistance commands price premiums.
Saudi Standards, Metrology and Quality Organization alignment with Gulf technical standards is eliminating regulatory fragmentation across UAE, Kuwait, Qatar, Bahrain, and Oman. Battery component safety protocols now require identical documentation for separator thermal shrinkage and puncture resistance. Commercial vehicle OEMs with regional assembly footprints are consolidating supplier qualification to single Gulf-compliant certification packages.
Long-term offtake agreements are displacing spot purchasing for ceramic-coated separator volumes. Tier-1 battery pack assemblers in South Africa and Morocco now contract directly with wet-process specialists for three-to-five-year supply commitments. This pattern is most visible in passenger vehicle programs where OEMs pre-secure separator capacity ahead of model launches, compressing distributor intermediation.
Middle East and Africa Electric Vehicle Battery Separator Market Segmentation
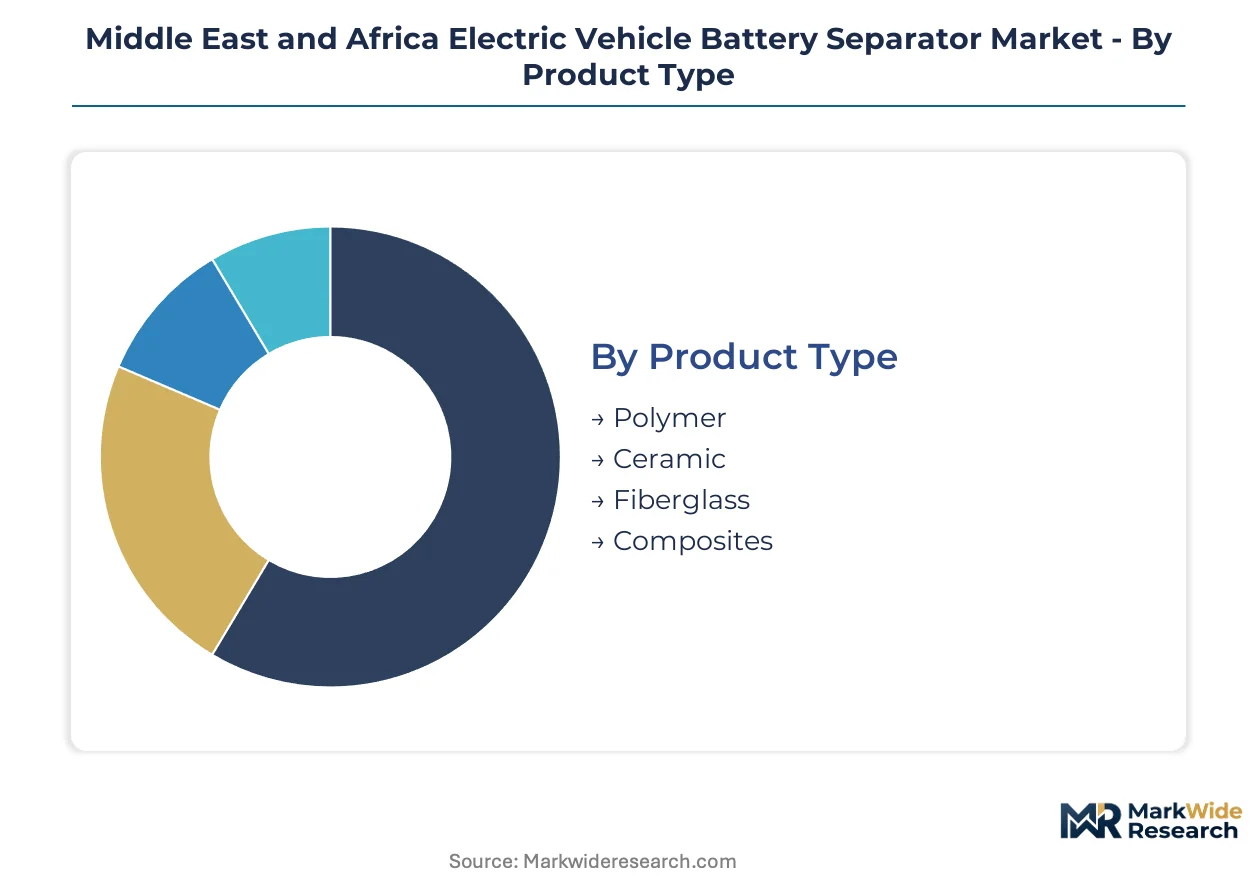
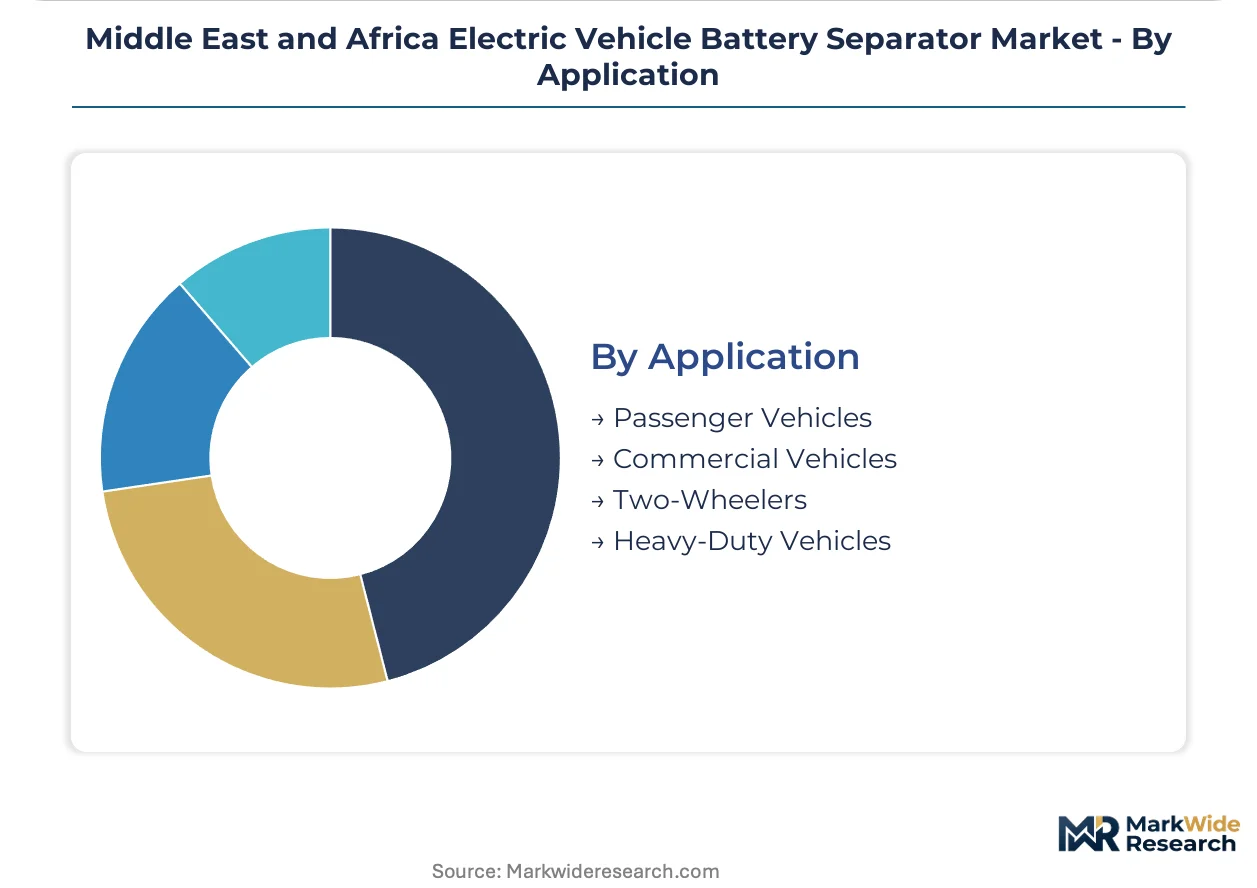
Separator procurement patterns across Middle East and Africa diverge sharply by thermal performance requirements, supply chain integration depth, and vehicle platform electrification timelines. Fleet operators in high-ambient-temperature corridors prioritize ceramic composites, while cost-sensitive two-wheeler assemblers in East Africa drive polymer volume.
Product Type:
Cost tier separates buyers into commodity polymer users versus premium ceramic adopters seeking thermal runaway protection.
- Polymer:Microporous polyolefin membranes manufactured through dry or wet extrusion dominate unit economics. Logistics electrification across Gulf Cooperation Council corridors pulls uncoated polymer demand from fleet operators balancing acquisition cost against baseline thermal stability.
- Ceramic:Alumina- or boehmite-coated substrates deliver 150°C dimensional stability for high-voltage battery architectures. South African automotive manufacturing hubs concentrate procurement of ceramic-coated separators as OEMs pre-secure capacity for premium passenger vehicle programs.
- Fiberglass:Woven glass fiber separators serve niche high-temperature cycling applications in heavy-duty commercial platforms.
- Composites:Hybrid polymer-ceramic laminates address thickness-performance tradeoffs for emerging fast-charging EV specifications.
Polymer leads volumes today; ceramic is gaining share fastest.
End User:
Supply chain position determines technical specification authority and contract tenure length.
- OEMs:Vehicle manufacturers with regional assembly footprints in Morocco and South Africa wield direct separator qualification power. Three-to-five-year offtake agreements with wet-process specialists compress distributor intermediation as battery pack designs freeze ahead of model launches.
- Aftermarket Providers:Independent battery rebuilders serving legacy EV fleets in Kenya and Ethiopia source spot-market polymer volumes. Import dependency for ceramic coating precursors across Red Sea shipping lanes constrains product mix expansion.
- Tier-1 Suppliers:Battery pack assemblers consolidate supplier bases around single Gulf-compliant certification packages. Saudi Standards, Metrology and Quality Organization harmonization reduces compliance fragmentation across six economies.
- Vehicle Assemblers:Contract manufacturers without full OEM status rely on tier-1 specification inheritance, limiting direct separator procurement influence.
Tier-1 suppliers anchor contract value; aftermarket channels are expanding most quickly.
Technology:
Manufacturing process selection locks in ionic transport consistency versus capital intensity tradeoffs.
- Coating:Ceramic slurry application atop polyolefin substrates absorbs the bulk of regional R&D investment. UAE and Saudi Arabia commercial vehicle programs specify coated materials for thermal propagation resistance, pulling wet-process specialists into direct OEM relationships.
- Extrusion:Dry and wet extrusion of microporous films remains the volume foundation for polymer separator production. South Africa's National Regulator for Compulsory Specifications enforces safety benchmarks that stretch validation timelines for new extrusion line qualifications.
- Electrospinning:Nanofiber web formation offers sub-12-micron thickness potential with mechanical integrity challenges limiting adoption.
- Laminating:Multi-layer bonding of dissimilar separator materials addresses electrolyte compatibility requirements for high-voltage formulations.
Extrusion commands installed capacity; coating climbs the fastest as thermal specifications tighten.
Application:
Vehicle platform duty cycle and ambient operating environment dictate separator thermal performance thresholds.
- Passenger Vehicles:Premium EV platforms in UAE and Saudi Arabia specify ceramic-coated separators for thermal runaway mitigation. Long-term offtake agreements pre-secure capacity ahead of regional model launches, consolidating procurement around qualified wet-process channels.
- Commercial Vehicles:Electric truck procurement across Gulf Cooperation Council logistics corridors pulls high-temperature-stable separator demand. Battery swapping infrastructure expansion along East African trade routes presents underpenetrated demand for commercial vehicle separator volumes.
- Two-Wheelers:Cost-sensitive electric motorcycle and scooter assemblers in Kenya and Ethiopia drive polymer separator volume with minimal coating requirements.
- Heavy-Duty Vehicles:Mining and port electrification applications in South Africa stress-test separator mechanical integrity under high-rate cycling.
Passenger vehicles dominate revenue; commercial vehicles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The battery separator industry traces its commercial origins to Japanese polymer extrusion innovations of the 1980s, subsequently scaling through South Korean wet-process maturation and Chinese coating technology diffusion. Middle East and Africa markets now absorb these technologies through import channels and emerging local finishing operations.
Saudi Arabia
Logistics electrification across GCC corridors pulls separator demand from fleet operators specifying thermal-stable materials. Saudi Standards, Metrology and Quality Organization harmonization with Gulf technical standards compresses compliance timelines for imported components. Riyadh-based battery pack assemblers pre-secure ceramic-coated separator capacity through three-year offtake agreements.
United Arab Emirates
Commercial vehicle OEMs in Dubai and Abu Dhabi specify ceramic-coated separators for 150°C dimensional stability in premium EV platforms. Ministry of Industry and Advanced Technology alignment with Gulf standards eliminates duplicate certification requirements. Jebel Ali industrial zones concentrate separator warehousing and distribution for re-export into African markets.
South Africa
Automotive manufacturing hubs in Gauteng and Eastern Cape concentrate procurement of ceramic-coated separators for premium passenger vehicle programs. National Regulator for Compulsory Specifications enforces six-to-nine-month safety benchmark approvals that stretch validation timelines. Port Elizabeth battery pack assemblers contract directly with wet-process specialists to bypass distributor intermediation.
Morocco
Passenger vehicle OEMs with regional assembly footprints leverage proximity to European markets for separator supply chain integration. EU Green Deal traceability mandates reshape sourcing decisions for components serving re-export manufacturing. Tangier Med industrial zone hosts battery pack operations sourcing through qualified wet-process channels.
Kenya
East African trade route electrification drives polymer separator volume for cost-sensitive electric truck and two-wheeler assemblers. Battery swapping infrastructure expansion along Mombasa-Nairobi logistics corridors presents underpenetrated commercial vehicle demand. Nairobi-based aftermarket providers source spot-market polymer volumes with minimal coating requirements.
Middle East and Africa Electric Vehicle Battery Separator Market Competitive Landscape
The competitive structure tilts toward technology-licensing specialists and wet-process scale operators. Regional market access concentrates around suppliers holding Gulf-compliant certification packages. Three archetypes dominate: North American ceramic-coated polymer exporters, East Asian wet-process extrusion specialists, and regional distributors managing import logistics. Capacity pre-commitments and direct OEM contracting displace traditional distributor relationships.
Among Japanese chemical conglomerates, Toray International Inc. and UBE Corporation exemplify the wet-process technology archetype. Sumitomo Chemical Co., Ltd. occupies a position within the specialty materials tier alongside Asahi Kasei Corporation. Korean suppliers SK IE Technology and SEMCO represent the coating-technology vector. North American presence concentrates through Entek International LLC. Chinese fabricators Sinoma Science & Technology Co., Ltd. anchor the cost-optimized polymer segment. Celgard exemplifies the ceramic-coated specialist archetype.
| Leading Market Players |
|---|
| Entek International LLC |
| Toray International Inc. |
| Sinoma Science & Technology Co., Ltd. |
| UBE Corporation |
| Sumitomo Chemical Co., Ltd. |
| Celgard |
| Asahi Kasei Corporation |
| SK IE Technology |
| SEMCO |
| Others |
Pricing and Supply Chain Analysis
Polyolefin feedstock volatility cascades through separator pricing tiers as propylene and ethylene input costs compress margins for dry-process manufacturers while wet-process specialists with thicker raw material buffers maintain pricing power across Gulf Cooperation Council procurement channels.
Pricing Analysis
Long-term offtake contracting dominates premium ceramic-coated volumes as Tier-1 battery pack assemblers in South Africa and Morocco lock in three-to-five-year supply commitments ahead of model launches. Price differentiation separates Gulf-compliant certified separators from spot-market polymer volumes, with thermal stability specifications and Saudi Standards, Metrology and Quality Organization alignment commanding premiums. Cost compression in uncoated polymer tiers is intensifying as East African two-wheeler assemblers drive volume procurement with minimal specification requirements. Fleet operators across GCC logistics corridors show lowest price sensitivity, prioritizing 150°C dimensional stability over acquisition cost.
Supply Chain Analysis
Gulf-compliant certification packages gate market access as Saudi Standards, Metrology and Quality Organization harmonization with UAE Ministry of Industry and Advanced Technology protocols eliminates duplicate qualification requirements across six economies. Manufacturing concentration centers on South Korea, Japan, and China for wet-process extrusion capacity, with ceramic coating precursors drawing from East Asian alumina and boehmite supply. Single-source vulnerability runs through Red Sea shipping lanes for coating material imports. Distribution feeds from Jebel Ali industrial zones into African re-export markets and direct OEM relationships in Riyadh and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa separator markets reward players capturing ceramic-coating premium tiers as logistics electrification and thermal runaway mitigation requirements shift procurement toward high-specification products with superior margin profiles.
For Market Incumbents: Anchor wet-process capacity commitments through direct OEM contracting in Morocco and South Africa, bypassing distributor intermediation that erodes margin capture. Deepen backward integration into ceramic coating precursor supply to mitigate Red Sea logistics concentration risk and defend against East Asian coating specialists expanding Gulf direct sales. For New Entrants and Emerging Players: Launch via battery swapping infrastructure partnerships along Kenya-Ethiopia logistics corridors, targeting underpenetrated commercial vehicle separator demand with cost-optimized polymer specifications. Pursue white-space capture in aftermarket rebuild channels serving legacy EV fleets in Nairobi and Addis Ababa before Tier-1 supplier consolidation closes access. For Investors and Strategic Acquirers: Consolidation pressure builds where wet-process technology scarcity intersects with Gulf certification bottlenecks, favoring acquisition of regional distributors holding Saudi Standards, Metrology and Quality Organization approval packages. Viability over the coming decade hinges on ceramic-coating capability maturation; monitor East African trade route electrification tender awards as inflection signal for commercial vehicle separator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Precursors | Captive alumina supply secures margin against Red Sea shipping disruption. |
| Gulf Certification Package Consolidation | Single-qualification access across Saudi Arabia, UAE, Kuwait, Qatar, Bahrain, and Oman reduces compliance cost. |
| Direct OEM Contracting | Three-to-five-year offtake agreements with South African and Moroccan assemblers displace distributor intermediation. |
| Battery Swapping Infrastructure Partnership | East African logistics corridor positioning captures commercial vehicle separator growth ahead of grid-scale charging. |
| Ceramic-Polymer Hybrid R&D Investment | Atomic layer deposition coating lines offer tailored thermal shutdown without full ceramic substrate cost. |
Research Methodology
Bottom-up battery pack production modeling reconciled against top-down separator import tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, Saudi Standards, Metrology and Quality Organization certification specialists, and East African aftermarket distributors combined with secondary validation from customs trade data, Gulf technical standards documentation, vehicle production databases, and battery pack assembly facility disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side capacity and trade flow observations.
Input-output matrices map separator consumption to EV platform launches across the analysis window, with segmentation dimensions spanning product type, end-user supply chain position, manufacturing technology, and vehicle application duty cycle. CAGRs derive from modeled unit demand expansion and value-per-unit trajectories tied to ceramic-coating adoption curves. Forecast inputs incorporate thermal specification tightening timelines from Gulf regulators and logistics electrification capex commitments from GCC fleet operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyolefin feedstock price spikes or Red Sea shipping lane disruptions. Projections reflect documented assumptions regarding Gulf harmonization implementation speed and East African infrastructure buildout cadence. A model refresh is warranted upon material change in Saudi Arabia electric truck procurement targets or ceramic coating precursor supply diversification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Battery Lug Market