
 United States Battery Manufacturing Equipment Market | 2026-2036
United States Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Battery Manufacturing Equipment Market Analytics
The Inflation Reduction Act's domestic content bonus credit structure is hardening requirements for US-sourced battery components. Durr AG leverages its coating and drying expertise to anchor electrode production lines for Midwest gigafactories. Hitachi High-Tech Corporation sustains its position in inspection and metrology systems critical to yield management. Schuler AG dominates mechanical forming presses for cell casing and module assembly.
United States Battery Manufacturing Equipment encompasses the specialized machinery used to produce electrochemical cells, including precision coating systems that apply active material slurries to copper and aluminum foils at tolerances below two micrometers. These systems enable the mass fabrication of lithium-ion, lead-acid, and nickel-metal hydride cells for transportation, grid storage, and portable electronics applications. Coating machines and drying ovens command the largest installed base, reflecting the capital intensity of electrode manufacturing. Testing systems represent the fastest-growing equipment category as manufacturers implement 100% inline defect detection to reduce scrap rates. Automated systems technology is capturing margin pools through software-defined process control and predictive maintenance integration.
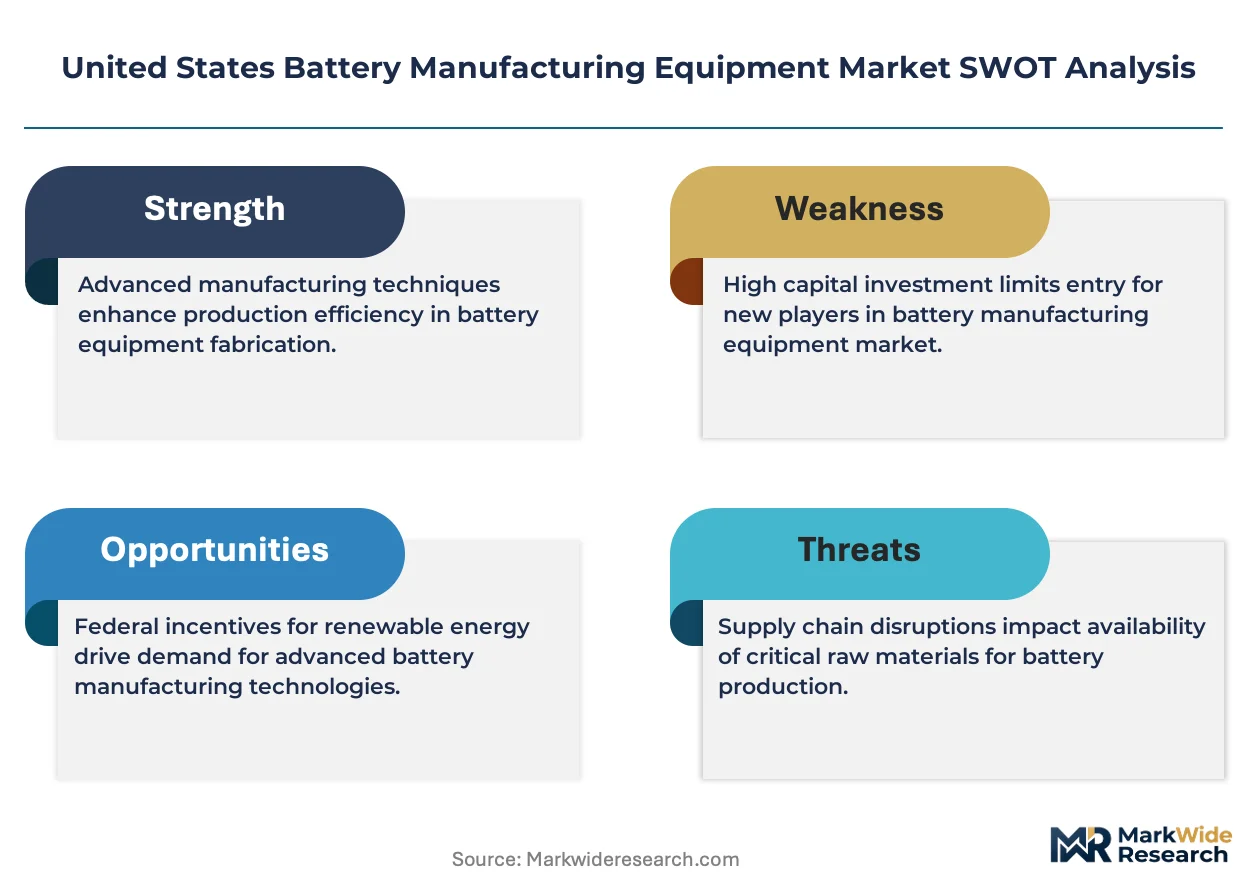
The EPA oversees emissions compliance for solvent-based coating operations, while OSHA mandates specific safeguards for dry room environments handling lithium electrolytes. The Department of Energy's loan programs and NHTSA's vehicle electrification mandates collectively steer procurement toward domestic equipment suppliers capable of certifying local content percentages. Stakeholders must weigh the trade-off between European and Asian equipment provenance and the IRA's escalating domestic assembly requirements when committing to multi-year production line investments.
Market Dynamics
The Inflation Reduction Act's domestic content bonus credit structure is hardening requirements for US-sourced battery components, redirecting capital toward Midwest and Sun Belt gigafactories while compressing procurement timelines for electrode coating and cell assembly equipment.
Growth Catalysts
- IRA Domestic Content Credits:The Inflation Reduction Act's escalating assembly requirements are forcing electric vehicle OEMs to source electrode coating systems and formation equipment from US-based suppliers, accelerating capital deployment toward Michigan and Texas manufacturing corridors.
- Transportation Electrification Mandates:NHTSA's vehicle electrification standards are compelling automakers to secure captive cell production capacity, driving sequential orders for precision coating machines and dry room infrastructure.
- Solid-State Cell Development:Next-generation solid-state electrolyte manufacturing requires specialized vacuum deposition and ceramic pressing equipment, opening new equipment categories beyond conventional lithium-ion wet coating processes.
Market Restraints
- Specialized Component Supply Concentration:Precision coating heads and laser inspection systems rely heavily on German and Japanese component suppliers, exposing US integrators to extended lead times and currency volatility.
- Dry Room Infrastructure Costs:Lithium-ion cell assembly requires humidity-controlled environments below 1% relative humidity, with HVAC and dehumidification systems representing 15-20% of total line capital expenditure.
- Electrolyte Handling Regulations:OSHA's process safety management requirements for flammable solvent storage and lithium hexafluorophosphate handling add compliance layers that extend facility commissioning timelines.
Strategic Opportunities
- Second-Life Battery Processing:Grid-scale energy storage operators are demanding automated disassembly and diagnostic equipment for retired electric vehicle packs, creating aftermarket equipment demand distinct from virgin cell manufacturing.
- Sodium-Ion Chemistry Transition:Sodium-ion electrode manufacturing eliminates copper current collectors and dry room stringency, enabling equipment suppliers to offer simplified coating lines at lower capital intensity for stationary storage applications.
- Department of Energy Loan Programs:The DOE's Advanced Technology Vehicles Manufacturing loan authority is de-risking equipment purchases for first-of-a-kind US cell factories, accelerating adoption of integrated formation and aging systems.
Industry Challenges
- Electrochemical Process Engineering Talent Scarcity:Gigafactory commissioning requires specialists in slurry rheology, coating defect analysis, and cell formation protocols, with US universities producing insufficient graduates to match facility ramp schedules.
- Multi-Technology Integration Complexity:Battery lines combine mechanical forming, thermal processing, vacuum systems, and inline metrology, requiring systems integrators to coordinate disparate equipment sub-suppliers under unified software architectures.
- EPA Air Permitting Timelines:Solvent-based electrode coating operations trigger New Source Review requirements that extend environmental approval cycles, compressing available windows for production line startup.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Battery Manufacturing Equipment Market |
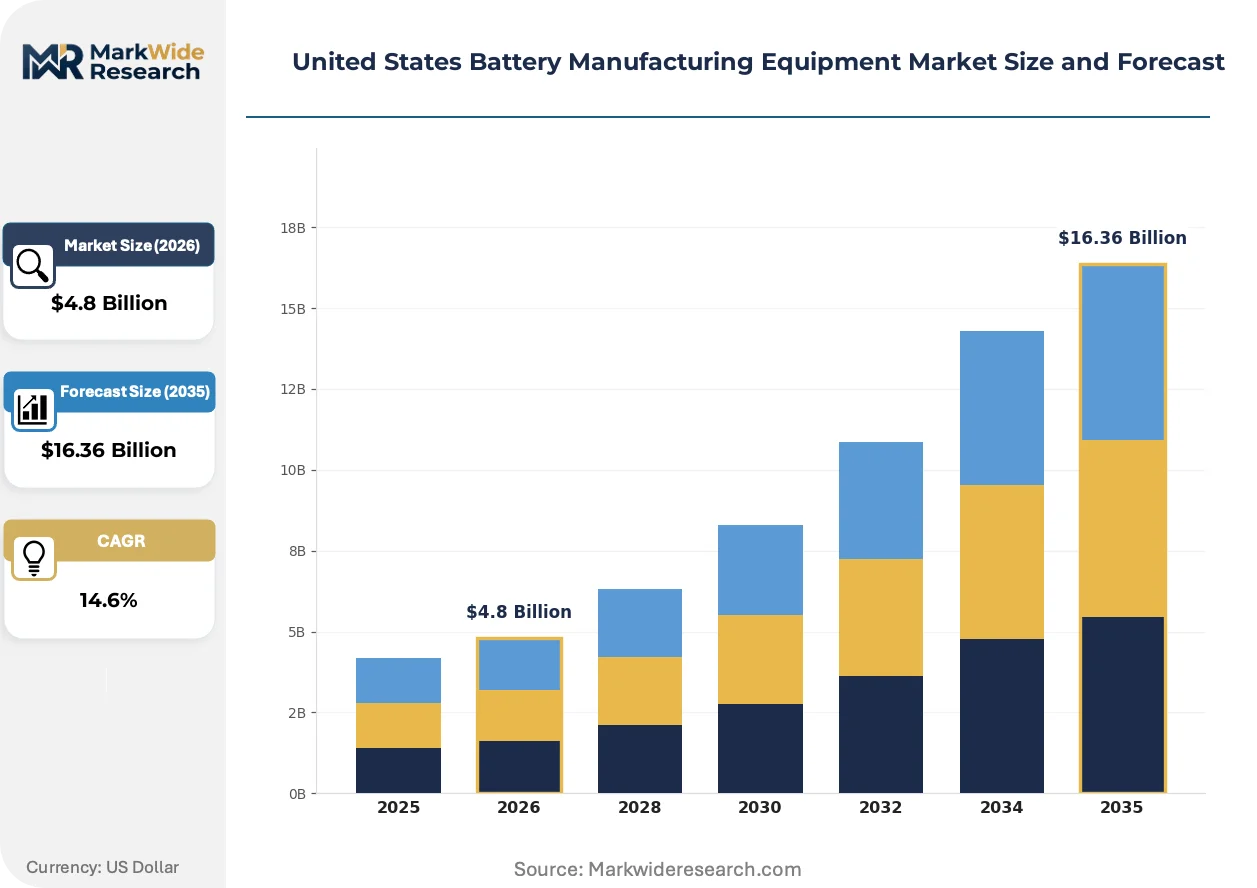
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Mixing Equipment, Coating Machines, Drying Ovens, Testing Systems Application: Lead Acid Batteries, Lithium-ion Batteries, Nickel Metal Hydride, Others End User: Automotive Manufacturers, Consumer Electronics, Energy Storage Solutions, Industrial Applications Technology: Electrochemical, Mechanical, Automated Systems, Safety Mechanisms |
| Companies Covered | Durr AG, Hitachi High-Tech Corporation, IPG Photonics Corporation, Xiamen Lith Machine Limited, Xiamen Tmax Battery Equipments Limited, Schuler AG, Manz AG, Nordson Corporation, ULVAC, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Battery Manufacturing Equipment Market Evolving Landscape
Digital thread integration across coating, calendering, and formation stages is compressing yield learning curves while predictive maintenance algorithms reduce unplanned downtime in continuous-flow electrode production.
Dry electrode coating technology is electrifying conventional battery manufacturing by eliminating solvent-based slurries and thermal drying ovens. Tesla and BMW are piloting Maxwell Technologies' dry bonding process at pilot scale in Nevada and South Carolina facilities. This shift is electrifying capital allocation toward mechanical calendering and electrostatic deposition equipment while de-emphasizing traditional coating and drying system investments.
The EPA's National Emission Standards for Hazardous Air Pollutants for battery manufacturing is tightening volatile organic compound capture requirements from electrode coating operations. Equipment suppliers must now integrate thermal oxidizers and solvent recovery systems as standard line components rather than optional add-ons. Midwest gigafactories in Michigan and Ohio are most affected, with several facilities delaying startup to install enhanced abatement systems.
Automotive OEMs are consolidating equipment procurement under single-source systems integrators rather than purchasing discrete machines from multiple vendors. This behavior concentrates negotiation leverage with Dürr, Manz, and Wuxi Lead Intelligent Equipment, displacing the prior model of direct relationships with coating, assembly, and testing specialists. The trend is most visible in Texas and Arizona, where Rivian, Tesla, and Lucid Motors have awarded turnkey line contracts.
United States Battery Manufacturing Equipment Market Segmentation
Equipment procurement patterns diverge sharply between integrated turnkey lines and standalone machines. Understanding these structural splits reveals where capital concentrates and which technology layers command pricing power.
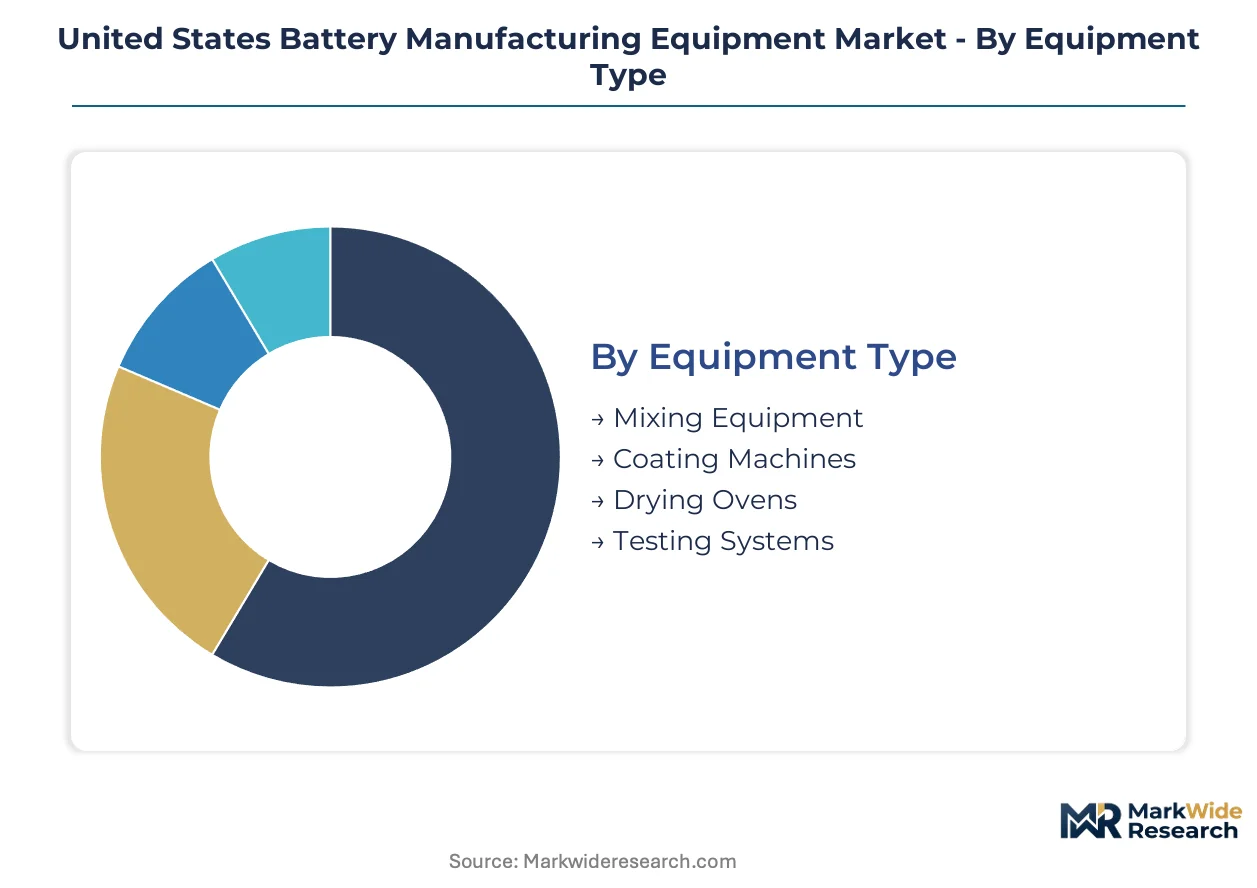
Equipment Type:
Standalone coating and drying systems dominate brownfield expansions, while greenfield gigafactories favor fully integrated electrode production modules.
- Coating Machines:Precision slot-die and comma-bar systems apply active material slurries to metal foils at sub-10-micron tolerances. Michigan and Texas gigafactories are standardizing on 1.6-meter web widths to match Korean and Chinese cell formats, compressing commissioning timelines for electrode lines.
- Testing Systems:Inline laser inspection and electrochemical impedance spectroscopy units enable 100% defect detection during formation cycling. These systems are displacing offline sampling protocols as IRA domestic content rules tighten traceability requirements for qualifying vehicles.
- Mixing Equipment:Twin-shaft planetary mixers with vacuum deaeration handle high-solids cathode slurries for NMC chemistries.
- Drying Ovens:Multi-zone infrared and convection systems remove NMP solvents from coated electrodes before calendering.
Coating machines lead volumes today; testing systems are gaining share fastest.
Application:
Process requirements vary by electrochemistry, with lithium-ion demanding the most capital-intensive dry room and formation infrastructure.
- Lithium-ion Batteries:NMC and LFP cell production requires precision coating, vacuum drying, and formation aging systems operating below 1% humidity. Arizona and Nevada facilities are optimizing equipment footprints for LFP chemistries to serve stationary storage and entry-level electric vehicle segments.
- Lead Acid Batteries:Mature grid casting and paste mixing equipment serves automotive starter battery and industrial backup applications with lower automation levels.
- Nickel Metal Hybride:Specialized sintering and impregnation systems support hybrid vehicle battery production with declining new capital deployment.
- Others:Emerging sodium-ion and solid-state chemistries require modified coating and assembly equipment still in pilot-scale validation.
Lithium-ion equipment dominates capital deployment; sodium-ion-compatible systems are expanding most quickly.
End User:
Automotive OEMs consolidate procurement under single-source integrators, while industrial buyers purchase discrete machines from specialized vendors.
- Automotive Manufacturers:Detroit Three and Tesla-affiliated suppliers demand turnkey electrode-to-module lines with unified software architectures and predictive maintenance integration. These buyers prioritize equipment provenance documentation to satisfy IRA assembly bonus credit thresholds.
- Energy Storage Solutions:Grid-scale battery integrators in Texas and California favor flexible formation systems accommodating multiple cell formats for utility-scale projects.
- Consumer Electronics:Cylindrical cell equipment for power tools and portable devices emphasizes compact footprint and rapid format changeover.
- Industrial Applications:Forklift and stationary backup battery producers maintain legacy lead-acid equipment with selective automation upgrades.
Automotive manufacturers absorb the largest equipment volumes; energy storage solutions are climbing the fastest.
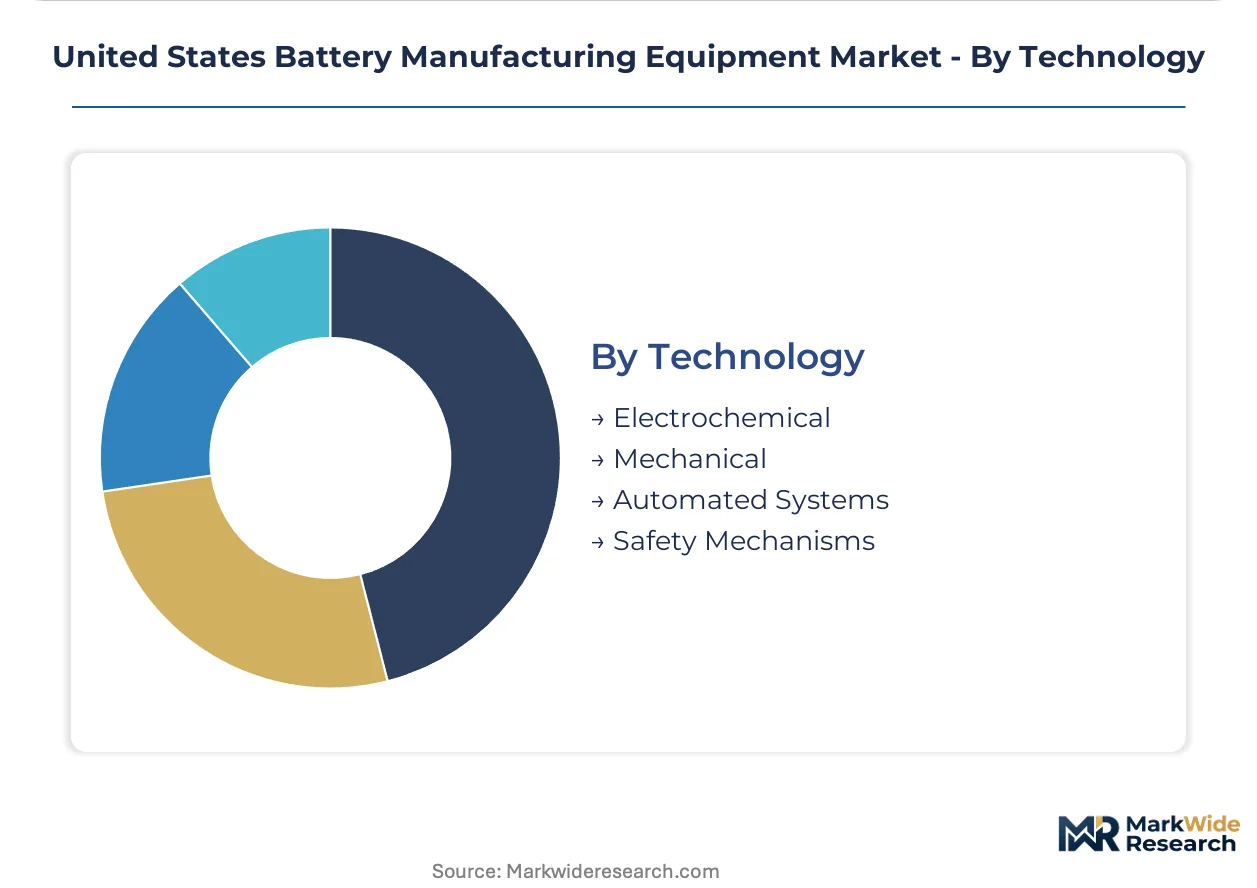
Technology:
Mechanical and electrochemical process layers anchor capital intensity, while automation and safety systems determine operational uptime.
- Automated Systems:Software-defined process control, robotic cell handling, and digital thread integration compress yield learning curves. Midwest gigafactories are mandating OPC-UA connectivity and AI-driven predictive maintenance as standard specifications rather than upgrade options.
- Electrochemical:Formation cycling, electrolyte filling, and aging systems determine cell performance consistency. These processes represent 25-30% of line capital expenditure and 40-50% of cycle time in lithium-ion manufacturing.
- Mechanical:Calendering, winding, and stacking equipment handles physical cell assembly with precision tolerance requirements.
- Safety Mechanisms:Dry room HVAC, fire suppression, and electrolyte containment systems address OSHA and NFPA compliance for flammable solvent handling.
Electrochemical process equipment leads installed value; automated systems are capturing margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical process engineers and battery manufacturing specialists cluster disproportionately in the Great Lakes industrial corridor and the Texas-Arizona Sun Belt manufacturing belt, anchoring equipment demand in these geographies.
Michigan
Detroit Three automakers and their tier-one suppliers are commissioning electrode coating lines at scale to satisfy IRA domestic content thresholds. The Michigan Department of Environment, Great Lakes, and Energy enforces air permitting for solvent-based coating operations. Holland and Grand Rapids host precision coating equipment integrators serving the broader Midwest gigafactory network.
Texas
Tesla, Rivian, and emerging cell producers are consolidating turnkey equipment procurement under single-source integrators in the Austin-San Antonio corridor. ERCOT grid stability concerns are driving demand for on-site formation and aging systems with backup power integration. Dallas-Fort Worth logistics hubs are becoming distribution points for Asian and European component suppliers.
Arizona
LFP chemistry optimization for stationary storage and entry-level electric vehicles is concentrating equipment specification expertise in Phoenix and Tucson metro areas. The Arizona Department of Environmental Quality administers New Source Review for coating operations. Mesa and Chandler host pilot-scale validation facilities for next-generation solid-state electrolyte manufacturing equipment.
Ohio
Legacy automotive supplier networks are retooling for cell module and pack assembly, creating demand for mechanical forming and welding equipment. The Ohio EPA is tightening volatile organic compound capture requirements for electrode coating lines. Lordstown and the broader Mahoning Valley are seeing brownfield industrial site conversions for battery manufacturing.
Nevada
Tesla's Gigafactory operations and Maxwell Technologies pilot facilities are validating dry electrode coating processes at commercial scale. The Nevada Division of Environmental Protection oversees emissions compliance for thermal processing equipment. Sparks and the Tahoe-Reno Industrial Center are becoming testbeds for solvent-free manufacturing technologies.
United States Battery Manufacturing Equipment Market Competitive Landscape
Capital-heavy equipment integrators compete with specialized component suppliers for margin capture across the battery production stack. The vendor base separates into turnkey line providers, standalone machine specialists, and precision sub-component fabricators. Three archetypes dominate: German-Japanese precision engineering houses, Chinese scale manufacturers, and US-based systems integrators serving IRA compliance requirements. Consolidation is accelerating through strategic partnerships between coating technology licensors and regional assembly specialists, while portfolio diversification into solid-state and sodium-ion compatible equipment broadens addressable market scope.
Among German precision engineering houses, Durr AG and Schuler AG exemplify the coating-to-assembly integration archetype, leveraging established automotive supplier relationships to anchor Midwest gigafactory contracts. Hitachi High-Tech Corporation represents the Japanese inspection and metrology specialization, occupying a position in yield-critical process control layers. Chinese scale manufacturers including Xiamen Lith Machine Limited and Xiamen Tmax Battery Equipments Limited sit within the cost-optimized equipment tier, serving brownfield expansions and price-sensitive stationary storage applications.
| Leading Market Players |
|---|
| Durr AG |
| Hitachi High-Tech Corporation |
| IPG Photonics Corporation |
| Xiamen Lith Machine Limited |
| Xiamen Tmax Battery Equipments Limited |
| Schuler AG |
| Manz AG |
| Nordson Corporation |
| ULVAC, Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up coating equipment specialists have consolidated Midwest electrode line integrators, tightening pricing discipline on turnkey contracts while compressing procurement timelines for IRA-compliant domestic content verification.
Pricing Analysis
Bundled turnkey electrode production modules command substantial premiums over unbundled standalone machines, with pricing stratifying across premium, standard, and economy tiers based on automation depth and UL certification status. Project-based contracting dominates greenfield gigafactory deployments, while brownfield expansions favor per-unit transactional purchasing of discrete coating and testing systems. Cost compression in standard-tier equipment is intensifying because Chinese manufacturers are penetrating the stationary storage segment. Automotive OEMs exhibit the lowest price sensitivity due to IRA credit compliance requirements, whereas industrial battery producers remain highly cost-conscious.
Supply Chain Analysis
Reverse-logistics flows for retired electric vehicle battery packs are creating secondary equipment demand streams distinct from virgin cell manufacturing, with automated disassembly systems feeding refurbishment and materials recovery operations. Precision coating heads and laser inspection subsystems draw from German and Japanese component fabricators, while complete machine assembly centers on US-based integrators in Michigan and Texas. Single-source vulnerability concentrates in ceramic pressing equipment for solid-state development. Distribution runs through direct OEM procurement channels with minimal distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States battery manufacturing equipment market functions as a geographic-arbitrage play, with Michigan and Texas production corridors capturing capital flows diverted from higher-cost European assembly operations by IRA domestic content incentives.
For Market Incumbents: Anchor market position through backward integration into precision coating head manufacturing to reduce dependency on German sub-suppliers and compress lead times for Midwest gigafactory contracts. Expand captive service organizations in the Texas-Arizona corridor to capture predictive maintenance revenue streams and lock out emerging Chinese competitors seeking aftermarket footholds. For New Entrants and Emerging Players: Digital-channel equipment financing platforms offer the most penetrable entry vector for sodium-ion-compatible coating line sales to price-sensitive stationary storage developers in California and Texas. Target second-life battery processing equipment as an underserved white-space segment with lower incumbent concentration and simplified dry room requirements. For Investors and Strategic Acquirers: Automotive OEM captive equipment divisions are the most active acquirer in this space, consolidating turnkey line integrators to secure IRA compliance documentation and vertical control over electrode production capacity. Acquisition targets with solid-state vacuum deposition expertise command strategic premiums. Monitor EPA New Source Review permit issuance timelines as the critical inflection signal for production line commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces lead time exposure to German and Japanese sub-suppliers for coating head assemblies. |
| Solid-State Equipment Portfolio Expansion | Captures emerging demand from BMW and Tesla pilot lines for ceramic pressing and vacuum deposition systems. |
| IRA Compliance Documentation Services | Enables automotive OEMs to satisfy domestic content bonus credit thresholds for qualifying vehicles. |
| Predictive Maintenance Platform Deployment | Compresses unplanned downtime in continuous-flow electrode production through AI-driven failure anticipation. |
| Sodium-Ion Compatible Line Development | Opens stationary storage segment with simplified coating equipment eliminating copper current collectors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gigafactory commissioning engineers, electrode line procurement directors, dry room HVAC specialists, and EPA air permitting officers with secondary validation against SEC equipment supplier filings, Department of Energy loan program disclosures, and NHTSA vehicle electrification mandate documents. Bottom-up equipment shipment tallies and top-down gigafactory capital expenditure estimates were cross-referenced to anchor volume figures.
Historical reference periods spanning pre-IRA and post-IRA implementation phases anchored the forecast window, with growth trajectories modeled across equipment type, application chemistry, end-user industry, and automation technology segmentation dimensions. CAGRs were derived from slope-intercept analysis of capital deployment curves and gigafactory announcement pipelines. Formation cycling system adoption rates and dry room infrastructure cost inflation served as industry-specific forecast sensitivity inputs.
IRA domestic content rule modifications, EPA New Source Review permitting delays, and solid-state technology maturation timelines are the dominant revision risks to the projection framework. Practitioners should monitor federal register notices for IRA guidance updates and state environmental agency permit backlogs for early signals of commissioning timeline compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Substation Battery Market