
 Germany Electric Vehicle Battery Separator Market | 2026-2036
Germany Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Separator Market Insights
Software-defined battery management is shifting how separator performance gets contracted, with OEMs now subscribing to real-time diagnostics that require separator-grade traceability. Asahi Kasei Corporation leverages its polymer science heritage to sustain premium positioning in microporous films. SK Innovation Co. Ltd. anchors supply relationships through integrated cell-separator co-development programs in European pilot lines. Toray Industries Europe GmbH competes on manufacturing scale from its regional extrusion base.
A Germany electric vehicle battery separator is a microporous or non-woven membrane, typically 5–30 micrometers thick, placed between anode and cathode to prevent electrical shorting while permitting lithium-ion transport; polyethylene and polypropylene dominate material stacks due to their shutdown safety behavior at thermal runaway temperatures. Microporous separators currently lead installed capacity, though composite architectures with ceramic coatings capture expanding margin pools as OEMs demand longer cycle life. Non-woven formats grow fastest among next-generation entries, particularly for solid-state cell interfaces where traditional films face mechanical compatibility limits. Battery Manufacturers represent the most concentrated end-user channel, with procurement consolidating around suppliers offering in-line quality verification.
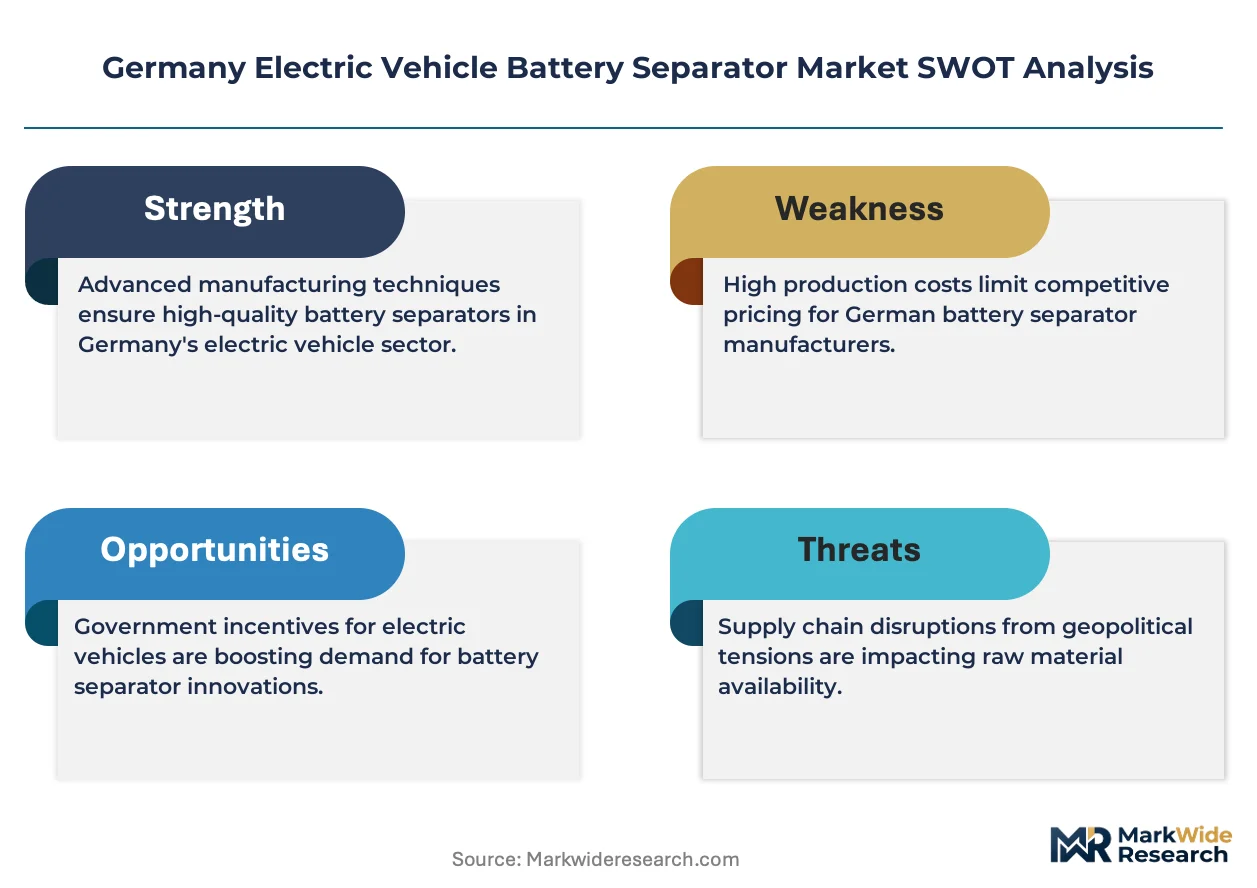
KBA type-approval protocols and the EU Battery Regulation shape separator specifications through mandatory carbon footprint disclosure and recycled content thresholds, while REACH restricts certain wetting-agent chemistries in coating formulations. Germany's national implementation of the EU Green Deal industrial plan channels R&D funding toward domestic separator substrate production, reducing reliance on Asian membrane imports. Stakeholders must monitor how solid-state cell timelines reshape separator thickness and porosity requirements before committing capacity expansion decisions.
Market Dynamics
Cell gigafactory clustering in Baden-Württemberg and Bavaria is concentrating separator procurement power among a handful of battery manufacturers, compressing supplier margins while elevating technical performance requirements. The EU Battery Regulation's carbon footprint disclosure mandates and recycled content thresholds are forcing substrate producers to reconfigure coating chemistries and sourcing strategies ahead of 2027 enforcement deadlines.
Growth Catalysts
- EU Battery Regulation mandates:Mandatory recycled content thresholds and carbon footprint disclosure requirements are accelerating domestic separator substrate production investments, reducing import dependence on Asian membrane suppliers.
- Solid-state cell interfaces:Next-generation battery architectures require non-woven separator formats with enhanced mechanical compatibility, opening specification windows beyond traditional polyethylene and polypropylene films.
- Baden-Württemberg engineering density:Proximity between automotive OEM technical centers and cell pilot lines enables rapid iteration cycles for separator-grade traceability systems integrated with software-defined battery management platforms.
Market Restraints
- Asian import concentration:Domestic production capacity for microporous substrates remains limited, exposing German cell manufacturers to supply chain disruptions from East Asian membrane specialists.
- REACH wetting-agent restrictions:Coating formulation adjustments to comply with restricted chemistry lists are extending qualification timelines and raising reformulation costs for ceramic-coated separator variants.
- Polyethylene price volatility:Feedstock cost fluctuations for shutdown-safety polymers are compressing margin pools at the commodity separator tier, disadvantaging non-integrated converters.
Strategic Opportunities
- Solid-state timeline acceleration:Ceramic-polymer composite architectures for sulfide and oxide electrolyte interfaces represent white-space specifications where European material science capabilities can anchor premium positioning.
- Bavaria pilot-line integration:Co-development programs between separator producers and cell manufacturers in regional extrusion corridors enable captive offtake arrangements with embedded quality verification systems.
- National Green Deal R&D funding:Federal industrial plan allocations for domestic substrate production create non-dilutive capital pathways for microporous film manufacturing scale-up.
Industry Challenges
- Polymer electrochemistry specialization:Scarce talent pools combining membrane physics with lithium-ion transport modeling are constraining in-house separator design capabilities at emerging German producers.
- KBA type-approval synchronization:Battery pack certification timelines are misaligned with separator qualification cycles, forcing parallel validation tracks that extend program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Separator Market |
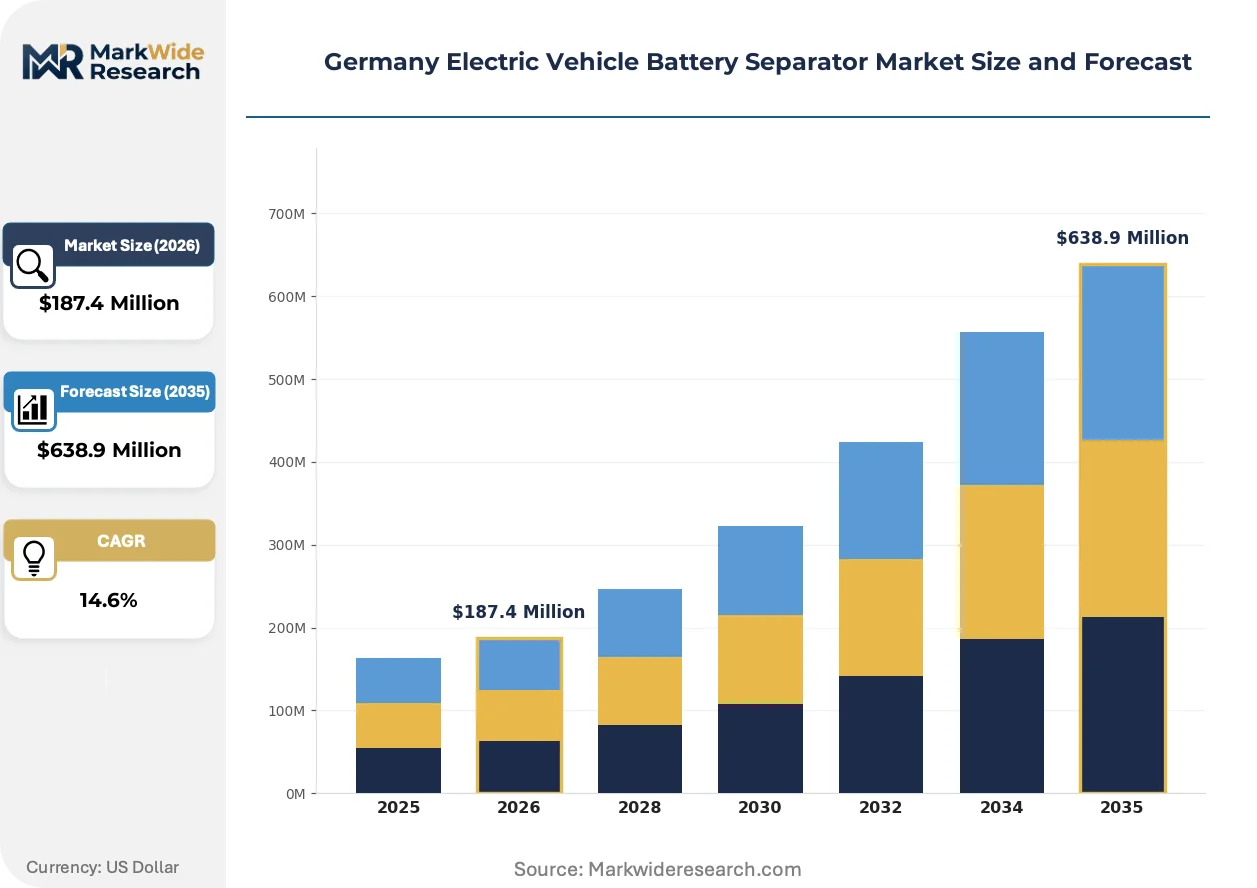
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microporous, Non-woven, Composite, Nano Material: Polyethylene, Polypropylene, PVDF, Ceramics End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Heavy-duty Trucks |
| Companies Covered | Contemporary Amperex Technology Co., Limited, SK Innovation Co. Ltd., Asahi Kasei Corporation, Brückner Maschinenbau GmbH, Toray Industries Europe GmbH, SEMCORP Advanced Materials Group, Coperion GmbH, Delfort Germany GmbH, Sepion Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Separator Market Trends and Innovations
In-line quality verification systems are embedding spectroscopic and dimensional inspection directly into extrusion and coating lines, collapsing the traditional batch-release timeline from days to minutes. Separator producers are racing to deploy these capabilities as table-stakes for OEM co-development programs.
Ceramic coating deposition is automating porosity control across separator surfaces, enabling sub-micron thickness uniformity that solid-state cell architectures demand. Battery manufacturers in Bavaria are specifying these systems for pilot-line trials. The technology is automating what previously required manual inspection intervention, compressing the defect-detection feedback loop.
REACH restrictions on perfluorinated wetting agents are forcing reformulation of ceramic coating binders, with ECHA guidance pushing producers toward bio-based surfactant alternatives. Reformulation timelines are extending qualification cycles by six to twelve months. High-voltage battery pack suppliers are absorbing these delays through buffer inventory strategies.
Subscription-based separator performance diagnostics are displacing traditional spot-purchase contracts, with OEMs demanding real-time traceability data as a service component. Battery manufacturers are consolidating procurement around suppliers offering integrated data packages. This shift is most visible in Baden-Württemberg, where Mercedes-Benz and Porsche cell engineering centers are mandating connected separator specifications.
Germany Electric Vehicle Battery Separator Market Segmentation
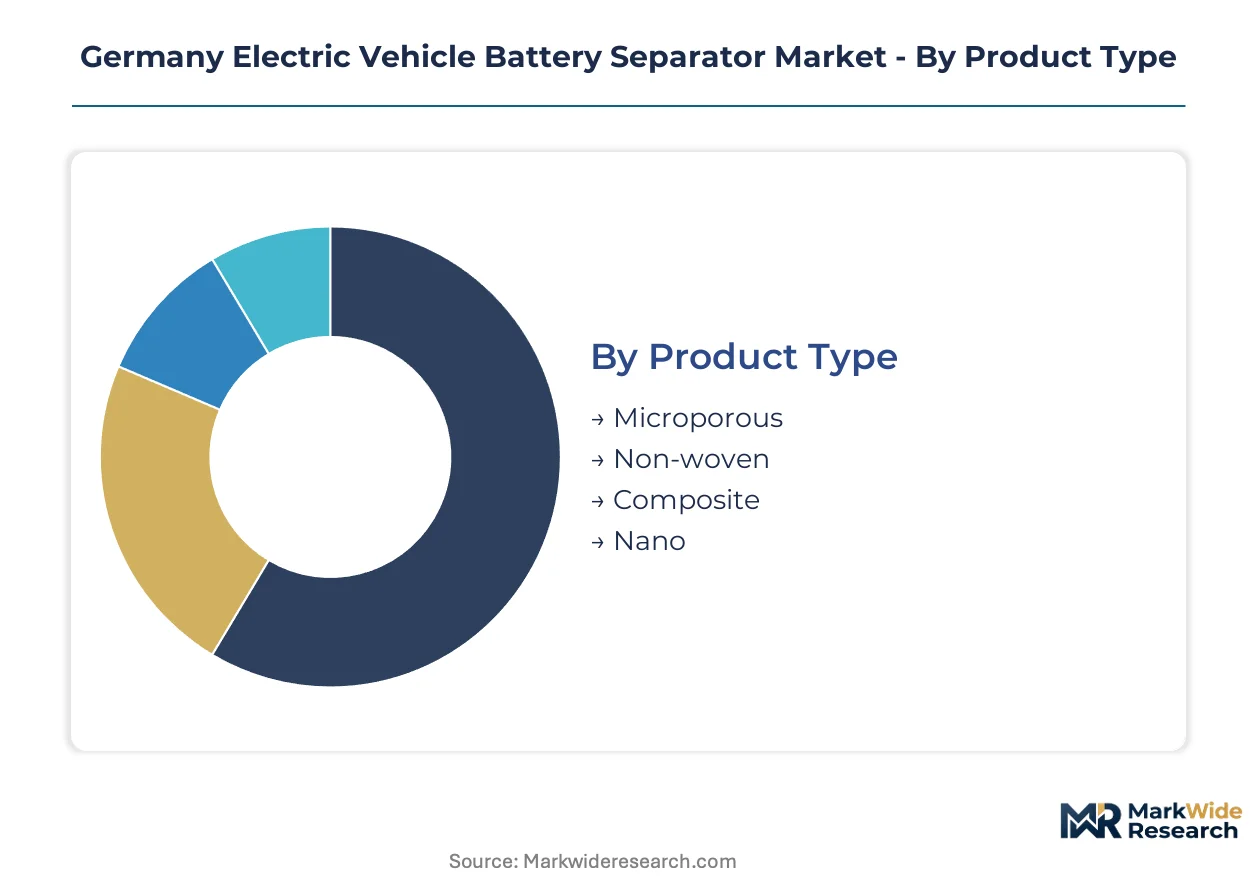
Separator procurement in Germany fragments across four distinct dimensions, each shaping supplier strategy differently. Product type determines manufacturing capital intensity, while end-user concentration in Baden-Württemberg and Bavaria compresses pricing power for commodity formats.
Product Type:
Supply concentration among battery manufacturers in southern Germany favors separator formats enabling rapid qualification cycles and integrated quality verification.
- Microporous:Polyethylene and polypropylene films dominate installed capacity, leveraging shutdown-safety behavior at thermal runaway temperatures. Procurement from Baden-Württemberg cell gigafactories concentrates around suppliers offering sub-20-micron thickness consistency for high-voltage packs. Ceramic coating integration is accelerating margin capture beyond commodity substrate tiers.
- Composite:Ceramic-polymer architectures capture expanding specification windows as OEMs demand longer cycle life and enhanced thermal stability. Bavaria pilot lines are specifying these formats for next-generation cell trials, embedding in-line porosity verification as a contractual requirement.
- Non-woven:Mechanical compatibility with solid-state electrolyte interfaces positions this format for sulfide and oxide cell architectures.
- Nano:Sub-micron precision films address emerging high-energy-density cell designs from Stuttgart engineering centers.
Today's leader: Microporous. Tomorrow's challenger: Composite.
Material:
Cost tier differentiation separates integrated polymer producers from coating-dependent converters facing REACH reformulation headwinds.
- Polyethylene:Shutdown-safety polymers anchor commodity separator stacks, though feedstock price volatility compresses margin pools at non-integrated producers. KBA type-approval protocols favor established PE substrate suppliers with validated thermal runaway documentation.
- Polypropylene:Higher melting points suit high-voltage battery architectures, with demand concentrating among Bavaria-based cell manufacturers specifying 130°C+ dimensional stability. Domestic extrusion capacity remains limited, exposing procurement to Asian import concentration risks.
- PVDF:Fluoropolymer binders face ECHA scrutiny under perfluorinated substance restrictions, extending qualification timelines.
- Ceramics:Alumina and silica coatings enable premium positioning through automated deposition systems controlling sub-micron uniformity.
Polyethylene commands current volume. Ceramics capture margin expansion.
End User:
Customer type determines contract structure, with software-defined diagnostics reshaping procurement from spot purchase to subscription-based performance verification.
- Battery Manufacturers:The most concentrated channel, with procurement consolidating around suppliers offering in-line quality verification and real-time traceability data. Baden-Württemberg and Bavaria gigafactories are mandating connected separator specifications integrated with battery management platforms.
- OEMs:Mercedes-Benz and Porsche cell engineering centers are driving subscription-based separator performance diagnostics, displacing traditional spot-purchase contracts with real-time traceability requirements.
- Fleet Operators:Secondary demand channel focused on replacement separator sourcing for refurbished battery packs.
- Aftermarket Providers:Fragmented procurement serving repair networks and independent battery refurbishers with limited specification leverage.
Battery Manufacturers anchor procurement volume. OEMs reshape contract terms.
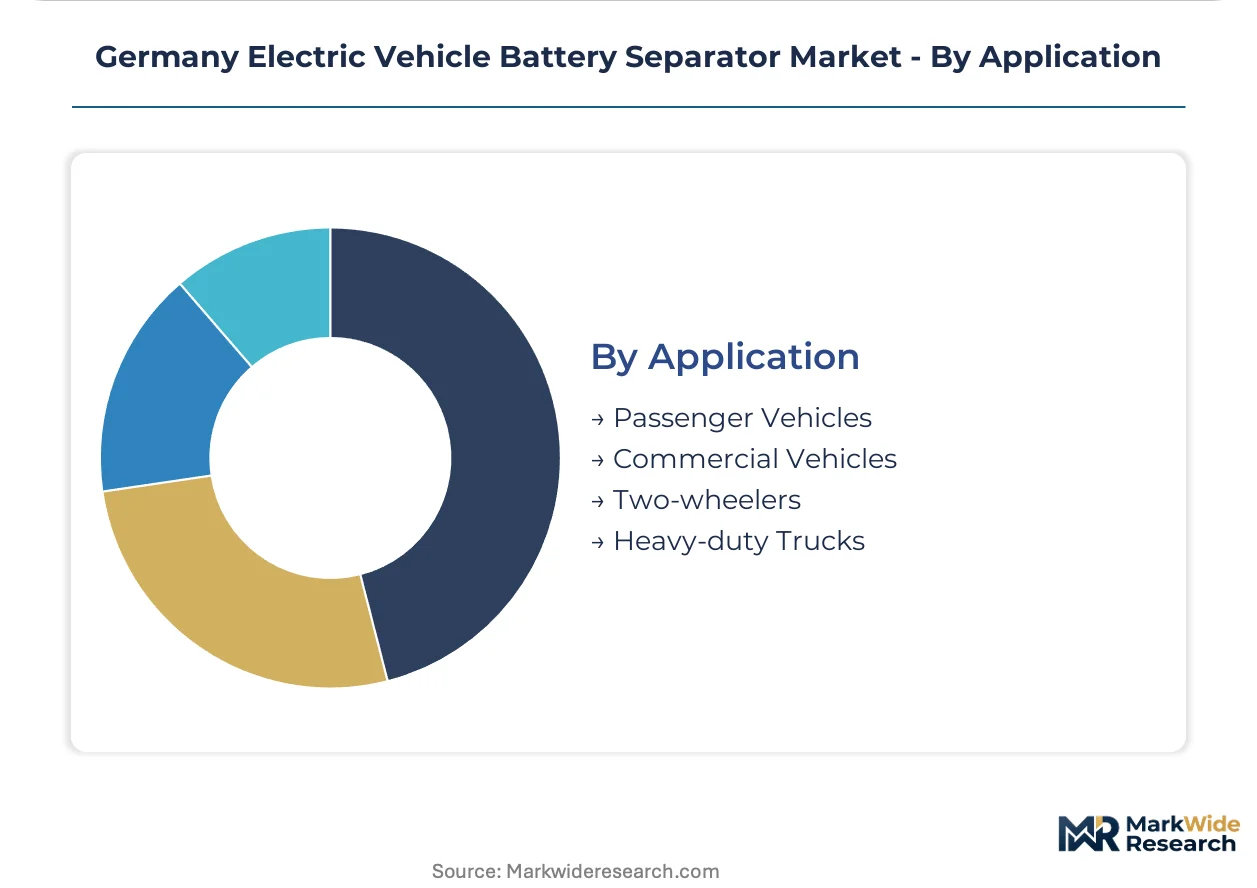
Application:
Volume concentration in passenger vehicles masks faster expansion trajectories in commercial electrification segments.
- Passenger Vehicles:German OEM high-voltage pack expansion drives separator demand scale, with Mercedes-Benz, BMW, and Volkswagen cell programs specifying ceramic-coated formats for premium segment battery architectures. EU Battery Regulation carbon footprint mandates are accelerating domestic substrate qualification.
- Commercial Vehicles:Heavy-duty electrification timelines are opening specification windows for non-woven separators with enhanced mechanical durability. Bavaria-based logistics fleet trials are testing separator formats for 500,000+ kilometer cycle life requirements.
- Two-wheelers:Niche demand from urban mobility startups with limited procurement scale.
- Heavy-duty Trucks:Emerging segment with prototype separator specifications for 1,000V+ architectures under development.
Passenger Vehicles dominate current procurement. Commercial Vehicles expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Germany are diverging in separator procurement strategies, with French cell manufacturers favoring ceramic-polymer composites while German gigafactories prioritize microporous substrates with integrated quality verification systems.
Bavaria
BMW and Northvolt pilot lines drive demand for non-woven separator formats compatible with solid-state cell architectures. The EU Battery Regulation's recycled content thresholds accelerate domestic substrate qualification programs. Munich engineering centers specify sub-micron thickness uniformity for next-generation high-voltage packs.
Baden-Württemberg
Mercedes-Benz and Porsche cell programs concentrate procurement power among battery manufacturers mandating real-time traceability data. KBA type-approval protocols favor established suppliers with validated thermal runaway documentation. Stuttgart's automotive engineering density enables rapid iteration cycles for separator-grade diagnostics.
North Rhine-Westphalia
Chemical industry heritage supports coating chemistry reformulation efforts responding to REACH wetting-agent restrictions. The region's polymer science research infrastructure attracts federal Green Deal R&D funding for domestic membrane production. Düsseldorf-based material suppliers are qualifying bio-based surfactant alternatives.
Lower Saxony
Volkswagen's Salzgitter cell factory anchors separator demand for high-volume electric vehicle platforms. National industrial plan allocations target extrusion capacity expansion to reduce Asian import dependence. Wolfsburg procurement teams are consolidating supplier relationships around integrated quality verification capabilities.
Hesse
Frankfurt logistics hubs facilitate separator distribution to southwestern cell gigafactories while hosting regulatory compliance services for EU Battery Regulation carbon footprint disclosure. The state's financial infrastructure supports battery supply chain investment vehicles. Darmstadt technical universities contribute polymer electrochemistry research talent.
Germany Electric Vehicle Battery Separator Market Competitive Landscape
Top-tier vendors anchor premium microporous and composite separator supply, while mid-tier converters compete on coating specialization and regional logistics proximity. The market structure concentrates procurement leverage among Baden-Württemberg and Bavaria battery manufacturers, compressing margins for non-integrated substrate suppliers. Three strategic archetypes dominate: integrated polymer producers with captive resin supply, coating-specialist converters with automated deposition systems, and equipment-technology hybrid vendors offering extrusion line integration. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing pilot-line integration commitments ahead of solid-state cell commercialization timelines.
Within the integrated polymer producer tier, Asahi Kasei Corporation and Toray Industries Europe GmbH exemplify scale-driven positioning anchored in regional extrusion infrastructure. SK Innovation Co. Ltd. occupies a distinct co-development specialist position, leveraging integrated cell-separator programs to secure captive offtake arrangements.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited |
| SK Innovation Co. Ltd. |
| Asahi Kasei Corporation |
| Brückner Maschinenbau GmbH |
| Toray Industries Europe GmbH |
| SEMCORP Advanced Materials Group |
| Coperion GmbH |
| Delfort Germany GmbH |
| Sepion Technologies |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's recycled content thresholds and carbon footprint disclosure mandates gate both qualified supply access and premium-tier pricing power, compressing margins for non-compliant converters while elevating ceramic-coated separator premiums among validated substrate producers.
Pricing Analysis
Capacity additions in Lower Saxony and North Rhine-Westphalia are reshaping price floors for polyethylene substrates, though Asian import concentration preserves premium capture for ceramic-polymer composites. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and in-line quality verification capabilities. Pricing pressure stems from feedstock volatility in shutdown-safety polymers, squeezing non-integrated converters. Battery manufacturers in Baden-Württemberg exhibit lowest price sensitivity due to subscription-based diagnostics mandates, while aftermarket providers face acute cost compression.
Supply Chain Analysis
Single-source vulnerability sits with East Asian microporous membrane specialists, exposing German cell manufacturers to logistics disruptions from South Korea, Japan, and China. Domestic production draws from polyethylene resin, ceramic coating precursors, and automated extrusion equipment. Tariff exposure on wetting-agent chemistries compounds REACH reformulation delays. Distribution runs through Bavaria and Baden-Württemberg gigafactory corridors with just-in-time delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany electric vehicle battery separator market functions as a regulatory compounder, where EU Battery Regulation enforcement timelines are accelerating demand for carbon-footprint-verified substrates ahead of qualification deadlines.
For Market Incumbents: Cement pilot-line integration commitments in Bavaria and Baden-Württemberg through co-development programs that embed real-time traceability systems. Deepen backward integration into ceramic coating deposition equipment to defend margin pools against REACH reformulation cost inflation. Prioritize KBA type-approval documentation for thermal runaway safety validation. For New Entrants and Emerging Players: Direct-to-cell-manufacturer digital channels offer white-space entry around non-woven separator formats for solid-state electrolyte interfaces. Target commercial vehicle pilot programs in Lower Saxony specifying 500,000+ kilometer cycle life requirements. Lead with automated porosity control capabilities that collapse qualification timelines versus incumbent batch-release systems. For Investors and Strategic Acquirers: Roll-up economics work for coating-specialist converters because ceramic deposition automation creates captive offtake moats with Bavaria battery manufacturers. Five-to-ten-year viability hinges on solid-state cell commercialization trajectories. Watch sulfide electrolyte interface specifications as the inflection signal for non-woven format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Coating Deposition | Captures margin pools beyond commodity substrate tiers while meeting EU Battery Regulation recycled content mandates. |
| Pilot-Line Co-Development Programs | Secures captive offtake arrangements with BMW and Northvolt in Bavaria through embedded quality verification. |
| Non-Woven Separator Format Development | Positions for sulfide and oxide solid-state electrolyte interfaces where traditional films face mechanical limits. |
| Subscription-Based Performance Diagnostics | Aligns with Mercedes-Benz and Porsche mandates for real-time traceability data as a service component. |
| Domestic Extrusion Capacity Expansion | Reduces import dependence on Asian membrane suppliers while qualifying for federal Green Deal R&D funding. |
Research Methodology
Coverage spans Germany's federal states with primary inputs from each, combining interviews with separator procurement leads at battery manufacturers, coating chemistry specialists at polymer producers, and regulatory compliance officers alongside secondary validation. Stakeholder inputs included KBA certification engineers, EU Battery Regulation implementation advisors, and equipment-technology hybrid vendors. Secondary sources encompassed ECHA guidance documents, federal industrial plan funding disclosures, and customs trade data for membrane imports. Bottom-up volume modeling triangulated against top-down value projections.
Granularity-level modeling addressed product type, material stack, end-user channel, and application segment across the projection horizon. Passenger vehicle and commercial vehicle applications were disaggregated by OEM platform and cycle life specification. CAGRs derived from production capacity buildout timelines, solid-state cell commercialization assumptions, and regulatory enforcement phasing. Industry-specific inputs included KBA type-approval synchronization delays and REACH reformulation qualification extensions.
The model assumes a particular technology adoption path; alternative pathways for sulfide solid-state electrolyte commercialization would alter the outlook for non-woven separator demand. Forecasts reflect assumptions around EU Battery Regulation enforcement timing, ceramic coating automation deployment rates, and domestic extrusion capacity scaling. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market