
 Europe Electric Vehicle Battery Separator Market | 2026-2036
Europe Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Separator Market Insights
Aftermarket separator refurbishment is reconfiguring margin pools away from virgin material supply toward cell regeneration services. Freudenberg SE leverages its non-woven expertise to anchor separator supply contracts with European cell manufacturers. SK ie technology competes through coating technology leadership, while Asahi Kasei Corporation sustains polyolefin dominance via integrated resin-to-film operations across the region.
Europe Electric Vehicle Battery Separators are microporous membranes, typically 5–30 micrometers thick, composed of polyolefin or ceramic-coated substrates that electrically isolate anode and cathode while permitting lithium-ion transport during charge and discharge cycles. Ceramic coating technology commands widening share as thermal runaway resistance becomes critical for high-energy-density cells. Polyolefin retains volume leadership in cost-optimized passenger vehicle applications, whereas glass fiber segments occupy niche positions in grid-scale energy storage where cycle stability outweighs weight constraints.
The EU Green Deal and REACH framework mandate recyclability thresholds and restricted substance controls that reshape separator material selection and end-of-life obligations for manufacturers. ECHA substance evaluations and CE marking requirements under the EU Battery Regulation create compliance gateways that favor producers with established European testing infrastructure. Stakeholders must monitor how evolving F-Gas Regulation amendments affect fluorinated binder chemistries used in ceramic coating formulations.
Market Dynamics
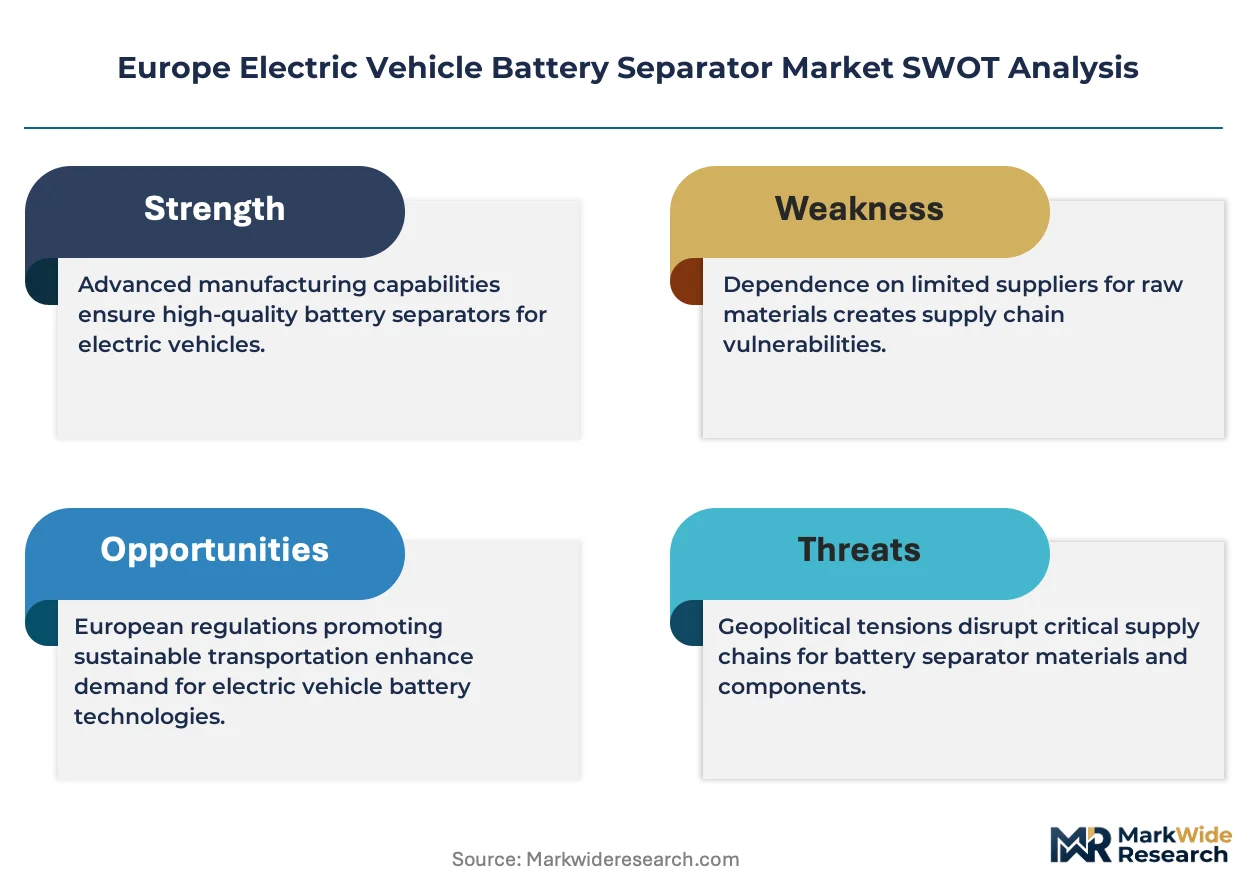
Ceramic coating technology is virtualizing separator procurement across European cell manufacturing, compressing the addressable market for uncoated polyolefin films while elevating thermal safety specifications as the primary purchasing criterion.
Growth Catalysts
- Fleet emission mandates:The EU Green Deal compels European OEMs to scale electric passenger vehicle output, directly expanding separator demand from gigafactory projects in Germany and Hungary.
- High-nickel cathode architectures:NMC 811 and NCA chemistries require ceramic-coated separators for thermal runaway resistance, pulling investment toward coating capacity expansion.
- REACH recyclability thresholds:End-of-life obligations under the EU Battery Regulation favor separator designs compatible with hydrometallurgical recovery processes.
Market Restraints
- Polypropylene resin concentration:Virgin polyolefin feedstock supply concentrates among petrochemical complexes in Belgium and the Netherlands, exposing converters to input cost volatility.
- Fluorinated binder dependency:Ceramic coating formulations rely on PVDF chemistries restricted under evolving F-Gas Regulation amendments, creating formulation uncertainty.
- Dry-process technical ceiling:Stretch-based separator manufacturing cannot achieve the sub-10 micrometer thickness required for next-generation 4680 cylindrical cells.
Strategic Opportunities
- Polish battery corridor:LG Energy Solution and SK On manufacturing presence in Wroclaw and Kobierzyce creates captive demand for localized separator supply.
- Cell regeneration services:Aftermarket separator refurbishment reconfigures margin pools toward diagnostics and remanufacturing rather than virgin material sales.
- Grid-scale storage ceramics:Glass fiber separator variants for stationary energy storage command premium positioning where cycle stability outweighs gravimetric density requirements.
Industry Challenges
- Coating technician scarcity:Sol-gel ceramic application and atomic layer deposition expertise concentrates among Asian equipment suppliers, constraining European talent pipelines.
- CE marking timeline compression:New EU Battery Regulation conformity assessment procedures extend certification cycles for novel separator architectures.
- Multi-layer lamination complexity:Integrating ceramic layers with polyolefin substrates requires cleanroom infrastructure that legacy film converters lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Separator Market |
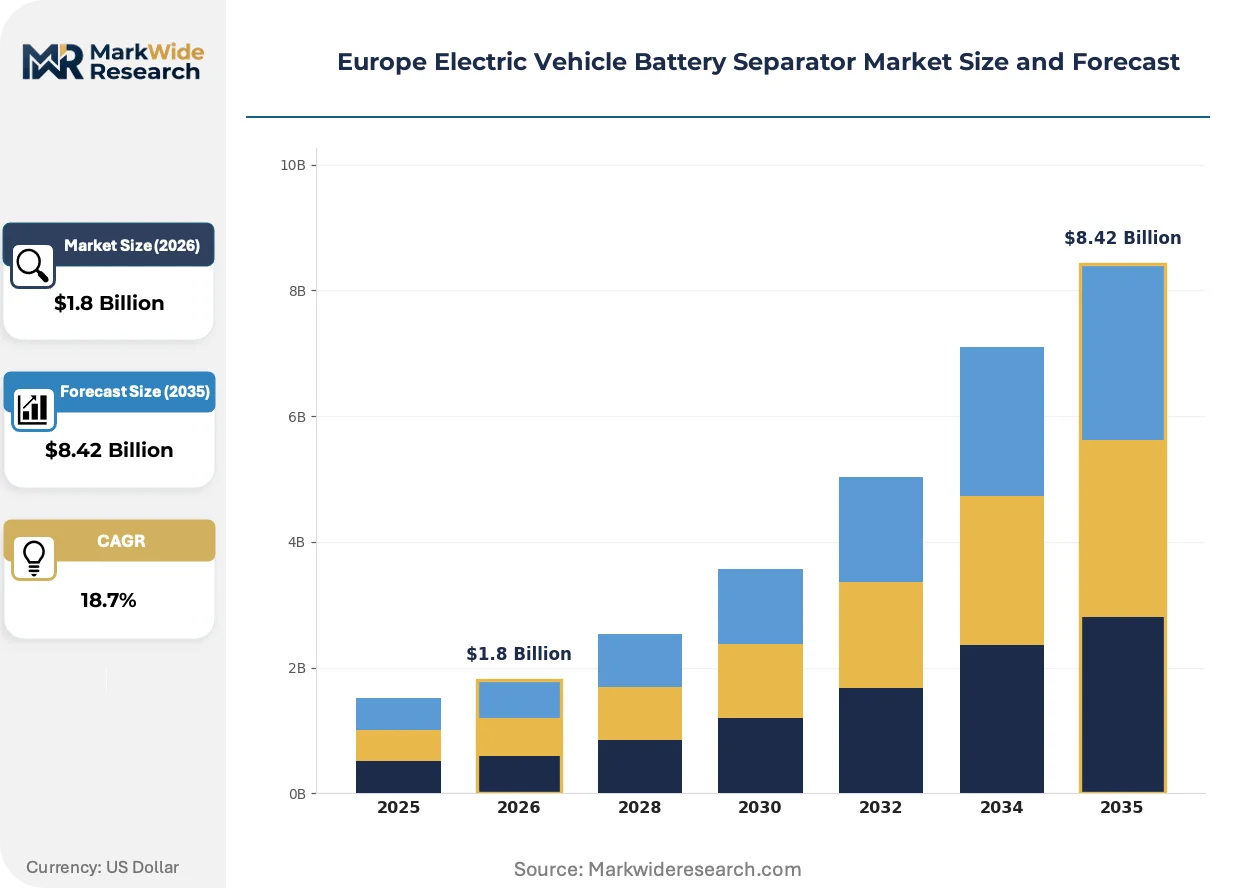
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, Cellulose, Glass Fiber, Non-woven End User: Passenger Vehicles, Commercial Vehicles, E-Bikes, Hybrid Vehicles Application: Energy Storage, Electric Mobility, Grid Applications, Consumer Electronics Technology: Sustainable Manufacturing, Coating Technology, Ultra-thin Separator, Ceramic Coating |
| Companies Covered | Toray Industries Inc., UBE Corporation, ENTEK International LLC, Bernard Dumas, Hollingsworth & Vose, Freudenberg SE, SK ie technology, Evonik Industries AG, Asahi Kasei Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology trajectories center on thermal safety elevation, regulatory-driven material redesign, and the unbundling of cell manufacturing from component supply. These forces compress traditional procurement patterns while opening specialized service layers.
Ceramic coating formulations incorporating aluminum oxide and boehmite nanoparticles are virtualizing the separator value proposition. European cell manufacturers specify coated substrates for all high-energy-density pouch and prismatic designs. The technology is virtualizing quality assurance protocols, replacing destructive testing with inline impedance spectroscopy and machine-vision defect detection.
The EU Battery Regulation's carbon footprint declaration requirements are reshaping material provenance rules. Separator producers must document upstream emissions from resin polymerization through film extrusion and coating application. German automotive OEMs now require supply-chain-specific LCA data for CE marking eligibility, favoring converters with integrated European resin-to-film operations.
Buyer concentration among gigafactory operators is consolidating procurement leverage. Volkswagen PowerCo, Northvolt, and ACC negotiate multi-year offtake agreements that displace spot-market transactions. Spanish and Italian industrial buyers report lengthened qualification timelines as cell manufacturers prioritize volume scale over supplier diversification.
Europe Electric Vehicle Battery Separator Market Segmentation
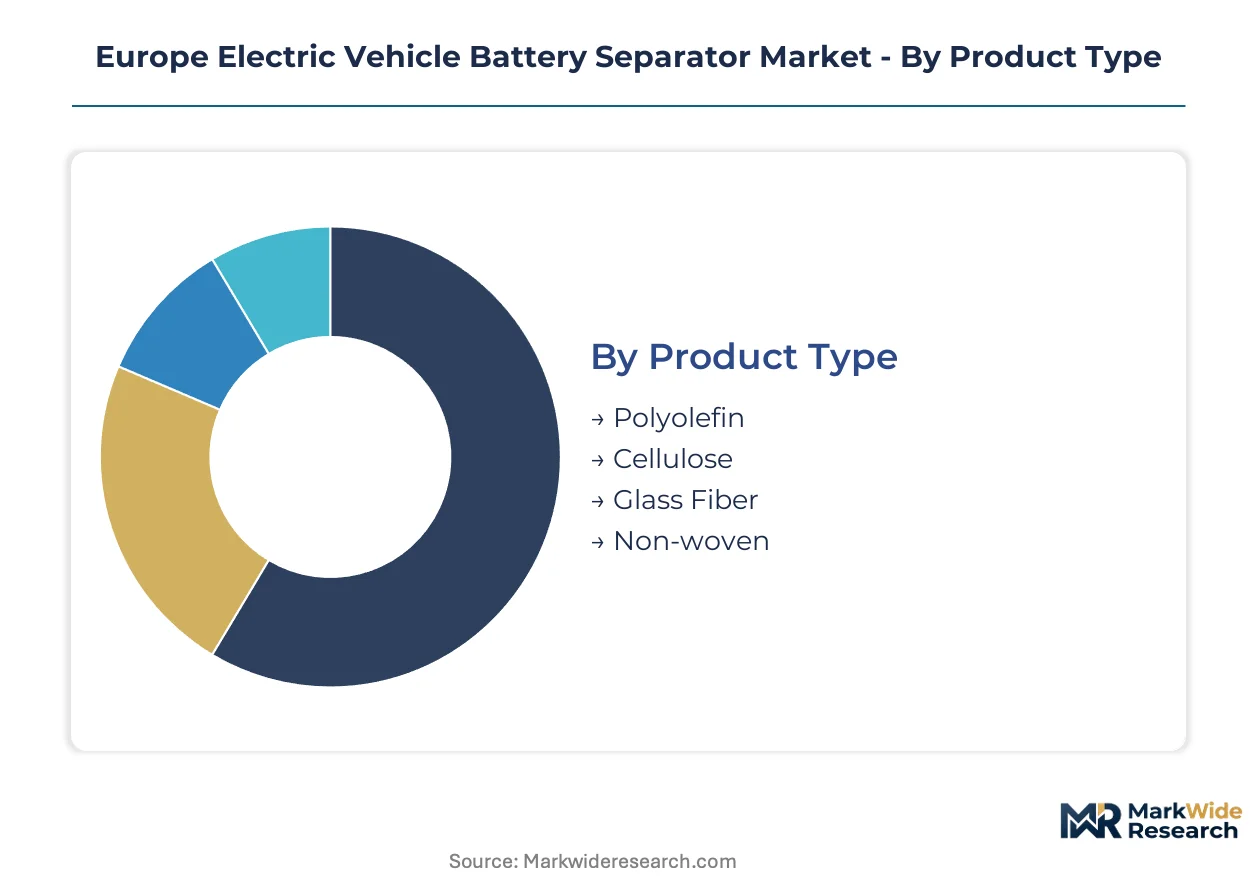
Separator procurement patterns diverge sharply across material chemistry, vehicle architecture, and manufacturing process maturity. European cell manufacturers specify different separator grades based on thermal safety thresholds, cost positioning, and recyclability compliance under EU Battery Regulation mandates.
Product Type:
Mature polyolefin films dominate installed capacity, while ceramic-coated and non-woven variants represent the emerging technology frontier for high-energy-density applications.
- Polyolefin:Microporous membranes of polyethylene or polypropylene, typically 12–25 micrometers thick, manufactured through wet or dry stretching processes. German automotive OEMs in Stuttgart and Munich specify uncoated polyolefin for cost-optimized mid-range passenger vehicles where thermal runaway risk remains manageable. REACH recyclability thresholds favor this substrate for hydrometallurgical recovery compatibility.
- Cellulose:Biodegradable separator substrates derived from wood pulp, offering superior electrolyte wettability compared to synthetic alternatives. Demand concentrates in French and Italian niche applications where end-of-life biodegradability outweighs mechanical durability constraints. The material faces thickness limitations below 20 micrometers that exclude high-power automotive cells.
- Glass Fiber:Non-flammable woven or non-woven mats with exceptional thermal stability exceeding 500°C. Grid-scale energy storage installations in Spain and Poland specify glass fiber where cycle stability trumps gravimetric density requirements.
- Non-woven:Synthetic fiber mats produced through electrospinning or melt-blowing, enabling tunable pore structures for specialized ion transport. Freudenberg SE anchors European supply through integrated non-woven manufacturing in Germany.
Polyolefin handles the majority of throughput; ceramic-coated derivatives are expanding most quickly on share as high-nickel cathode architectures proliferate.
End User:
Cost tier stratification separates mass-market automotive applications from premium and industrial segments with divergent performance specifications.
- Passenger Vehicles:Battery electric and plug-in hybrid cars from Volkswagen, BMW, and Mercedes-Benz constitute the volume anchor. Separator specifications prioritize thin-gauge films below 16 micrometers for pack energy density optimization. German PowerCo and Northvolt gigafactories drive procurement concentration.
- Commercial Vehicles:Heavy-duty trucks and buses require thicker separators with enhanced mechanical integrity for vibration resistance. Daimler Truck and Volvo Group operations in Sweden and Germany specify ceramic-coated substrates for thermal safety in high-duty-cycle applications.
- E-Bikes:Light electric two-wheelers utilize cost-optimized polyolefin separators in cylindrical 18650 and 21700 cell formats. Assembly operations in Portugal and Romania source standardized separator grades through distributor channels.
- Hybrid Vehicles:Full and mild hybrid powertrains demand separators optimized for high-rate partial state-of-charge cycling. Toyota and Hyundai manufacturing in the Czech Republic and Slovakia anchor regional demand for this segment.
Passenger vehicles absorb the dominant procurement volume; commercial vehicles are climbing the fastest as fleet electrification mandates tighten.
Application:
Volume scale separates mobility applications from stationary energy storage, with divergent margin structures and qualification timelines.
- Energy Storage:Stationary battery systems for residential, commercial, and industrial backup power. Glass fiber and thick polyolefin separators dominate where cycle life exceeds 6,000 cycles. Projects in Poland and Hungary prioritize cost-per-kWh over gravimetric density.
- Electric Mobility:Automotive and light transport applications requiring thin, mechanically robust separators. This application commands premium pricing for ceramic-coated substrates meeting OEM thermal runaway specifications.
- Grid Applications:Utility-scale storage with megawatt-hour configurations. Separator selection emphasizes fire safety certification and 20-year operational life. Spanish and Italian grid operators specify enhanced ceramic coatings for containerized battery installations.
- Consumer Electronics:Smartphones, laptops, and power tools utilizing small-format cylindrical or pouch cells. Separator thickness requirements below 12 micrometers favor wet-process polyolefin from Asian suppliers with established CE marking pathways.
Electric mobility commands the largest revenue pool; grid applications are gaining share fastest as renewable integration accelerates.
Technology:
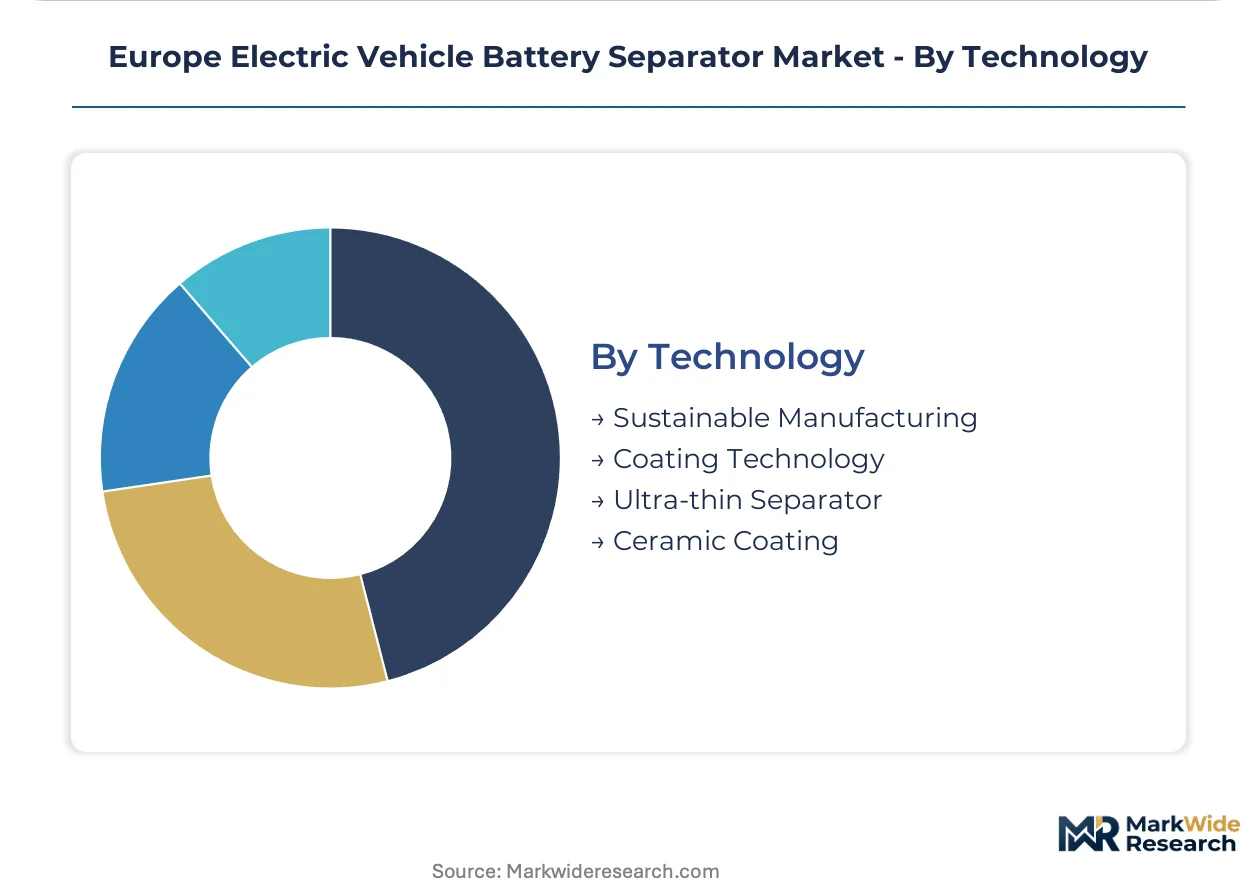
Manufacturing process maturity spans established extrusion methods through emerging coating and sustainability-focused production routes.
- Sustainable Manufacturing:Solvent-free processing, bio-based feedstocks, and closed-loop recycling integration. EU Green Deal carbon footprint declarations drive adoption among German OEMs requiring supply-chain-specific LCA documentation.
- Coating Technology:Sol-gel and atomic layer deposition of ceramic nanoparticles onto polyolefin substrates. SK ie technology and Asahi Kasei compete through coating uniformity and adhesion strength metrics.
- Ultra-thin Separator:Sub-10 micrometer films for next-generation 4680 cylindrical and large-format prismatic cells. Dry-process technical ceilings constrain European converter capabilities, creating import dependency.
- Ceramic Coating:Aluminum oxide and boehmite nanoparticle layers providing thermal shutdown resistance above 150°C. European cell manufacturers specify this technology for all NMC 811 and NCA chemistry implementations.
Conventional coating technology handles current volume; sustainable manufacturing processes are expanding most rapidly as CE marking eligibility tightens carbon documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European separator supply chains concentrate in Germany's automotive corridor, with coating capacity and resin-to-film operations clustering around Stuttgart, Munich, and Wolfsburg. Converter infrastructure in Belgium and the Netherlands handles virgin polyolefin feedstock, while emerging cell manufacturing in Poland and Hungary reshapes regional demand geography.
Germany
Volkswagen PowerCo's Salzgitter and Northvolt's Heide gigafactories drive separator procurement volume. The EU Battery Regulation's carbon footprint declaration requirements favor domestic converters with integrated European operations. Stuttgart anchors ceramic coating qualification centers serving BMW and Mercedes-Benz thermal safety specifications.
Poland
LG Energy Solution and SK On manufacturing presence in Wroclaw and Kobierzyce creates captive demand for localized separator supply. The country's national industrial regulator supports battery corridor development through investment incentives. Lower Silesia emerges as a secondary sourcing node reducing German supply chain concentration.
Hungary
Samsung SDI and CATL cell manufacturing investments in Debrecen and Gödöllő expand addressable separator demand. REACH compliance infrastructure attracts coating technology providers seeking EU market access. The Budapest-Debrecen industrial axis hosts emerging qualification laboratories for CE marking pathways.
France
Automotive Cell Company gigafactory construction in Douvrin and Billy-Berclau drives procurement specifications for high-nickel cell architectures. The EU Green Deal fleet emission mandates compel Renault and Stellantis electrification timelines. Hauts-de-France battery valley clusters separator logistics with cathode active material supply.
Sweden
Northvolt's Skellefteå gigafactory and R&D operations in Västerås prioritize sustainable manufacturing process adoption. The ECHA substance evaluation framework shapes local material selection for recyclability compliance. Norrbotten's renewable energy infrastructure supports carbon footprint reduction for CE marking eligibility.
Europe Electric Vehicle Battery Separator Market Competitive Landscape
Integrated resin-to-film operators and specialized coating technology providers split the market structure. The vendor base concentrates among Asian-headquartered multinationals with European distribution infrastructure and regional European converters with automotive supply relationships. Three archetypes dominate: petrochemical-integrated film extruders, ceramic coating specialists, and non-woven materials diversifiers. Competitive dynamics center on multi-year offtake agreement negotiation and CE marking qualification timeline acceleration.
Among Japanese and Korean fabricators, Toray Industries Inc., UBE Corporation, and SK ie technology represent coating technology leadership archetypes. Freudenberg SE anchors the European non-woven specialist tier. Asahi Kasei Corporation exemplifies integrated polyolefin dominance through captive resin operations.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| UBE Corporation |
| ENTEK International LLC |
| Bernard Dumas |
| Hollingsworth & Vose |
| Freudenberg SE |
| SK ie technology |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| Others |
Pricing and Supply Chain Analysis
Belgian and Dutch petrochemical complexes concentrate virgin polypropylene feedstock supply, anchoring margin pools in resin-to-film conversion rather than raw material extraction. This upstream concentration forces European separator converters to absorb input cost volatility while gigafactory buyers consolidate procurement leverage through multi-year offtake agreements.
Pricing Analysis
EU Battery Regulation carbon footprint declarations dictate the pricing tier structure across the European separator market. Three-tier pricing structure across premium ceramic-coated, standard polyolefin, and economy uncoated grades separates OEM-qualified supply from distributor-grade alternatives. Cost compression in standard polyolefin intensifies because dry-process technical ceilings constrain European converter capabilities. E-bike and consumer electronics assemblers in Portugal and Romania exhibit highest price sensitivity, whereas German automotive OEMs prioritize thermal safety certification over unit cost.
Supply Chain Analysis
Export control regimes on atomic layer deposition equipment and sol-gel coating technology limit flows from South Korea and Japan to European converter facilities. Separator supply draws from South Korea, Japan, and China for ceramic coating machinery, Belgium and the Netherlands for polypropylene resin, and Germany for non-woven substrate expertise. Single-source vulnerability concentrates in ceramic nanoparticle supply for aluminum oxide and boehmite formulations. Distribution runs through just-in-time logistics corridors serving PowerCo, Northvolt, and ACC gigafactories with qualified material batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the European separator market as cell manufacturer qualification timelines extend and coating technician scarcity constrains incumbent expansion. Divergent thermal safety specifications between passenger vehicle and grid-storage applications create defendable niche positions.
For Market Incumbents: Pre-empt coating capacity bottlenecks by securing atomic layer deposition equipment orders before South Korean and Japanese export license queues lengthen. Anchor multi-year offtake agreements with Polish and Hungarian cell manufacturers before qualification windows close. Backward integration into ceramic nanoparticle supply reduces aluminum oxide cost exposure and secures CE marking pathway control. For New Entrants and Emerging Players: Establish a beachhead in glass fiber separator supply for Spanish and Italian grid-scale storage projects where cycle stability specifications exceed gravimetric density requirements. Target aftermarket refurbishment services in Germany's automotive corridor where cell regeneration margin pools displace virgin material sales. Lead with sustainable manufacturing process certification to satisfy EU Green Deal carbon footprint documentation requirements. For Investors and Strategic Acquirers: Capital is best deployed toward coating technology specialists with established CE marking pathways and captive equipment supplier relationships. Long-term viability hinges on qualification timeline acceleration capabilities rather than raw capacity scale. Monitor F-Gas Regulation amendment progress as an inflection indicator for fluorinated binder chemistry substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | SK ie technology and Asahi Kasei anchor supply contracts with PowerCo and Northvolt gigafactories. |
| Backward Integration into Resin | Freudenberg SE secures polypropylene feedstock through Belgian petrochemical partnerships. |
| CE Marking Qualification Acceleration | Converters with ECHA testing infrastructure reduce certification cycles for novel separator architectures. |
| Aftermarket Regeneration Services | Cell refurbishment reconfigures margin pools toward diagnostics rather than virgin material sales. |
| Sustainable Manufacturing Certification | German OEMs require supply-chain-specific LCA documentation for carbon footprint declarations. |
Research Methodology
Desk research of ECHA substance evaluations, EU Battery Regulation compliance databases, and customs trade data preceded structured interviews with separator procurement managers at European cell manufacturers, coating technology equipment suppliers, and petrochemical resin distributors. Primary fieldwork with gigafactory planning officers and ceramic coating R&D directors validated secondary findings on qualification timeline compression. Bottom-up volume estimates from individual production facility disclosures were triangulated against top-down demand projections derived from OEM electrification commitments.
Assumptions around EU Green Deal fleet emission mandate enforcement, REACH recyclability threshold implementation, and F-Gas Regulation amendment timelines were held fixed across the analysis window while ceramic coating adoption rates and cell manufacturer localization patterns were varied. Segmentation modeling incorporated material chemistry, vehicle architecture class, manufacturing process maturity, and regional production cluster dimensions. CAGRs were computed from annual growth rate progression analysis. Forecast inputs included gigafactory construction announcements, cathode chemistry transition roadmaps, and coating equipment order backlogs.
Stress conditions across resin price volatility, export license delays, and qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution pathways. Material shifts in EU Battery Regulation carbon footprint declaration requirements or F-Gas Regulation amendment scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market