
 Asia Pacific Electric Vehicle Battery Separator Market | 2026-2036
Asia Pacific Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle Battery Separator Market Insights
Multi-source procurement strategies among Korean cell manufacturers is rebalancing supply chain risk away from Japanese incumbents. SK Innovation Co. Ltd leverages its integrated petrochemical base to sustain captive separator output for in-house cell plants. UBE Corporation anchors high-purity polypropylene membrane supply to Japanese and Southeast Asian battery makers. Yunnan Enjie New Materials Co. Ltd dominates domestic Chinese supply through wet-process polyethylene capacity expansion.
Electric vehicle battery separators are microporous membranes, typically 10–30 micrometers thick, that physically isolate anode and cathode while permitting lithium-ion transport between electrodes. Polyethylene and polypropylene wet-process films retain cost leadership for mainstream cylindrical and prismatic cells, though ceramic composite coatings command premium positioning in high-nickel cathode systems where thermal runaway resistance proves critical. Thin film and nano-structured technologies attract R&D allocation from cell makers seeking energy density gains, yet micro-porous platforms still occupy the majority of installed manufacturing equipment. Coating technology segments—ceramic alumina, PVDF, and aramid layers—differentiate on safety certification tiers rather than base chemistry alone.
China's MIIT enforces GB/T battery safety standards that mandate separator performance under nail penetration and overcharge scenarios, directly shaping product qualification requirements for domestic and export-bound suppliers. South Korea's KATS aligns with IEC 62660 cell testing protocols, while Japan's METI subsidizes next-generation solid-state separator research through its Green Innovation Fund. Manufacturers must monitor how these regulatory frameworks evolve around solid-state battery timelines and whether ceramic coating specifications become mandatory rather than premium-tier features.
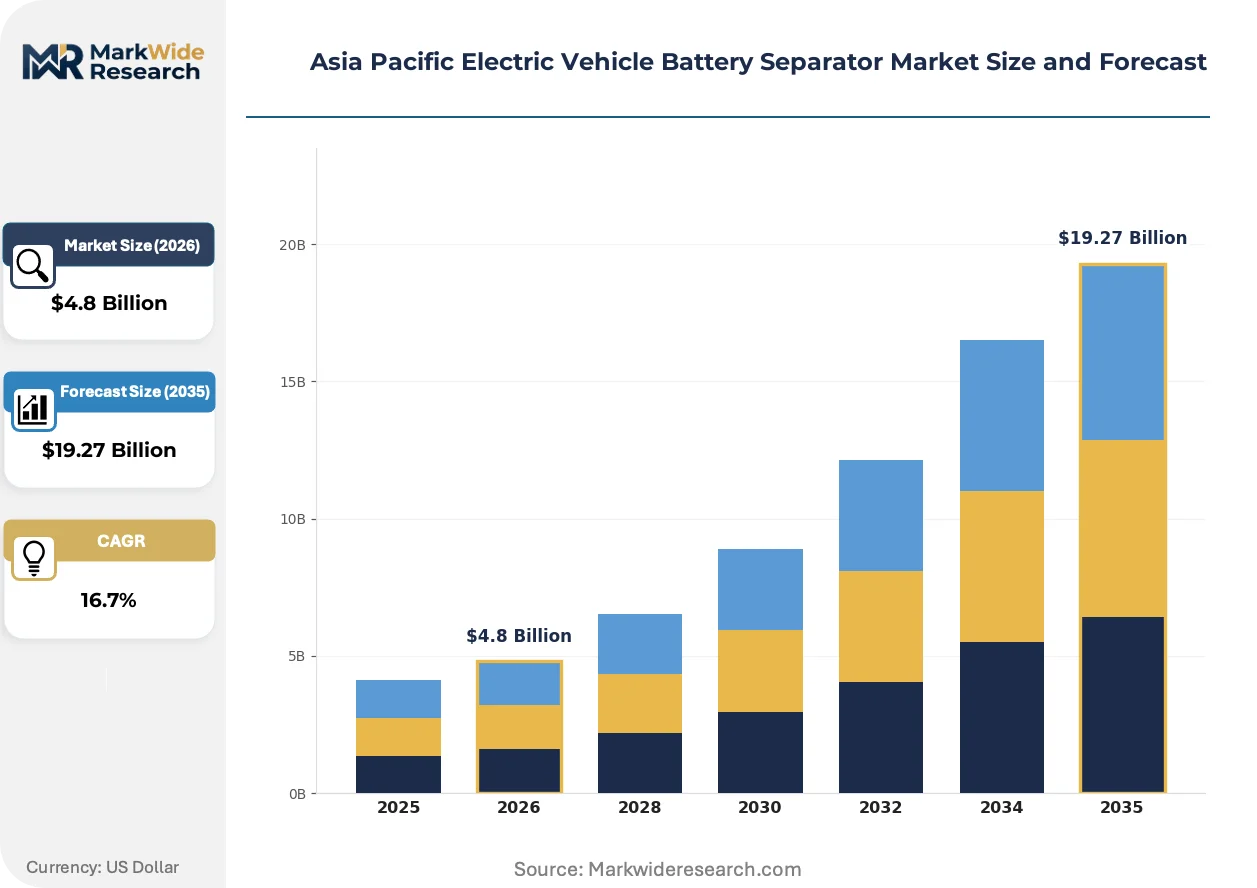
Market Dynamics
China's MIIT safety mandates and South Korea's cathode-anode-separator industrial clustering are compressing qualification timelines while concentrating supply capability in specific coastal manufacturing zones.
Growth Catalysts
- MIIT GB/T Battery Safety Standards:China's mandatory nail penetration and overcharge testing protocols force separator upgrades across domestic and export-bound production lines.
- High-nickel cathode chemistry:NCM 811 and beyond drive ceramic-coated separator penetration for thermal runaway resistance in premium electric vehicle platforms.
- Ulsan-Gumi industrial corridor:South Korea's integrated cathode-anode-separator clustering reduces logistics friction and accelerates joint qualification cycles.
Market Restraints
- Polypropylene feedstock volatility:Separator margins compress when propylene monomer prices spike, hitting non-integrated manufacturers hardest.
- Japanese incumbent concentration:UBE Corporation and Toray Industries control high-purity wet-process capacity, creating single-source risk for Korean cell makers.
- Solid-state battery substitution timeline:Next-generation solid electrolytes threaten to eliminate microporous membrane demand by the mid-2030s.
Strategic Opportunities
- Southeast Asia cell manufacturing:Indonesia and Thailand's emerging battery plants lack qualified local separator supply, creating first-mover qualification windows.
- Aramid coating technology:PVDF-alternative ceramic-aramid composites command premium positioning in aviation and heavy-duty vehicle segments.
- Japan's METI Green Innovation Fund:Subsidies for solid-state separator R&D offer co-development pathways for materials suppliers with Japanese cell makers.
Industry Challenges
- Thin-film manufacturing talent scarcity:Biaxial stretching and precision coating expertise concentrates in Japan and Korea, constraining Chinese capacity ramp timelines.
- Dual certification burden:Suppliers must simultaneously qualify under China's GB/T, South Korea's KATS-aligned IEC 62660, and OEM-specific protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle Battery Separator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Composite, Ceramic End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Application: Electric Vehicles, Hybrid Vehicles, Energy Storage, Grid Applications Technology: Thin Film, Micro-porous, Nano-structured, Coating |
| Companies Covered | Senior plc, UBE Corporation, SK Innovation Co. Ltd, Hitachi Chemical Company Ltd, Teijin Ltd, Mitsubishi Chemical Group Corporation, Sembcorp Industries Ltd, Yunnan Enjie New Materials Co. Ltd, Toray Industries Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle Battery Separator Market Trends and Innovations
Ceramic composite coatings, regulatory pressure on thermal safety, and procurement consolidation among tier-one cell makers are restructuring how separator value gets captured across the Asia Pacific supply base.
Alumina ceramic coating is electrifying the high-nickel cathode segment by delivering the 150°C thermal shutdown resistance that base polyethylene films cannot achieve. SK Innovation and CATL have made ceramic-coated separators standard for their flagship cell platforms. This technology is electrifying the competitive hierarchy, forcing non-integrated suppliers to license coating IP or exit premium tiers entirely.
China's dual carbon goals and MIIT battery safety mandates are tightening separator performance thresholds faster than Western regulatory timelines. Domestic suppliers must now demonstrate nail penetration survival and overcharge tolerance to qualify for state-backed vehicle procurement. South Korean and Japanese exporters to China face parallel compliance burdens, compressing their product development cycles.
Cell makers are consolidating supplier rosters from six-plus qualified sources to three strategic partners per geography. Korean manufacturers now demand captive equity stakes or long-term offtake guarantees in exchange for volume commitments. This behavior is most pronounced in China's Yangtze River Delta, where CATL and BYD have squeezed independent separator margins through concentrated purchasing power.
Asia Pacific Electric Vehicle Battery Separator Market Segmentation
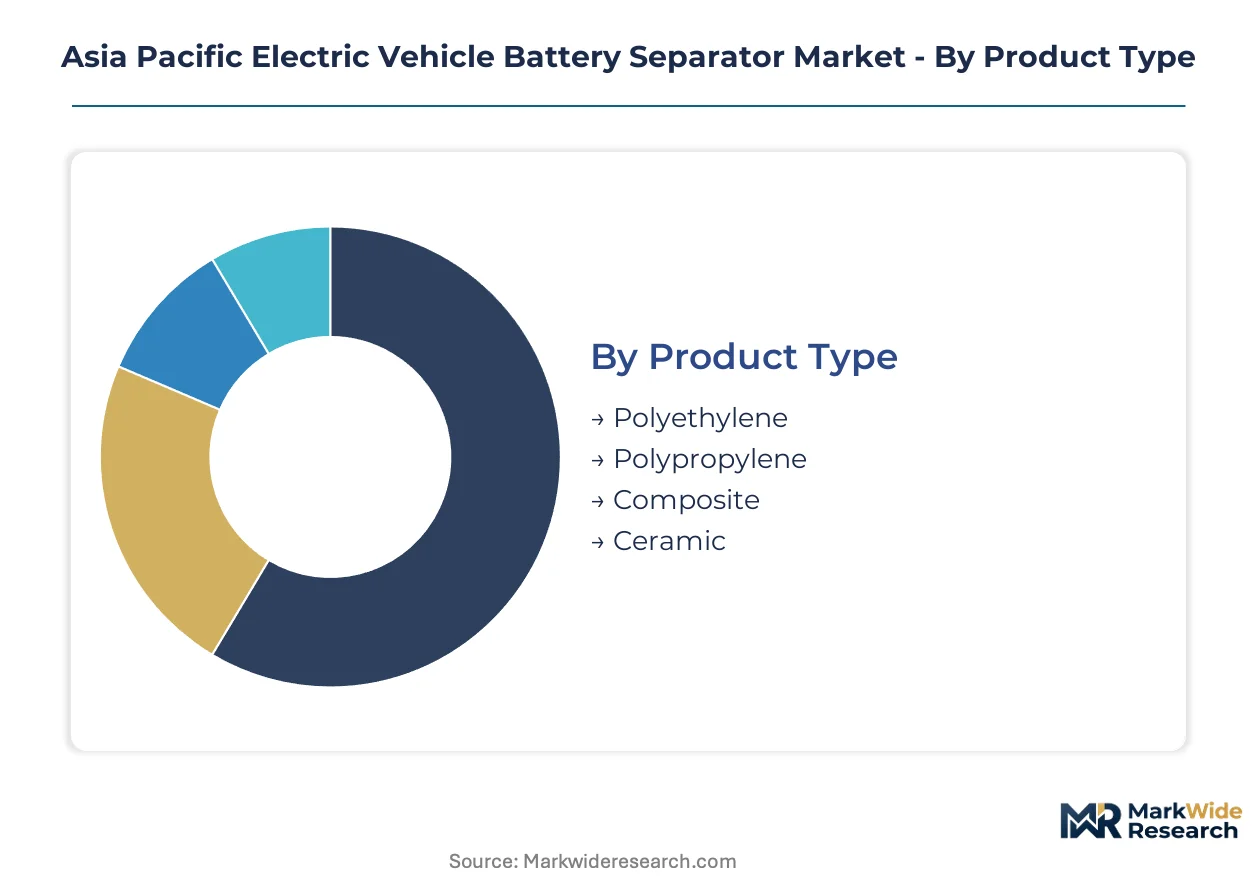
Battery separator segmentation in Asia Pacific tracks the tension between standardized base films and customized safety coatings. Cell makers configure procurement portfolios across chemistry, thickness, and thermal performance tiers to match cathode chemistry and OEM qualification requirements.
Product Type:
Customization intensity escalates from commodity polyolefins toward ceramic composites, with each tier commanding distinct qualification timelines and margin structures.
- Polyethylene:Wet-process ultra-high molecular weight films deliver 10-25 micrometer thickness with uniform pore distribution for cylindrical and prismatic cells. Chinese wet-process capacity expansion concentrates in Jiangsu and Zhejiang provinces, where MIIT safety mandates accelerate domestic qualification.
- Polypropylene:Dry-process biaxially stretched membranes offer superior oxidation resistance at elevated voltages, anchoring supply from Japanese and Korean petrochemical-integrated producers. SK Innovation's captive Ulsan output feeds directly into its cell plants, reducing qualification friction for high-volume contracts.
- Composite:Multi-layer polyethylene-polypropylene laminates balance mechanical strength with shutdown behavior, serving mid-tier energy storage applications where cost sensitivity moderates performance requirements.
- Ceramic:Alumina-coated substrates command premium positioning for NCM 811 and solid-state transition platforms, with coating thickness and particle size distribution becoming critical specification parameters.
Most installed capacity flows through polyethylene wet-process lines. Expansion is steepest in ceramic coating operations.
End User:
Volume concentration versus specification intensity varies sharply across vehicle categories, with passenger platforms driving standardization and commercial segments demanding customization.
- Passenger Vehicles:Premium sedan and SUV platforms from CATL and BYD supply chains specify ceramic-coated separators as baseline, with 150°C thermal shutdown resistance mandatory for high-nickel cell configurations.
- Commercial Vehicles:Heavy-duty truck and van battery packs prioritize cycle life over energy density, directing procurement toward thicker polypropylene films with reinforced mechanical properties.
- Two-Wheelers:Cost-optimized cylindrical cell production in Vietnam and Indonesia absorbs commodity polyethylene supply, with minimal coating penetration due to price ceilings.
- Buses:Municipal fleet procurement in Chinese tier-one cities enforces GB/T safety certification that mandates nail penetration survival, filtering supplier rosters toward ceramic-capable manufacturers.
Passenger vehicle demand absorbs the majority of qualified separator output. Commercial vehicle procurement is expanding most quickly as fleet electrification accelerates.
Application:
Automotive qualification standards diverge from stationary storage requirements, creating parallel supply chains with incompatible certification timelines.
- Electric Vehicles:OEM-specific protocols from Tesla, BYD, and Hyundai Motor Group dominate qualification burden, with separator suppliers maintaining parallel technical service teams for each anchor customer.
- Hybrid Vehicles:Smaller battery packs and lower depth-of-discharge cycles permit thinner base films, with Toyota and Honda supply chains sustaining dedicated polypropylene specifications.
- Energy Storage:Grid-scale and residential systems prioritize cost per kilowatt-hour over energy density, accepting thicker separators with extended calendar life.
- Grid Applications:Utility procurement in Australia and Japan emphasizes fire safety certification that favors ceramic-coated or aramid-reinforced configurations despite premium pricing.
Electric vehicle applications command the dominant share of high-performance separator output. Grid applications are gaining share fastest as renewable integration drives storage deployment.
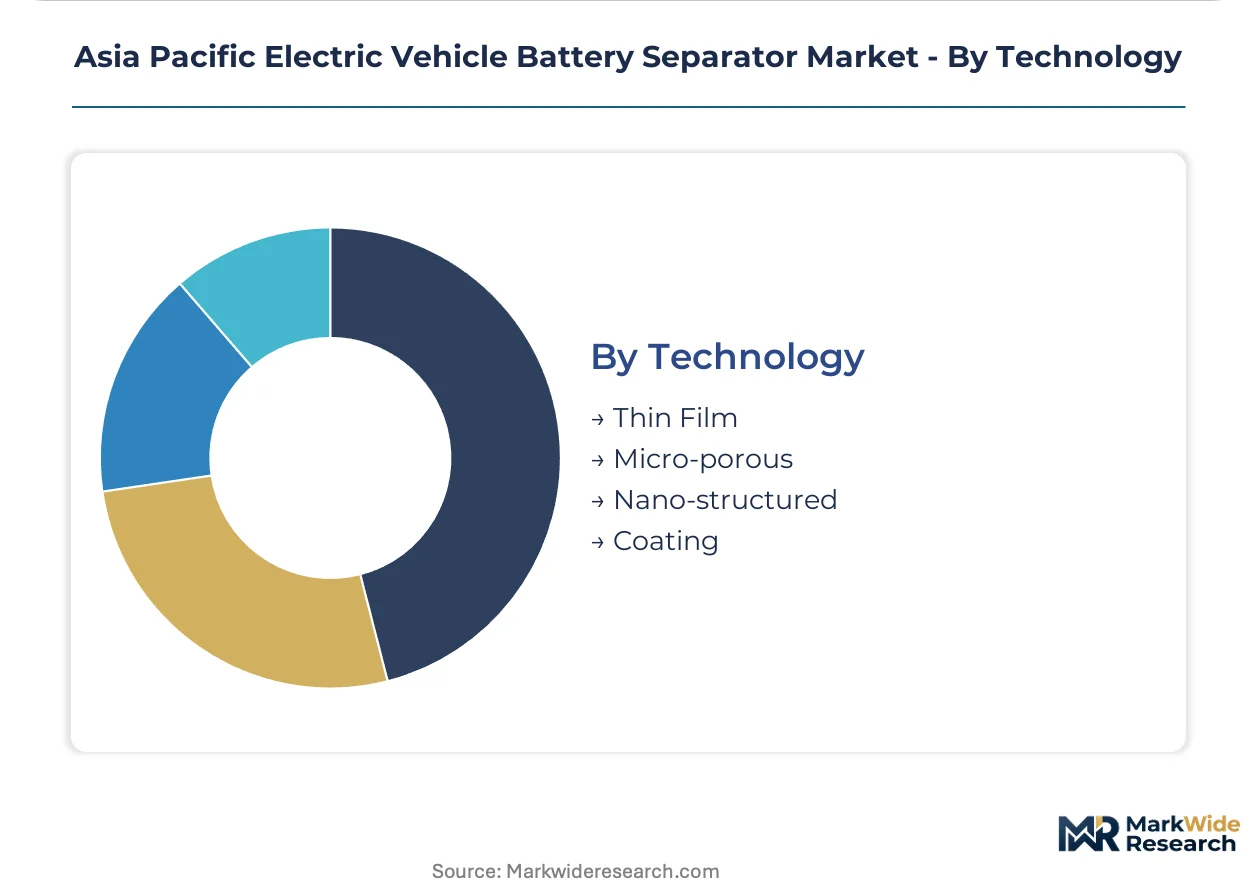
Technology:
Manufacturing process selection determines equipment investment thresholds and technical talent requirements, concentrating capability in established industrial clusters.
- Thin Film:Sub-10 micrometer substrates target next-generation cell formats where energy density maximization overrides safety margin, attracting R&D allocation from Korean and Japanese cell makers.
- Micro-porous:Wet-process phase inversion dominates installed equipment base across China, Korea, and Japan, with biaxial stretching expertise concentrating in Ulsan and Tsuruga manufacturing corridors.
- Nano-structured:Electrospun and template-based architectures remain pre-commercial, with METI Green Innovation Fund subsidies supporting Japanese pilot lines.
- Coating:Precision ceramic and polymer layer deposition differentiates supplier tiers, with coating line utilization rates determining margin sustainability for independent manufacturers.
Micro-porous platforms retain the majority of operational equipment. Coating technology is climbing the fastest as high-nickel cathode penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between China's MIIT-mandated GB/T certification and South Korea's IEC-aligned KATS protocols are redirecting separator investment toward jurisdictions with faster qualification pathways. Manufacturers exploit regulatory arbitrage by locating coating operations in industrial zones where safety testing timelines compress.
China
CATL and BYD procurement drives separator demand across Jiangsu and Zhejiang provinces. MIIT's nail penetration and overcharge testing protocols force ceramic-coated upgrades for all domestic and export-bound production. The Yangtze River Delta clustering concentrates wet-process polyethylene capacity expansion near qualified cathode supply.
South Korea
SK Innovation's captive Ulsan output feeds directly into in-house cell plants, reducing logistics friction for high-nickel cathode platforms. KATS alignment with IEC 62660 cell testing protocols accelerates joint qualification cycles with cathode-anode partners. The Ulsan-Gumi corridor anchors the region's integrated separator-cell industrial base.
Japan
Toray Industries and UBE Corporation sustain high-purity wet-process capacity for premium export markets. METI's Green Innovation Fund subsidizes solid-state separator R&D through pilot line investments. Tsuruga manufacturing corridors concentrate biaxial stretching expertise that constrains competitor entry timelines.
Indonesia
Emerging battery cell plants in the Indonesia Morowali Industrial Park lack qualified local separator supply, creating first-mover qualification windows. The country's national industrial regulator enforces battery safety standards adapted from ASEAN harmonized frameworks. Domestic procurement policies favor suppliers establishing coating operations within special economic zones.
Thailand
Board of Investment incentives attract separator manufacturers serving emerging EV assembly operations in the Eastern Economic Corridor. Thailand's national standards body aligns battery component certification with UN ECE regulations for automotive export compatibility. Rayong province clustering targets integration with Japanese and Korean cell maker supply chains.
Asia Pacific Electric Vehicle Battery Separator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic coating specialization to bypass incumbent polymer expertise advantages. The market structures around three archetypes: petrochemical-integrated cell makers with captive separator output, independent membrane specialists licensing coating IP, and materials suppliers pivoting from industrial films. Capacity expansion and strategic partnerships dominate competitive moves, with procurement consolidation forcing supplier roster reductions from six-plus qualified sources to three strategic partners per geography.
Within the integrated petrochemical tier, SK Innovation Co. Ltd exemplifies captive supply chain configuration. Among independent membrane specialists, Yunnan Enjie New Materials Co. Ltd and UBE Corporation occupy positions representing Chinese wet-process expansion and Japanese high-purity incumbent supply respectively. These three anchors illustrate how geographic concentration and regulatory compliance capabilities stratify competitive positioning across the Asia Pacific separator base.
| Leading Market Players |
|---|
| Senior plc |
| UBE Corporation |
| SK Innovation Co. Ltd |
| Hitachi Chemical Company Ltd |
| Teijin Ltd |
| Mitsubishi Chemical Group Corporation |
| Sembcorp Industries Ltd |
| Yunnan Enjie New Materials Co. Ltd |
| Toray Industries Inc. |
| Others |
Pricing and Supply Chain Analysis
Polypropylene feedstock indices cascade through Asia Pacific separator manufacturing, compressing margins for non-integrated producers while petrochemical-backed cell makers absorb volatility through captive supply. Ceramic coating premiums widen against base film commoditization as MIIT safety mandates force qualification upgrades across Chinese and export-bound production lines.
Pricing Analysis
Input-cost pass-through from propylene monomer volatility shapes margin structures across polyethylene and polypropylene base films. Pricing stratifies across ceramic-coated premium tiers, standard wet-process films, and economy dry-process membranes, with thermal safety certification under GB/T and IEC 62660 protocols driving differentiation. Cost compression in standard tiers intensifies as Chinese capacity expansion outpaces qualification velocity. Korean cell makers exhibit least price sensitivity due to integrated supply chains, while Southeast Asian emerging plants face acute budget constraints.
Supply Chain Analysis
Ultra-high molecular weight polyethylene resin supply rests on Japanese and Korean petrochemical producers, with biaxial stretching equipment concentrated in Tsuruga and Ulsan manufacturing corridors. Ceramic alumina coating materials draw from Chinese and Australian specialty chemical suppliers. Single-source vulnerability persists in precision coating line technology, where Japanese equipment makers control deposition uniformity specifications. Distribution runs through cathode-anode-separator industrial clusters, with qualified material flowing directly from membrane plants to cell manufacturing lines under long-term offtake frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific separator demand has shifted toward late-cycle quality specifications, with ceramic-coated thermal safety performance becoming non-negotiable for high-nickel cathode platforms across Chinese and Korean supply chains.
For Market Incumbents: Acquire coating technology IP portfolios to defend premium positioning against solid-state battery substitution threats. SK Innovation's captive Ulsan model demonstrates how backward integration into petrochemical feedstock secures margin resilience when propylene volatility spikes. UBE Corporation and Toray Industries should extend qualification support services to Southeast Asian cell plants before local competitors establish coating capability. For New Entrants and Emerging Players: Tier 2 Korean cell manufacturers represent the most penetrable customer segment, as procurement consolidation from six-plus sources to three strategic partners creates supplier roster gaps. Indonesia Morowali Industrial Park and Thailand's Eastern Economic Corridor offer first-mover qualification windows where local coating operations satisfy domestic content requirements. Licensing Japanese biaxial stretching expertise accelerates time-to-qualification versus greenfield equipment development. For Investors and Strategic Acquirers: Asymmetric upside sits with ceramic coating specialists possessing GB/T and IEC 62660 dual certification capability, as regulatory compliance becomes scarcer than base membrane capacity. The five-to-ten year viability window favors suppliers with demonstrated nail penetration survival and overcharge tolerance validation. Watch for METI Green Innovation Fund pilot line announcements signaling solid-state separator timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyolefin Feedstock | SK Innovation's captive Ulsan supply chain insulates margins from propylene monomer volatility. |
| Ceramic Coating Capacity Expansion | Alumina deposition lines command premium positioning as CATL and BYD mandate thermal shutdown resistance. |
| Dual Certification Investment | Simultaneous GB/T and IEC 62660 qualification opens access to Chinese state-backed and Korean export vehicle procurement. |
| Southeast Asian Coating Localization | Indonesia Morowali and Thailand Eastern Economic Corridor plants reduce logistics friction for emerging cell manufacturing. |
| Solid-State Separator R&D Partnership | METI Green Innovation Fund subsidies offer co-development pathways with Japanese cell makers transitioning electrolyte platforms. |
Research Methodology
Multiple input streams — technical interviews with separator plant managers and coating line engineers, procurement lead discussions at CATL and SK Innovation, and regulatory affairs dialogues with MIIT and KATS officials — were reconciled against secondary validation. Trade data from Korean and Japanese customs authorities, SEC filings from petrochemical-integrated cell makers, and MIIT battery safety standard documentation provided demand-side calibration. Bottom-up capacity tallies across Jiangsu, Zhejiang, Ulsan, and Tsuruga manufacturing zones were cross-referenced against top-down vehicle production forecasts.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of qualification timeline compression. The analytical framework modeled separator demand across product type, end-use vehicle category, coating technology tier, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from segmented volume projections weighted by cathode chemistry penetration rates and OEM platform rollout schedules. Ceramic coating adoption curves and solid-state battery substitution timelines served as critical scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state electrolyte commercialization pace and propylene feedstock price volatility. Projections reflect documented assumptions regarding MIIT enforcement consistency and Korean industrial clustering sustainability. A small set of named triggers — METI pilot line scale-up announcements, Indonesian domestic content policy shifts, and high-nickel cathode chemistry transitions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market