
 Flow Battery Market | 2026-2036
Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Battery Market Intelligence
Electrolyte chemist and systems engineering talent scarcity is redrawing competitive boundaries in the flow battery sector. Invinity Energy Systems leverages its manufacturing scale to anchor utility-scale deployments across multiple continents. VRB Energy sustains technology leadership in all-vanadium architectures through deep R&D intensity. Sumitomo Electric Industries dominates membrane-based system reliability with decades of operational field data.
Flow batteries store electrical energy in liquid electrolytes separated by an ion-selective membrane, with power and energy capacity decoupled to enable 8-12 hour discharge durations for grid stabilization. Vanadium chemistries occupy the largest installed base due to electrolyte recyclability and minimal capacity degradation over 20,000 cycles. Zinc-bromine systems compete on lower material costs and higher energy density for commercial and industrial behind-the-meter applications. Redox flow technology leads in megawatt-scale deployments while membrane-based innovations target efficiency gains that reshape margin pools toward system integrators.
FERC Order 2222 and state-level storage mandates in California, New York, and Massachusetts shape wholesale market participation rules for long-duration assets in the United States. China's MIIT and National Energy Administration enforce dual carbon compliance timelines that mandate renewable-plus-storage configurations for new grid interconnection. The EU Green Deal and F-Gas Regulation constrain fluorinated membrane chemistries, redirecting R&D toward hydrocarbon alternatives. Stakeholders must monitor electrolyte supply chain localization requirements and evolving capacity remuneration mechanisms as procurement criteria shift from capital cost toward total lifecycle value.
Market Dynamics
Long-duration storage procurement mandates are compressing technology evaluation cycles, forcing utilities to select between vanadium, zinc-bromine, and emerging organic chemistries before full performance validation completes.
Growth Catalysts
- Grid Interconnection Mandates:China's MIIT dual carbon compliance rules require renewable-plus-storage configurations for new utility-scale solar and wind projects, accelerating vanadium flow battery deployments.
- Wholesale Market Reform:FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in capacity and ancillary service markets, creating revenue stacking for 8-12 hour storage assets.
- Electrolyte Recyclability:Vanadium's infinite reuse without capacity degradation attracts circular economy-focused utilities in Germany seeking to minimize lifecycle environmental liability.
Market Restraints
- Vanadium Price Volatility:Steel industry demand spikes for vanadium pentoxide create input cost instability that compresses project developer margins during procurement.
- Membrane Supply Concentration:Perfluorinated ion-exchange membrane production concentrates among specialty chemical suppliers in Japan and the United States, exposing system integrators to single-source risk.
- Energy Density Limitation:Aqueous flow chemistries achieve 15-25 Wh/L versus 200+ Wh/L for lithium-ion, constraining footprint-constrained urban substation retrofits.
Strategic Opportunities
- Industrial Microgrids:Mining operations in Australia and Chile seek 12-16 hour discharge durations for diesel displacement, opening zinc-bromine penetration where lithium thermal runaway risks dominate.
- Hydrocarbon Membrane Development:EU F-Gas Regulation restrictions on fluorinated chemistries redirect R&D investment toward non-fluorinated alternatives that qualify for green public procurement.
- Electrolyte Leasing Models:Third-party ownership of vanadium electrolyte inventories separates energy asset financing from power conversion hardware, reducing utility capex barriers.
Industry Challenges
- Systems Integration Expertise Gap:Utility-scale project timelines suffer from scarce talent capable of optimizing power conversion system sizing against variable electrolyte flow rates.
- Extended Certification Cycles:IEC 62933-5-2 safety testing for redox flow batteries requires 12-18 month validation periods that delay commercial operation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Battery Market |
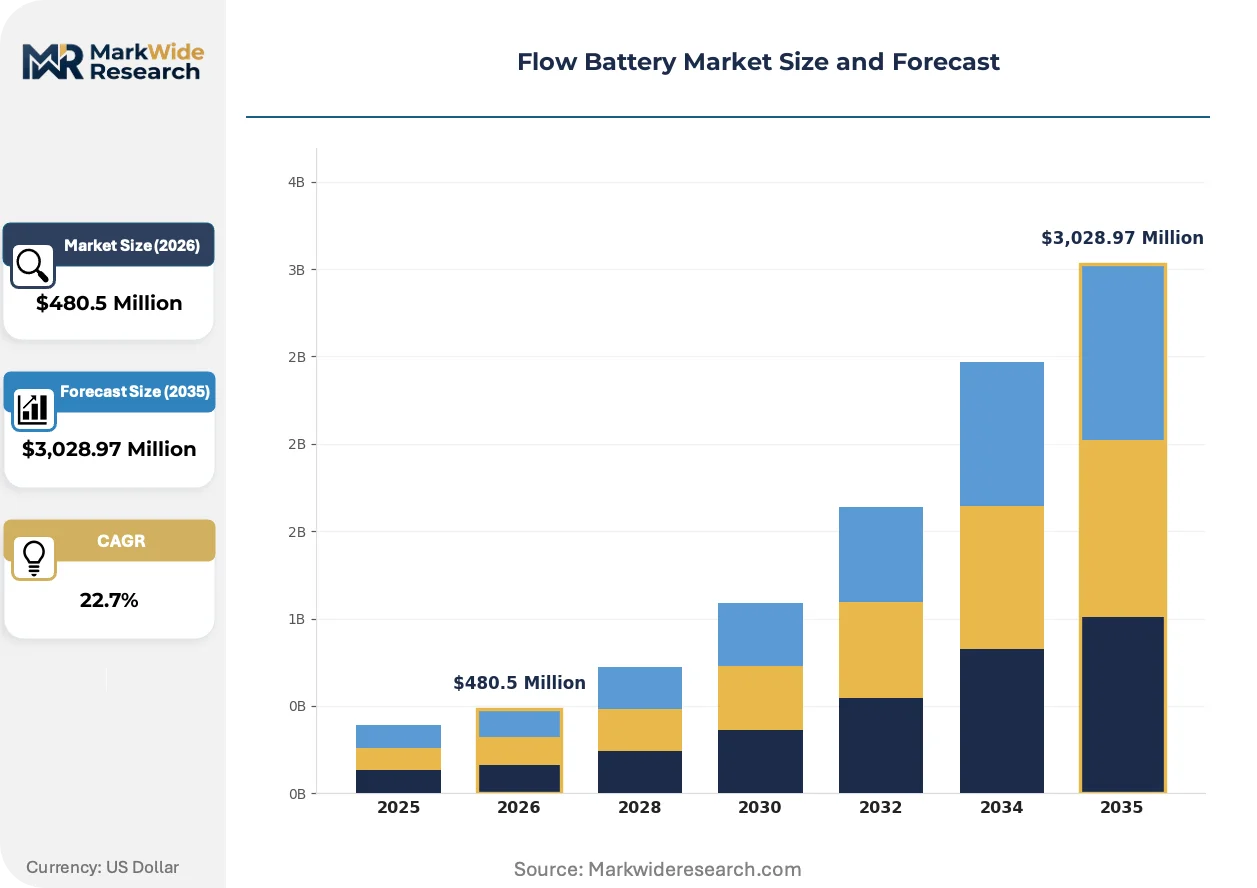
| Market Size in 2026 | $480.5 Million |
| Market Size in 2035 | $3,028.97 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanadium, Zinc-Bromine, All-Vanadium, Hybrid End User: Utilities, Renewable Energy, Industrial, Commercial Application: Grid Storage, Renewable Integration, Backup Power, Microgrid Technology: Redox Flow, Membrane-Based, Flow-Through, Electrolyte Management |
| Companies Covered | ESS Tech Inc., VRB Energy, Invinity Energy Systems, Sumitomo Electric Industries, Ltd., Primus Power, Largo Inc., Redox One, Enerox GmbH, Elestor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Battery Market Strategic Shifts & Innovations
Electrolyte chemistry diversification and membrane material substitution are fragmenting technology roadmaps, with R&D investment rotating away from incumbent vanadium architectures toward lower-cost organic and hybrid metal-ligand systems.
Organic redox-active molecules are decomposing the traditional vanadium cost structure by eliminating metal mining dependencies. European research consortia and Massachusetts-based startups are piloting anthraquinone and viologen derivatives in 100 kW-class installations. This chemistry is decomposing incumbent supplier margins by enabling electrolyte synthesis from commodity petrochemical feedstocks rather than specialty metal processing.
REACH and EU F-Gas Regulation amendments are accelerating membrane material substitution timelines. The constraint on perfluorinated compounds forces manufacturers to validate hydrocarbon-based ionomers that trade chemical stability for regulatory compliance. German and Dutch system integrators are most affected, restructuring supply agreements to exclude fluorinated components from 2027 delivery contracts.
Utility procurement departments are consolidating vendor evaluation criteria around total lifecycle cost rather than capital expenditure alone. Independent power producers in California and Texas now require 20-year electrolyte performance guarantees and residual value recovery clauses. This behavioral shift is most visible in competitive solicitations where levelized cost of storage calculations dominate bid scoring matrices over upfront unit pricing.
Flow Battery Market Segmentation
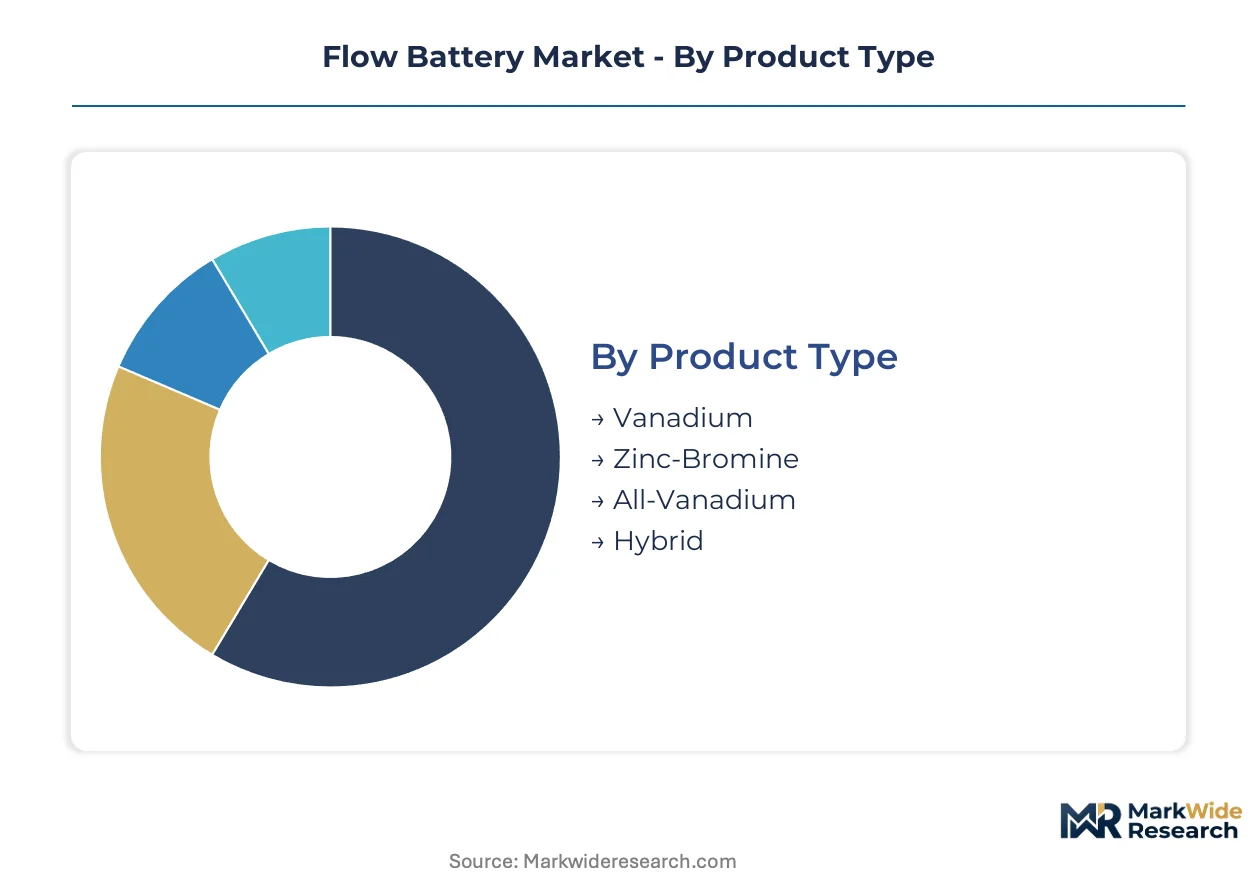
Flow battery technology fragments across chemistry, customer archetype, and integration architecture. Each segmentation axis reveals distinct margin pools, certification requirements, and channel strategies that reshape competitive positioning.
Product Type:
Product type determines electrolyte supply chain configuration and project financing structure. Vanadium architectures flow through utility procurement channels with long-term service contracts, while zinc-bromine systems penetrate industrial distributors.
- Vanadium:Aqueous vanadium electrolyte stores energy in multiple oxidation states within a single metal species, eliminating cross-contamination. Utility-scale deployments in China and Germany concentrate here, driven by MIIT dual carbon mandates and circular economy liability frameworks. By volume, vanadium leads. By growth pace, hybrid chemistries are expanding most quickly.
- Zinc-Bromine:Zinc plating and bromine complexation achieve higher energy density than vanadium alternatives. Mining microgrids in Australia and Chile favor this chemistry for diesel displacement where thermal runaway risks exclude lithium-ion.
- All-Vanadium:Symmetric vanadium species in both half-cells simplify electrolyte management and enable indefinite rebalancing. Grid interconnection codes in China explicitly reference this architecture for renewable-plus-storage configurations.
- Hybrid:Metal-ligand and organic redox couples combine low-cost synthesis with tunable redox potentials. Massachusetts-based pilots and European research consortia validate 100 kW-class installations.
Hybrid architectures gain share fastest in venture-backed deployments, while vanadium dominates utility procurement pipelines.
End User:
End user segmentation maps to discharge duration requirements and procurement sophistication. Utilities negotiate 20-year performance guarantees, while commercial buyers prioritize capital expenditure thresholds.
- Utilities:Transmission and distribution operators procure 8-12 hour duration assets for capacity services and renewable firming. FERC Order 2222 in the United States enables wholesale market participation that stacks revenue streams.
- Renewable Energy:Solar and wind developers integrate flow batteries to meet grid interconnection mandates. China's National Energy Administration requires storage co-location for new utility-scale projects.
- Industrial:Manufacturing facilities and mining operations seek behind-the-meter resilience. Zinc-bromine penetration concentrates here due to footprint constraints and safety preferences.
- Commercial:Retail and office buildings deploy smaller systems for demand charge management. Procurement evaluates payback periods against lithium-ion alternatives.
Utilities command the largest average transaction size. Renewable energy developers are climbing the fastest as interconnection queues lengthen.
Application:
Application determines power-to-energy ratio engineering and control system architecture. Grid storage applications prioritize round-trip efficiency, while microgrids emphasize black-start capability.
- Grid Storage:Bulk energy shifting and ancillary services require megawatt-scale power conversion with 8-12 hour discharge. California and Texas independent power producers dominate procurement.
- Renewable Integration:Solar and wind firming smooths output variability for grid code compliance. Germany's transmission system operators specify ramp rate control in procurement criteria.
- Backup Power:Critical facility resilience demands instantaneous response with multi-hour duration. Data centers and hospitals evaluate flow batteries against diesel gensets.
- Microgrid:Islanded operation with renewable generation requires frequency regulation and voltage support. Remote mining camps in Chile and Australia validate 12-16 hour discharge configurations.
Grid storage anchors installed capacity. Microgrid applications show steepest expansion trajectory as diesel displacement accelerates.
Technology:
Technology segmentation separates cell stack engineering from balance-of-plant integration. Redox flow architectures dominate megawatt deployments, while membrane innovations target efficiency gains.
- Redox Flow:Active species dissolved in liquid electrolyte circulate through electrochemical cells. Decoupled power and energy sizing enables modular capacity expansion.
- Membrane-Based:Ion-selective separators enable proton exchange while blocking active species crossover. EU F-Gas Regulation restrictions redirect R&D toward hydrocarbon alternatives.
- Flow-Through:Electrolyte passes once through the electrochemical reactor without recirculation. Simplified plumbing reduces system complexity for smaller installations.
- Electrolyte Management:State-of-charge monitoring, thermal regulation, and rebalancing systems preserve capacity over 20,000 cycles. Third-party leasing models separate electrolyte ownership from hardware financing.
Redox flow systems lead by megawatt-hours deployed. Electrolyte management technology is gaining share fastest as lifecycle guarantees become procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys flow batteries predominantly for utility-scale renewable firming under mandatory interconnection codes, while Germany emphasizes circular economy liability frameworks that favor vanadium recyclability, and the United States stacks wholesale market revenues through FERC-enabled aggregation models.
China
Provincial grid operators in Inner Mongolia and Gansu procure multi-hundred-megawatt vanadium systems to manage wind curtailment. MIIT dual carbon compliance rules require storage co-location for new renewable projects above 50 MW. Manufacturing clusters in Dalian and Beijing-Tianjin-Hebei anchor electrolyte production and cell stack assembly.
United States
Independent power producers in California and Texas dominate long-duration storage procurement for solar-plus-storage hybrids. FERC Order 2222 enables aggregated distributed resources to bid into capacity markets, creating revenue stacking for 8-12 hour assets. Project development concentrates in ERCOT and CAISO balancing authority areas.
Germany
Transmission system operators specify ramp rate control and frequency regulation in grid storage tenders. EU F-Gas Regulation restricts fluorinated membrane chemistries, redirecting R&D toward hydrocarbon alternatives. Industrial demand clusters in North Rhine-Westphalia evaluate vanadium systems for steel plant renewable integration.
Australia
Mining operations in Western Australia and Queensland seek 12-16 hour discharge for diesel displacement at remote camps. Zinc-bromine chemistry penetrates where lithium thermal runaway risks dominate safety assessments. Port Hedland and Pilbara region microgrids validate flow battery configurations for iron ore logistics.
Chile
Copper and lithium mining operations in the Atacama Desert require resilient power for desalination and processing loads. National energy policy mandates renewable penetration targets that drive storage procurement. Antofagasta and Calama industrial corridors host pilot deployments for solar smoothing and backup power.
Flow Battery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the flow battery sector. Tier-one players combine captive electrolyte supply with in-house membrane engineering and utility-scale project execution capabilities. The specialist tier fragments across chemistry-specific pure-plays, regional system integrators, and research-spinout technology developers. Competitive moves concentrate on electrolyte leasing model innovation and hydrocarbon membrane validation partnerships.
Among the integrated tier, Sumitomo Electric Industries, Ltd. exemplifies membrane-based system reliability through decades of operational field data, while Invinity Energy Systems occupies a position anchored in manufacturing scale for utility deployments across multiple continents. VRB Energy represents the all-vanadium technology leadership archetype through sustained R&D intensity in symmetric cell architectures.
| Leading Market Players |
|---|
| ESS Tech Inc. |
| VRB Energy |
| Invinity Energy Systems |
| Sumitomo Electric Industries, Ltd. |
| Primus Power |
| Largo Inc. |
| Redox One |
| Enerox GmbH |
| Elestor |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance gates both membrane supplier qualification and system integrator price differentiation simultaneously, forcing hydrocarbon membrane validation timelines into procurement negotiations while tiering contract values by fluorinated-content exclusion guarantees.
Pricing Analysis
Long-term electrolyte offtake contracts dominate utility-scale procurement, separating vanadium inventory financing from power conversion hardware capex. Price differentiation hinges on IEC 62933-5-2 certification tier and bundled 20-year performance guarantees versus bare equipment supply. Cost compression in zinc-bromine systems is intensifying because mining microgrids prioritize total lifecycle cost over upfront unit pricing. Commercial buyers exhibit highest price sensitivity; transmission operators least.
Supply Chain Analysis
Strategic stockpiling of vanadium pentoxide concentrates among Chinese electrolyte producers contrasts with just-in-time membrane sourcing from Japanese and United States specialty chemical suppliers. Manufacturing clusters in Dalian and Beijing-Tianjin-Hebei anchor cell stack assembly, drawing from Chilean and Australian vanadium feedstock. Single-source vulnerability concentrates in perfluorinated ion-exchange membrane production. Distribution runs through utility procurement channels with EPC contractor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte leasing and third-party residual value recovery are expanding faster than hardware sales, converting flow battery deployments into recurring-revenue infrastructure services.
For Market Incumbents: Shield installed base relationships by accelerating hydrocarbon membrane certification partnerships ahead of EU F-Gas deadlines. Deepen backward integration into vanadium electrolyte recycling capabilities to neutralize price volatility from steel industry demand spikes. Prioritize captive membrane engineering talent retention as specialist scarcity intensifies competitive poaching. For New Entrants and Emerging Players: Lead with organic redox chemistry pilots in Massachusetts and European research consortia where incumbent vanadium architectures carry legacy cost structures. Mining microgrids in Western Australia and Chilean Atacama corridors represent most penetrable white-space for zinc-bromine diesel displacement. Pursue power purchase agreement co-development with remote industrial offtakers rather than utility direct sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrolyte leasing sub-segments as third-party ownership models separate energy assets from hardware financing. Five-to-ten year viability favors integrated players combining captive electrolyte supply with utility-scale project execution capabilities. Watch for vanadium price volatility spikes as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Leasing Model Expansion | Separates vanadium inventory financing from power conversion hardware capex for utility buyers. |
| Hydrocarbon Membrane Validation Partnership | Qualifies non-fluorinated ionomers under EU F-Gas Regulation ahead of 2027 contract exclusions. |
| Utility-Scale EPC Capability Buildout | Captures procurement consolidation toward integrated project execution in China and Germany. |
| Remote Mining Microgrid Deployment | Penetrates Australian and Chilean diesel displacement markets where lithium thermal runaway risks dominate. |
| Electrolyte Recycling Infrastructure Investment | Secures circular economy liability advantages under German and EU circular economy frameworks. |
Research Approach
Desk research of FERC interconnection filings, EIA storage deployment databases, and MIIT policy circulars preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork validated electrolyte cost assumptions and membrane supply timelines against secondary trade data and customs records. Bottom-up project pipeline aggregation triangulated with top-down capacity forecasts across chemistry and application segments.
Variance decomposition across chemistry type, customer archetype, and regional regulatory framework shaped the analytical approach over the projection horizon. Segmentation modeling incorporated discharge duration requirements, power-to-energy ratios, and certification tier adoption curves. CAGRs derived from unit economics trajectories in vanadium and zinc-bromine systems, cross-referenced with interconnection queue data from CAISO and ERCOT balancing authorities.
Forecasts assume regulatory continuity in FERC Order 2222 implementation and MIIT dual carbon compliance timelines; material policy shifts would require re-modeling wholesale market participation rules or renewable-plus-storage mandates. Vanadium price volatility spikes, membrane supply disruptions, or IEC 62933-5-2 certification timeline extensions constitute specific revision triggers. Revision becomes warranted when electrolyte leasing penetration crosses utility procurement threshold preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
48 Volt Battery System Market
Batteries
Japan Mobile Battery Market
Batteries
Lithium Marine Battery Market
Batteries
3D-Printed Battery Market
Batteries
Portable Battery Market
Batteries
Lead Carbon Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Automotive Starting Battery Market
Batteries
PERC Battery Market
Batteries
North America Battery Market
Batteries
High Voltage Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Deep Cycle Battery Market
Batteries
Battery Separators Market