
 France Electric Vehicle Battery Materials Market | 2026-2036
France Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Materials Market Insights
The capability gap between integrated cathode producers and merchant chemical suppliers is collapsing as cell manufacturers demand qualified, traceable material streams at scale. BASF SE anchors its position through backward integration into precursor chemistries and partnerships with European cell builders. Umicore competes via closed-loop recycling infrastructure that recovers nickel, cobalt, and lithium from industrial scrap and end-of-life batteries. Eramet SA leverages its nickel mining and refining assets to secure feedstock for high-nickel cathode formulations serving French OEM programs.
France electric vehicle battery materials encompass active materials, electrolytes, separators, and current collectors engineered to specific electrochemical performance thresholds, including energy density above 250 Wh/kg for premium cell designs and cycle life exceeding 1,000 deep discharges. These materials enable rechargeable energy storage systems that power traction motors in battery electric and plug-in hybrid vehicles across passenger, commercial, and mass-transit platforms. Lithium and nickel segments command the dominant share of value given their centrality to high-energy-density cathode chemistries, while solid-state battery technology represents the fastest-growing technology category as French and European developers push toward ceramic and polymer electrolyte architectures. Graphite occupies a mature, volume-driven position in anode applications, though silicon-doped formulations are emerging as a margin pool for differentiated suppliers.
France's national implementation of the EU Battery Regulation, alongside ECHA oversight of chemical substance restrictions under REACH, imposes mandatory recycled content rates and supply chain due diligence that elevate compliance costs for non-integrated importers. The French government's national low-carbon strategy and industrial clustering incentives through the France 2030 investment plan direct public funding toward domestic cathode and cell production, tightening market access for unqualified foreign suppliers. Stakeholders must monitor how evolving carbon border adjustment mechanisms and country-of-origin rules for critical raw materials reshape sourcing economics before committing to long-term offtake agreements or facility locations.
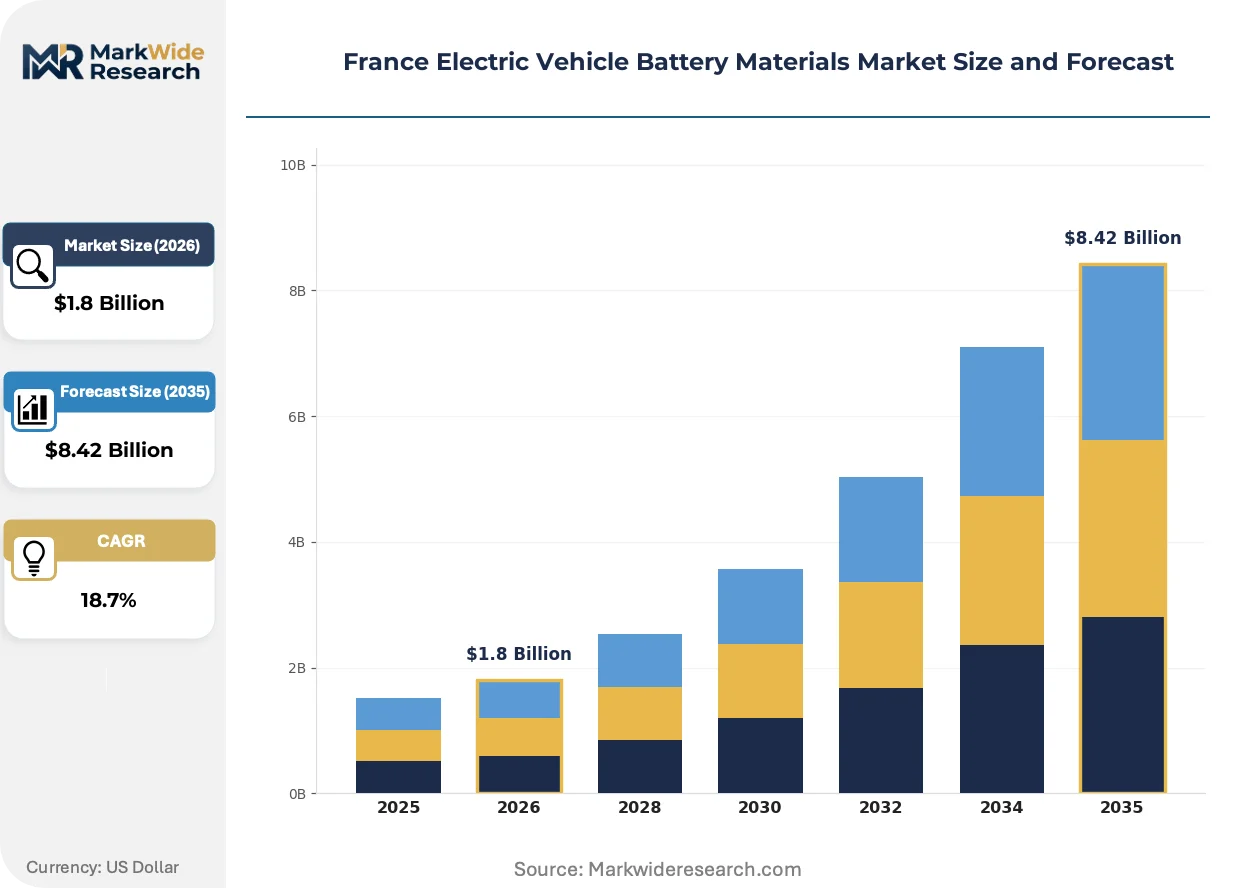
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are compressing supply chain timelines, forcing material suppliers to qualify traceable feedstock streams ahead of 2030 enforcement thresholds.
Growth Catalysts
- Cell manufacturing scale-up:Gigafactory investments by Automotive Cells Company and Verkor in Hauts-de-France and Dunkirk are pulling qualified cathode precursor volumes into domestic production.
- France 2030 industrial incentives:Public funding through the national investment plan is de-risking domestic cathode and separator manufacturing capacity.
- High-nickel cathode chemistry penetration:French OEM programs are specifying NMC 811 and beyond for premium platform ranges, tightening specification tolerance for nickel sulfate and cobalt-free alternatives.
Market Restraints
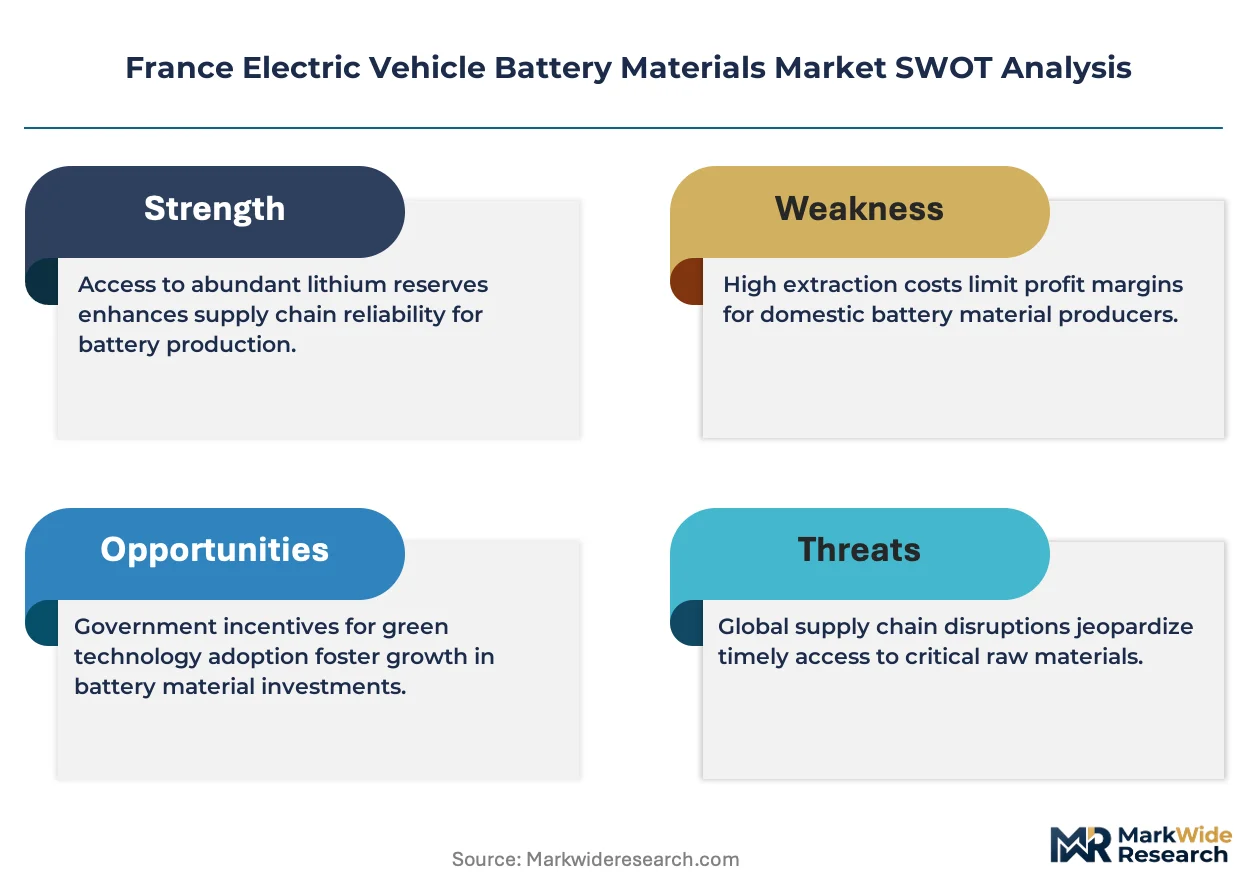
- Feedstock concentration risk:Nickel and cobalt refining capacity concentrates in Southeast Asian and African supply corridors, exposing French processors to geopolitical disruption and logistics bottlenecks.
- Technical limitation in solid-state electrolyte manufacturing:Ceramic and sulfide electrolyte architectures remain constrained by moisture-sensitive production environments and yield consistency below commercial thresholds.
- Regulatory friction from REACH substance restrictions:ECHA oversight of fluorinated compounds and nickel metal classifications is complicating electrolyte salt and cathode binder qualification pathways.
Strategic Opportunities
- Underpenetrated silicon-anode formulations:Silicon-doped graphite blends for next-generation cells present margin capture potential for differentiated anode material suppliers serving French cell builders.
- Regulatory tailwind from EU Green Deal industrial policy:Carbon border adjustment mechanisms and domestic content preferences are tilting procurement economics toward EU-qualified material streams.
- Technology convergence in dry electrode coating:Elimination of solvent-based processing reduces energy intensity and facility footprint, aligning with ESG underwriting criteria for gigafactory financing.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell chemistry optimization and materials characterization expertise pools remain shallow relative to projected facility staffing requirements across Grand Est and Nouvelle-Aquitaine clusters.
- Certification timeline compression:Automotive Cells Company and Stellantis are demanding qualified material streams on 18-month cycles that outpace standard electrochemical validation protocols.
- Supply chain reconfiguration friction:Transitioning from Asian-qualified feedstock to EU-verified recycled content streams requires parallel inventory management and dual-sourcing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Materials Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Graphite Battery Technology: Li-ion, NiMH, Solid State, Lead-Acid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Sumitomo Chemical, BASF SE, Umicore, Arkema SA, Solvay SA, Eramet SA, Imerys SA, SAFT Groupe, Toray Carbon Fibers Europe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Materials Market Trends and Innovations
Solid-state electrolyte architectures and silicon-anode formulations are converging with regulatory pressure on carbon intensity, compressing development timelines for next-generation cell chemistries.
Polymer and ceramic solid-state electrolytes are miniaturizing cell packaging requirements while enabling lithium-metal anode compatibility. Stellantis and Renault engineering teams are targeting 2027-2028 platform integration for these architectures. The technology is miniaturizing thermal management hardware and enabling cell-to-pack designs that compress module-level overhead.
France's transposition of the EU Battery Regulation imposes mandatory recycled content thresholds and supply chain due diligence obligations that elevate compliance costs for non-integrated importers. The national low-carbon strategy reinforces these requirements through public procurement preferences and facility permitting conditions. Cathode precursor suppliers are responding by accelerating partnerships with European recycling infrastructure operators to secure qualified secondary feedstock.
Automotive OEMs are consolidating supplier relationships around qualified material streams with traceable carbon footprints, displacing spot-market procurement of unverified feedstock. Tier-1 cell manufacturers are demanding multi-year offtake commitments with embedded recycling provisions and ESG certification. This concentration is most visible in Hauts-de-France, where Automotive Cells Company and Verkor are pre-qualifying cathode and separator suppliers against 2030 carbon intensity targets.
France Electric Vehicle Battery Materials Market Segmentation
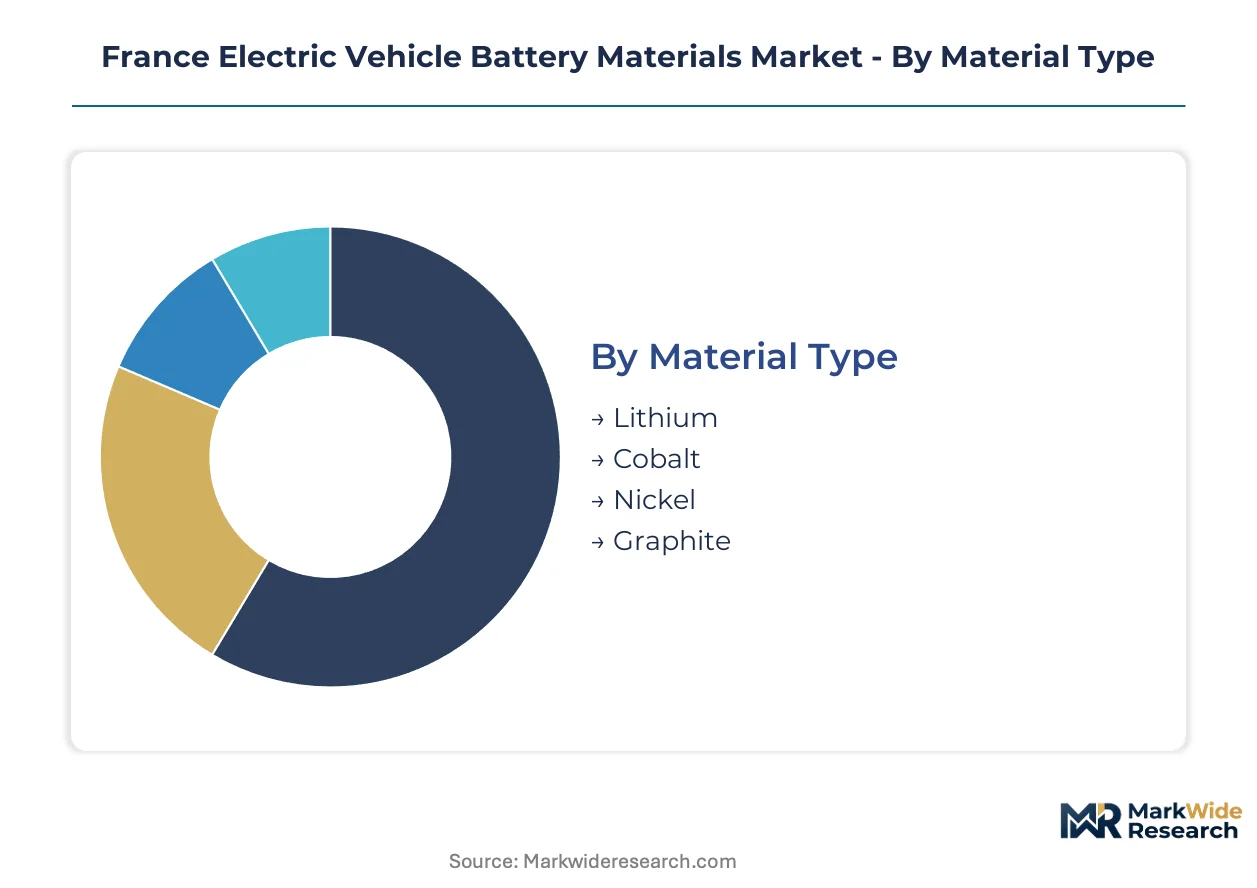
Material qualification pathways differ sharply across battery chemistries and vehicle platforms in France, with gigafactory procurement teams demanding segment-specific carbon footprint documentation and recycled content verification under EU Battery Regulation timelines.
Material Type:
Channel flows split between direct cathode precursor supply to cell manufacturers and merchant chemical distribution serving smaller processors, with qualification requirements determining route selection.
- Lithium:Lithium carbonate and hydroxide specifications for NMC cathode production dominate procurement volumes from Automotive Cells Company and Verkor facilities in Hauts-de-France. French OEM battery programs specify battery-grade lithium with tightly controlled impurity profiles for high-nickel formulations, tightening supplier qualification windows ahead of 2030 recycled content mandates.
- Nickel:Nickel sulfate hexahydrate serves as the primary feedstock for NMC 811 and NCMA cathode chemistries specified in premium French EV platforms. Eramet SA's Sandouville refinery and imported Southeast Asian material compete for qualification status with domestic gigafactories, with carbon intensity disclosures now mandatory for contract eligibility.
- Cobalt:Cobalt sulfate for cathode precursors flows through qualified supply chains subject to EU conflict mineral due diligence and responsible sourcing certification.
- Graphite:Spherical purified graphite for anode applications concentrates in synthetic and natural varieties, with silicon-doped blends emerging for next-generation cell designs.
By volume, nickel leads given its centrality to high-energy-density cathodes. By growth pace, lithium is climbing the fastest as cell production capacity scales across Grand Est and Nouvelle-Aquitaine clusters.
Battery Technology:
Cost tier stratification separates premium solid-state development programs from volume lithium-ion deployments, with manufacturing maturity determining margin capture potential.
- Li-ion:NMC and LFP cell architectures dominate current French EV production, with cathode active material specifications calibrated to OEM platform requirements for energy density above 250 Wh/kg and cycle life exceeding 1,000 discharges. Stellantis and Renault engineering teams specify cell formats ranging from prismatic to cylindrical across passenger and commercial vehicle programs, with separator and electrolyte qualification tied to specific cell designs.
- Solid State:Ceramic and sulfide electrolyte architectures target 2027-2028 platform integration by Stellantis and Renault engineering teams, promising lithium-metal anode compatibility and simplified thermal management. Moisture-sensitive production environments and yield consistency below commercial thresholds constrain near-term volume, positioning solid-state as a premium technology tier with concentrated development funding.
- NiMH:Nickel-metal hydride cells retain niche application in hybrid auxiliary systems and specific commercial vehicle configurations where proven cycle stability outweighs energy density requirements.
- Lead-Acid:Lead-acid technology persists in 12V auxiliary power applications and specific low-voltage vehicle electrical architectures, though lithium substitution accelerates across new French EV platforms.
By volume, Li-ion leads through established gigafactory supply chains. By margin expansion, solid-state is gaining share fastest as development timelines compress toward platform integration.
Application:
Customer type differentiation separates fleet procurement specifications from retail passenger vehicle requirements, with duty cycle intensity determining material performance thresholds.
- Passenger Vehicles:Premium French OEM platforms specify high-nickel NMC cathodes with silicon-doped anode formulations for range-extended battery electric configurations. Stellantis STLA Medium and Large platforms and Renault Scenic E-Tech programs drive cathode precursor demand with stringent carbon footprint documentation requirements under France 2030 incentive conditions.
- Commercial Vehicles:Heavy-duty battery electric trucks and vans for French logistics fleets prioritize LFP chemistries for cycle life and thermal stability under sustained load profiles. Renault Trucks and Stellantis Pro One commercial divisions specify cell formats optimized for depot charging infrastructure and predictable duty cycles.
- Two-Wheelers:Lithium-ion and emerging sodium-ion configurations serve electric motorcycle and scooter platforms from French and European manufacturers, with compact cell formats and simplified battery management systems.
- Buses:Electric transit bus deployments across Île-de-France Mobilités and regional transport authorities specify high-capacity battery packs with LFP or NMC configurations depending on route length and charging infrastructure availability.
By volume, passenger vehicles lead through Renault and Stellantis production scale. By policy tailwind, commercial vehicles are expanding most quickly as French urban freight electrification mandates tighten.
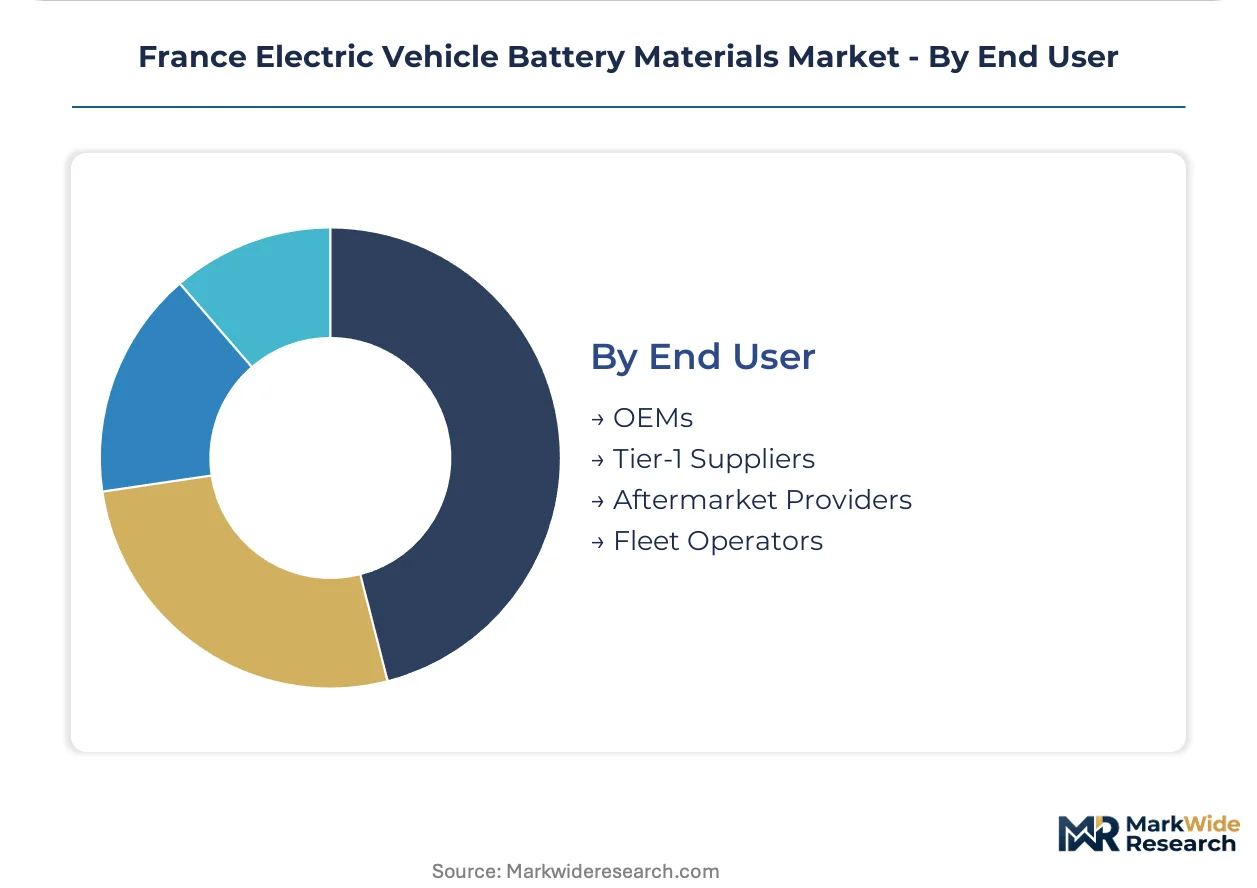
End User:
Supply concentration tilts toward direct OEM and Tier-1 relationships, with aftermarket and fleet channels requiring parallel inventory and service infrastructure.
- OEMs:Renault, Stellantis, and emerging French EV manufacturers specify qualified material streams with embedded recycling provisions and ESG certification, consolidating supplier relationships around traceable carbon footprints. Direct cathode precursor offtake agreements with Automotive Cells Company and Verkor compress procurement timelines and displace spot-market sourcing.
- Tier-1 Suppliers:Cell manufacturers and battery pack integrators serve as the primary demand aggregation point for active materials, with Automotive Cells Company, Verkor, and Saft Groupe qualifying suppliers against 2030 carbon intensity targets and recycled content thresholds.
- Aftermarket Providers:Replacement battery and remanufacturing services require qualified secondary feedstock streams and reverse logistics infrastructure for end-of-life material recovery.
- Fleet Operators:Large French logistics and transit fleets negotiate direct battery supply agreements or leasing structures with embedded material traceability and end-of-life take-back provisions.
By procurement volume, Tier-1 suppliers lead as cell manufacturing scales domestically. By contract structure innovation, OEMs are pulling ahead through integrated vertical partnerships with material processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's electric vehicle battery materials trade flows reflect a structural import dependency for processed lithium and nickel feedstocks, even as domestic refining capacity expands at Eramet SA's Sandouville facility and precursor investments cluster in Hauts-de-France.
Germany
BASF SE's cathode precursor operations in Ludwigshafen and Schwarzheide anchor European supply for French gigafactories, with the EU Battery Regulation's carbon footprint declarations forcing qualification alignment across the Rhine corridor. Germany's national implementation of the EU Green Deal industrial policy channels public funding toward domestic cell manufacturing, tightening cross-border material specifications.
Belgium
Umicore's closed-loop recycling infrastructure in Hoboken recovers nickel, cobalt, and lithium from industrial scrap and end-of-life batteries, positioning the country as a secondary feedstock hub for French cathode producers. The ECHA's REACH oversight of chemical substance restrictions shapes qualification pathways for materials crossing into France.
Spain
Stellantis' planned battery plant in Zaragoza and Volkswagen Group's Valencia gigafactory are pulling Spanish refining investments into nickel sulfate and lithium hydroxide processing. Spain's transposition of the EU Battery Regulation imposes parallel recycled content thresholds that harmonize procurement standards with French requirements.
Italy
Stellantis' Mirafiori complex in Turin and planned Termoli battery facility are specifying high-nickel cathode chemistries that strain Italian domestic precursor availability, forcing reliance on French and German qualified suppliers. Italy's national recovery plan allocates industrial incentives toward cathode active material production.
Sweden
Northvolt's Skellefteå gigafactory and planned Borlänge cathode plant are establishing Nordic supply corridors for French cell manufacturers seeking low-carbon intensity feedstocks. Sweden's early implementation of EU Battery Regulation mandates has accelerated carbon footprint documentation standards that French procurement teams now demand.
France Electric Vehicle Battery Materials Market Competitive Landscape
Concentration sits with integrated chemical conglomerates possessing backward integration into mining or refining assets and specialized materials firms with captive recycling infrastructure. The vendor base stratifies between diversified multinationals qualifying at scale for Automotive Cells Company and Verkor offtake agreements, and regional specialists serving secondary feedstock niches. Two dominant archetypes emerge: mining-integrated refiners controlling nickel and lithium supply corridors, and recycling-integrated processors securing qualified secondary material streams. Capacity expansion and strategic partnerships constitute the primary competitive moves, with firms racing to pre-qualify against 2030 carbon intensity targets.
Among diversified chemical conglomerates, BASF SE anchors the integrated precursor tier through its European cathode material network, while Umicore exemplifies the recycling-integrated archetype via its closed-loop recovery infrastructure. Eramet SA occupies a distinct position as a mining-integrated refiner leveraging nickel assets to supply high-nickel cathode formulations. These three firms represent the competitive core around which French gigafactory procurement is consolidating.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| BASF SE |
| Umicore |
| Arkema SA |
| Solvay SA |
| Eramet SA |
| Imerys SA |
| SAFT Groupe |
| Toray Carbon Fibers Europe |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification cycles for cathode precursors now govern procurement negotiations, compressing supplier margins while amplifying pricing power for integrated refiners with verified carbon footprints under EU Battery Regulation timelines.
Pricing Analysis
Configured-to-order pricing for high-nickel cathode precursors commands a 15-25% premium over standard NMC formulations, reflecting tighter impurity tolerances and embedded recycling certification. Contract-based long-term offtake agreements dominate procurement between Automotive Cells Company, Verkor, and qualified suppliers, with price differentiation driven by carbon intensity documentation and volume scale commitments. Pricing pressure stems from feedstock concentration in Southeast Asian refining corridors, exposing French processors to logistics cost volatility. Tier-1 cell manufacturers exhibit lowest price sensitivity given platform qualification requirements, while merchant chemical distributors face margin compression from spot-market lithium carbonate volatility.
Supply Chain Analysis
Strategic stockpiling of nickel sulfate and lithium hydroxide is displacing just-in-time inventory models as French gigafactories buffer against 90-day ocean freight exposure from Indonesian and Australian supply corridors. Raw material dependencies center on Class 1 nickel, battery-grade lithium spodumene, and synthetic graphite anode feedstocks. Single-source vulnerability concentrates in Southeast Asian cathode precursor refining, where Eramet SA's Sandouville facility offers partial domestic hedge. Distribution runs through direct supplier-Tier-1 relationships with embedded recycling provisions, bypassing traditional chemical distribution channels for qualified material streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's EV battery materials market is approaching a platform-economics inflection as cell-to-pack architectures and solid-state electrolyte standardization reshape interoperability requirements across Stellantis and Renault engineering ecosystems.
For Market Incumbents: Consolidate backward integration into precursor chemistries and captive recycling infrastructure to defend margin position against merchant chemical suppliers facing EU Battery Regulation compliance cost escalation. BASF SE and Umicore demonstrate viable pathways through Sandouville-adjacent refining partnerships and Hoboken closed-loop recovery assets. Priority lever sits with pre-qualifying against 2030 carbon intensity targets before certification windows compress further. For New Entrants and Emerging Players: Anchor in silicon-anode formulation supply for next-generation cell designs, where technical differentiation remains underexploited by incumbent graphite processors. White-space concentrates in silicon-doped blends serving Hauts-de-France gigafactory demand with qualified secondary feedstock streams. Go-to-market angle emphasizes dry electrode coating compatibility and reduced solvent processing intensity aligned with ESG underwriting criteria. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining conglomerates seeking to monetize non-core nickel refining assets amid battery materials specialization. Long-term viability favors operators with integrated European feedstock access and qualified recycling partnerships. Signal to watch is Automotive Cells Company supplier consolidation announcements as pre-qualification timelines compress toward platform integration deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Eramet SA's Sandouville expansion secures nickel sulfate supply for NMC 811 formulations serving French OEM programs. |
| Closed-Loop Recycling Partnership | Umicore's Hoboken infrastructure recovers lithium and cobalt from end-of-life batteries under EU Battery Regulation thresholds. |
| Carbon Footprint Certification Investment | BASF SE qualifies cathode materials against 2030 intensity targets demanded by Stellantis and Renault procurement teams. |
| Solid-State Electrolyte Development Alliance | Ceramic and sulfide architectures target 2027-2028 platform integration with lithium-metal anode compatibility. |
| Silicon-Anode Formulation Scale-Up | Next-generation cell designs specify silicon-doped graphite blends for energy density above 250 Wh/kg. |
Research Methodology
A standing panel of cathode precursor procurement managers, gigafactory operations directors, and ESG underwriting specialists provided ongoing calibration against evolving EU Battery Regulation implementation timelines. Primary interviews with Tier-1 cell manufacturer supply chain executives and secondary validation through ECHA REACH substance restriction databases, France 2030 investment plan disclosures, and customs trade flow records established material flow quantification. Bottom-up facility capacity modeling and top-down OEM platform production forecasts were triangulated for consistency.
Consistency checks validated volume and value outputs against external benchmarks including gigafactory announcement timelines and qualified supplier certification registries. Segmentation modeling spanned material type, battery technology, vehicle application, and end-user procurement structure across the projection horizon. CAGRs were derived from production capacity ramp schedules and cathode chemistry penetration curves, with inputs from nickel sulfate demand intensity per kWh and lithium hydroxide specification shifts toward high-nickel formulations.
Material uncertainties — regulatory enforcement delays, solid-state electrolyte yield breakthroughs, and Indonesian export policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding EU Battery Regulation transposition timing and recycled content threshold implementation. Revision becomes warranted when carbon border adjustment mechanism coverage expands beyond current scope or solid-state platform integration accelerates past engineering team targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market