
 France Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
France Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Manufacturing Equipment Market Insights
High-precision assembly standards for next-generation cells is rotating equipment procurement toward vendors capable of sub-micron tolerance control. Automotive Cells Company (ACC) leverages its Dunkirk gigafactory footprint to anchor demand for French-made formation and testing lines. Verkor competes on speed-to-scale in its northern France operations. Saft Groupe S.A. differentiates through its legacy in industrial battery systems and specialized process knowledge.
France Electric Vehicle Battery Manufacturing Equipment comprises machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and end-of-line validation, with typical line throughputs exceeding 200 cells per minute for automotive-grade lithium-ion production. The primary commercial purpose is enabling domestically manufactured battery packs that meet EU origin rules for electric vehicle subsidies. Assembly Equipment dominates capital expenditure as gigafactories prioritize scalable stacking and winding platforms. Solid State technology commands premium equipment valuations despite limited near-term volume, while Automation Systems capture expanding share as labor costs and precision requirements intensify across French production sites.
ANSM oversees workplace safety standards for chemical handling in battery plants, while the EU Battery Regulation imposes mandatory carbon footprint declarations and recycled content quotas that directly shape equipment specifications for French manufacturers. CE marking and France's national industrial strategy further condition market access and public funding eligibility for production line investments. Stakeholders must monitor how evolving EU due diligence rules and domestic content thresholds reshape vendor qualification criteria and equipment sourcing decisions.
Market Dynamics
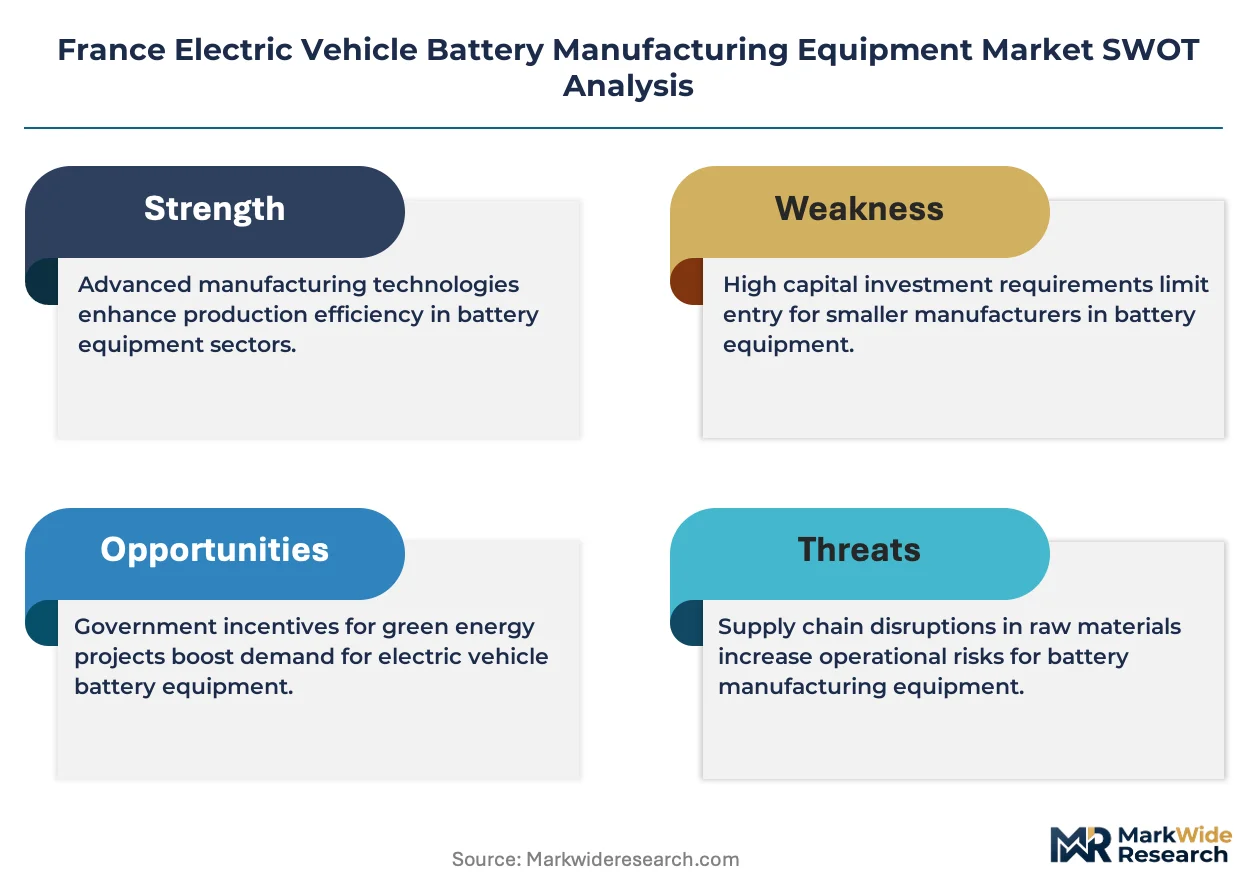
EU Battery Regulation mandates are compressing equipment procurement timelines as French gigafactories race to localize supply chains before carbon footprint thresholds take effect in 2027.
Growth Catalysts
- EU Battery Regulation carbon thresholds:Mandatory localized supply chain requirements are pulling formation and testing equipment demand toward domestic vendors capable of certifying origin compliance.
- Hauts-de-France industrial clustering:Gigafactory concentration in this northern region is generating network effects that reduce equipment installation costs and accelerate technical support response times.
- Solid-state pilot line investments:Next-generation cell architectures are opening premium equipment slots for dry electrode coating and solid electrolyte handling systems.
Market Restraints
- Specialized component import dependency:High-precision laser welding heads and vacuum drying chambers remain concentrated among German and Japanese suppliers, exposing French integrators to currency volatility and lead time extensions.
- CE marking complexity for novel processes:First-of-kind solid-state assembly equipment faces extended conformity assessment timelines that delay production line commissioning.
- Lithium supply concentration:Refining and chemical precursor processing clusters in China create upstream bottlenecks that constrain French cell output regardless of domestic equipment availability.
Strategic Opportunities
- Grand Est recycling integration:Emerging hydrometallurgical recovery facilities in this eastern region are creating demand for disassembly and black mass processing equipment that complements virgin cell manufacturing lines.
- EU Green Deal industrial funding:Strategic Important Projects of Common European Interest (IPCEI) allocations are subsidizing formation cycling infrastructure upgrades that private capital alone would not finance.
- Artificial vision-robotics convergence:Machine learning-enhanced defect detection paired with adaptive pick-and-place systems is opening retrofit markets for existing stacking platforms.
Industry Challenges
- Electrochemist-robotics engineer skill gap:French technical universities produce insufficient graduates fluent in both cell chemistry and automated production line programming, forcing manufacturers to poach from aerospace and semiconductor sectors.
- Legacy PLC integration friction:Brownfield automotive plants retrofitting for battery production face protocol incompatibilities between existing Siemens and Rockwell automation layers and new Asian equipment control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Manufacturing Equipment Market |
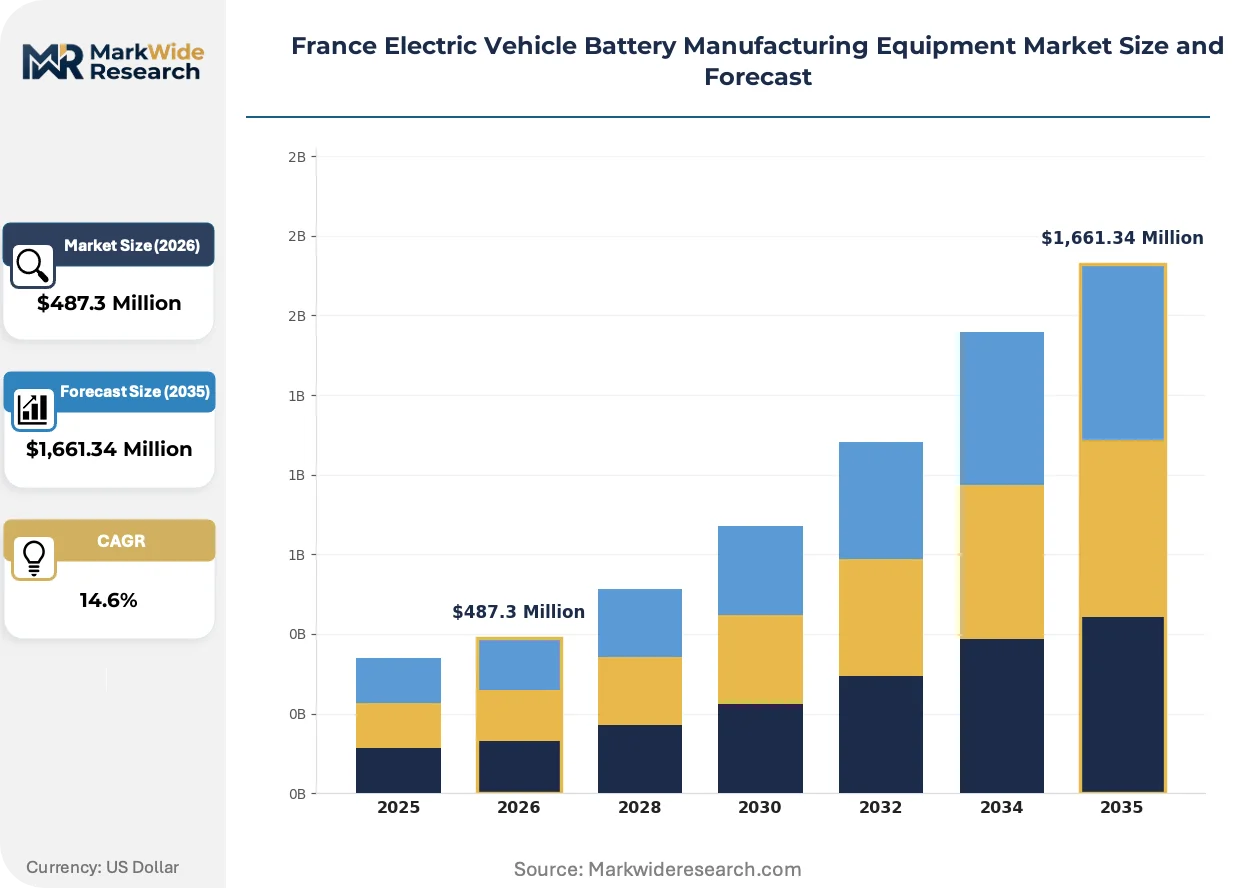
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Equipment, Testing Equipment, Automation Systems, Charging Stations Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Flow Batteries End User: Automotive Manufacturers, Battery Suppliers, Research Institutions, Aftermarket Services Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Automotive Cells Company (ACC), Verkor, AESC, ProLogium, Saft Groupe S.A., Contemporary Amperex Technology Co. Ltd., Tesla Inc., FIAMM SpA, Enersys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry electrode coating processes are eliminating solvent recovery infrastructure and reshaping factory layout economics for French producers.
Dry electrode deposition is fragmenting conventional slurry-based coating equipment procurement. Automotive OEMs in northern France are piloting binder-free calendaring systems that eliminate N-methyl-2-pyrrolidone handling entirely. This technology is fragmenting the incumbent wet chemistry equipment installed base and compressing maintenance service contract values.
ANSM workplace exposure limits for nickel and cobalt compounds are tightening ventilation and containment specifications for electrode production areas. Equipment vendors must now integrate real-time atmospheric monitoring with automated emergency isolation protocols. Cell stacking and electrolyte filling segments face the steepest retrofit costs to achieve compliance.
Buyers are consolidating vendor relationships around full-line integrators capable of warrantying throughput guarantees rather than sourcing individual machines. Tier 1 automotive suppliers in the Dunkirk corridor are rejecting multi-vendor line architectures in favor of single-source accountability for yield performance. This concentration is most visible in formation and aging equipment contracts where downtime penalties have escalated.
France Electric Vehicle Battery Manufacturing Equipment Market Segmentation
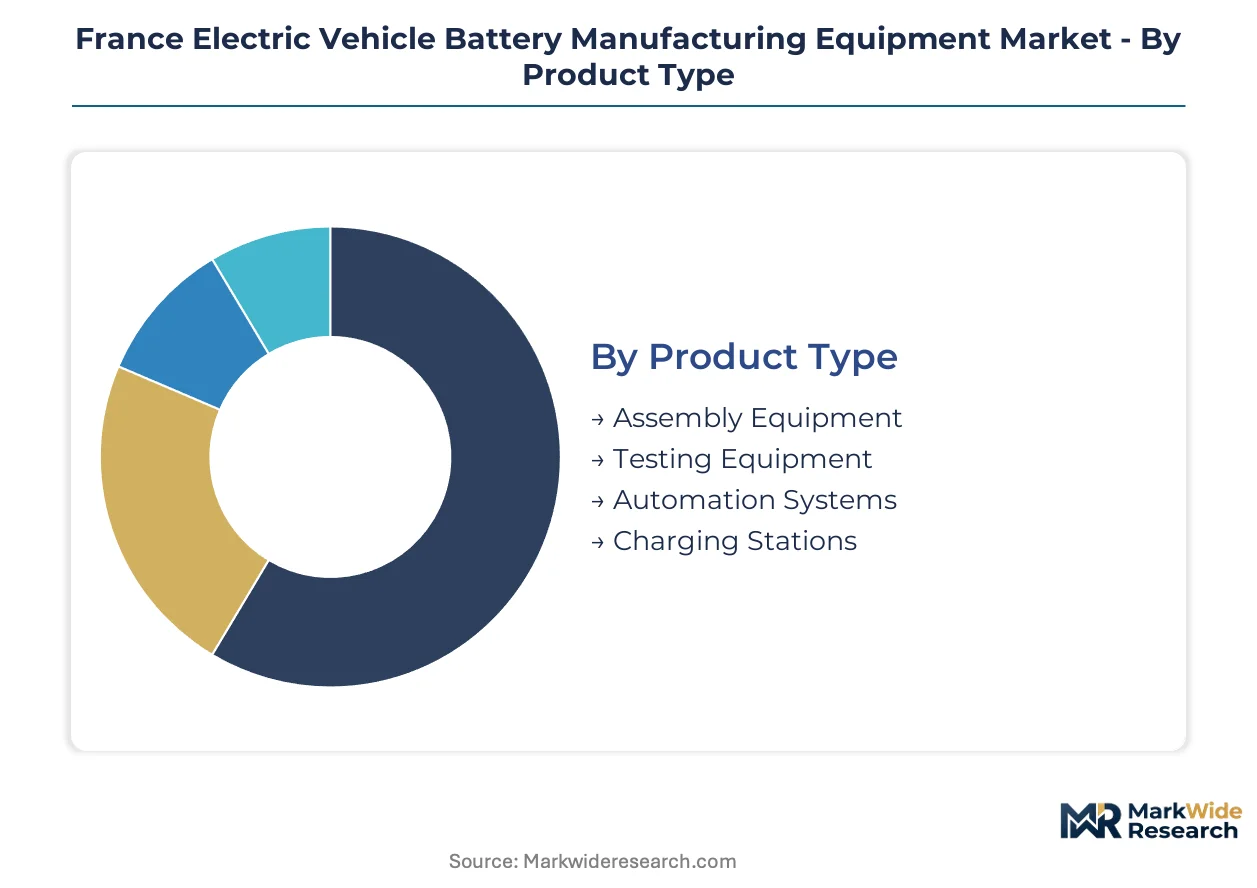
Equipment segmentation in the France Electric Vehicle Battery Manufacturing Equipment Market reveals how capital flows cluster around high-volume automotive production versus emerging technology pilots. Channel dynamics differ sharply between established lithium-ion infrastructure and next-generation solid-state development lines.
Product Type:
Direct sales dominate high-value assembly and testing platforms, while automation systems increasingly route through systems integrators serving the Hauts-de-France gigafactory corridor.
- Assembly Equipment:Stacking, winding, and tab welding machinery form the physical core of cell production lines. Demand concentrates at ACC's Dunkirk facility and Verkor's northern France operations, where line throughputs exceeding 200 cells per minute mandate sub-micron tolerance platforms.
- Testing Equipment:Formation cycling and end-of-line validation systems verify electrochemical performance before pack integration. Grand Est research partnerships are pulling specialized testing benches toward university-affiliated pilot facilities.
- Automation Systems:Robotic handling and artificial vision platforms reduce labor intensity in electrode coating and cell finishing areas.
- Charging Stations:Formation and aging infrastructure for cell conditioning before commercial deployment.
Assembly Equipment dominates installed base. Automation Systems is where expansion concentrates.
Technology:
Cost tiers separate mature lithium-ion infrastructure from premium solid-state pilot investments, with French OEMs allocating capital proportionally to near-term volume certainty.
- Lithium-ion:Wet electrode coating and liquid electrolyte handling equipment represents the standardized production backbone. Hauts-de-France gigafactories are scaling NMC and LFP cell lines to meet EU Battery Regulation origin requirements.
- Solid State:Dry electrode deposition and sulfide electrolyte handling systems command equipment valuations significantly above conventional lines. ANSM workplace exposure limits for nickel and cobalt compounds are tightening ventilation specifications specifically for this segment's pilot installations.
- Nickel-Metal Hydride:Legacy hybrid vehicle battery production equipment with limited new capital deployment.
- Flow Batteries:Stationary energy storage manufacturing systems with distinct stack assembly requirements.
Lithium-ion captures the majority of current procurement volume. Solid State is climbing the fastest despite limited near-term output.
End User:
Customer type determines warranty structures and technical support intensity, with automotive manufacturers demanding single-source accountability versus research institutions accepting multi-vendor architectures.
- Automotive Manufacturers:Stellantis, Renault, and their joint ventures anchor equipment demand through captive production strategies. These buyers consolidate vendor relationships around full-line integrators capable of throughput guarantees.
- Battery Suppliers:Specialized cell producers serving multiple OEMs require flexible reconfigurable lines. Saft Groupe S.A. leverages its industrial battery heritage to specify equipment for non-automotive applications.
- Research Institutions:CEA and university laboratories pilot next-generation chemistries with lower-volume, higher-mix equipment needs.
- Aftermarket Services:Diagnostic and remanufacturing equipment providers serving second-life battery applications.
Automotive Manufacturers dominate installed base. Battery Suppliers is where expansion concentrates.
Application:
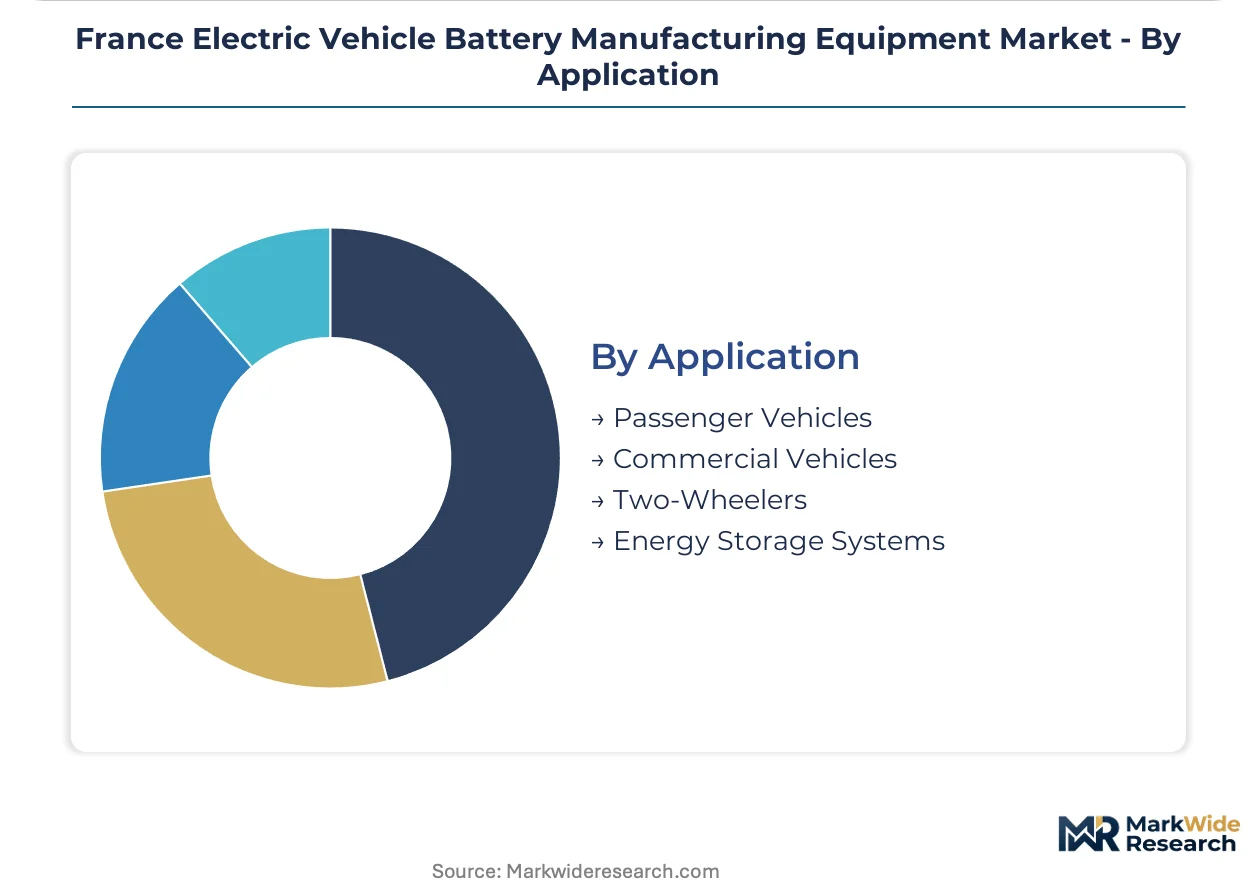
Volume scale differentiates passenger vehicle production—where line economics mandate 24/7 operation—from commercial vehicle and stationary storage segments with batch-oriented workflows.
- Passenger Vehicles:High-speed winding and stacking platforms optimized for cylindrical and prismatic cell formats. French OEMs are localizing supply chains for C-segment and D-segment electric platforms.
- Commercial Vehicles:Heavy-duty cell assembly with enhanced thermal management specifications. Battery pack scaling for electric buses and delivery vans requires modified welding and sealing equipment.
- Two-Wheelers:Compact cell production with simplified handling systems.
- Energy Storage Systems:Prismatic cell and containerized battery module assembly for grid-scale deployments.
Passenger Vehicles dominates installed base. Energy Storage Systems is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment suppliers dominate export flows into French gigafactories, while Italian automation specialists and Japanese precision component vendors complete the procurement matrix for northern France's cell production corridor.
Germany
Precision laser welding systems and vacuum drying chambers move across the Rhine into Hauts-de-France facilities. KBA vehicle certification standards and EU Battery Regulation carbon thresholds shape equipment specifications for cross-border supply contracts. Stuttgart and Munich industrial clusters anchor the supplier base serving ACC's Dunkirk operations.
Italy
Robotic handling platforms and artificial vision systems reach French plants through Alpine logistics channels. CE marking conformity assessments and national industrial automation incentives condition vendor qualification timelines. Turin-area integrators concentrate on stacking and winding line retrofits for Stellantis-linked production sites.
Japan
High-tolerance formation cycling chambers and electrolyte filling nozzles arrive via consolidated air freight routes. METI technology export frameworks and bilateral industrial cooperation agreements facilitate equipment licensing. Nagoya and Osaka precision manufacturers occupy premium slots in solid-state pilot line procurement.
South Korea
Roll-to-roll electrode coating systems and dry room environmental controls enter through Le Havre port infrastructure. MFDS chemical safety protocols and EU-Korea Free Trade Agreement tariff schedules influence total landed costs. Seoul Capital Area equipment houses compete on throughput guarantees for Verkor's northern France expansion.
China
Cost-optimized stacking machinery and automated guided vehicle systems penetrate through Rotterdam transshipment hubs. GB standards alignment pressures and EU anti-subsidy investigations create procurement friction for French buyers. Yangtze River Delta fabricators compete on price for non-critical handling equipment tiers.
France Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Listed leaders compete with private specialists across equipment integration depth, with publicly traded Asian battery giants facing off against European family-owned automation houses and venture-backed French startups. The vendor base stratifies into three tiers: full-line integrators warrantying throughput, component specialists dominating single-process niches, and emerging solid-state technology shops commanding premium valuations. Consolidation pressure runs through formation equipment contracts where downtime penalties have escalated. Geographic expansion and strategic partnerships constitute the dominant competitive moves as vendors position for EU Battery Regulation compliance certification.
Among France-based operators, Automotive Cells Company (ACC) and Verkor occupy anchor positions as demand aggregators rather than equipment vendors, their gigafactory investments pulling supplier decisions across the value chain. Saft Groupe S.A. represents the legacy industrial battery archetype, its TotalEnergies parentage enabling capital access that pure-play equipment houses cannot match. These three entities exemplify how French industrial policy channels public funding toward captive production capacity, reshaping competitive dynamics for external machinery suppliers who must now qualify through nationally sponsored procurement frameworks.
| Leading Market Players |
|---|
| Automotive Cells Company (ACC) |
| Verkor |
| AESC |
| ProLogium |
| Saft Groupe S.A. |
| Contemporary Amperex Technology Co. Ltd. |
| Tesla Inc. |
| FIAMM SpA |
| Enersys |
| Others |
Pricing and Supply Chain Analysis
Gigafactory scale economies in Hauts-de-France compress unit equipment costs while concentrating procurement leverage among ACC and Verkor, creating price floors that smaller battery suppliers cannot match and locking out marginal vendors from formation equipment contracts.
Pricing Analysis
Next-generation solid-state pilot lines command equipment valuations significantly above conventional lithium-ion infrastructure, while legacy wet-chemistry coating systems face price erosion from dry electrode displacement. Project-based contracting dominates high-value assembly platforms, with price differentiation hinging on CE marking tier and throughput guarantee structures. Cost compression in standard lithium-ion equipment intensifies as Chinese stacking machinery penetrates through Rotterdam transshipment. Research institutions exhibit highest price sensitivity due to budget constraints, whereas Stellantis-linked automotive manufacturers prioritize single-source accountability over unit cost.
Supply Chain Analysis
Rhine corridor transit underwrites just-in-time delivery of German precision laser welding heads to Dunkirk facilities, yet this chokepoint exposes French integrators to KBA certification delays and currency volatility. Equipment sourcing draws from Germany, Japan, and South Korea for high-tolerance components including vacuum drying chambers and formation cycling chambers. Raw material dependencies span lithium chemical precursors from Chinese refining clusters, precision ceramics for solid-state electrolyte handling, and rare-earth magnets for robotic handling platforms. Single-source vulnerability concentrates in Japanese electrolyte filling nozzle suppliers. Distribution runs through Le Havre port infrastructure for Korean roll-to-roll coating systems and Alpine logistics channels for Italian automation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive moat anchored in regulatory entrenchment, where EU Battery Regulation carbon thresholds and ANSM workplace exposure mandates create certification barriers that external vendors cannot rapidly replicate.
For Market Incumbents: Consolidate vendor relationships around full-line integrators capable of warrantying throughput guarantees for formation equipment contracts, neutralizing emerging Asian equipment houses competing on price. Deepen backward integration into dry electrode coating technology to capture premium valuations from solid-state pilot investments, while investing in ANSM-compliant ventilation specifications to lock in regulatory entrenchment against non-compliant challengers.
For New Entrants and Emerging Players: Aftermarket retrofit services for existing stacking platforms represent the most penetrable white space, as ACC and Verkor prioritize greenfield capacity over brownfield upgrades. Target research institution partnerships in Grand Est where university-affiliated pilot facilities accept multi-vendor architectures and lower-volume contracts. Lead with artificial vision-robotics convergence offerings that incumbent full-line integrators under-serve, using machine learning-enhanced defect detection as the go-to-market wedge.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation systems vendors with service contracts tied to 24/7 automotive production lines, offering superior cash flow quality against project-based equipment sales. Long-term viability favors specialists with captive relationships to Hauts-de-France gigafactory clusters and demonstrated EU Battery Regulation compliance certification. Watch for inflection signals in IPCEI funding allocations that subsidize formation cycling infrastructure upgrades beyond private capital capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dry Electrode Technology | Eliminates N-methyl-2-pyrrolidone handling costs and captures solid-state pilot line premiums. |
| CE Marking Acceleration for Novel Processes | Compresses conformity assessment timelines that currently delay solid-state equipment commissioning. |
| Grand Est Recycling Facility Partnership | Positions disassembly equipment vendors for hydrometallurgical recovery demand from emerging black mass processors. |
| Artificial Vision-Robotics Platform Launch | Opens retrofit markets for existing stacking platforms through machine learning-enhanced defect detection. |
| IPCEI Funding Alignment | Captures subsidized formation cycling infrastructure that private capital alone cannot finance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Battery Regulation implementation guidance, ANSM workplace safety directives, and French national industrial strategy documents. Primary interviews engaged equipment procurement managers at automotive OEMs, plant engineers at Hauts-de-France gigafactories, regulatory affairs specialists navigating CE marking pathways, and aftermarket service heads at existing production facilities. Secondary validation drew from customs trade data, SEC filings of listed battery equipment vendors, IPCEI project disclosure databases, and IHS Markit vehicle production forecasts. Bottom-up equipment procurement tracking triangulates against top-down gigafactory capacity announcements.
Segmentation dimensions modeled span product type, technology generation, end-user archetype, and regional industrial cluster concentration across the analysis window. CAGRs derive from equipment shipment value aggregation by process stage, normalized against announced gigafactory nameplate capacity and technology mix assumptions. Industry-specific forecast inputs include dry electrode adoption curves for solvent-free coating transitions and solid-state pilot line investment schedules from CEA research partnerships.
Forecasts assume regulatory continuity in EU Battery Regulation carbon threshold implementation and ANSM workplace exposure limit enforcement; material policy shifts would require re-modeling origin compliance requirements and ventilation specification retrofits. Technology disruption from solid-state chemistry maturation or lithium supply concentration in Chinese refining clusters present specific revision risks. Practitioners should keep alternative scenarios live as IPCEI funding allocation patterns and dry electrode process yields evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Advance Battery Technologies Market