
 Europe Portable Generator Market | 2026-2036
Europe Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Portable Generator Market Foresight
Copper winding substitution by aluminum in stator assemblies is restructuring cost structures across mid-power portable generator classes. Atlas Copco leverages its Swedish engineering base to dominate premium inverter segments with extended runtime architectures. HIMOINSA anchors Mediterranean demand through specialized dual-fuel systems engineered for construction site mobility. FG Wilson competes aggressively on diesel reliability ratings across British Isles rental fleets.
Europe portable generators are self-contained prime or standby power units, typically employing reciprocating engines driving synchronous alternators with output ranging from sub-kilowatt residential inverters to 50 kW+ industrial skid packages, designed for transport without fixed installation. Conventional generators still occupy the largest revenue share in industrial and events end-use, though inverter architectures are displacing them in residential and commercial segments where harmonic sensitivity and noise ordinances tighten. Diesel fuel type retains structural dominance above 5 kW power ratings across German and French industrial channels, while propane and dual-fuel options penetrate residential backup applications constrained by European storage tank regulations.
EU Stage V emission standards enforced by national regulators in Germany and France are elevating after-treatment costs and compressing margins on conventional diesel architectures below 19 kW. CE marking requirements under the EU Machinery Directive and national noise ordinances in Italy and Spain dictate acoustic enclosure specifications that differentiate market-accessible products from gray-import alternatives. Stakeholders must monitor how Stage V compliance timelines interact with battery-hybrid generator introductions to determine whether engine downsizing or electrification wins the product planning cycle.
Market Dynamics
EU Stage V emission standards are compressing margins on sub-19 kW diesel architectures while simultaneously accelerating manufacturer investment in dual-fuel and battery-hybrid platforms across German and French industrial channels.
Growth Catalysts
- Construction Fleet Electrification Mandates:German rental houses are expanding inverter generator procurement to meet municipal low-emission zones in Berlin and Hamburg construction corridors.
- CE Marking Enforcement:Stricter Machinery Directive interpretation by Italian and Spanish regulators is eliminating gray-market competition, redirecting demand toward certified European manufacturers.
- Aluminum Stator Adoption:Copper winding substitution in mid-power classes is reducing bill-of-materials costs by approximately one-fifth, enabling competitive pricing in price-sensitive Mediterranean markets.
Market Restraints
- After-Treatment Cost Burden:Stage V compliance requires diesel particulate filters and selective catalytic reduction systems that add substantial cost to sub-10 kW units, eroding affordability in residential backup segments.
- Copper Supply Concentration:European smelter capacity constraints and import dependency on Chilean and Peruvian concentrate create input volatility for manufacturers retaining copper-wound architectures in premium inverter lines.
- Propane Storage Regulation:French and Italian national fire codes restrict above-ground tank sizing for residential properties, limiting penetration of cleaner-burning gaseous fuel options in suburban backup applications.
Strategic Opportunities
- Battery-Hybrid Convergence:Integration of lithium-ion storage with downsized diesel prime movers offers runtime extension and load-following capability for UK event infrastructure contractors facing noise ordinance constraints.
- Polish Industrial Corridor:Underpenetrated manufacturing and logistics sectors in Silesia and Greater Poland present expansion targets for rental fleet operators seeking alternatives to saturated German markets.
- EU Green Deal Procurement Incentives:Public tender scoring preferences for low-carbon equipment are creating specification advantages for dual-fuel and hybrid units in municipal and utility maintenance contracts.
Industry Challenges
- Emissions Calibration Expertise Gap:Stage V engine management system tuning requires scarce combustion and after-treatment engineering talent, constraining product development velocity at mid-tier manufacturers.
- Acoustic Certification Timeline:National noise ordinance testing protocols in Italy and Spain lack harmonization, forcing redundant certification cycles that delay product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Portable Generator Market |
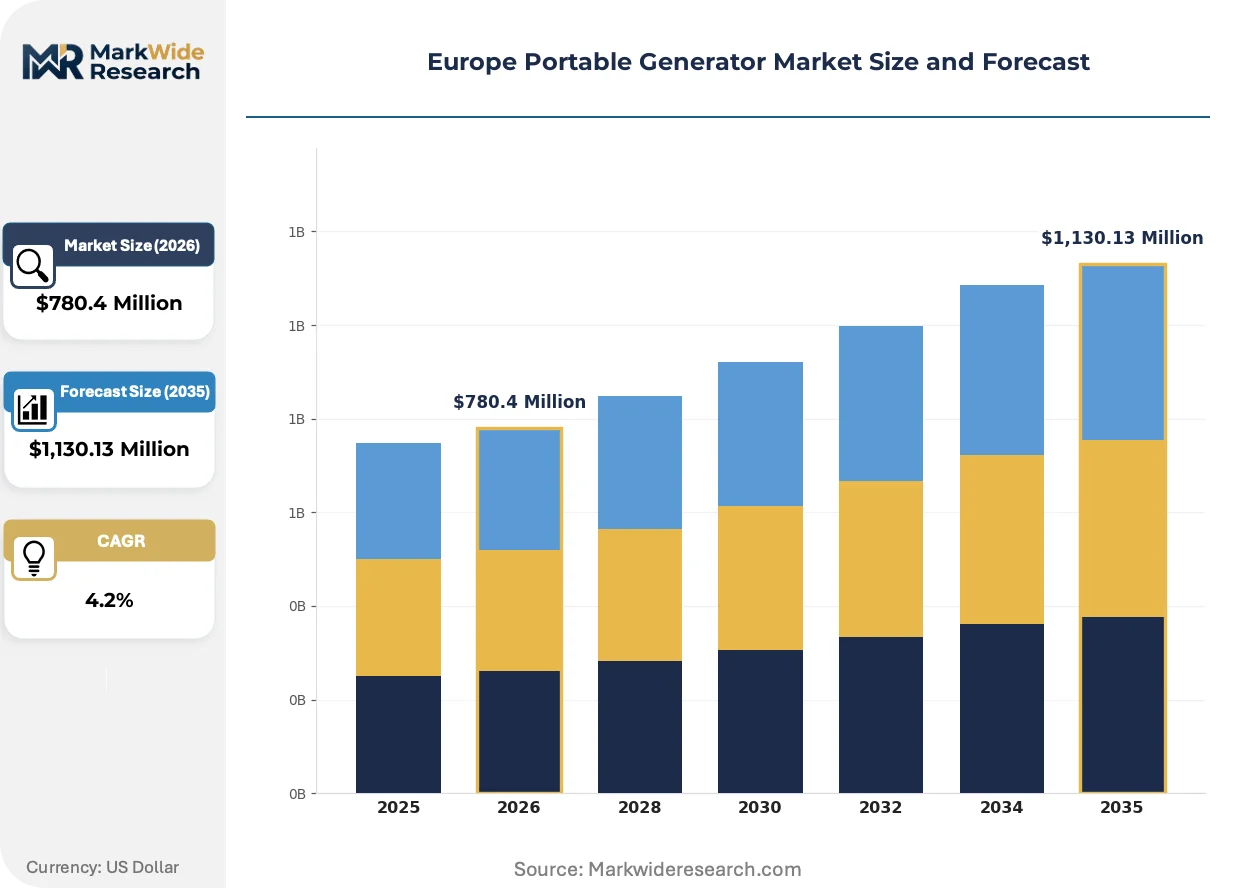
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,130.13 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generator, Conventional Generator, Solar Generator, Dual Fuel Generator End User: Residential, Commercial, Industrial, Events Fuel Type: Gasoline, Diesel, Propane, LNG Power Rating: Less than 2 kW, 2 kW to 5 kW, 5 kW to 10 kW, More than 10 kW |
| Companies Covered | Atlas Copco, HIMOINSA, Inmesol SLA, FG Wilson, Wacker Neuson SE, Generac Power Systems, Caterpillar Inc., Cummins Inc., PRAMAC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Portable Generator Market Shifts & Advancements
Product architecture is bifurcating between premium inverter platforms with extended runtime and cost-optimized conventional units, while regulatory pressure and buyer sophistication are compressing the viable middle market.
Silicon carbide power electronics in inverter generator DC-AC conversion stages is rewriting thermal management requirements and enabling 15-20% fuel efficiency gains over conventional IGBT architectures. German commercial rental operators are specifying SiC-equipped units for multi-day event deployments where refueling access is constrained. This semiconductor transition is compressing the performance gap between portable and stationary backup systems.
EU Stage V emission standards enforced by German KBA and French ANSM regulators are elevating after-treatment hardware costs and forcing engine downsizing below 19 kW displacement thresholds. Manufacturers are responding with dual-fuel architectures that can operate on diesel or pipeline natural gas, preserving runtime flexibility while reducing particulate emissions during grid-connected standby operation. French construction contractors are adopting these systems to maintain site access in Paris and Lyon low-emission zones.
Rental fleet operators are unbundling generator procurement from maintenance contracts, shifting toward hourly-usage service agreements with telemetry-enabled remote monitoring. This consumption-based model is displacing traditional capital purchase with scheduled maintenance in UK event infrastructure and German commercial construction channels. British rental houses are deploying telematics platforms that optimize fleet positioning and preventive maintenance scheduling based on actual runtime accumulation rather than calendar intervals.
Europe Portable Generator Market Segmentation
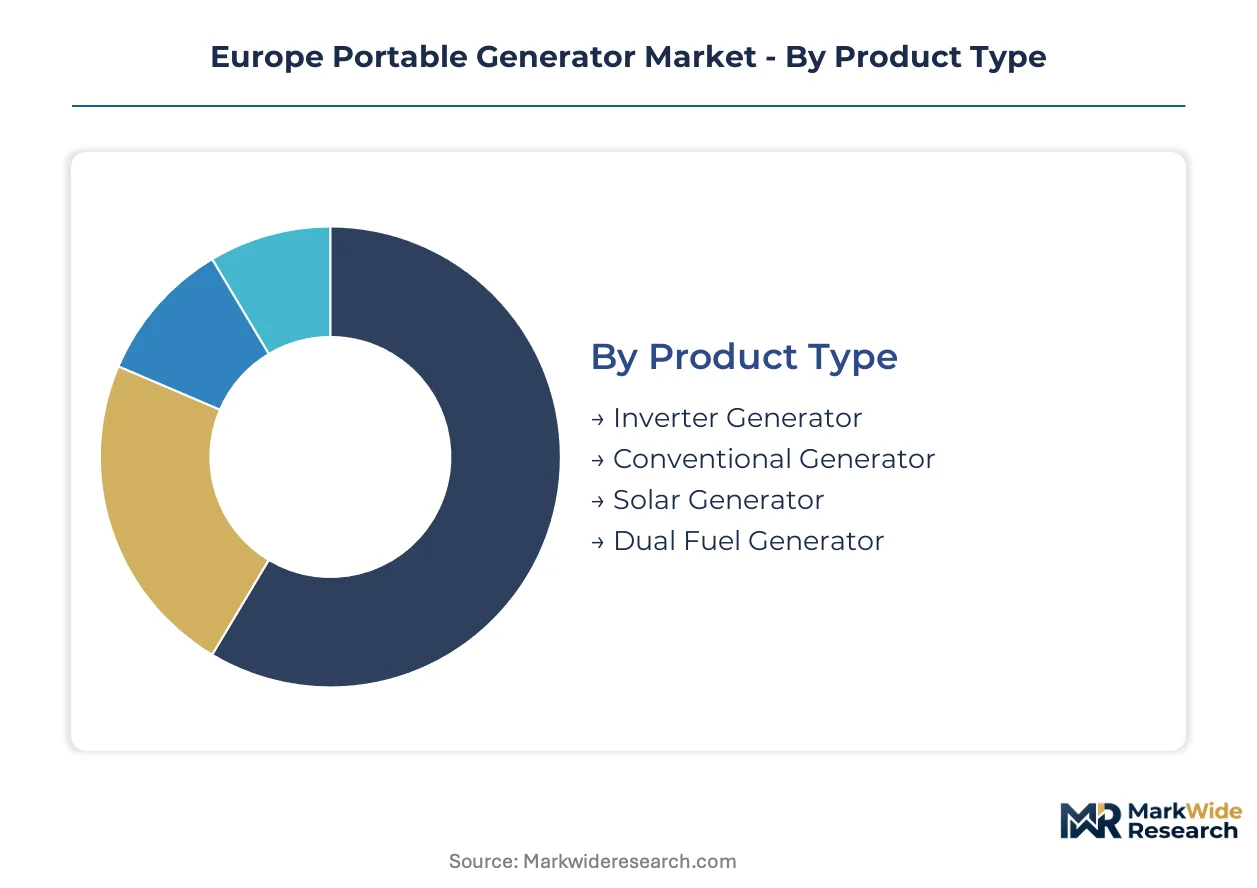
Portable generator segmentation in Europe reflects divergent certification burdens across product architectures. CE marking under the EU Machinery Directive and national noise ordinances create tiered compliance costs that reshape competitive positioning within each category.
Product Type:
Inverter architectures face the heaviest electromagnetic compatibility testing under CE marking, while conventional units confront stricter acoustic enclosure requirements in Italy and Spain.
- Inverter Generator:Silicon carbide power electronics enable 15-20% fuel efficiency gains over IGBT architectures. German rental houses specify these units for Berlin and Hamburg low-emission construction zones where harmonic sensitivity and runtime extension matter.
- Conventional Generator:Synchronous alternator designs with copper or aluminum stator windings dominate industrial and events end-use. Cost-optimized units from Mediterranean manufacturers penetrate price-sensitive channels despite higher noise profiles.
- Solar Generator:Lithium-ion battery packs with integrated PV charge controllers serve residential backup in suburban UK markets.
- Dual Fuel Generator:Diesel-natural gas flexibility preserves site access in French low-emission zones.
Conventional generators sit at the top of the volume ranking, with inverter generators climbing the fastest.
End User:
Customer type determines warranty terms and service contract structures, with rental fleet operators demanding telemetry integration unavailable in residential channels.
- Residential:Sub-kilowatt to 5 kW inverter units serve suburban backup demand. French and Italian fire codes restrict propane tank sizing, pushing diesel and dual-fuel adoption despite Stage V cost burdens.
- Commercial:UK event infrastructure contractors specify battery-hybrid configurations for noise ordinance compliance at multi-day deployments. Hourly-usage service agreements with remote monitoring displace traditional capital purchases.
- Industrial:German construction corridors drive fleet procurement of Stage V-compliant diesel above 5 kW.
- Events:Temporary power rental concentrates in British Isles infrastructure projects.
Industrial demand holds the largest revenue share, with commercial applications expanding most quickly.
Fuel Type:
Emissions calibration requirements under Stage V fragment engineering resources across combustion chemistries, elevating development costs for multi-fuel platforms.
- Gasoline:Carbureted and fuel-injected spark-ignition engines dominate sub-5 kW residential classes. Italian and Spanish regulators enforce evaporative emissions standards that eliminate gray-market competition.
- Diesel:Compression-ignition architectures retain structural dominance above 5 kW across German and French industrial channels. After-treatment hardware for Stage V compliance adds substantial cost to sub-10 kW units.
- Propane:Cleaner combustion profile constrained by European storage tank regulations in residential applications.
- LNG:Pipeline natural gas integration in dual-fuel systems reduces particulate emissions during grid-connected standby operation.
Diesel maintains the top volume position, with dual-fuel configurations gaining share fastest.
Power Rating:
Displacement thresholds for Stage V compliance create regulatory cliffs at 19 kW and 56 kW, compressing product planning around specific engine platforms.
- Less than 2 kW:Compact inverter units for recreational and light residential use. Aluminum stator substitution reduces bill-of-materials costs by approximately one-fifth in this class.
- 2 kW to 5 kW:Core residential backup segment where propane penetration faces storage regulation barriers. German KBA and French ANSM interpretation of Stage V timelines accelerates battery-hybrid introductions.
- 5 kW to 10 kW:Commercial crossover range where after-treatment cost burdens erode affordability. CE marking and national noise ordinances dictate acoustic enclosure specifications.
- More than 10 kW:Industrial and events infrastructure requiring skid-mounted or towable packages. Extended runtime architectures with telemetry-enabled fleet management dominate UK rental channels.
5 kW to 10 kW units represent the largest installed base, with more than 10 kW systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German construction corridors anchor European portable generator demand, with Berlin and Hamburg municipal low-emission zones driving fleet procurement of Stage V-compliant inverter units. KBA enforcement timelines compress product planning cycles for sub-19 kW diesel architectures.
Germany
Commercial rental houses in Berlin and Hamburg expand inverter generator procurement to meet municipal low-emission zone mandates. KBA interpretation of EU Stage V timelines accelerates battery-hybrid introductions in the 2 kW to 5 kW residential crossover segment. Bavarian manufacturing clusters concentrate engineering talent for emissions calibration expertise.
United Kingdom
Event infrastructure contractors in London and the Southeast specify battery-hybrid configurations for noise ordinance compliance at multi-day deployments. British rental houses deploy telematics platforms that optimize fleet positioning based on runtime accumulation. Midlands-based logistics sectors present expansion targets for hourly-usage service agreements.
France
Construction contractors in Paris and Lyon adopt dual-fuel systems to maintain site access in low-emission zones. ANSM enforcement of Stage V standards elevates after-treatment costs on conventional diesel architectures. Fire codes in suburban Île-de-France restrict propane tank sizing, pushing diesel and dual-fuel adoption despite compliance burdens.
Italy
Stricter Machinery Directive interpretation by Italian regulators eliminates gray-market competition, redirecting demand toward certified European manufacturers. National noise ordinance testing protocols force redundant certification cycles that delay product launches. Lombardy and Veneto industrial districts concentrate cost-optimized conventional unit production.
Poland
Underpenetrated manufacturing and logistics sectors in Silesia and Greater Poland present expansion targets for rental fleet operators. CE marking requirements under the EU Machinery Directive create specification barriers for non-certified imports. Warsaw logistics corridors drive demand for skid-mounted industrial packages above 10 kW.
Europe Portable Generator Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to share Stage V compliance costs and accelerate dual-fuel platform development. The vendor base structures around three tiers: premium inverter specialists with Swedish engineering heritage, Mediterranean dual-fuel fabricators serving construction mobility needs, and British Isles diesel reliability providers targeting rental fleet operators. Two competitive moves define current positioning: technology licensing agreements for silicon carbide power electronics integration, and backward integration into aluminum stator winding capabilities to capture cost reductions in mid-power classes.
Within the premium engineering tier, Atlas Copco anchors Scandinavian design positioning for extended runtime architectures. HIMOINSA occupies a central role in Mediterranean demand through specialized dual-fuel system fabrication. FG Wilson exemplifies British Isles competitive positioning through diesel reliability ratings across rental fleet channels. These three entities represent distinct geographic-technological archetypes rather than overlapping market contests.
| Leading Market Players |
|---|
| Atlas Copco |
| HIMOINSA |
| Inmesol SLA |
| FG Wilson |
| Wacker Neuson SE |
| Generac Power Systems |
| Caterpillar Inc. |
| Cummins Inc. |
| PRAMAC |
| Others |
Supply & Pricing Matrix
Aluminum stator winding substitution cuts material costs by roughly one-fifth as it flows from Chinese and Indian smelters through Mediterranean assembly plants into mid-power generator pricing tiers, compressing margins for copper-dependent premium inverter manufacturers while enabling competitive positioning in price-sensitive Southern European channels.
Pricing Analysis
Input-cost pass-through from copper and silicon carbide semiconductor markets shapes tiered pricing across premium inverter, standard conventional, and economy aluminum-wound segments. Price differentiation hinges on CE marking certification grade and acoustic enclosure compliance level, with Italian and Spanish noise ordinances adding certification premiums. Pricing pressure intensifies in sub-10 kW diesel classes as Stage V after-treatment hardware raises manufacturing costs without commensurate demand elasticity. Residential backup buyers exhibit highest price sensitivity, while UK event infrastructure contractors prioritize runtime extension and telemetry integration over unit economics.
Supply Chain Analysis
Reverse-logistics flows for diesel particulate filter refurbishment and lithium-ion battery pack recycling are emerging as cost centers rather than afterthoughts, with German KBA and French ANSM compliance documentation creating traceability requirements that alter end-of-life economics. Manufacturing concentrates in Germany, Italy, and Poland, with Lombardy and Veneto districts hosting cost-optimized conventional unit production. The supply chain draws from Chilean copper concentrate, Chinese rare earth processing, and Taiwanese semiconductor fabrication. Single-source vulnerability in silicon carbide substrate supply creates procurement risk. Distribution runs through rental fleet operators and specialized industrial equipment dealers rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's portable generator market has entered a late-cycle quality phase where specification premiums for Stage V compliance and extended runtime architectures now command durable pricing power against commoditized conventional alternatives.
For Market Incumbents: Hedge margin exposure in sub-19 kW diesel architectures by accelerating dual-fuel platform development and securing backward integration into aluminum stator winding capabilities. Battery-hybrid introductions threaten to displace prime-mover sales in UK event channels; defend position through telemetry-enabled service contract bundling that captures recurring revenue beyond unit placement. For New Entrants and Emerging Players: Begin with Polish Silesia and Greater Poland logistics corridors, where underpenetrated rental fleet demand meets less saturated competitive intensity than German markets. The 5 kW to 10 kW commercial crossover segment offers the most penetrable entry point, with CE marking compliance as the qualifying threshold and hourly-usage service agreements as the differentiated go-to-market mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where Stage V calibration expertise concentrates in Bavarian engineering clusters and emissions after-treatment suppliers face margin compression from engine downsizing trends. Long-term viability favors manufacturers with captive dual-fuel intellectual property and rental fleet telemetry platforms. Watch German municipal low-emission zone expansion timelines as the signal for inflection in inverter generator procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Development | Preserves site access in Paris and Lyon low-emission zones while reducing particulate emissions during standby operation. |
| Silicon Carbide Power Electronics Integration | Enables 15-20% fuel efficiency gains that close the performance gap with stationary backup systems for German rental operators. |
| Aluminum Stator Backward Integration | Captures cost reductions in mid-power classes and defends margin position against Mediterranean price competition. |
| Telemetry-Enabled Service Contract Bundling | Shifts revenue model from capital sale to hourly usage with preventive maintenance scheduling based on runtime accumulation. |
| Polish Industrial Corridor Expansion | Targets underpenetrated manufacturing and logistics sectors in Silesia with skid-mounted packages above 10 kW. |
Research Methodology
Bottom-up construction and events demand modeling reconciled against top-down engine manufacturer shipment tracking forms the analytical core of this study. Primary interviews with rental fleet procurement directors, construction site managers, event infrastructure contractors, and emissions calibration engineers were validated against secondary sources including EU Stage V implementation guidance from KBA and ANSM, Machinery Directive CE marking databases, and national noise ordinance testing protocols from Italian and Spanish regulators.
Input-output matrices mapping aluminum and copper price volatility to stator winding cost structures, silicon carbide substrate supply constraints to inverter generator production capacity, and Stage V compliance timelines to product launch cadences structured the projection framework across the analysis window. Segmentation dimensions included product architecture, power rating tier, fuel type, and end-use application. CAGRs were derived from regression analysis of historical fleet procurement patterns and regulatory mandate acceleration curves.
Several conditions sit outside the modeled scope, including potential harmonization of EU noise ordinance testing protocols, breakthroughs in solid-state battery energy density for generator replacement, and trade policy shifts affecting Chilean copper concentrate import terms. Forecasts reflect documented assumptions about Stage V enforcement consistency and rental operator willingness to adopt consumption-based service contracts. Practitioners should monitor German municipal low-emission zone expansion announcements and silicon carbide substrate capacity additions for early signals of competitive inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
US Generator Sales Market
Generators
India Diesel Generator Market
Generators
Gas Generator Sets Market
Generators
Commercial Generator Market
Generators
Telecom Generator Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Industrial Generator Sets Market
Generators
Digital Inverter Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
North America Gasoline Gensets Market
Generators
North West Europe Diesel Generator Market
Generators
India Portable Generator Market
Generators
Europe Generator Sets Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Hand Crank Power Generator Market
Generators
Global Portable Generator Market