
 United States Electric Vehicle Battery Separator Market | 2026-2036
United States Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Separator Market Insights
Polypropylene is realigning cost structures across the separator stack as manufacturers seek alternatives to higher-priced ceramic-coated substrates. Entek International leverages its domestic extrusion footprint to serve Detroit-area cell plants with reduced logistics exposure. Asahi Kasei Corporation anchors its position through wet-process polyolefin expertise refined across Japanese and US production lines. SK Innovation Co. Ltd. competes by extending its separator division's integration with sibling battery cell operations in Georgia.
A battery separator is a microporous membrane, typically 7-25 micrometers thick, positioned between anode and cathode to prevent electrical shorting while permitting lithium-ion transport; it functions as a safety-critical component whose shutdown behavior at elevated temperatures protects against thermal runaway. Polyethylene dominates volume shipments for its favorable fuse characteristics, though ceramic composite variants command premium positioning where high-nickel cathode chemistries push thermal tolerance requirements. Wet process technology leads manufacturing yield metrics, while electrospinning occupies emerging niches demanding nonwoven architectures for solid-state cell prototypes.
The Inflation Reduction Act, NHTSA battery safety protocols, and EPA industrial emissions standards collectively shape domestic separator sourcing by mandating North American assembly, prescribing abuse-test performance thresholds, and constraining solvent recovery in wet-process plants. The Department of Energy's loan programs amplify these effects by conditioning capital access on demonstrated supply chain localization. Stakeholders must weigh ceramic coating ramp timelines against polyolefin purity improvements as cell formats diversify beyond cylindrical into prismatic and pouch architectures.
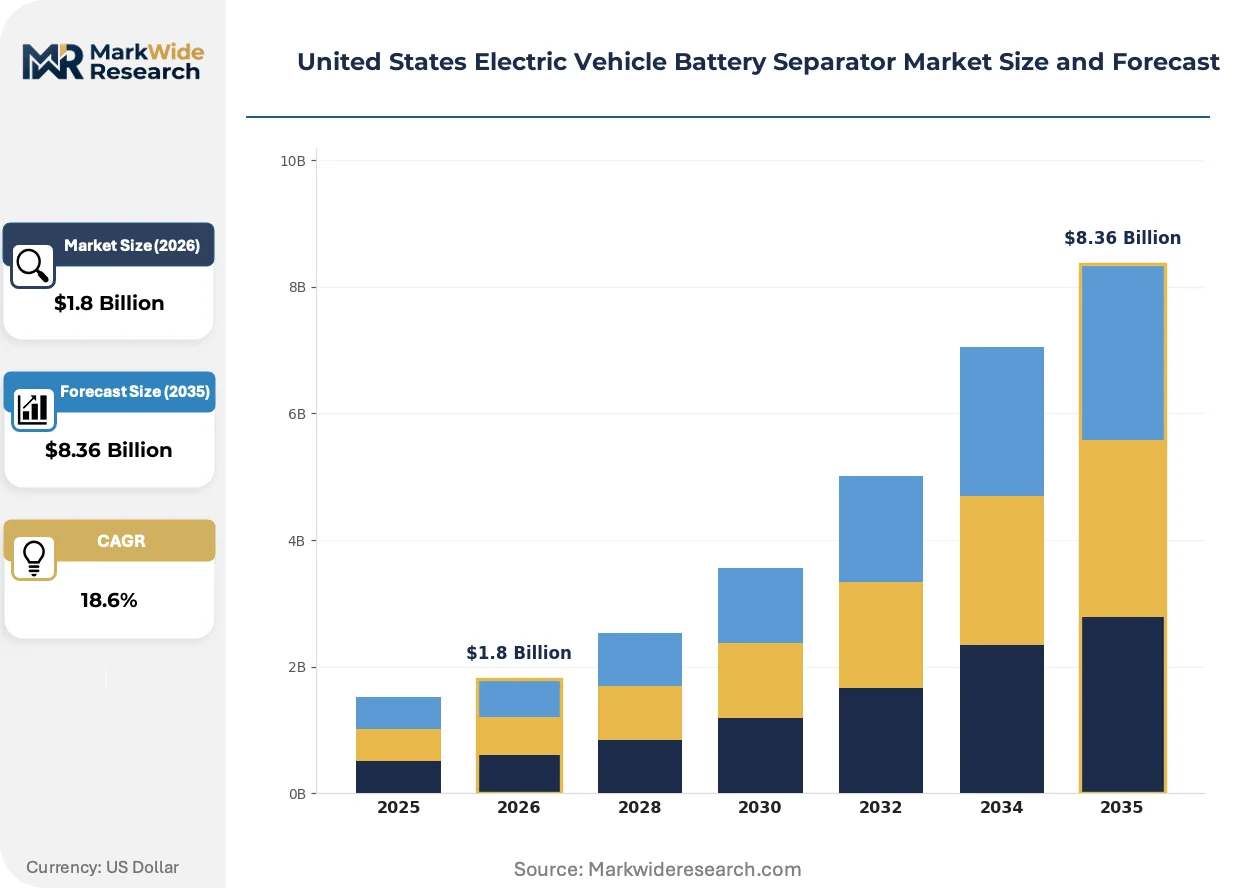
Market Dynamics
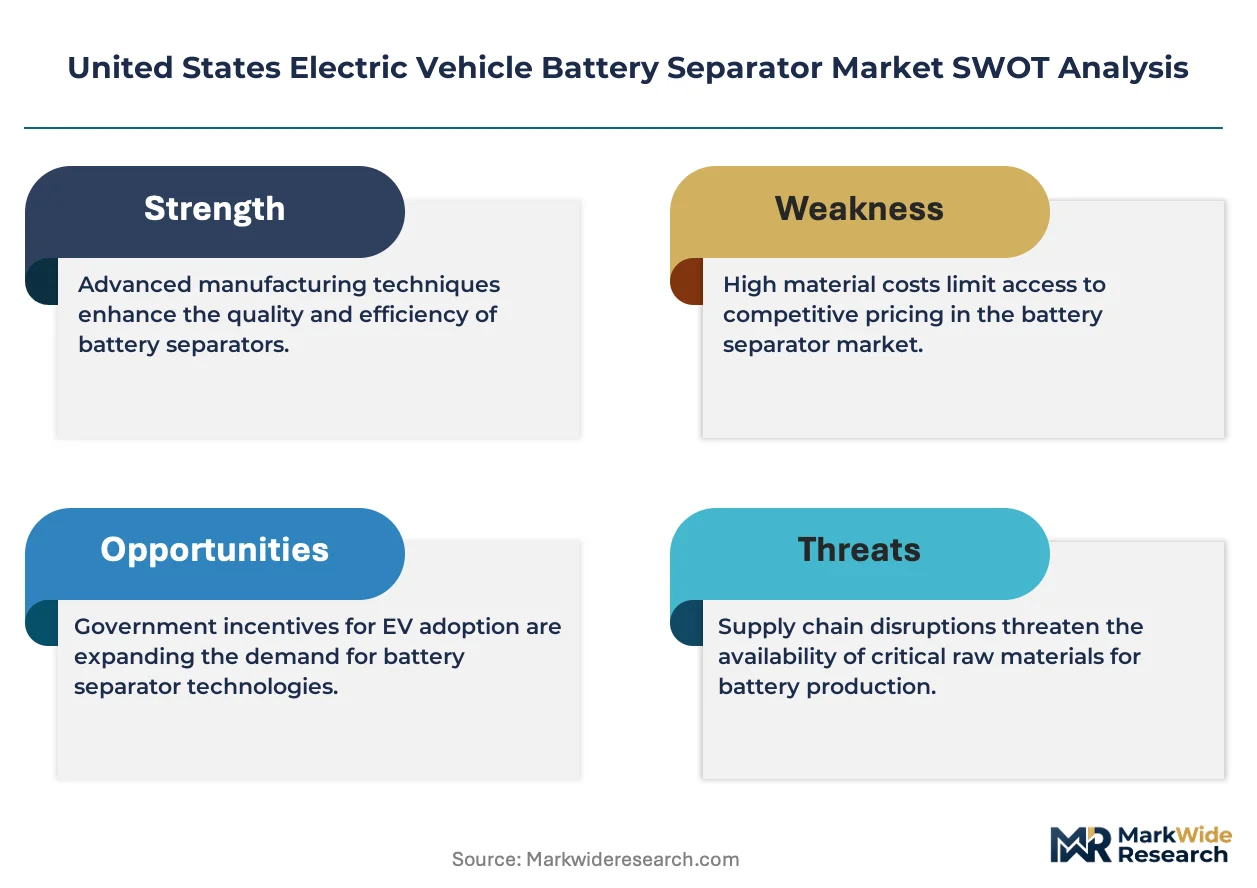
The Inflation Reduction Act's domestic content mandates are compressing separator supply chains into US-based manufacturing corridors, forcing producers to localize wet-process capacity and ceramic coating operations ahead of 2027 tax credit phase-ins.
Growth Catalysts
- Automotive OEM localization:Detroit-area cell plants are scaling cylindrical and prismatic formats, pulling separator demand toward Michigan and the Great Lakes corridor.
- IRA manufacturing credits:The Inflation Reduction Act's $35 per kWh cell production incentive conditions eligibility on North American separator sourcing.
- Ceramic-coated polyolefin migration:High-nickel cathode chemistries in next-generation cells are accelerating thermal tolerance requirements that ceramic composites satisfy.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin costs fluctuate with Gulf Coast refinery capacity and natural gas liquids pricing.
- Asian wet-process equipment concentration:Precision extrusion and biaxial stretching machinery suppliers cluster in Japan and South Korea, creating import dependency for US greenfield plants.
- NMP solvent recovery constraints:EPA emissions standards limit wet-process plant siting options and extend permitting timelines in industrial zones.
Strategic Opportunities
- Solid-state cell architectures:Electrospun nonwoven separators for sulfide and oxide electrolyte interfaces represent uncontracted demand from US solid-state startups.
- Georgia battery cluster expansion:SK Innovation's sibling cell operations in the state create captive offtake potential for integrated separator divisions.
- DOE loan program access:The Department of Energy's Advanced Technology Vehicles Manufacturing loans favor applicants with demonstrated domestic supply chain localization plans.
Industry Challenges
- Specialized polymer processing talent:Microporous membrane extrusion expertise concentrates in legacy packaging and filtration industries, requiring cross-sector recruitment.
- Qualification cycle compression:Cell OEMs demand 18-month separator validation timelines that conflict with 24-36 month wet-process line construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Separator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ceramic, Composite Technology: Electrospinning, Dry Process, Wet Process, Hybrid Process End User: Automotive OEMs, Aftermarket Providers, Fleet Services, Commercial Vehicles Performance Parameter: Thermal Stability, Ionic Conductivity, Mechanical Strength, Thickness |
| Companies Covered | Entek International, Asahi Kasei Corporation, SK Innovation Co. Ltd., Toray Industries Inc., Sumitomo Chemical Co., Ltd., Celgard LLC, SEMCORP Advanced Materials Group, Sepion Technologies, W-SCOPE Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology is bifurcating between cost-optimized polyolefin stacks for mainstream lithium-iron-phosphate cells and thermally engineered ceramic composites for high-energy-density chemistries, with manufacturing process selection becoming the critical competitive variable.
Ceramic coating deposition is integrating atomic layer precision onto polyethylene substrates to maintain ionic conductivity while elevating shutdown temperature thresholds. Tier-one cell producers in the Great Lakes region are qualifying these hybrid architectures for 800-volt fast-charge platforms. The structural consequence is compressing pure polyolefin margins while elevating coating equipment utilization rates at domestic extrusion sites.
NHTSA battery safety protocols are mandating nail-penetration and thermal propagation test performance that ceramic-reinforced separators satisfy more reliably than baseline polyolefin. Cell OEMs must document abuse-test thresholds to maintain federal vehicle certification eligibility. Prismatic format producers serving Detroit automakers are responding by specifying 12-16 micrometer ceramic-coated substrates as standard build-of-material.
Long-term supply agreements are displacing spot procurement as OEMs secure separator volume commitments tied to IRA domestic content verification requirements. Tier-one automotive cell plants are consolidating supplier panels to three qualified sources per substrate type. This concentration is most visible in Michigan, where OEMs require auditable North American assembly documentation for tax credit eligibility.
United States Electric Vehicle Battery Separator Market Segmentation
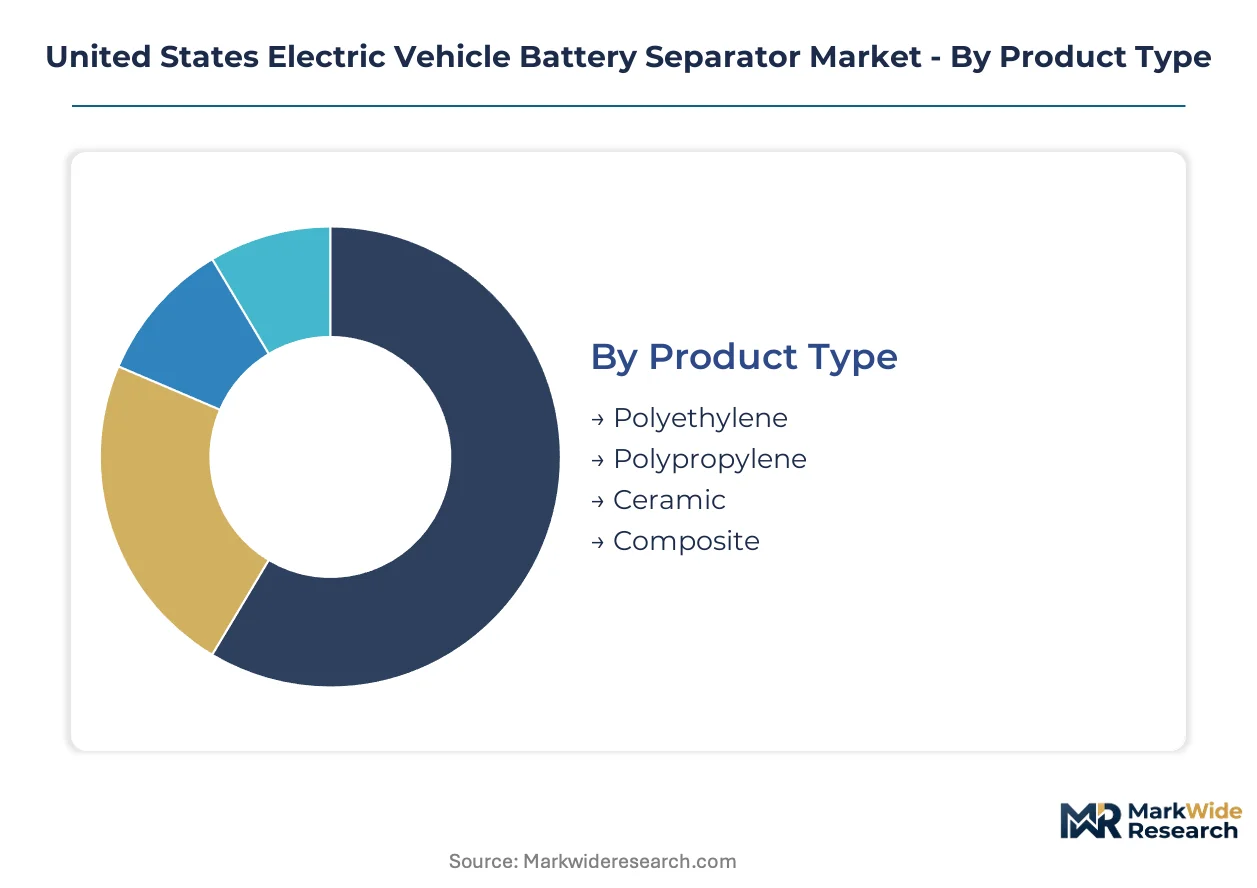
Separator segmentation in the US EV battery market tracks divergent capital requirements across material systems and process technologies. Cell OEMs configure sourcing strategies around thermal tolerance thresholds, format specifications, and IRA domestic content verification pathways.
Product Type:
Capital intensity varies sharply across material platforms, with ceramic coating infrastructure demanding the heaviest upfront investment in deposition equipment and cleanroom facilities.
- Polyethylene:Dominates volume production through wet-process biaxial stretching, yielding 7-16 micrometer membranes with reliable shutdown behavior at 130°C. Michigan-based cylindrical cell plants specify PE substrates for standard-range EV platforms where cost control outweighs extreme thermal margins.
- Polypropylene:Offers superior mechanical resilience and broader chemical stability, commanding premium positioning in prismatic formats serving Detroit automakers. Georgia cell facilities are qualifying PP-based separators for commercial vehicle duty cycles where vibration tolerance matters.
- Ceramic:Requires alumina or silica coating deposition onto polyolefin substrates, elevating puncture resistance and thermal runaway suppression for high-nickel cathode chemistries.
- Composite:Blends organic and inorganic layers to optimize ionic conductivity with abuse-test performance, gaining traction in 800-volt fast-charge architectures.
Most installed capacity flows through Polyethylene. Expansion is steepest in Ceramic.
Technology:
Process selection determines yield rates, energy consumption, and qualification timelines for domestic manufacturing.
- Wet Process:Solvent-based extraction of plasticizers from extruded polyolefin sheets produces highly uniform pore structures with superior ion transport efficiency. The Great Lakes corridor hosts the majority of US wet-process capacity, though EPA NMP recovery standards constrain greenfield siting.
- Dry Process:Mechanical stretching of crystalline polyolefin films eliminates solvent handling entirely, reducing environmental compliance burdens and capital requirements. Dry lines ramp faster but achieve narrower pore size distributions, limiting adoption in premium cell tiers.
- Electrospinning:Produces nonwoven fiber mats with tunable porosity for solid-state electrolyte interfaces, occupying pre-commercial niches.
- Hybrid Process:Combines stretching and coating stages to balance cost efficiency with performance customization.
Wet Process retains the largest operational footprint. Electrospinning is climbing the fastest as solid-state startups advance toward pilot production.
End User:
Customer concentration shapes contract structures, with automotive OEMs driving long-term offtake agreements tied to IRA credit eligibility.
- Automotive OEMs:Tier-one cell plants in Michigan and Georgia procure separators through multi-year supply agreements with auditable North American assembly documentation. OEMs specify ceramic-coated substrates for premium vehicle platforms while accepting polyolefin stacks for mass-market models.
- Commercial Vehicles:Battery electric trucks and buses demand enhanced mechanical durability and extended cycle life, pulling thicker separator specifications.
- Aftermarket Providers:Service replacement cells for legacy EV fleets, representing fragmented demand with limited volume concentration.
- Fleet Services:Electrification of rental and logistics vehicle pools creates scheduled replacement demand with predictable timing.
Procurement volume concentrates in Automotive OEMs. Commercial Vehicles are gaining share fastest as heavy-duty electrification accelerates.
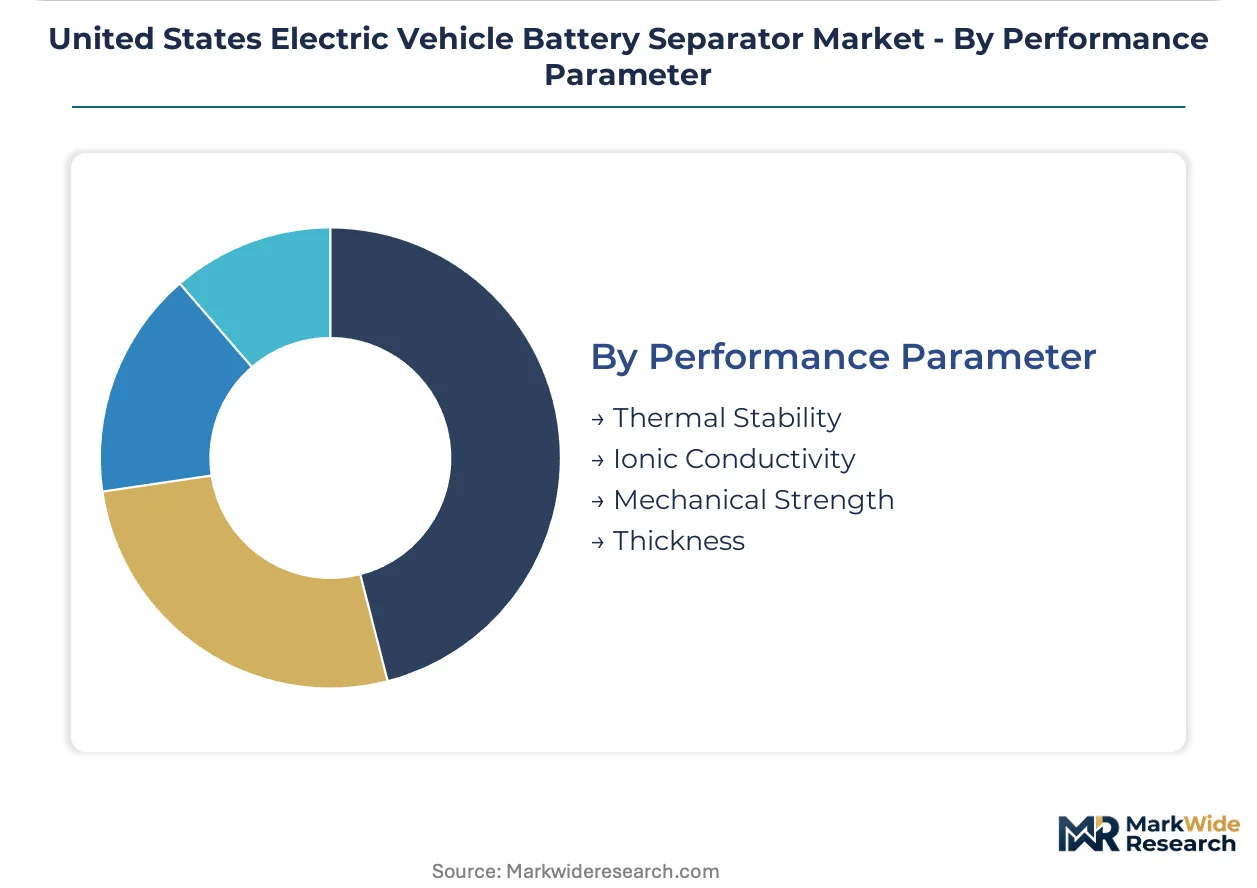
Performance Parameter:
Specification hierarchies reflect cell chemistry evolution and safety protocol mandates from NHTSA.
- Thermal Stability:Ceramic-reinforced separators demonstrate shutdown temperatures exceeding 180°C, satisfying nail-penetration test requirements for federal vehicle certification. High-nickel cathode adoption makes this the dominant selection criterion for next-generation cell designs.
- Ionic Conductivity:Directly impacts charge rate capability and energy efficiency, with wet-process PE substrates optimizing lithium-ion transport through controlled pore geometry.
- Mechanical Strength:Puncture resistance and tensile properties determine manufacturing yield and cell durability under vibration.
- Thickness:Thinning membranes below 12 micrometers increases energy density but raises manufacturing defect rates.
Supplier qualification prioritizes Thermal Stability. Thickness optimization is expanding most quickly as cell formats diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes automotive manufacturing corridor anchors domestic separator demand as Michigan cell plants scale cylindrical and prismatic production lines. Federal incentives under the Inflation Reduction Act compress supply chains into US-based manufacturing bases ahead of 2027 tax credit phase-ins.
Michigan
Detroit-area cylindrical cell plants pull polyolefin separator volume toward the Great Lakes corridor. NHTSA battery safety protocols mandate nail-penetration test performance that ceramic-coated substrates satisfy. Battle Creek and Holland host wet-process extrusion sites serving tier-one OEM qualification programs.
Georgia
SK Innovation's sibling battery operations in the state create integrated offtake demand for separator divisions. EPA NMP solvent recovery standards constrain wet-process plant siting in industrial zones. The Commerce-Jackson County corridor attracts ceramic coating deposition capacity for high-nickel cathode cell production.
Ohio
Prismatic format producers serving commercial vehicle electrification specify thicker polypropylene separators for vibration tolerance. Department of Energy loan programs condition capital access on demonstrated supply chain localization. Toledo-area polymer processing talent migrates from legacy packaging industries into membrane extrusion roles.
Texas
Gulf Coast petrochemical feedstock availability shapes polyethylene resin cost structures for separator manufacturers. OSHA industrial emissions standards intersect with EPA constraints on solvent handling facilities. Houston-area logistics infrastructure supports resin distribution to emerging Southwest cell plant locations.
California
Solid-state cell startups in the San Francisco Bay Area generate pre-commercial demand for electrospun nonwoven separators. CARB zero-emission vehicle mandates accelerate battery electric truck adoption requiring enhanced thermal tolerance membranes. Fremont-area pilot lines qualify hybrid ceramic-polyolefin architectures for 800-volt platforms.
United States Electric Vehicle Battery Separator Market Competitive Landscape
Global majors compete with regional champions across process technology and domestic content verification capabilities. The vendor base organizes around wet-process polyolefin expertise, ceramic coating deposition scale, and captive integration with cell manufacturing. Three archetypes dominate: Japanese-Korean wet-process specialists, US-based extrusion incumbents, and Chinese material suppliers seeking IRA-compliant assembly documentation. Capacity expansion and strategic localization partnerships constitute the primary competitive moves as OEMs consolidate supplier panels.
Among Japanese-Korean wet-process specialists, Asahi Kasei Corporation and Toray Industries Inc. occupy positions refined through decades of biaxial stretching expertise across Pacific Rim production lines. SK Innovation Co. Ltd. exemplifies the captive integration archetype, with its separator division's proximity to sibling cell operations in Georgia creating auditable North American assembly pathways. Entek International anchors the US-based extrusion tier, leveraging domestic footprint to serve Detroit-area plants with reduced logistics exposure and accelerated qualification timelines.
| Leading Market Players |
|---|
| Entek International |
| Asahi Kasei Corporation |
| SK Innovation Co. Ltd. |
| Toray Industries Inc. |
| Sumitomo Chemical Co., Ltd. |
| Celgard LLC |
| SEMCORP Advanced Materials Group |
| Sepion Technologies |
| W-SCOPE Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive integration with sibling battery cell operations anchors supply positioning and pricing power for separator divisions serving Georgia-based OEM qualification programs. IRA domestic content verification requirements compress procurement into long-term offtake agreements, eliminating spot-market volatility and cementing volume commitments from tier-one automotive cell plants.
Pricing Analysis
Polypropylene and polyethylene resin costs pass through directly to separator substrate pricing, with Gulf Coast petrochemical feedstock volatility creating quarterly adjustments in contract structures. Three-tier pricing structure across ceramic-coated premium, wet-process polyolefin standard, and dry-process economy levels reflects thermal tolerance certification tiers and NHTSA abuse-test performance thresholds. Cost compression in baseline polyolefin stacks intensifies as Asian equipment imports elevate capital recovery requirements for US greenfield plants. Mass-market lithium-iron-phosphate cell producers exhibit highest price sensitivity, while 800-volt fast-charge platform OEMs accept premium positioning for ceramic-reinforced architectures.
Supply Chain Analysis
Reverse-logistics flows for separator manufacturing center on solvent recovery and resin reprocessing, with EPA NMP recovery standards mandating closed-loop extraction systems at wet-process plants. Primary manufacturing concentrates in Japan, South Korea, and the United States, with precision extrusion and biaxial stretching machinery sourcing tethered to Pacific Rim equipment suppliers. Raw material dependencies span polyethylene and polypropylene resins, alumina and silica ceramic coating precursors, and NMP solvent stocks. Single-source vulnerability in wet-process equipment imports creates qualification timeline risk for domestic capacity expansion. Distribution runs through direct mill-to-plant supply agreements with tier-one cell producers, bypassing distributor intermediaries to satisfy IRA assembly documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electric Vehicle Battery Separator Market functions as a stable compounder, with IRA manufacturing credits and NHTSA safety protocols locking in decade-long procurement visibility for qualified suppliers.
For Market Incumbents: Extend ceramic coating deposition capacity in the Great Lakes corridor ahead of 800-volt platform qualification cycles, while backward integration into polyolefin resin compounding defends margin position against petrochemical feedstock volatility. SK Innovation's captive Georgia integration model threatens independent suppliers without sibling cell offtake; incumbents must secure multi-year supply agreements with auditable North American assembly documentation to maintain OEM panel positions. For New Entrants and Emerging Players: Launch via electrospun nonwoven separator supply to California solid-state cell startups, where pre-commercial demand lacks incumbent qualification lock-in. The San Francisco Bay Area cluster represents the most penetrable geography, with sulfide and oxide electrolyte interface specifications creating white-space demand unaddressed by wet-process polyolefin specialists. Target DOE loan program applicants requiring demonstrated domestic supply chain localization plans as anchor customers. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion specialists with EPA-compliant wet-process assets because IRA domestic content mandates compress supplier panels to three qualified sources per substrate type. Five-to-ten-year viability hinges on ceramic coating equipment utilization rates and OEM qualification cycle completion. Monitor Georgia and Michigan cell plant construction permits as inflection indicators for separator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captures premium positioning for high-nickel cathode chemistries in 800-volt platforms. |
| Backward Integration into Resin Compounding | Reduces Gulf Coast petrochemical feedstock exposure and stabilizes input cost structures. |
| DOE Loan Program Participation | Accelerates capital access for domestic wet-process greenfield capacity ahead of tax credit phase-ins. |
| Solid-State Separator Partnership | Positions electrospun nonwoven supply for sulfide electrolyte interface commercialization. |
| Long-term OEM Supply Agreement | Locks in volume commitments with auditable North American assembly documentation for IRA eligibility. |
Research Methodology
Multiple input streams — primary interviews with separator division executives, OEM procurement leads, and EPA compliance officers, alongside secondary validation — were reconciled to construct demand estimates. Primary fieldwork engaged wet-process plant managers, ceramic coating equipment suppliers, and tier-one cell producer qualification engineers. Secondary sources included NHTSA battery safety protocol filings, DOE loan program application disclosures, EPA emissions compliance records, and SEC 10-K filings from listed materials companies. Bottom-up capacity-by-facility analysis and top-down OEM demand aggregation were cross-referenced to triangulate market sizing.
Historical production trends were cross-referenced against panel input from industry stakeholders to anchor growth trajectory assumptions across the analysis window. Segmentation modeling tracked material system, process technology, end-user category, and performance parameter dimensions. CAGRs were derived from facility expansion announcements, OEM cell plant commissioning schedules, and IRA credit uptake projections. Forecast inputs incorporated resin cost curves, equipment import lead times, and NHTSA regulatory evolution timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMP solvent recovery standard revisions or Pacific Rim equipment export restrictions. Practitioners should monitor Georgia cell plant production ramp rates and Michigan OEM qualification cycle completions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Battery Lug Market