
 Italy Electric Vehicle Battery Separator Market | 2026-2036
Italy Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Battery Separator Market Insights
Modular separator-cell bundling is hardening as the dominant procurement pattern across Italian battery supply chains. Asahi Kasei Corporation anchors its European position through high-porosity polymer substrate specialization. SK Innovation Co. Ltd competes on coated separator architectures designed for nickel-rich cathode chemistries. Toray Industries Inc. leverages its Torayca carbon fiber know-how to differentiate in composite separator substrates.
An electric vehicle battery separator is a microporous membrane, typically 10–30 micrometers thick, interposed between anode and cathode to prevent electrical shorting while permitting lithium-ion transport through electrolyte-filled pores. Its primary function is thermal shutdown protection, where pores collapse above a threshold temperature to halt ion flow and avert thermal runaway. Ceramic-coated separators command premium positioning in passenger vehicle applications where cycle life and abuse tolerance outweigh cost sensitivity. Micro-porous polymer substrates sustain volume leadership across Italian supply chains due to mature extrusion and biaxial stretching infrastructure. Nanofiber technology represents the fastest-growing segment, though manufacturing scale constraints limit near-term margin capture.
Italy's Ministry of Economic Development enforces battery safety protocols aligned with EU Battery Regulation traceability mandates, while CE marking under the EU Green Deal framework shapes product access thresholds for separator suppliers. The National Recovery and Resilience Plan channels state aid toward Turin-Milan corridor gigafactory zones, conditioning where separator qualification programs concentrate. Stakeholders must monitor how EU Critical Raw Materials Act sourcing rules reshape ceramic coating supply chains before committing to fixed separator-platform contracts.
Market Dynamics
Modular separator-cell bundling is hardening procurement patterns across Italian battery supply chains, compressing qualification timelines and conditioning separator suppliers to platform-level integration rather than component-only sales.
Growth Catalysts
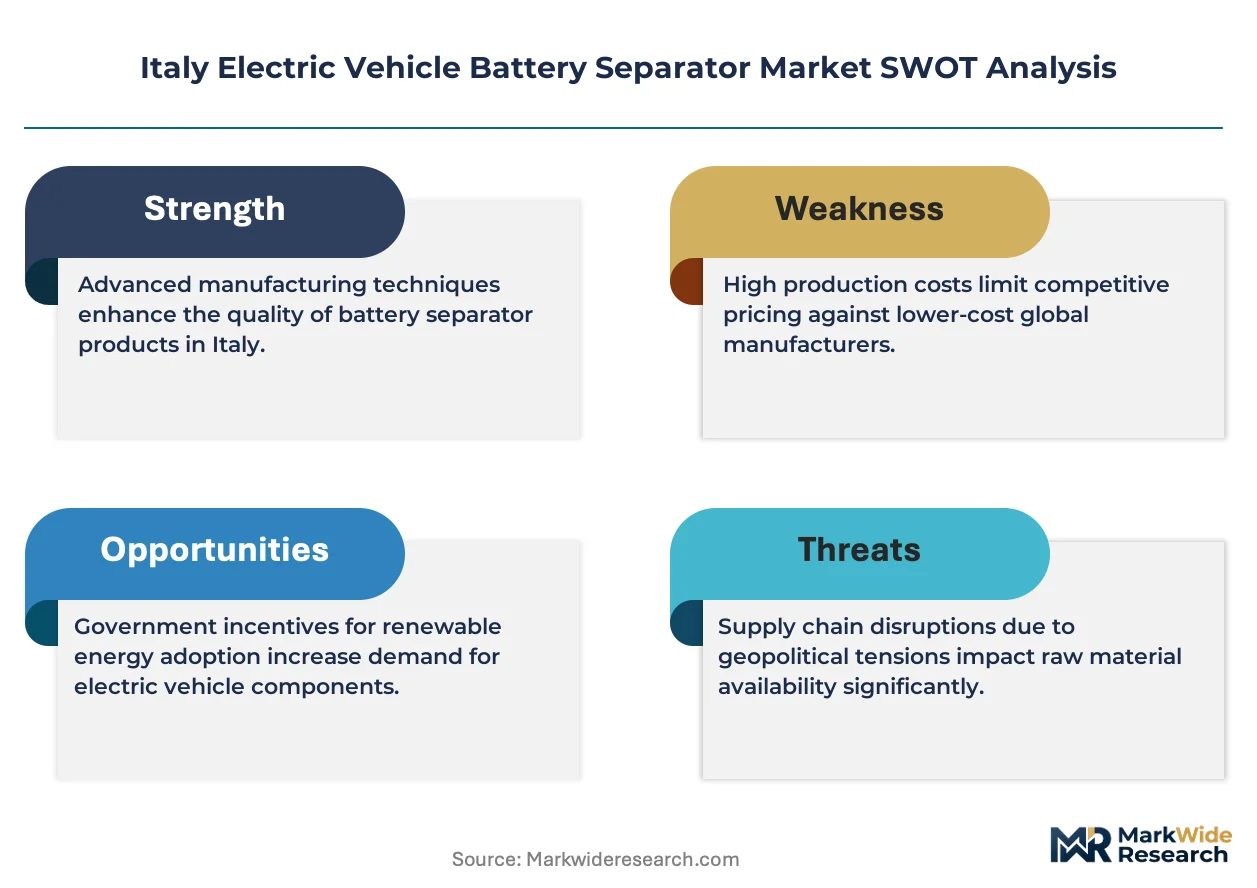
- National Recovery and Resilience Plan:State aid flows toward Turin-Milan corridor gigafactory zones, concentrating separator demand in qualified industrial clusters with pre-approved infrastructure.
- Thicker ceramic-coated architectures:Premium passenger vehicle platforms absorb advanced separator stacks, pulling investment toward high-porosity substrate specialization.
- Northern industrial corridor concentration:Piedmont-Lombardy-Emilia-Romagna manufacturing density creates captive demand pools adjacent to separator production sites.
Market Restraints
- Ceramic coating input volatility:Alumina and boehmite supply chains face price instability from EU Critical Raw Materials Act sourcing constraints.
- Extrusion infrastructure lock-in:Mature biaxial stretching equipment across Italian polymer substrate producers limits rapid pivot to nanofiber architectures.
- CE marking compliance friction:EU Battery Regulation traceability mandates extend separator qualification timelines by 8-14 months for new entrants.
Strategic Opportunities
- Emilia-Romagna gigafactory adjacency:Underdeveloped separator qualification programs near Modena and Bologna production sites offer first-mover positioning.
- Nanofiber-polymer hybrid convergence:Composite substrate architectures blend electrospun layers with stretched polymer backbones, opening patent white space.
- Direct OEM contracting channels:Stellantis platform integration teams seek bypass relationships with separator specialists, disintermediating traditional cell-maker procurement.
Industry Challenges
- Electrospinning scale-up talent scarcity:Nanofiber manufacturing requires polymer physics specialists absent from Italian technical training pipelines.
- Platform-lock certification timelines:Fixed separator-cell bundling contracts demand 18-24 month validation cycles that freeze supplier switching.
- Backward integration pressure:Cell producers demand in-house coating capabilities, compressing margins for substrate-only suppliers.
Report Scope
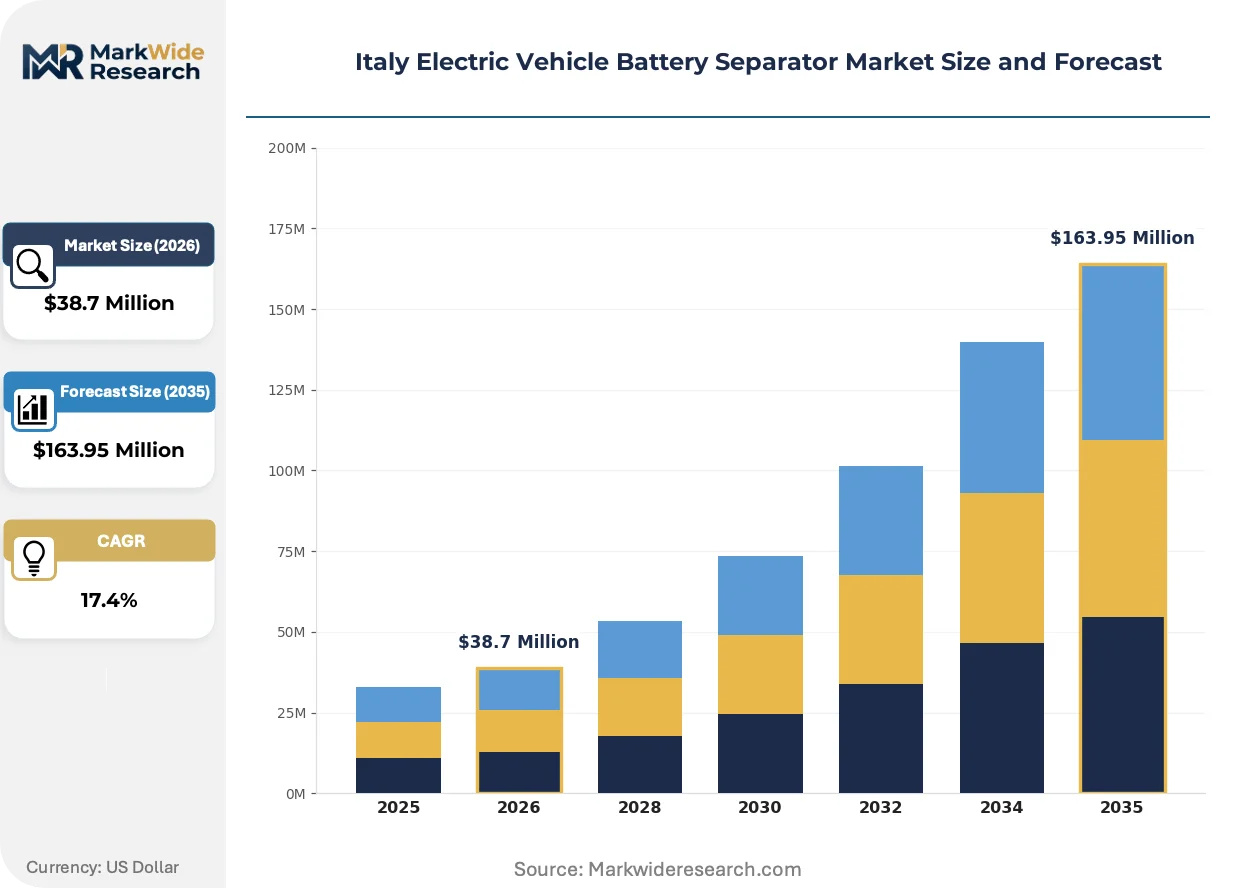
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Battery Separator Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $163.95 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Ceramic, Glass, Composite Technology: Micro-porous, Nanofibers, Coated, Laminated End User: Automakers, Battery Manufacturers, Research Institutes, Aftermarket Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage |
| Companies Covered | Teijin Ltd, Asahi Kasei Corporation, Mitsubishi Chemical Group Corporation, W-SCOPE Corporation, SK Innovation Co. Ltd, Hitachi Chemical Company Ltd, Sumitomo Chemical Co. Ltd, SEMCORP Co. Ltd, Toray Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology trajectories in Italy center on thickness-precision automation, regulatory traceability hardening, and procurement model compression toward platform-level contracts.
Automated ceramic coating thickness control is automating quality consistency across separator production lines. Stellantis integration teams specify sub-micron coating uniformity for next-generation nickel-rich cathode packs. This precision automation is compressing reject rates and enabling single-source platform awards previously split across multiple suppliers.
EU Battery Regulation traceability mandates reshape separator supply chain documentation. CE marking under the EU Green Deal framework now requires batch-level material origin certification extending to ceramic coating precursors. Northern Italian cell producers are responding by pre-qualifying separator suppliers with embedded supply chain audit capabilities, favoring integrated substrate-coating operations over pure-play substrate vendors.
Platform-level procurement contracts are displacing component spot purchasing across Italian battery supply chains. Cell producers now contract directly with separator specialists for multi-year platform supply, bundling qualification, volume guarantees, and technical co-development. This behavioral shift concentrates most visibly in the Turin-Milan corridor where Stellantis and Ferrari integration teams operate with consolidated supplier panels.
Italy Electric Vehicle Battery Separator Market Segmentation
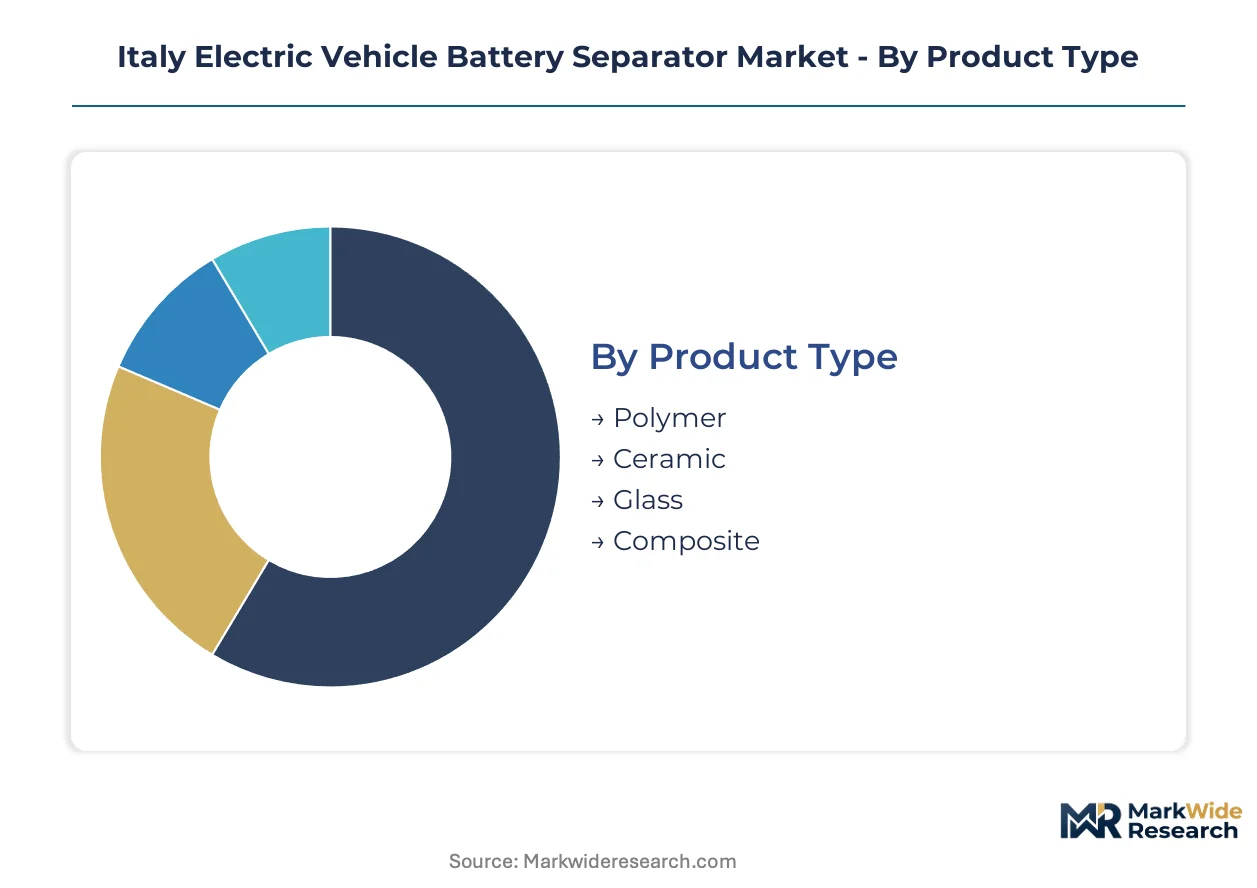
Separator procurement in Italy stratifies sharply across certification tiers. CE marking under the EU Battery Regulation applies differentially to ceramic-coated versus polymer substrates, while traceability mandates reshape supplier qualification pathways for each segment cluster.
Product Type:
CE marking intensity varies by substrate composition, with ceramic formulations facing the steepest documentation burdens under EU Battery Regulation traceability rules.
- Polymer:Polyethylene and polypropylene substrates dominate Italian production through mature biaxial stretching infrastructure. Piedmont-based extrusion lines supply Stellantis platform teams with 12-25 micrometer membranes qualified for nickel-manganese-cobalt cell architectures.
- Ceramic:Alumina and boehmite coatings command premium positioning in Ferrari and Stellantis luxury platforms where thermal runaway tolerance outweighs cost sensitivity. CE marking documentation extends 8-14 months for new ceramic coating suppliers due to precursor origin certification requirements.
- Glass:Borosilicate fiber matrices serve niche high-temperature applications in commercial vehicle battery packs.
- Composite:Hybrid polymer-ceramic laminates blend electrospun layers with stretched backbones, opening patent white space for Turin-Milan corridor developers.
Polymer sits at the top of the volume ranking, with Composite climbing the fastest.
Technology:
Cost tiers separate technologies sharply, with micro-porous extrusion at the economy end and nanofiber electrospinning at premium positioning.
- Micro-porous:Biaxial stretching of polyolefin films sustains volume leadership across Italian supply chains due to depreciated capital equipment and qualified technician pools.
- Nanofibers:Electrospun polymer architectures achieve sub-micron pore precision for high-rate cycling applications. Manufacturing scale constraints limit near-term margin capture, though patent filings from Emilia-Romagna research clusters signal acceleration.
- Coated:Ceramic deposition onto polymer substrates absorbs the majority of Stellantis platform integration investment, with automated thickness control compressing reject rates.
- Laminated:Multi-layer stacks fuse separator functions with electrolyte retention layers, qualifying for solid-state cell development programs near Milan.
Micro-porous dominates shipment volumes, while Nanofibers gain share fastest in patent filings.
End User:
Customer type determines contract structure, with automakers driving platform-level bundling and battery manufacturers resisting backward integration pressure.
- Automakers:Stellantis and Ferrari integration teams specify separator performance at the platform level, compressing cell-maker procurement autonomy. Direct OEM contracting channels disintermediate traditional supply relationships in the Turin-Milan corridor.
- Battery Manufacturers:Cell producers demand in-house coating capabilities, squeezing margins for substrate-only specialists. Northern Italian gigafactory operators pre-qualify suppliers with embedded supply chain audit capabilities.
- Research Institutes:Politecnico di Torino and University of Bologna labs pilot nanofiber scale-up for next-generation solid-state architectures.
- Aftermarket:Replacement separator demand remains negligible given cell-level sealing and battery pack integration.
Automakers anchor procurement volumes, with Research Institutes expanding most quickly in patent output.
Application:
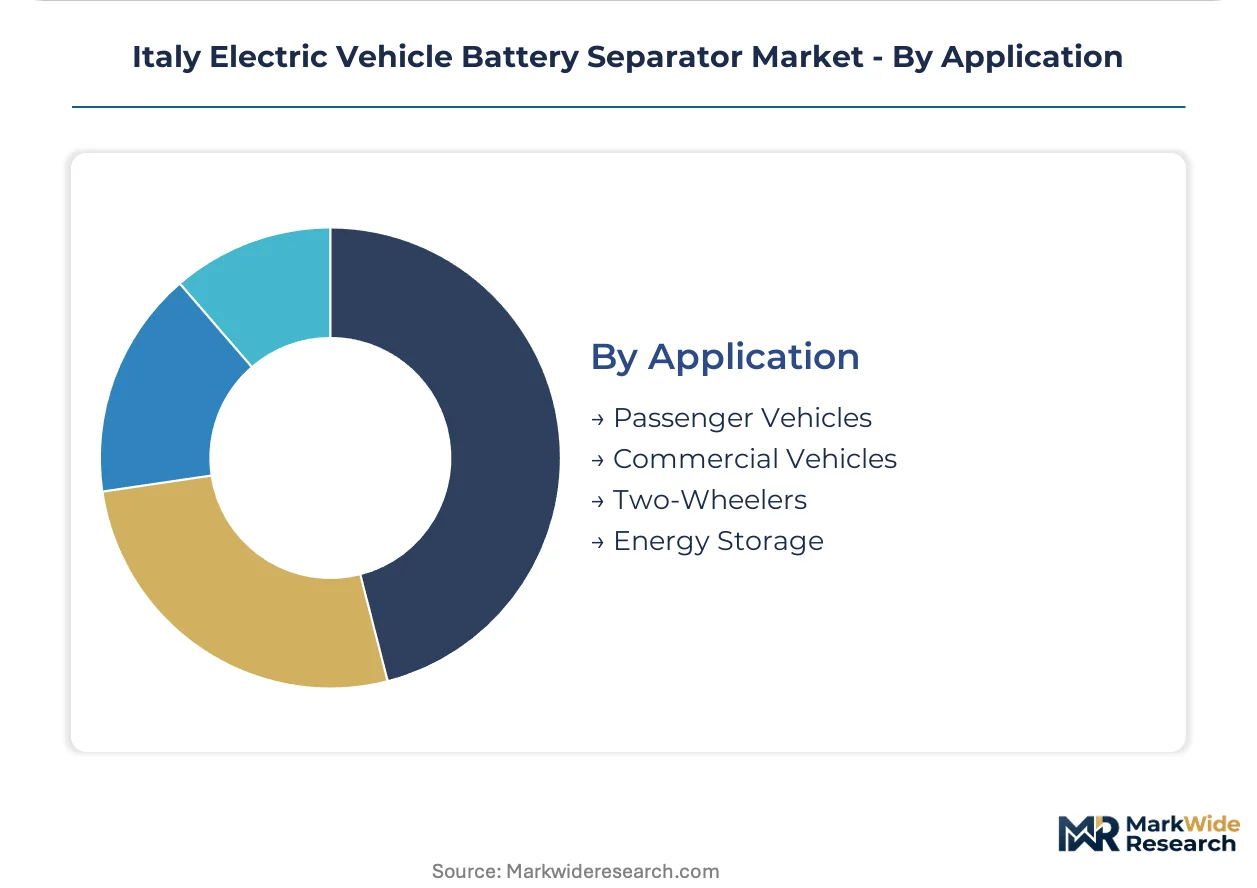
Application maturity separates segments, with passenger vehicles at commercial scale and energy storage still qualifying separator architectures.
- Passenger Vehicles:Premium platforms from Stellantis and Ferrari absorb thicker ceramic-coated separator stacks. Cycle life specifications exceed 1,500 cycles for Italian luxury electric vehicle programs.
- Commercial Vehicles:Heavy-duty cycle profiles demand enhanced abuse tolerance, pulling composite separator development toward bus and truck platforms.
- Two-Wheelers:Cost-constrained scooter and motorcycle applications sustain polymer substrate dominance with minimal coating layers.
- Energy Storage:Grid-scale battery qualification programs near Modena test separator longevity under static cycling regimes distinct from automotive duty cycles.
Passenger Vehicles command the volume lead, with Energy Storage posting the steepest expansion trajectory in pilot program announcements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's battery separator industry traces its lineage to Turin's post-war polymer processing clusters, which evolved from Fiat's supply base into specialized membrane extrusion corridors serving European automotive platforms.
Piedmont
Stellantis integration teams in Turin specify ceramic-coated separator stacks for premium electric vehicle platforms. The National Recovery and Resilience Plan channels state aid toward gigafactory zones near the city. Polymer substrate extrusion lines in the region supply qualified membranes to nickel-manganese-cobalt cell architectures.
Lombardy
Milan's industrial automation ecosystem supports precision coating equipment for separator thickness control. CE marking compliance centers cluster here under EU Battery Regulation traceability mandates. Research institutes near the city pilot nanofiber scale-up for next-generation solid-state battery programs.
Emilia-Romagna
Underdeveloped separator qualification programs near Modena and Bologna production sites attract first-mover investment. The region's automotive heritage from Ferrari and Lamborghini operations pulls demand for high-tolerance ceramic formulations. Pilot energy storage programs test separator longevity under static cycling regimes distinct from automotive duty cycles.
Veneto
Chemical processing infrastructure around Padua and Verona supplies alumina and boehmite precursors for ceramic coating operations. EU Critical Raw Materials Act sourcing constraints reshape procurement patterns for these inputs. Technical training partnerships with local universities address electrospinning talent scarcity.
Italy Electric Vehicle Battery Separator Market Competitive Landscape
The competitive structure tilts toward substrate-coating specialists with integrated European supply chains. Three to five Japanese and Korean conglomerates anchor procurement panels through long-term platform contracts. Two strategic archetypes dominate: polymer extrusion specialists with depreciated capital bases, and ceramic coating integrators commanding premium positioning. Competitive moves concentrate on backward integration into precursor supply and automated thickness-control licensing.
Among Japanese fabricators, Teijin Ltd and Toray Industries Inc. occupy positions within the composite substrate tier, while Asahi Kasei Corporation exemplifies the high-porosity polymer specialization archetype. These entities represent the established supplier base against which newer coating integrators compete for Stellantis platform awards.
| Leading Market Players |
|---|
| Teijin Ltd |
| Asahi Kasei Corporation |
| Mitsubishi Chemical Group Corporation |
| W-SCOPE Corporation |
| SK Innovation Co. Ltd |
| Hitachi Chemical Company Ltd |
| Sumitomo Chemical Co. Ltd |
| SEMCORP Co. Ltd |
| Toray Industries Inc. |
| Others |
Pricing and Supply Chain Analysis
Alumina and boehmite precursor price indices cascade through Italian separator supply chains, compressing margins for ceramic coating specialists while amplifying pricing power for integrated substrate-coating operators serving Stellantis platform teams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Italian separator market by certification grade and thermal performance tier. CE marking under EU Battery Regulation traceability mandates commands premium positioning for ceramic-coated architectures, while uncoated polymer substrates face cost compression from depreciated extrusion infrastructure. Price differentiation hinges on coating uniformity precision and batch-level material origin documentation. Battery manufacturers exhibit highest price sensitivity due to backward integration pressure, whereas Ferrari and Stellantis luxury platforms absorb premium pricing for abuse-tolerant separator stacks.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stellantis and Ferrari integration teams, displacing traditional cell-maker procurement intermediaries. Raw material sourcing draws from Japanese polymer substrate specialists, Korean coating technology providers, and Chinese alumina precursor suppliers. Ceramic coating input dependencies rest on alumina, boehmite, and high-porosity polyolefin films. Single-source vulnerability concentrates in electrospinning equipment and nanofiber scale-up talent pools. Distribution runs through platform-level bundling contracts with 18-24 month validation cycles that freeze supplier switching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy EV battery separator market represents a late-cycle quality story as premium passenger vehicle platforms from Stellantis and Ferrari absorb thicker ceramic-coated architectures with cycle life specifications exceeding 1,500 cycles.
For Market Incumbents: Acquire electrospinning scale-up capabilities to defend against nanofiber patent acceleration from Emilia-Romagna research clusters. Secure backward integration into alumina and boehmite precursor supply chains before EU Critical Raw Materials Act sourcing constraints tighten. Pre-qualify separator suppliers with embedded supply chain audit capabilities to meet CE marking documentation burdens.
For New Entrants and Emerging Players: Platform-level procurement portals offer direct contracting channels with Stellantis integration teams, bypassing traditional cell-maker intermediaries. Target underdeveloped separator qualification programs near Modena and Bologna production sites where first-mover positioning remains available. Emphasize automated ceramic coating thickness control as the technical differentiator for nickel-rich cathode pack specifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated substrate-coating specialists commanding premium positioning in Ferrari and Stellantis luxury platforms. Long-term viability centers on patent white space in nanofiber-polymer hybrid architectures and captive supply of ceramic coating precursors. Watch nanofiber manufacturing scale-up milestones from Politecnico di Torino and University of Bologna labs as inflection indicators for technology trajectory shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Precursor Supply | Captive alumina and boehmite sourcing insulates margins from EU Critical Raw Materials Act volatility. |
| Automated Coating Thickness Control Deployment | Sub-micron uniformity enables single-source platform awards from Stellantis integration teams. |
| Nanofiber-Polymer Hybrid Patent Filing | Electrospun layer integration opens white space for next-generation solid-state cell architectures. |
| Direct OEM Contracting Channel Establishment | Platform-level bundling with Ferrari and Stellantis displaces traditional cell-maker procurement. |
| Supply Chain Audit Capability Embedding | Batch-level material origin certification satisfies EU Battery Regulation traceability mandates. |
Research Methodology
Multiple input streams — primary interviews with separator production executives, OEM platform integration teams, and ceramic coating specialists; secondary validation through EU Battery Regulation filings, Italian Ministry of Economic Development state aid disclosures, and Piedmont-Lombardy industrial cluster trade data — were reconciled through bottom-up and top-down triangulation.
Historical production volume trajectories were cross-referenced against panel input from gigafactory development stakeholders to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and regional production cluster. CAGRs were derived from fitted growth curves incorporating platform-level procurement contract announcements and nanofiber patent filing velocity from Emilia-Romagna research institutes.
The model assumes a particular technology adoption path; alternative pathways for solid-state cell architectures would alter the outlook for laminated separator demand. Forecasts reflect assumptions regarding EU Critical Raw Materials Act implementation timing and Stellantis platform rollout cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market