
 Battery Production Machine Market | 2026-2036
Battery Production Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Production Machine Market Insights
High-precision specification tiers for solid-state cell manufacturing is rotating procurement priorities across the battery production machine value chain. Lead Intelligent Equipment Co., Ltd. leverages its dominance in winding and stacking equipment for prismatic cells. Dürr Group anchors European demand through its coating and drying system specialization. Hitachi High-Tech Corporation differentiates via inspection and measurement technology leadership at sub-micron resolution thresholds.
Battery production machines encompass the integrated mechanical, electromechanical, and robotic systems used to manufacture electrochemical cells, with specifications typically requiring coating uniformity within ±1.5 micrometers, electrolyte filling precision below 0.5 grams deviation, and cleanroom compatibility at ISO Class 7 or stricter. These systems serve the industrial purpose of converting raw electrode materials, separators, and electrolytes into finished cells at throughput rates exceeding 200 parts per minute for cylindrical formats. Assembly machines command the largest installed base across lithium-ion technology lines, while robotic systems represent the fastest-expanding margin pool as OEMs automate material handling between formation and aging stages. Solid-state technology lines pull premium pricing for testing equipment due to stricter dry-room protocols and novel pressure-assisted sintering processes.
China's MIIT enforces GB standards for battery manufacturing equipment safety and energy efficiency, while the EU Green Deal and REACH frameworks constrain solvent recovery systems and material traceability across European supply chains. The US EPA and OSHA jointly govern emissions and worker exposure limits at electrode coating facilities, creating compliance-driven replacement cycles. Stakeholders must monitor how solid-state pilot-to-mass-production transitions reshape equipment qualification protocols and supplier certification timelines.
Market Dynamics
Solid-state battery pilot-to-mass-production transitions are compressing equipment qualification timelines and forcing suppliers to recalibrate dry-room protocols, coating precision thresholds, and pressure-assisted sintering capabilities simultaneously.
Growth Catalysts
- EU Green Deal decarbonization mandates:European OEMs must localize battery supply chains to comply with carbon border adjustments, pulling investment into Stuttgart and Dresden production corridors.
- China's MIIT equipment safety standards:GB certification requirements for winding and stacking systems are accelerating replacement cycles in Ningbo and Shenzhen manufacturing clusters.
- Silicon-anode chemistry migration:The shift from graphite to silicon-dominant anodes demands recalibrated calendaring and coating systems with tighter thickness control tolerances.
Market Restraints
- High-purity lithium supply concentration:Chilean and Australian spodumene refining bottlenecks transmit volatility into electrode material costs and equipment utilization planning.
- Dry-room infrastructure intensity:Solid-state lines require ISO Class 6 or stricter environments, multiplying facility capex by factors that deter mid-tier entrants.
- REACH solvent recovery obligations:European coating facilities face escalating compliance costs for NMP recovery systems that extend payback periods on new equipment investments.
Strategic Opportunities
- US Inflation Reduction Act localization incentives:Domestic content credits are pulling Korean and European equipment suppliers toward Michigan and Tennessee greenfield partnerships.
- Second-life battery disassembly automation:End-of-life cell processing creates demand for robotic sorting and diagnostic systems in emerging recycling verticals.
- Sodium-ion chemistry diversification:Hard carbon anode production lines require modified coating and drying equipment that opens parallel revenue streams for incumbent suppliers.
Industry Challenges
- Mechatronics technician scarcity:German and Japanese equipment installers face 18-month backlogs as vocational pipelines fail to match Gigafactory construction velocity.
- Multi-physics simulation integration:Coupled thermal-electrochemical-mechanical modeling for solid-state cell formation demands software competencies that outpace legacy engineering team capabilities.
- Cross-border certification synchronization:Divergent GB, CE, and UL approval timelines for high-voltage testing equipment delay revenue recognition on multinational orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Production Machine Market |
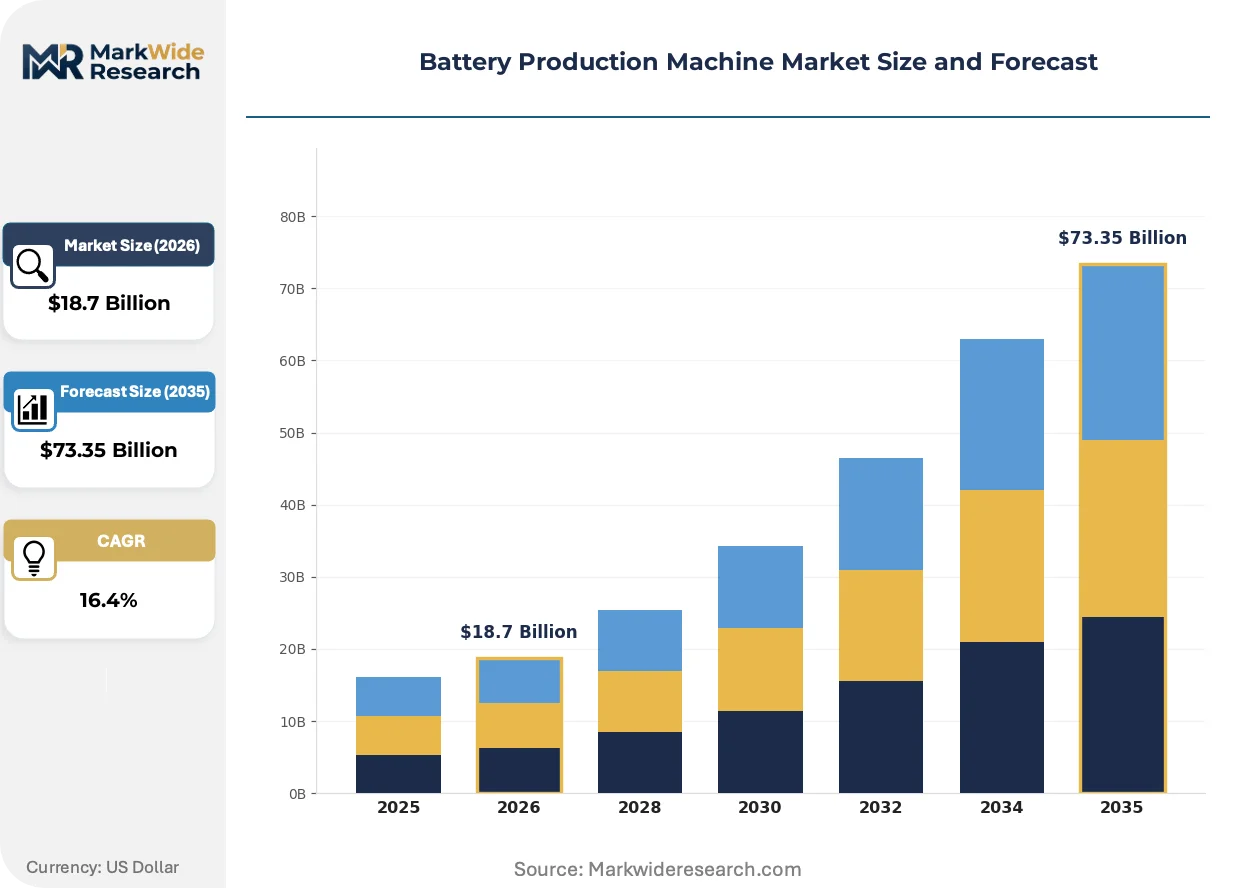
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Machines, Testing Equipment, Robotic Systems, Inspection Tools Technology: Lithium-Ion, Solid-State, Lead-Acid, Nickel-Cadmium Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Applications End User: Automotive Manufacturers, Electronics Firms, Energy Companies, OEMs |
| Companies Covered | Lead Intelligent Equipment Co., Ltd., Yinghe Technology Co., Ltd., Hitachi High-Tech Corporation, Dürr Group, ANDRITZ Schuler GmbH, Manz AG, Guangdong Lyric Robot Automation Co. Ltd., Nordson Corporation, CKD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Production Machine Market Trends and Innovations
Electrode manufacturing workflows are fragmenting into chemistry-specific process islands, with equipment architectures diverging between high-nickel ternary, lithium-iron-phosphate, and solid-state production paradigms rather than converging on universal platforms.
Laser drying technology is bifurcating electrode production economics. Nidec and Korean equipment integrators are deploying infrared-laser systems that slash drying energy intensity by half compared to conventional convection ovens. The structural consequence is compressing the total cost of ownership gap between European and Asian coating line suppliers, forcing incumbents to accelerate R&D partnerships or cede mid-market positioning.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent use are tightening coating emission thresholds across European electrode facilities. Industrial consequence includes mandatory closed-loop recovery systems that add fifteen to twenty percent to line capex. German coating specialists are responding with aqueous binder formulations that eliminate solvent recovery infrastructure entirely, though these require redesigned drying profiles.
Buyers are consolidating procurement authority at the Gigafactory program level rather than delegating to individual line managers. Tier-one OEMs now mandate equipment-as-a-service contracts bundling maintenance, spare parts, and throughput guarantees across ten-year horizons. This concentration is most visible in Chinese Ningbo and German Baden-Württemberg clusters where CATL and PowerCo negotiate master agreements covering multiple plant locations simultaneously.
Battery Production Machine Market Segmentation
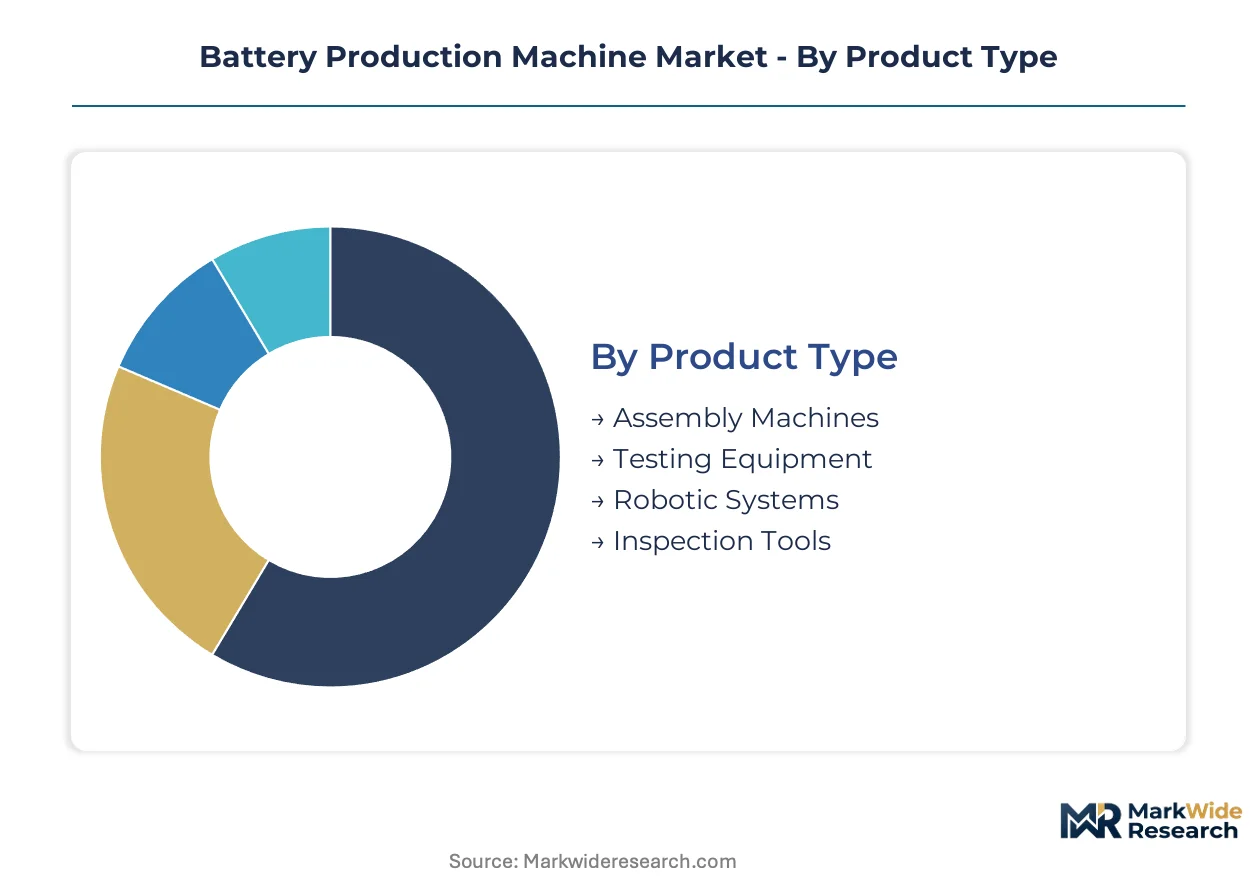
Battery production machine procurement diverges sharply across cell formats and chemistry platforms, with equipment specifications, qualification protocols, and margin structures varying by an order of magnitude between legacy lithium-ion lines and emerging solid-state pilot facilities.
Product Type:
Margin pools concentrate in systems governing cell formation precision, where throughput guarantees and dry-room compatibility command premium pricing tiers.
- Assembly Machines:Integrated mechanical platforms execute electrode stacking, tab welding, and electrolyte filling at rates exceeding 200 cylindrical cells per minute. Procurement from CATL in Ningbo and PowerCo in Baden-Württemberg concentrates demand for prismatic and pouch configurations, driven by Gigafactory localization mandates under the EU Green Deal and US IRA domestic content rules.
- Testing Equipment:High-voltage formation cabinets and electrochemical impedance spectroscopy systems verify cell performance across temperature cycles. Solid-state pilot lines in Germany and Japan pull specialized pressure-assisted sintering testers with stricter dry-room protocols at ISO Class 6 or above.
- Robotic Systems:Automated guided vehicles and articulated arms handle material transport between formation and aging stages.
- Inspection Tools:Sub-micron resolution measurement systems detect electrode coating defects and separator misalignment.
The dominant share belongs to Assembly Machines, while Robotic Systems is closing the gap fastest.
Technology:
Cost tiers stratify by chemistry maturity, with established formats amortizing R&D across volume and novel platforms absorbing heavy qualification overhead.
- Lithium-Ion:Mature electrode coating, calendaring, and winding systems dominate installed base economics. Ningbo and Shenzhen manufacturing clusters in China drive replacement cycles under MIIT GB safety standards, while European lines face REACH solvent recovery compliance costs.
- Solid-State:Pilot production demands recalibrated dry-room infrastructure, pressure-assisted sintering presses, and novel electrolyte deposition tools. German Stuttgart region and Japanese equipment integrators concentrate early procurement as cell developers scale from laboratory to mass production.
- Lead-Acid:Mature assembly lines serve industrial battery replacement markets with standardized plate stacking and acid filling equipment.
- Nickel-Cadmium:Declining chemistry retains niche aerospace and defense applications requiring specialized formation cycling.
Lithium-Ion retains the dominant share, though Solid-State is climbing the fastest as pilot lines convert to commercial scale.
Application:
Volume concentration tracks end-use electrification intensity, with automotive pulling the largest absolute equipment orders.
- Electric Vehicles:Cylindrical, prismatic, and pouch cell formats each demand dedicated winding, stacking, and formation lines. German OEMs and Chinese manufacturers anchor procurement in Stuttgart and Ningbo corridors, compelled by carbon border adjustments and supply chain security mandates.
- Consumer Electronics:Compact pouch cell production prioritizes precision coating and laser electrode cutting for smartphone and laptop battery suppliers.
- Renewable Energy Storage:Grid-scale battery systems require modified formation protocols for larger prismatic cells with extended cycle life specifications.
- Industrial Applications:Forklift, mining, and stationary backup systems sustain demand for robust lead-acid and lithium-iron-phosphate assembly lines.
Electric Vehicles commands the dominant share, while Renewable Energy Storage is gaining share fastest on utility-scale deployment.
End User:
Customer type determines procurement authority concentration, with integrated OEMs negotiating master agreements spanning multiple plant locations.
- Automotive Manufacturers:Volkswagen Group's PowerCo, CATL, and BYD consolidate equipment procurement at program level, bundling maintenance and throughput guarantees across ten-year horizons. German Baden-Württemberg and Chinese Ningbo clusters exhibit this concentration most visibly.
- Electronics Firms:Smartphone and laptop battery suppliers prioritize compact footprint lines with rapid format changeover capabilities.
- Energy Companies:Utility and independent power producers specify containerized formation systems for grid-scale storage integration.
- OEMs:Independent battery producers serving multiple downstream sectors balance flexibility against dedicated line economics.
Automotive Manufacturers hold the dominant share, with Energy Companies expanding most quickly on storage deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in battery production machinery tilt heavily toward Asian supply origins, with Chinese and Korean equipment makers capturing outbound volume while German and Japanese specialists dominate premium-tier imports into Western Gigafactory corridors.
China
Domestic Gigafactory construction by CATL and BYD absorbs the majority of winding and stacking equipment output. MIIT GB certification requirements for manufacturing safety accelerate replacement cycles across Ningbo and Shenzhen industrial clusters. The Yangtze River Delta concentration around Shanghai anchors procurement of high-precision coating and calendaring systems for prismatic cell formats.
Germany
PowerCo and Mercedes-Benz battery divisions localize supply chains to satisfy EU Green Deal carbon border adjustment mechanisms. REACH Annex XVII constraints on N-methyl-2-pyrrolidone solvent recovery multiply coating line compliance costs. The Stuttgart-Baden-Württemberg corridor concentrates demand for next-generation solid-state pilot line equipment.
United States
IRA domestic content credits pull Korean and European equipment suppliers toward Michigan and Tennessee greenfield partnerships. EPA and OSHA joint governance of electrode coating emissions creates compliance-driven replacement demand. The Southeast manufacturing belt exhibits fastest capacity absorption for cylindrical cell assembly systems.
Japan
Pilot-to-mass-production transitions for solid-state batteries compress equipment qualification timelines at Toyota and Panasonic divisions. METI industrial policy supports domestic equipment maker consolidation against Chinese price competition. The Nagoya-Tokyo industrial corridor retains specialized demand for sub-micron inspection and measurement systems.
South Korea
LG Energy Solution and Samsung SDI expand European and North American footprint through equipment export partnerships. Korean integrators deploy infrared-laser drying systems that halve energy intensity versus conventional convection ovens. The Busan-Ulsan manufacturing cluster anchors outbound equipment supply for cylindrical format lines.
Battery Production Machine Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing integrated coating-drying-formation portfolios, while mid-tier specialists survive on chemistry-specific niche dominance. The vendor base stratifies across three tiers: full-line integrators commanding Gigafactory master agreements, component specialists anchoring single-process excellence, and regional fabricators serving replacement parts markets. Competitive moves center on dry-room protocol certification races for solid-state qualification and ten-year equipment-as-a-service contract bundling to lock in aftermarket revenue streams.
Among Asian equipment fabricators, Lead Intelligent Equipment Co., Ltd. and Yinghe Technology Co., Ltd. represent the scale-driven archetype serving high-volume cylindrical and prismatic line demand. Hitachi High-Tech Corporation occupies a position within the precision-tier segment, exemplifying Japanese specialization in sub-micron measurement and inspection systems. Dürr Group anchors European coating and drying system supply, reflecting German industrial engineering consolidation around process automation.
| Leading Market Players |
|---|
| Lead Intelligent Equipment Co., Ltd. |
| Yinghe Technology Co., Ltd. |
| Hitachi High-Tech Corporation |
| Dürr Group |
| ANDRITZ Schuler GmbH |
| Manz AG |
| Guangdong Lyric Robot Automation Co. Ltd. |
| Nordson Corporation |
| CKD Corporation |
| Others |
Pricing and Supply Chain Analysis
Solid-state electrolyte materials replacing conventional liquid electrolytes are redrawing procurement maps from China's Yangtze Delta to Germany's Stuttgart corridor while compressing equipment pricing premiums for dry-room-compatible systems. This chemistry transition simultaneously elevates coating precision specifications and fragments supplier pricing power across legacy lithium-ion equipment tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around ten-year equipment-as-a-service bundles that merge maintenance, spare parts, and throughput guarantees into single negotiated rates. Pricing stratifies across ISO Class 6-certified premium tiers for solid-state lines, standard lithium-ion configurations, and economy-grade replacement equipment for lead-acid retrofit markets. Cost compression in mid-tier coating systems is intensifying because Korean integrators have halved energy intensity through infrared-laser drying technology. Automotive manufacturers exhibit lowest price sensitivity due to master agreement consolidation, while independent battery producers face acute margin pressure on standalone line purchases.
Supply Chain Analysis
Inventory buffers for high-precision coating heads and sub-micron inspection sensors now stretch eighteen months as German and Japanese fabricators struggle with mechatronics technician backlogs. Supply concentrates in China for winding and stacking systems, Germany for coating-drying integration, and Japan for measurement technology. Component sourcing draws from Chilean lithium carbonate, Australian spodumene, and Korean precision motion control hardware. Single-source vulnerability sits with European dry-room infrastructure specialists. Distribution runs through Gigafactory program-level procurement desks rather than decentralized line manager purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state pilot-to-mass-production transitions threaten incumbent lithium-ion equipment margins unless suppliers recalibrate dry-room protocols and pressure-assisted sintering capabilities simultaneously.
For Market Incumbents: Consolidate coating-drying-formation portfolios through selective acquisition of aqueous binder formulation specialists to eliminate REACH-mandated solvent recovery costs. Deepen backward integration into precision motion control hardware to offset Korean laser-drying price competition. Lock in ten-year aftermarket revenue through equipment-as-a-service contract bundling before Chinese fabricators capture European Gigafactory procurement authority. For New Entrants and Emerging Players: Anchor in sodium-ion chemistry equipment modification as hard carbon anode production lines open parallel revenue streams with lower qualification barriers than solid-state entry. Target second-life battery disassembly automation where robotic sorting and diagnostic systems face minimal incumbent concentration. Lead with aqueous coating formulations that sidestep European NMP recovery infrastructure entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating specialists possessing stranded solvent recovery technology as REACH Annex XVII tightens emission thresholds. Five-to-ten year viability hinges on successful solid-state qualification certification rather than lithium-ion volume maintenance. Watch for GB-MIIT certification acceleration in Ningbo and Shenzhen clusters as inflection signal for Chinese equipment export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motion Control | Captures Korean laser-drying cost advantages for European coating line suppliers. |
| Equipment-as-a-Service Contract Bundling | Locks ten-year aftermarket revenue streams at CATL and PowerCo Gigafactory programs. |
| Aqueous Binder Formulation Development | Eliminates REACH-mandated NMP recovery infrastructure from European coating facilities. |
| Solid-State Dry-Room Certification Race | Qualifies pressure-assisted sintering testers for Toyota and Panasonic pilot line procurement. |
| Sodium-Ion Equipment Line Modification | Opens parallel revenue streams in hard carbon anode coating and drying systems. |
Research Methodology
A standing panel of Gigafactory procurement directors, coating system plant engineers, and aftermarket service heads provided ongoing calibration against secondary validation from MIIT GB certification databases, EU Green Deal implementation trackers, and SEC equipment supplier filings. Primary interviews with OEM platform engineers and Tier 1 battery producer R&D directors combined with customs trade data and industrial cluster investment announcements. Bottom-up equipment shipment tallies triangulated against top-down Gigafactory capacity buildout projections.
Consistency checks validated volume and value outputs against IEA battery supply chain tracking, EPCA electrode equipment trade flows, and regional industrial policy disbursement records across the projection horizon. Segmentation modeling captured cell format, chemistry platform, and end-use application dimensions alongside regional regulatory cluster variations. CAGRs derived from coupled capacity expansion timelines and equipment replacement cycle analysis. Forecast inputs incorporated solid-state pilot line conversion rates and silicon-anode chemistry migration curves.
Decision-makers should treat outputs as directional under sustained IRA domestic content credit availability and stable lithium carbonate supply assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside REACH enforcement intensity and MIIT certification velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market