
 Automatic Battery Manufacturing Equipment Market | 2026-2036
Automatic Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Battery Manufacturing Equipment Market Insights
Market Context with Strategic Players
Chinese equipment builders is restructuring supply chains as domestic gigafactory orders surge. Wuxi Lead Intelligent Equipment Co., Ltd. dominates electrode coating and cell assembly systems for lithium-ion producers. Dürr AG leverages its automotive paint-line heritage to scale dry electrode coating machinery. Hitachi High-Tech Corporation anchors inspection and metrology systems for defect detection at high throughput.
Technical Definition and Structural Segments
Automatic battery manufacturing equipment encompasses electromechanical systems that execute electrode preparation, cell stacking, electrolyte filling, formation cycling, and end-of-line testing with precision tolerances below 10 micrometers. These systems enable mass production of electrochemical cells for traction, storage, and portable power applications. Assembly line configurations capture the largest capital allocation as OEMs replicate modular gigafactory layouts, while solid-state technology lines represent the fastest-growing segment due to dry-process electrode innovations. Quality control systems command premium pricing because inline X-ray and optical inspection reduce downstream warranty exposure.
Regulatory Frame and Forward-Looking Close
The EU Battery Regulation mandates digital product passports and recycled content thresholds that force equipment makers to integrate traceability modules. China's SAMR enforces GB standards for cell safety testing that dictate formation protocol design. The EPA and OSHA in the United States impose emissions and worker exposure limits on solvent-based electrode coating lines. Stakeholders must monitor which regulatory jurisdiction sets the de facto design standard for export-bound equipment.
Market Dynamics
Dry electrode coating technology is compressing capital requirements and reshaping competitive entry barriers for gigafactory builders. The shift away from solvent-based slurry processes eliminates drying ovens and reduces factory footprints by half.
Growth Catalysts
- EU Battery Regulation:Mandates for recycled content thresholds and digital product passports force OEMs to retrofit traceability modules onto existing lines, creating replacement demand for formation and inspection equipment.
- Electric vehicle OEMs:Automakers including Tesla, BYD, and Volkswagen are replicating modular gigafactory layouts across multiple continents, standardizing procurement specifications for electrode coating and cell stacking systems.
- Solid-state pilot lines:Dry-process electrode innovations for sulfide and oxide electrolyte cells require entirely new deposition and lamination machinery, opening greenfield equipment contracts.
Market Restraints
- Lithium and cobalt price volatility:Raw material cost swings compress cell producer margins, freezing expansion budgets and delaying equipment purchase orders by 6-18 months.
- Chinese equipment concentration:Wuxi Lead and先导智能 dominate electrode coating system supply, creating single-source risk for Western gigafactories subject to export control uncertainty.
- Formation protocol rigidity:China's GB standards for cell safety testing lock in specific cycling parameters, limiting equipment customization for export-bound producers.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting first-mover equipment contracts from domestic conglomerates establishing gigafactory capacity.
- Second-life battery sorting:Automated disassembly and grading lines for end-of-life EV packs represent an untapped application segment with minimal incumbent competition.
- Sodium-ion chemistry:Hard carbon anode coating and prismatic cell assembly require process adaptations that favor nimble equipment specialists over integrated giants.
Industry Challenges
- Mechatronics talent scarcity:Precision motion control engineers with sub-10-micrometer tolerance expertise command premium wages and 12-month recruitment cycles in Germany and South Korea.
- CE marking bottlenecks:EU machinery directive compliance documentation for high-voltage formation systems extends delivery timelines by 4-6 months versus Asian markets.
- Legacy MES integration:New inline X-ray inspection systems must interface with 15-year-old manufacturing execution software at incumbent cell plants, requiring costly custom middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Battery Manufacturing Equipment Market |
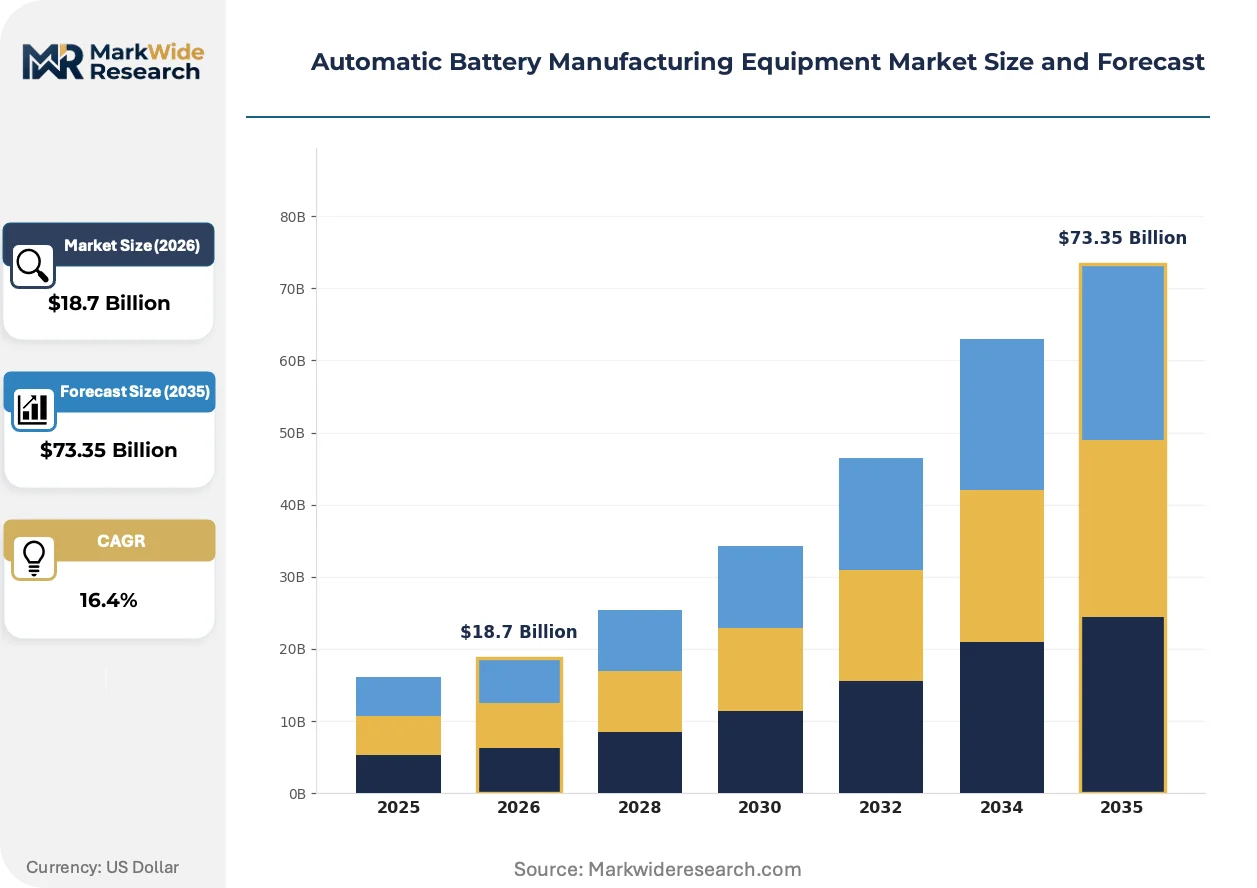
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Line, Testing Equipment, Battery Formation Unit, Quality Control Systems Technology: Lithium-ion, Lead-acid, Nickel-based, Solid State End User: OEM Manufacturers, Aftermarket Suppliers, Research Laboratories, Commercial Enterprises Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Equipment |
| Companies Covered | Hitachi High-Tech Corporation, Dürr AG, Wuxi Lead Intelligent Equipment Co., Ltd., ANDRITZ Schuler GmbH, Yinghe Technology Co., Ltd., Manz AG, Bühler AG, Nordson Corporation, IPG Photonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Battery Manufacturing Equipment Market Trends and Innovations
Equipment architecture is pivoting from centralized solvent recovery to distributed dry-process modules. This structural shift compresses factory footprints while elevating precision robotics and inline metrology to core competitive differentiators.
Dry electrode calendaring is decentralizing formation logistics by eliminating toxic solvent handling infrastructure. Battery startups in Scandinavia and the US Southwest are adopting this approach to bypass environmental permitting delays. The technology is decentralizing site selection constraints, enabling production facilities closer to raw material sources and end markets.
REACH authorization requirements for N-methyl-2-pyrrolidone (NMP) solvent are accelerating capital abandonment of wet coating lines. Equipment makers must now certify aqueous binder alternatives or dry deposition methods for EU market access. Cell producers with existing solvent permits face stranded asset risk as authorization renewals tighten.
Buyers are consolidating vendor relationships around full-line integrators capable of electrode-to-module turnkey delivery. Tier 2 equipment specialists without stacking or formation capabilities are losing access to prime contractor roles at new gigafactories. This pattern is most pronounced in Germany, where OEMs prioritize single-source accountability over component-level cost optimization.
Automatic Battery Manufacturing Equipment Market Segmentation
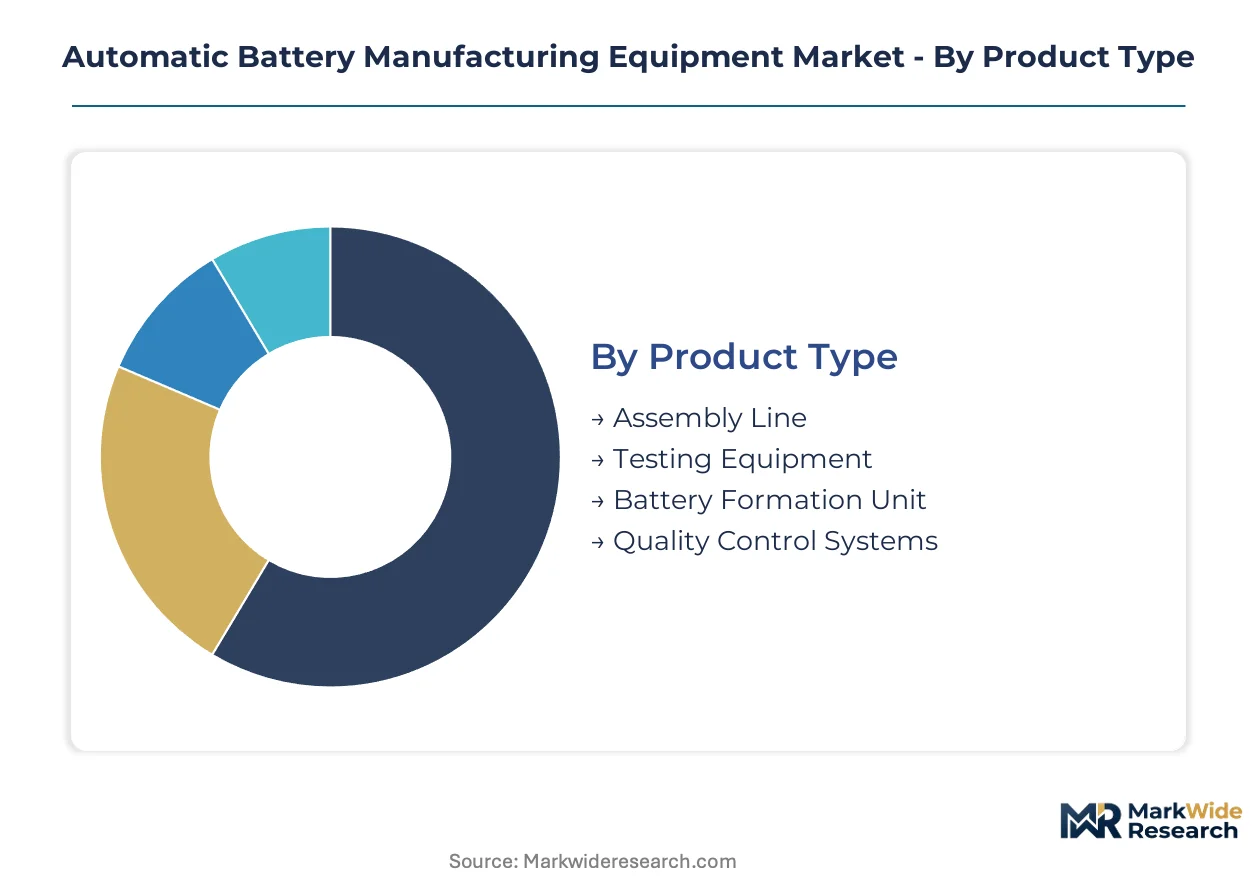
Capital allocation across equipment categories reflects divergent automation requirements and regulatory exposure. Cell producers prioritize segments that compress cycle times while satisfying traceability mandates.
Product Type:
Capital intensity peaks in integrated line configurations requiring precision motion control and inline metrology.
- Assembly Line:Modular electromechanical systems execute electrode coating, cell stacking, and electrolyte filling with sub-10-micrometer tolerances. German and South Korean gigafactories command the largest procurement volumes as OEMs replicate standardized layouts across multiple sites.
- Quality Control Systems:Inline X-ray and optical inspection modules detect electrode defects and separator misalignment before formation cycling. Premium pricing reflects downstream warranty exposure reduction for high-volume producers.
- Testing Equipment:End-of-line validation systems verify capacity, impedance, and thermal stability.
- Battery Formation Unit:High-voltage cycling cabinets execute initial charge-discharge protocols.
Most installed capacity flows through Assembly Line systems. Expansion is steepest in Quality Control Systems.
Technology:
Process chemistry dictates machinery design, with dry deposition methods reshaping equipment specifications.
- Lithium-ion:Wet slurry coating and calendaring systems dominate current procurement, though solvent handling infrastructure faces stranded asset risk from tightening REACH authorizations.
- Solid State:Dry electrode lamination and sulfide electrolyte deposition require entirely new machinery architectures. Scandinavian and US Southwest startups are adopting these systems to bypass environmental permitting delays.
- Lead-acid:Mature formation and grid casting equipment serves stationary storage and automotive starter applications.
- Nickel-based:Specialized winding and sealing systems address aerospace and defense cell formats.
Volume concentration remains in Lithium-ion. Solid State is gaining share fastest among new capacity announcements.
End User:
Procurement scale and technical sophistication diverge sharply across buyer categories.
- OEM Manufacturers:Vertically integrated automakers and dedicated cell producers demand turnkey electrode-to-module solutions with single-source accountability. Volkswagen and Tesla procurement teams standardize specifications across continental replication.
- Research Laboratories:Pilot line equipment with rapid reconfiguration capabilities supports materials science and process development. National laboratories in Germany and the United States anchor demand for flexible deposition and metrology platforms.
- Aftermarket Suppliers:Replacement formation and testing equipment serves independent cell rebuilders.
- Commercial Enterprises:Distributed energy storage integrators purchase modular assembly cells.
Contract value concentrates with OEM Manufacturers. Research Laboratories are expanding procurement most quickly.
Application:
End-use performance requirements cascade into distinct equipment specifications and throughput demands.
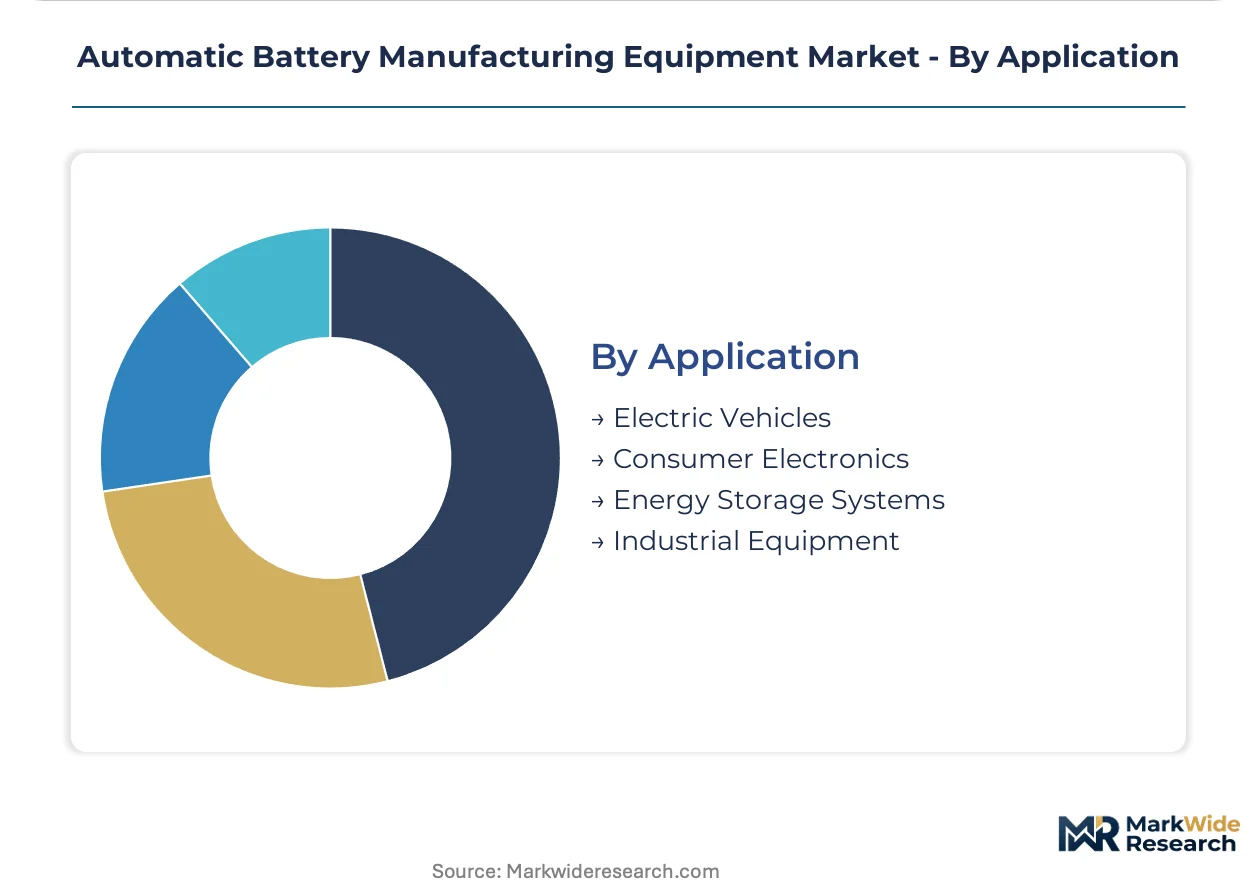
- Electric Vehicles:High-throughput stacking and laser welding systems produce prismatic and cylindrical cells for traction applications. BYD and CATL gigafactory investments in China drive the dominant share of current orders.
- Energy Storage Systems:Formation cycling equipment with extended protocol flexibility serves grid-scale battery installations. Utility procurement in Germany and the United States prioritizes systems capable of handling LFP and emerging sodium-ion chemistries.
- Consumer Electronics:Compact winding and tab welding equipment addresses pouch cell formats.
- Industrial Equipment:Ruggedized formation systems support forklift and stationary power applications.
Equipment deployment tilts toward Electric Vehicles. Energy Storage Systems show the steepest order book expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns track regulatory arbitrage opportunities as cell producers migrate toward jurisdictions with streamlined environmental permitting and favorable industrial policy. The cost-of-compliance gap between REACH-regulated Europe and Asia-Pacific manufacturing zones shapes capital allocation decisions for gigafactory builders.
Germany
Volkswagen and BMW procurement teams drive electrode coating system demand as domestic OEMs replicate modular gigafactory layouts across Saxony and Lower Saxony. The EU Battery Regulation mandates digital product passports that force equipment retrofits with integrated traceability modules. Emden and Zwickau anchor the densest concentration of cell assembly investments in Western Europe.
China
CATL and BYD gigafactory expansions in Fujian and Guangdong provinces consume the dominant share of global electrode coating capacity. SAMR enforcement of GB standards for cell safety testing locks formation protocol specifications for export-bound equipment. Wuxi and Shenzhen cluster the highest density of domestic equipment builders serving lithium-ion producers.
United States
Tesla and Rivian production targets in Nevada and Illinois stimulate procurement of high-throughput stacking and laser welding systems. The EPA imposes emissions limits on solvent-based electrode coating lines that elevate dry-process machinery preference. Michigan and South Carolina emerge as secondary clusters as automakers diversify manufacturing footprints.
South Korea
LG Energy Solution and Samsung SDI expansion programs in Gyeonggi and Chungcheong provinces sustain premium demand for precision metrology systems. MFDS alignment with international cell safety standards facilitates equipment export certification for European-bound production lines. Incheon and Daejeon concentrate domestic equipment engineering talent for sub-10-micrometer tolerance applications.
India
Reliance Industries and Ola Electric gigafactory commitments under the PLI scheme attract first-mover equipment contracts for advanced chemistry cell manufacturing. BIS implementation of cell safety standards lags global benchmarks, creating interim regulatory flexibility for process design. Gujarat and Tamil Nadu host the most advanced project pipelines among domestic conglomerates.
Automatic Battery Manufacturing Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state and sodium-ion process niches. The vendor base stratifies across three tiers: integrated line builders commanding turnkey contracts, component specialists supplying precision subsystems, and regional fabricators serving aftermarket replacement demand. Strategic archetypes include automotive heritage diversifiers, electrochemical equipment pure-plays, and laser or robotics technology transplants. Dominant competitive moves center on geographic expansion through local licensing partnerships and portfolio diversification into second-life battery processing machinery.
Among German automotive heritage diversifiers, Dürr AG and Manz AG exemplify the paint-line-to-coating-equipment transition archetype. Chinese electrochemical pure-plays Wuxi Lead Intelligent Equipment Co., Ltd. and Yinghe Technology Co., Ltd. occupy positions shaped by domestic gigafactory demand concentration. These entities represent contrasting strategic foundations: European players leverage process control expertise from adjacent automotive sectors, while Chinese counterparts scale through captive supply relationships with vertically integrated cell producers.
| Leading Market Players |
|---|
| Hitachi High-Tech Corporation |
| Dürr AG |
| Wuxi Lead Intelligent Equipment Co., Ltd. |
| ANDRITZ Schuler GmbH |
| Yinghe Technology Co., Ltd. |
| Manz AG |
| Bühler AG |
| Nordson Corporation |
| IPG Photonics Corporation |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price indices cascading from Chilean and Australian spot markets compress margin structures across electrode coating system tiers. Cell producers pass input volatility downstream, forcing equipment vendors to absorb cost spikes or sacrifice backlog conversion.
Pricing Analysis
Direct-to-OEM discounts dominate high-volume gigafactory contracts, compressing distributor margins to single-digit percentages on electrode coating systems. Three-tier pricing structure across premium, standard, and economy levels separates turnkey integrators from component specialists and regional fabricators. Pricing pressure stems from Chinese equipment builders capturing domestic orders at cost-plus terms. Tier 2 specialists without formation capabilities exhibit highest price sensitivity; integrated line builders with metrology portfolios maintain pricing power.
Supply Chain Analysis
Precision motion control engineer shortages in Germany and South Korea constrain sub-10-micrometer tolerance component output. Supply concentrates in China, South Korea, and Japan for high-voltage formation cabinets, laser welding heads, and inline X-ray sources. Raw material dependencies draw from Japanese servo motors, German precision bearings, and Chinese rare-earth magnet supply. Single-source vulnerability around Wuxi Lead electrode coating systems exposes Western gigafactories to export control disruption. Distribution runs through equipment integrators serving turnkey procurement mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-regulated Europe and Asia-Pacific manufacturing zones rewards equipment makers with dual-certification capabilities. The cost-of-compliance gap favors dry-process machinery vendors bypassing solvent permitting delays.
For Market Incumbents: Deploy backward integration into precision metrology subsystems to defend against laser technology transplants from adjacent industries. Capture stranded asset replacement demand as REACH authorization renewals force wet coating line abandonment. Lock in multi-site service contracts with Volkswagen and Tesla procurement teams replicating modular layouts.
For New Entrants and Emerging Players: Enter via sodium-ion hard carbon anode coating equipment, where process adaptations favor nimble specialists over integrated giants. Target India's PLI scheme first-mover contracts before domestic conglomerates consolidate vendor relationships. Lead with rapid formation protocol customization as BIS standards lag global benchmarks.
For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state dry deposition specialists holding sulfide electrolyte lamination IP. Five-to-ten year viability hinges on greenfield pilot line conversion rates rather than lithium-ion retrofit demand. Watch for CE marking bottleneck resolution as inflection signal for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Process Certification | REACH authorization compliance unlocks EU market access for equipment vendors. |
| Traceability Module Integration | Digital product passport mandates force retrofit demand across existing formation lines. |
| Solid-State Pilot Line Partnership | Sulfide electrolyte deposition contracts open greenfield equipment opportunities. |
| Second-Life Battery Machinery Development | Automated disassembly lines address end-of-life EV pack processing gaps. |
| Precision Robotics Capability Acquisition | Sub-10-micrometer tolerance expertise commands premium positioning in gigafactory procurement. |
Research Methodology
Coverage spans Germany, China, the United States, South Korea, and India, with primary inputs from each market cluster. The analysis combines interviews with gigafactory procurement directors, equipment engineering leads, and regulatory compliance officers alongside secondary validation through SAMR GB standard filings, EPA emissions disclosures, and EU Battery Regulation implementation texts. Trade data from customs authorities and SEC filings from listed equipment vendors support bottom-up and top-down triangulation.
Rate-of-change decomposition isolates volume and value drivers across the projection horizon. Segmentation dimensions include product type, process technology, end-user category, and regional regulatory cluster. CAGRs derive from equipment order book analysis and gigafactory capacity announcement tracking. Forecast inputs incorporate lithium price volatility indices and CE marking timeline distributions for high-voltage formation systems.
The model holds under stable regulatory enforcement timelines; deviation in REACH authorization schedules or GB standard revision cycles would shift equipment procurement patterns. Forecasts reflect assumptions about solid-state pilot line conversion rates and sodium-ion chemistry adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market