
 Strategic Bomber Market | 2026-2036
Strategic Bomber Market Size, Share, and Industry Trends Forecast 2026-2036
Strategic Bomber Market Intelligence
Aerospace engineering talent shortages is reorganizing how prime contractors allocate design resources across next-generation programs. Northrop Grumman Corporation leverages its B-21 Raider development pipeline to sustain engineering workforce depth in California and Florida. The Boeing Company anchors strategic bomber modernization through its Air Force One and bomber sustainment divisions in Missouri. BAE Systems competes for subsystem integration roles across European and Pacific supply chains.
A strategic bomber is a long-range, heavy-payload combat aircraft designed to penetrate or bypass enemy air defenses and deliver nuclear or conventional ordnance against strategic targets, typically operating at intercontinental ranges exceeding 5,000 nautical miles with gross takeoff weights above 150,000 pounds. Stealth bomber variants incorporate radar-absorbent materials, faceted airframes, and reduced infrared signatures to survive in contested airspace. Heavy bomber platforms occupy the core of nuclear deterrence budgets, while stealth technology segments capture premium margins as air defense networks densify. Avionics and navigation systems segments are accelerating as autonomous targeting and satellite-denied navigation become operational requirements.
The US Air Force's Nuclear Weapons Center, China's Central Military Commission Equipment Development Department, and Russia's Ministry of Defence shape bomber procurement through nuclear posture reviews and long-range aviation modernization directives. FAA airworthiness standards and ITAR export controls constrain technology transfer and foreign market access for subsystem suppliers. Stakeholders must monitor which nations commit to crewed versus optionally crewed long-range strike platforms, as this choice will redirect decade-long development funding and supplier specialization.
Market Dynamics
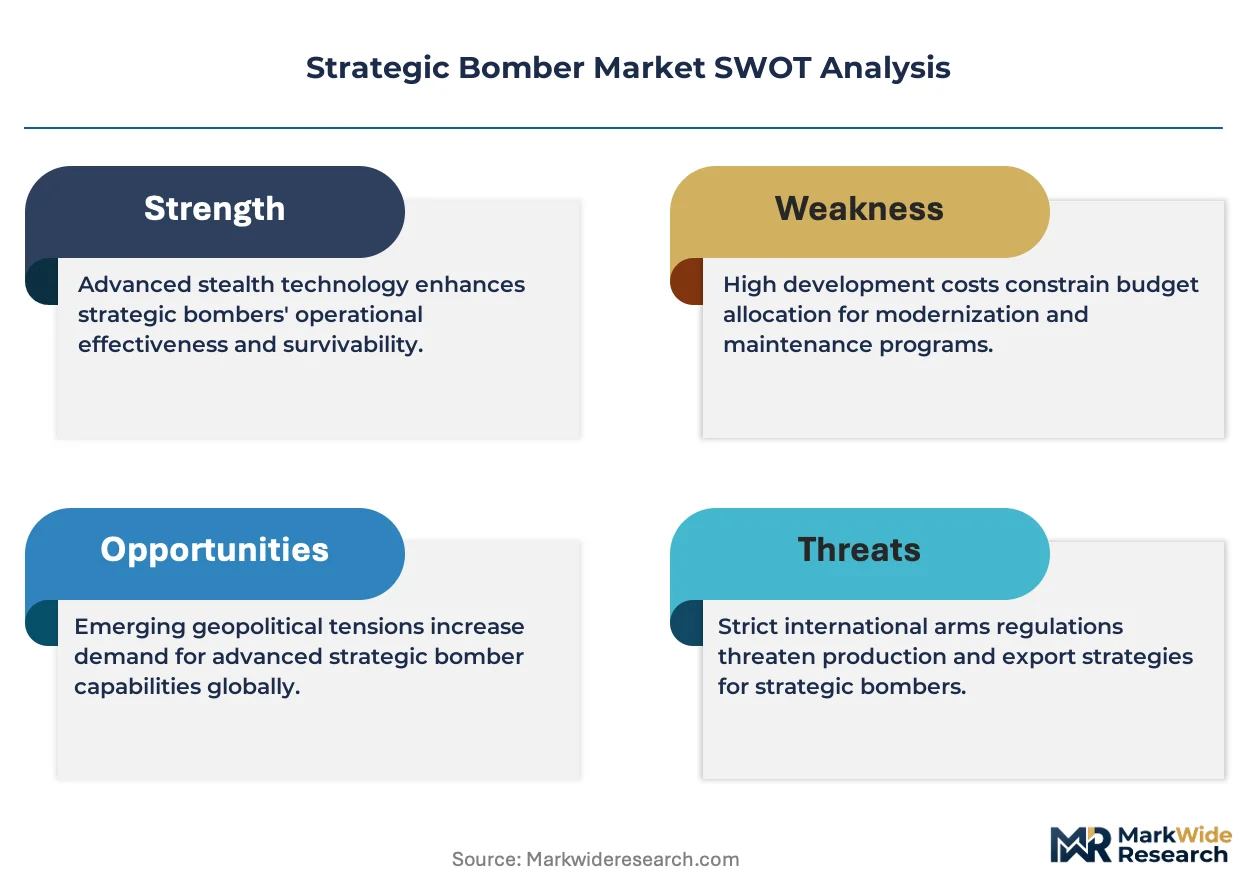
Nuclear posture reviews across NATO and Indo-Pacific alliances are redirecting defense procurement toward survivable long-range strike platforms, compressing development timelines and reshaping supplier specialization requirements.
Growth Catalysts
- Low-Observable Materials Advancement:Radar-absorbent composites and plasma-sheath technologies are expanding operational envelopes against integrated air defense networks. Air forces in the United States and China prioritize these material investments.
- NATO Nuclear Sharing Modernization:The alliance's extended deterrence framework is generating requirements for dual-capable bomber fleets compatible with modernized gravity bombs and standoff cruise missiles.
- Indo-Pacific Theater Expansion:China's Central Military Commission Equipment Development Department is accelerating H-20 platform development, triggering competitive procurement responses from regional air forces.
Market Restraints
- Titanium and Superalloy Supply Concentration:Russian and Chinese dominance in sponge titanium and nickel-based superalloy production creates input vulnerability for Western airframe manufacturers.
- ITAR Export Control Friction:United States International Traffic in Arms Regulations constrain subsystem supplier access to allied co-development programs, fragmenting supply chain efficiency.
- Crewed Platform Cost Trajectory:Unit production costs exceeding defense budget growth rates are forcing fleet size reductions despite capability requirements.
Strategic Opportunities
- Australian Long-Range Strike Investment:The Royal Australian Air Force's acquisition pathway for nuclear-capable bombers under AUKUS creates demand for training, sustainment, and subsystem integration services.
- Autonomous Wingman Convergence:Manned-unmanned teaming architectures pairing strategic bombers with attritable loyal wingman platforms are opening new avionics and software segments.
- United States B-21 Production Ramp:The Air Force Rapid Capabilities Office's multi-year procurement commitment is stabilizing demand visibility for stealth coating and electronic warfare suppliers.
Industry Challenges
- Aerospace Structural Engineering Talent Scarcity:Specialized expertise in low-observable airframe design is concentrating at prime contractors, constraining second-tier supplier technical depth.
- Airworthiness Certification Timeline Compression:FAA military derivative certification and military airworthiness board reviews are extending first-flight-to-initial-operational-capability intervals beyond program baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strategic Bomber Market |
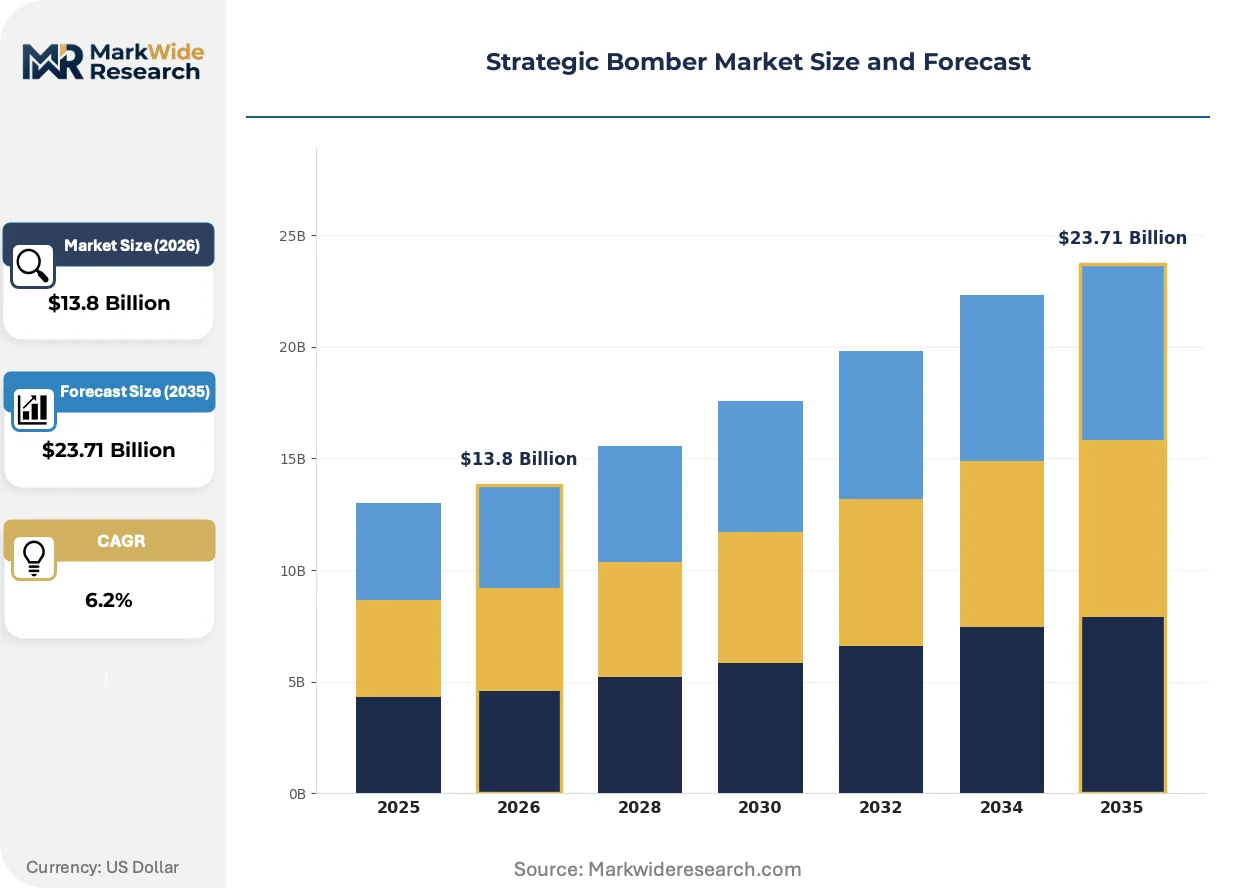
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $23.71 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Heavy Bomber, Medium Bomber, Stealth Bomber, Tactical Bomber Technology: Avionics, Weaponry Systems, Navigation Systems, Stealth Technology End User: Military Forces, Defense Contractors, Government Agencies, Aerospace Manufacturers Deployment: Airborne, Naval, Land-Based, Multi-Role Platforms |
| Companies Covered | Northrop Grumman Corporation, The Boeing Company, General Dynamics Corporation, BAE Systems, Collins Aerospace, Dassault Aviation SA, Russian Aircraft Corporation, Tupolev, Panavia Aircraft GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strategic Bomber Market Strategic Shifts & Innovations
Stealth technology integration, propulsion system evolution, and autonomous systems architecture are converging to redefine platform design specifications and operational concepts for next-generation strategic bombers.
Digital engineering environments are compressing prototype development cycles. The United States Air Force's eSeries acquisition pathway mandates model-based systems engineering from concept through sustainment. This methodology is miniaturizing traditional design-review-gate processes and enabling parallel hardware-software integration.
REACH regulation amendments in the European Union are restricting hexavalent chromium and cadmium coatings historically used in corrosion protection for aluminum airframes. Military aerospace suppliers are reformulating surface treatments and submitting alternative compliance proposals to the European Chemicals Agency, with German and French subsystem manufacturers most affected by substitution timelines.
Defense procurement offices are consolidating sustainment contracts under performance-based logistics frameworks. United States Air Force Materiel Command is shifting from transactional spare parts purchasing to availability-guaranteed service agreements, compressing supplier margins while extending contract durations and transferring inventory risk to prime contractors.
Strategic Bomber Market Segmentation
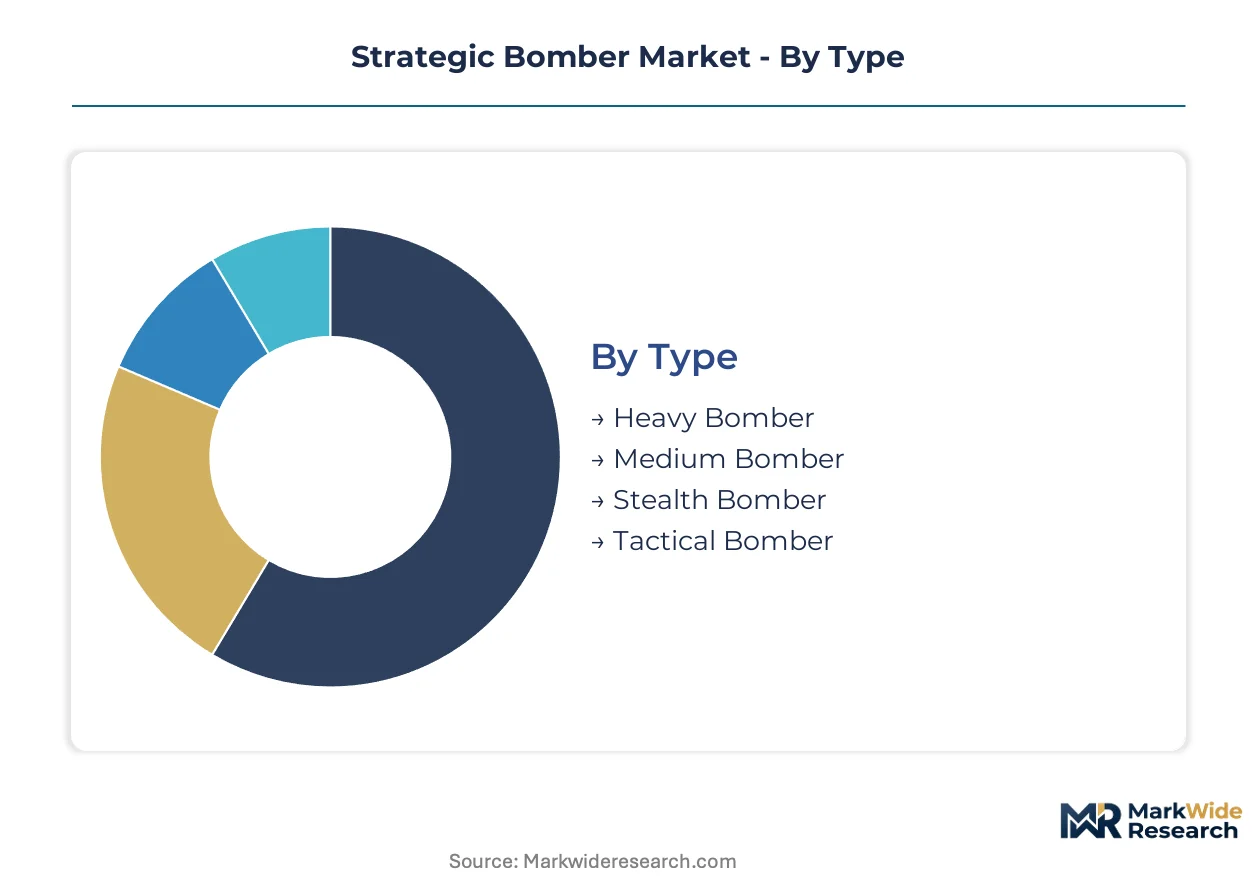
Strategic bomber procurement divides along capability tiers and operational requirements, with each segment facing distinct substitution pressures from standoff missiles, unmanned platforms, and space-based alternatives. Understanding these segment boundaries clarifies where defense budgets concentrate and where technology investments reshape competitive positioning.
Type:
Stealth bomber platforms face the most acute substitution pressure from hypersonic standoff weapons and autonomous wingman concepts, while heavy bombers benefit from nuclear triad leg requirements that resist rapid platform displacement.
- Heavy Bomber:Intercontinental-range platforms with gross takeoff weights exceeding 300,000 pounds and nuclear gravity bomb carriage. Demand concentrates in United States Air Force Global Strike Command and China's People's Liberation Army Air Force as both services modernize aging airframes under nuclear posture directives.
- Stealth Bomber:Radar-cross-section-optimized designs incorporating faceted geometry and radar-absorbent materials for contested airspace penetration. Procurement in the United States through Northrop Grumman's B-21 program and China's accelerating H-20 development absorbs premium development funding as integrated air defense networks densify across the Indo-Pacific.
- Medium Bomber:Regional-range platforms optimized for theater strike missions with reduced logistics footprints.
- Tactical Bomber:Shorter-range aircraft designed for frontline support and close air support integration.
Heavy bomber retains volume leadership; stealth bomber holds the steepest expansion curve.
Technology:
Technology segments stratify by margin structure, with stealth coatings and electronic warfare subsystems commanding premium pricing against commoditized navigation hardware.
- Stealth Technology:Radar-absorbent materials, plasma-sheath systems, and infrared signature management. United States and Chinese air forces prioritize these investments as S-400 and HQ-9 surface-to-air missile networks proliferate across Eastern Europe and the South China Sea.
- Avionics:Mission computers, electronic warfare suites, and sensor fusion architectures enabling satellite-denied navigation. Demand clusters in next-generation bomber programs requiring open systems architectures for rapid software refresh cycles.
- Weaponry Systems:Rotary launchers, bomb rack interfaces, and nuclear certification hardware.
- Navigation Systems:Inertial measurement units, celestial navigation backups, and GPS-denied positioning.
Avionics captures the largest addressable base; stealth technology is expanding most quickly.
End User:
End user concentration reflects procurement authority fragmentation, with military operators holding design specification power while contractors absorb development risk.
- Military Forces:Uniformed service branches with operational requirements definition and fleet management authority. United States Air Force Nuclear Weapons Center and China's Central Military Commission Equipment Development Department direct platform specifications through nuclear posture reviews and long-range aviation modernization directives.
- Defense Contractors:Prime integrators and subsystem suppliers executing design-build contracts under cost-plus and fixed-price arrangements. Northrop Grumman and Boeing sustain engineering workforces through multi-year bomber development pipelines in California, Florida, and Missouri.
- Government Agencies:Research laboratories and test organizations validating airworthiness and nuclear certification.
- Aerospace Manufacturers:Component fabricators and material suppliers feeding tiered supply chains.
Military forces retain volume leadership; defense contractors hold the steepest expansion curve.
Deployment:
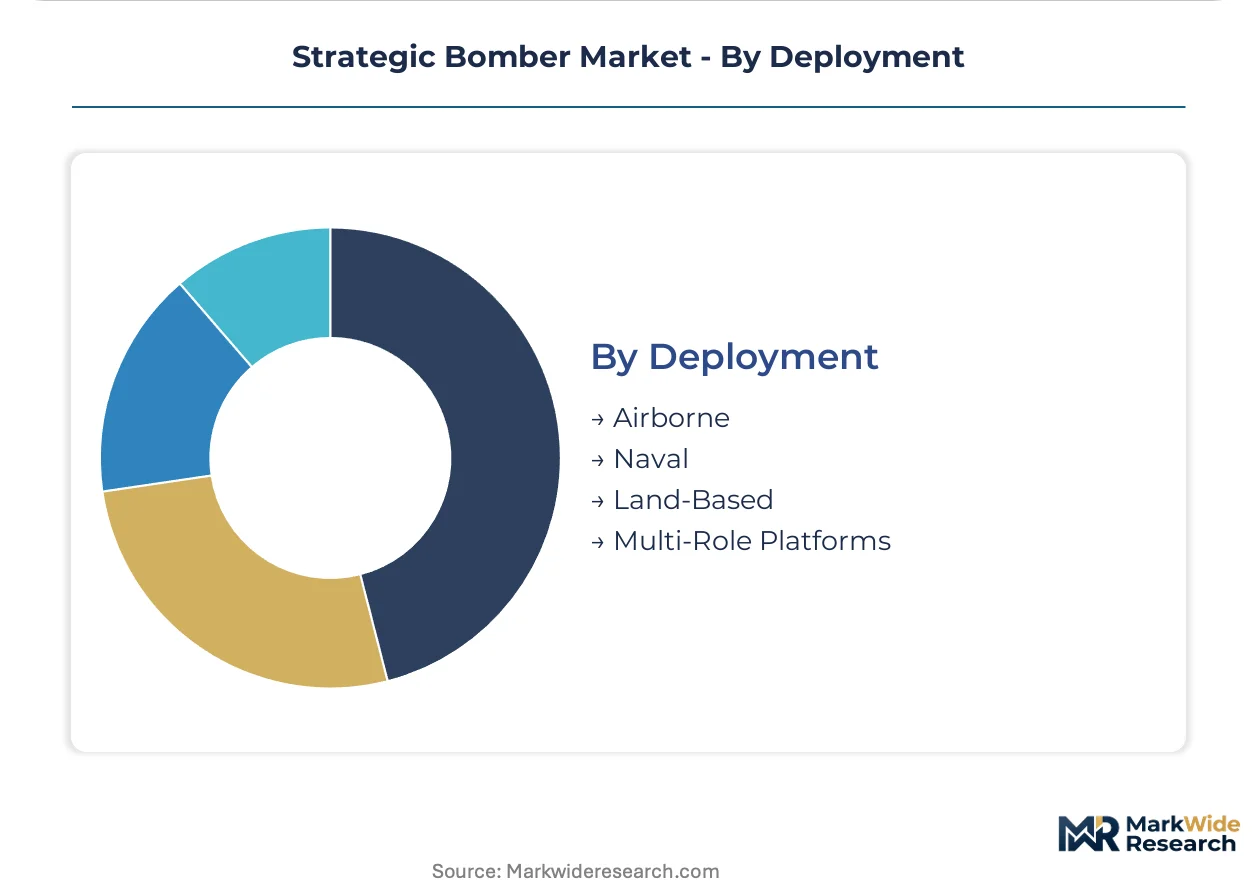
Deployment mode selection determines platform versatility and basing vulnerability tradeoffs, with multi-role architectures gaining preference as force structure constraints tighten.
- Airborne:Pure bomber platforms optimized for long-range strike with dedicated aerial refueling support. United States Air Force Global Strike Command and Russian Long-Range Aviation maintain this deployment mode for nuclear alert postures requiring rapid generation and dispersal.
- Multi-Role Platforms:Configurable airframes supporting strike, intelligence-surveillance-reconnaissance, and electronic attack missions. Royal Australian Air Force under AUKUS frameworks and United Kingdom Royal Air Force prioritize this flexibility to maximize limited fleet utilization rates.
- Naval:Carrier-compatible or maritime-strike optimized bomber derivatives.
- Land-Based:Fixed-site operations from continental airfields with hardened shelter infrastructure.
Airborne retains volume leadership; multi-role platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States prioritizes stealth penetration platforms for contested airspace, while China accelerates heavy bomber production for nuclear triad completion, and Russia sustains long-range aviation fleets through modernization rather than new development.
United States
The US Air Force Nuclear Weapons Center drives demand through the B-21 Raider program and B-52 re-engining. ITAR export controls constrain technology transfer to allied co-development programs. Engineering talent concentrates in Palmdale, California, where Northrop Grumman sustains low-observable design workforce depth through multi-year procurement commitments.
China
The Central Military Commission Equipment Development Department accelerates H-20 stealth bomber development to complete the nuclear triad air leg. GB standards and MIIT directives shape domestic supplier qualification requirements. Xian's aviation industrial cluster hosts flight test infrastructure and heavy bomber final assembly lines for the People's Liberation Army Air Force.
Russia
The Ministry of Defence prioritizes Tu-160M2 modernization and PAK DA development through state armament programs. Sanctions on titanium and superalloy exports have redirected supply chain sourcing toward domestic producers. Kazan Aviation Plant maintains heavy bomber production capacity despite Western technology access restrictions.
United Kingdom
The Royal Air Force participates in NATO nuclear sharing through dual-capable aircraft requirements under extended deterrence frameworks. Ministry of Defence procurement directives emphasize multi-role flexibility for limited fleet utilization. BAE Systems in Lancashire and Greater Manchester anchors subsystem integration for European supply chains.
Australia
The Royal Australian Air Force's long-range strike investment under AUKUS frameworks creates demand for nuclear-capable bomber training and sustainment infrastructure. Department of Defence acquisition pathways prioritize interoperability with US systems. RAAF Base Amberley in Queensland serves as the primary concentration for strike aircraft operations and logistics.
Strategic Bomber Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the strategic bomber market. Prime contractors absorb full-platform development risk under cost-plus arrangements, while subsystem suppliers compete for avionics, propulsion, and stealth coating contracts. Two archetypes dominate: vertically integrated airframe integrators and technology-specialized component houses. Competitive moves concentrate on securing multi-year procurement commitments and capturing sustainment contracts under performance-based logistics frameworks.
Within the integrated prime tier, Northrop Grumman Corporation and The Boeing Company exemplify the full-platform development archetype, anchoring engineering workforce concentration in California and Missouri respectively. BAE Systems occupies a position bridging European and Pacific supply chains as a subsystem integration specialist.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| The Boeing Company |
| General Dynamics Corporation |
| BAE Systems |
| Collins Aerospace |
| Dassault Aviation SA |
| Russian Aircraft Corporation |
| Tupolev |
| Panavia Aircraft GmbH |
| Others |
Cost & Logistics Intelligence
Radar-absorbent composite substitution for legacy metallic airframe structures simultaneously redistributes manufacturing gravity toward United States and Chinese industrial clusters and compresses unit economics through reduced titanium sponge dependency. This materials transition concentrates pricing power with coating technology specialists while eroding margins for conventional structural fabricators locked into superalloy supply chains.
Pricing Analysis
Long-term cost-plus development contracts dominate prime contractor arrangements, with multi-year procurement commitments stabilizing demand visibility for subsystem suppliers. Price differentiation rests on ITAR certification tier and low-observable engineering depth, with stealth coating specialists commanding premium margins against commoditized avionics hardware. Pricing pressure stems from performance-based logistics frameworks transferring inventory risk to primes. Defense contractors exhibit lowest price sensitivity due to sole-source dependencies, while second-tier component suppliers face acute cost compression.
Supply Chain Analysis
Extended lead times for radar-absorbent materials and nickel-based superalloys constrain production scheduling across North American and European assembly lines. Geographic supply concentration centers on Russia and China for sponge titanium, with United States and Japanese producers anchoring alternative sourcing for critical alloys. Raw material dependencies include carbon fiber composites, rare earth elements for electronic warfare systems, and specialized coatings feedstock. Single-source vulnerability in plasma-sheath technology creates procurement risk. Distribution runs through prime contractor tiered supplier networks with FAA military derivative certification gating market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stealth technology maturation and autonomous wingman convergence constitute a dual inflection reshaping procurement economics and supplier specialization requirements across NATO and Indo-Pacific defense frameworks.
For Market Incumbents: Compound engineering workforce depth in low-observable design through captive training pipelines in California and Florida engineering clusters. Deepen backward integration into radar-absorbent material production to defend margin position against emerging coating specialists. Prioritize multi-role platform architectures to capture Royal Australian Air Force and Royal Air Force procurement shifting away from pure bomber configurations.
For New Entrants and Emerging Players: Lead with avionics and sensor fusion subsystems where open systems architectures reduce certification barriers against entrenched prime contractors. Target Australian long-range strike infrastructure under AUKUS frameworks as the most penetrable geography. Pursue performance-based logistics sustainment contracts as the primary go-to-market angle, transferring operational risk while securing decade-long revenue streams.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aerospace component houses holding FAA military derivative certification and established prime contractor relationships. Long-term viability hinges on nuclear posture review durability and Indo-Pacific theater expansion commitments. Watch for B-21 production rate announcements as the critical signal indicating demand visibility stabilization for stealth coating and electronic warfare suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Procurement Commitment | Stabilizes demand visibility for Northrop Grumman's B-21 supplier base across California and Missouri. |
| Backward Integration into Coatings | Captures margin pool from radar-absorbent material specialists serving contested airspace penetration requirements. |
| Autonomous Wingman Development | Opens avionics and software segments through manned-unmanned teaming architectures with strategic bombers. |
| Performance-Based Logistics Contract | Transfers inventory risk to prime contractors while extending contract duration with United States Air Force Materiel Command. |
| AUKUS Interoperability Certification | Unlocks Royal Australian Air Force training and sustainment infrastructure for nuclear-capable bomber systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of United States Air Force budget justification documents, Nuclear Weapons Center procurement directives, and Congressional Research Service assessments. Primary interviews engaged program managers at Air Force Global Strike Command, nuclear certification engineers at the Air Force Nuclear Weapons Center, and subsystem procurement leads at prime contractor engineering divisions. Secondary validation drew from Department of Defense Selected Acquisition Reports, FAA military derivative certification filings, and trade data on titanium sponge and superalloy imports. Bottom-up platform production forecasts triangulated against top-down defense budget allocation analysis.
Segmentation dimensions modeled include bomber type tier, stealth technology penetration level, end-user procurement authority, and deployment mode configuration across the analysis window. CAGRs derived from production rate assumptions tied to nuclear posture review implementation timelines and long-range aviation modernization directives. Industry-specific forecast inputs incorporated ITAR export control friction coefficients and REACH regulation amendment compliance timelines for hexavalent chromium substitution.
The analysis sits within stated boundaries; outcomes outside sustained United States Congressional defense appropriation levels or escalated Indo-Pacific theater procurement commitments would require recalibration. Forecasts reflect documented assumptions regarding B-21 production ramp velocity and H-20 development progression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Online in-Flight Shopping Market
Aircraft
Aerospace Winglet System Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Amphibious Aircraft Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Turboprop Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Aircraft Sequencing System Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Aircraft Elevator Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Europe Business Jet Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Light Sport Aircraft (LSA) Market