
 Electronic Warfare Market | 2026-2036
Electronic Warfare Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Warfare Market Intelligence
The fragmentation of procurement beyond traditional defense forces to include specialized intelligence and homeland security agencies is repositioning the competitive landscape. L3Harris Technologies Inc. leverages its deep expertise in signal intelligence to serve these new buyers. BAE Systems Plc sustains its market position through extensive platform integration capabilities across air and naval domains. Thales Group competes on the strength of its advanced sensor and cyber electronic attack technologies in Europe.
Electronic warfare encompasses military action involving the use of electromagnetic energy to control the electromagnetic spectrum or attack an adversary. Systems are designed to operate across specific frequency bands, from VHF to Ka-band, to achieve objectives like jamming, deception, or intelligence gathering. Within product types, jamming equipment and advanced radar systems constitute mature, high-value segments. The technology segment shows the most dynamic evolution, with cyber electronic attack and cognitive RF spectrum analysis capabilities representing the next frontier of development.
Market access and product specifications are heavily influenced by national defense procurement standards, such as those set by the US Department of Defense, and interoperability mandates like NATO STANAGs. Stringent export control regimes, including the US International Traffic in Arms Regulations (ITAR), govern the international sale and transfer of these sensitive technologies. Navigating these complex regulatory and interoperability requirements remains a critical decision point for all system manufacturers and integrators.
Market Dynamics
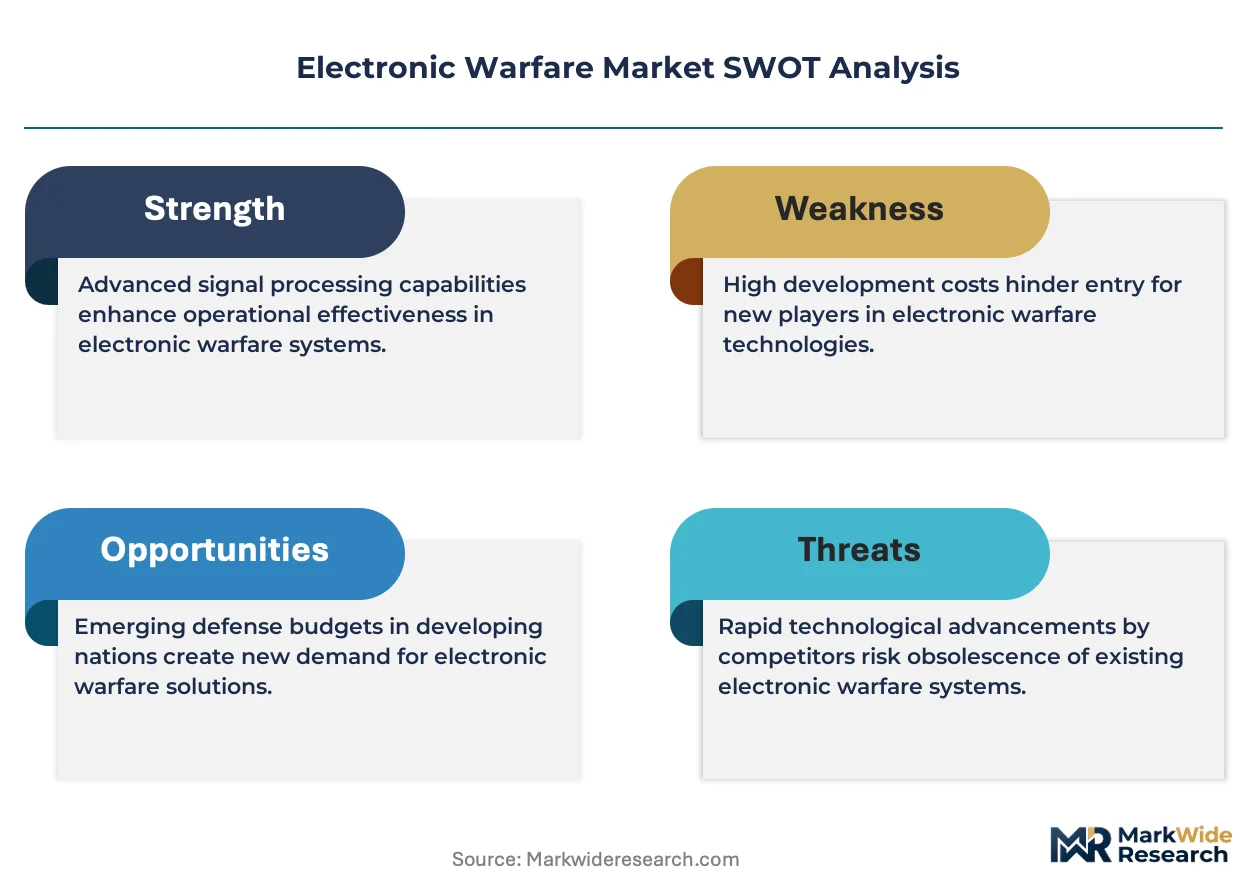
The central dynamic shaping the electronic warfare market is the escalating competition between the rapid pace of digital and cognitive technology development and the inherently slow, risk-averse processes of national defense procurement and certification, creating a persistent capability gap.
Growth Catalysts
- Modernization Mandates:Heightened geopolitical tensions are compelling NATO members and allies in the Asia-Pacific to accelerate modernization programs, specifically targeting the replacement of legacy electronic warfare suites with systems capable of countering near-peer adversary capabilities.
- Spectrum Dominance Doctrine:The formal adoption of electromagnetic spectrum superiority as a core warfighting tenet by armed forces, including the US Department of Defense, directly fuels investment in advanced jamming, deception, and signals intelligence technologies.
- Expansion to New Domains:The proliferation of electronic threats into the space and cyber domains is creating entirely new requirements for integrated, multi-domain electronic warfare systems beyond traditional air, sea, and land applications.
Market Restraints
- Export Control Regimes:Stringent regulations like the US International Traffic in Arms Regulations (ITAR) create significant friction for international sales, joint ventures, and technology transfers, limiting market access for manufacturers and procurement options for non-allied nations.
- Long Development Cycles:The extensive time required for the design, testing, and validation of mission-critical electronic warfare systems creates a significant lag between threat identification and the deployment of effective countermeasures, allowing adversaries to adapt.
- High System Costs:The immense research, development, and production costs associated with sophisticated radar and jamming systems place them out of reach for smaller nations and can constrain the procurement volumes of even major military powers.
Strategic Opportunities
- Cognitive EW Systems:The integration of artificial intelligence and machine learning into RF systems presents a major opportunity to develop cognitive electronic warfare capabilities that can autonomously adapt to novel and uncatalogued threats in real-time.
- Commercial Sector Protection:Applying electronic warfare techniques to defend critical civilian infrastructure, such as power grids and communication networks, from electromagnetic pulse (EMP) attacks or GPS spoofing opens a new, non-military market vertical.
- Modular Open Architectures:The push for non-proprietary, modular system designs allows specialized technology firms to supply best-of-breed components, creating an opportunity to compete for sub-contracts within larger platform integration programs.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of cleared personnel with deep expertise in radio frequency engineering, digital signal processing, and embedded software development constrains the ability of both government agencies and defense contractors to scale programs.
- Legacy System Integration:The operational challenge of integrating modern, digital electronic warfare pods and internal suites with older, analog-based avionics and communication systems on existing military platforms is a major source of cost overruns and program delays.
- Threat Signature Proliferation:The rapid proliferation of advanced and agile radar and communication systems globally makes it exceptionally difficult for threat library databases, which are critical for system effectiveness, to remain current and comprehensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Warfare Market |
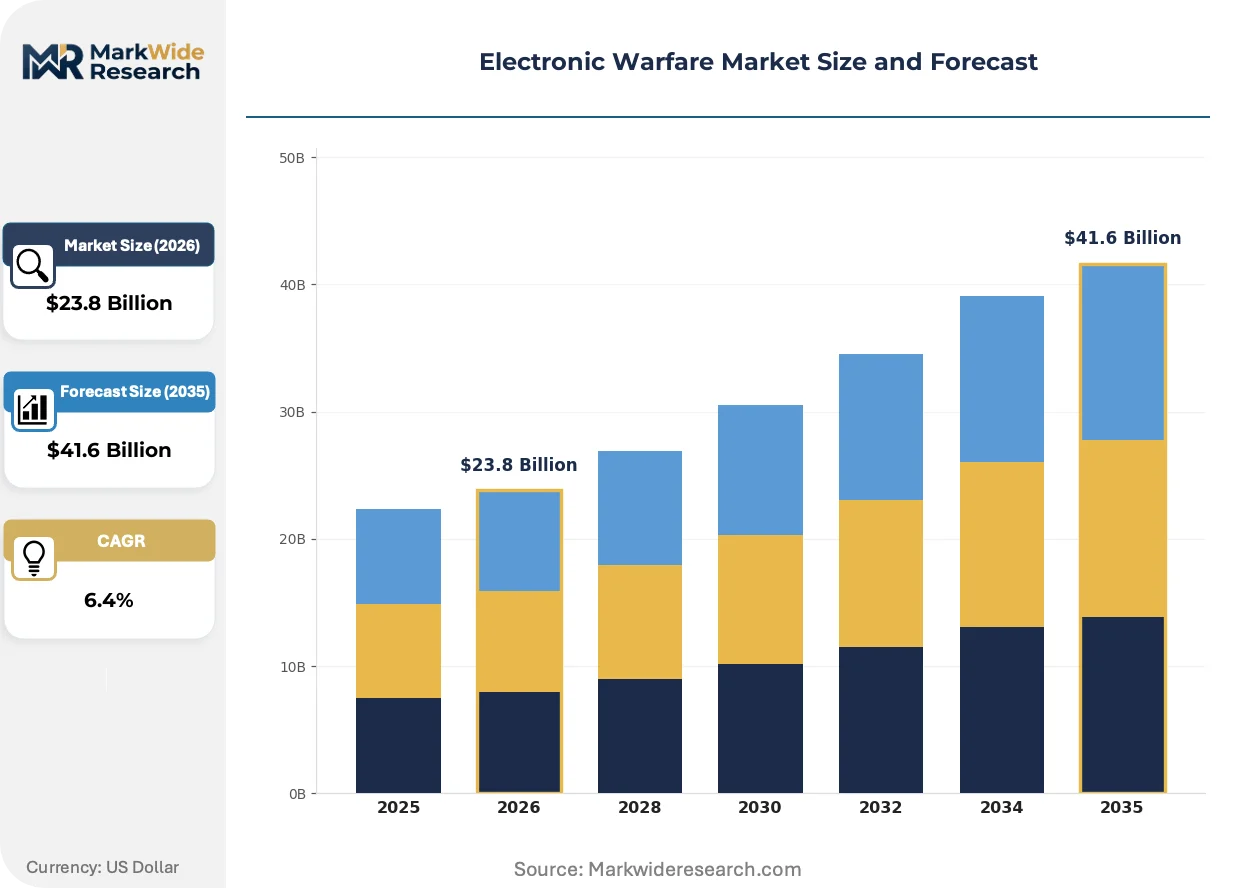
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jamming Equipment, Radar Systems, Electronic Countermeasures, Signal Intelligence, Decoys, Direction Finders Technology: RF Spectrum Analysis, Cyber Electronic Attack, Communications Intelligence, Electronic Protection, Electronic Support Measures, Sensors Application: Threat Detection, Target Tracking, Communication Disruption, Navigation Impairment, Surveillance Support, Electronic Deception End User: Defense Forces, Border Security, Naval Operations, Air Defense, Intelligence Agencies, Homeland Security |
| Companies Covered | RTX Corp., General Dynamics Corp., L3Harris Technologies Inc., Thales Group, Elbit Systems Ltd., Lockheed Martin Corp., BAE Systems Plc, Saab AB, Northrop Grumman Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Warfare Market Strategic Shifts & Innovations
The defining technological shift in electronic warfare is the transition from static, hardware-defined systems to software-defined, open architectures. This evolution enables rapid capability upgrades via software updates, decoupling the pace of innovation from lengthy hardware replacement cycles and fundamentally altering system lifecycle management.
Cognitive RF spectrum analysis technology utilizes machine learning algorithms to autonomously identify and classify signals within highly congested electromagnetic environments. Specialized military intelligence units are the primary adopters, seeking to dramatically shorten the response time to new and adaptive adversary threats. This software-driven capability is converging with traditional hardware-based signal intelligence platforms, enabling in-field reprogramming to counter novel threats without requiring a physical system overhaul.
Interoperability mandates, particularly NATO Standardization Agreements (STANAGs), are a powerful regulatory force shaping system design. These policies compel manufacturers to build systems with open architectures that can seamlessly exchange data and coordinate actions with allied assets. The air and naval platform segments are most affected, as STANAG compliance is now a non-negotiable entry requirement for participating in major multinational procurement programs and joint exercises.
A fundamental shift in acquisition strategy sees defense agencies increasingly mandating Modular Open Systems Approaches (MOSA) for new programs. This model disrupts the legacy vendor-lock of proprietary, monolithic systems, creating a more competitive ecosystem where specialized third-party suppliers can provide software and hardware modules. This change is most visible within the United States defense market, impacting platform upgrades across all services.
Electronic Warfare Market Segmentation
Understanding the electronic warfare market's segmentation reveals the diverse capabilities and operational requirements driving system development. This granular view clarifies how different product types, technologies, and end-user demands shape investment priorities. It highlights critical areas for innovation and strategic resource allocation.
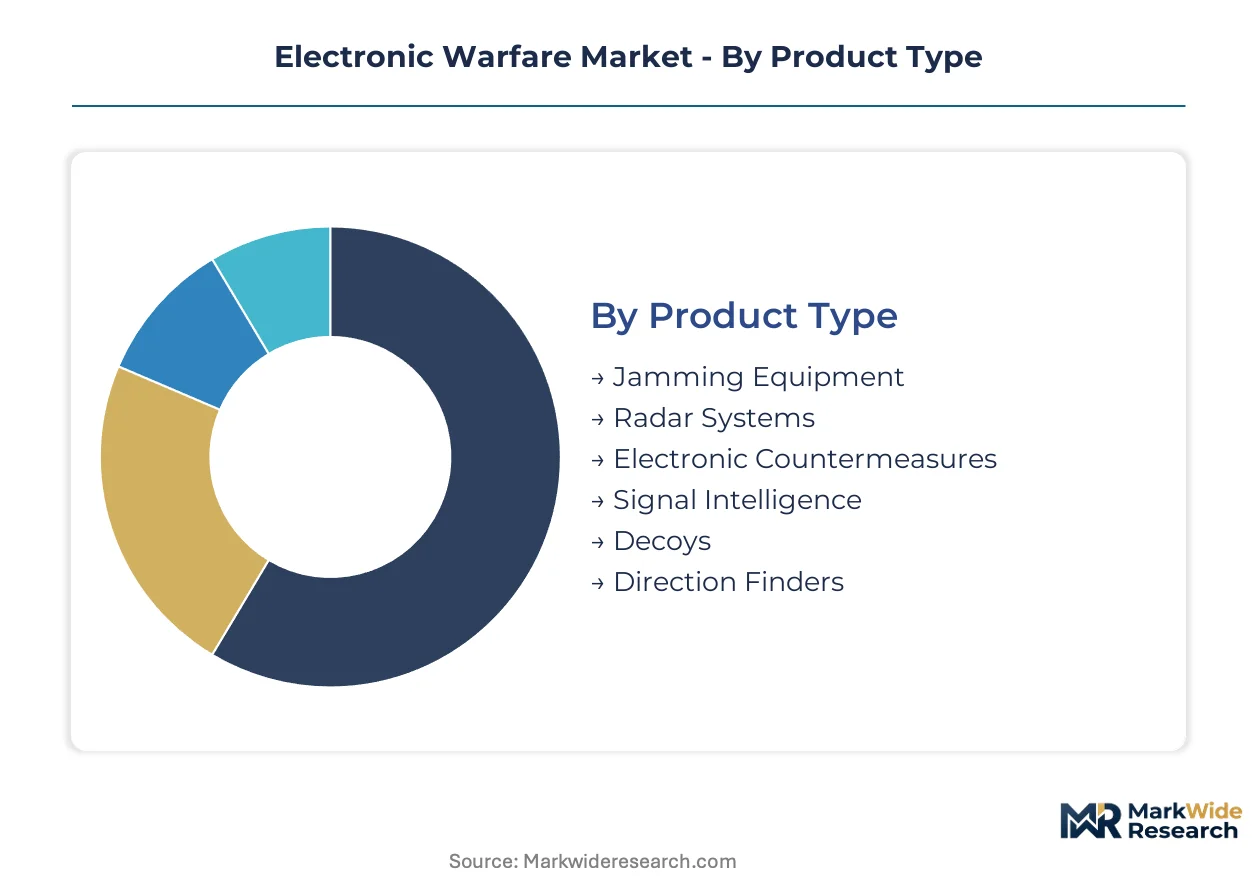
Product Type:
The product type segmentation highlights the volume-driven demand for established systems versus the premium pricing commanded by advanced, specialized equipment.
- Jamming Equipment:Jamming equipment actively emits electromagnetic energy to disrupt or deny adversary radar, communication, and navigation systems. Demand from NATO members is intensifying for advanced jamming solutions, driven by modernization mandates to counter sophisticated near-peer threats.
- Radar Systems:Advanced radar systems detect and track targets by emitting radio waves and analyzing their reflections, providing critical situational awareness. Procurement within the United States defense industrial base heavily emphasizes next-generation radar capabilities for air and naval platforms.
- Electronic Countermeasures:Electronic countermeasures deploy defensive measures to protect platforms from hostile electromagnetic threats, often involving chaff and flares.
- Signal Intelligence:Signal intelligence systems passively intercept and analyze adversary electromagnetic emissions to gather critical intelligence.
- Decoys:Decoys emit false signals to lure enemy sensors and weapons away from high-value military assets.
- Direction Finders:Direction finders locate the source of electromagnetic emissions, aiding in threat localization and intelligence gathering.
Mature deployment sits with Jamming Equipment. Newer deployment is concentrated in Signal Intelligence.
Technology:
The technology segmentation reveals the varying levels of innovation and strategic investment across foundational and cutting-edge capabilities.
- RF Spectrum Analysis:RF spectrum analysis uses advanced algorithms to monitor, identify, and classify electromagnetic signals across a wide frequency range. Specialized military intelligence units in the United States are primary adopters, seeking to dramatically shorten response times to adaptive adversary threats.
- Cyber Electronic Attack:Cyber electronic attack capabilities integrate cyber warfare techniques with electronic warfare to disrupt or degrade adversary systems through their electromagnetic interfaces. Thales Group leverages its expertise in cyber electronic attack technologies to compete effectively within the European market.
- Communications Intelligence:Communications intelligence focuses on intercepting and analyzing adversary communication signals for tactical and strategic insights.
- Electronic Protection:Electronic protection measures safeguard friendly forces and systems from hostile electronic attacks and interference.
- Electronic Support Measures:Electronic support measures passively search, intercept, and identify electromagnetic emissions to build situational awareness.
- Sensors:Advanced sensors are crucial components for detecting, characterizing, and localizing electromagnetic activity across various platforms.
Cognitive RF spectrum analysis technology represents the fastest-growing trajectory, driven by AI integration.
Application:
The application segment illustrates the diverse operational objectives that electronic warfare systems are designed to achieve across military domains.
- Threat Detection:Threat detection applications identify and classify hostile electromagnetic emissions from radars, communications, and weapon systems. Defense forces globally demand advanced threat detection systems, a primary catalyst for market expansion, particularly in Asia-Pacific.
- Communication Disruption:Communication disruption applications actively jam or interfere with adversary radio and data links, denying command and control. Armed forces adopting spectrum dominance doctrine heavily invest in communication disruption capabilities to achieve warfighting superiority.
- Target Tracking:Target tracking applications use electronic warfare systems to monitor the movement of identified enemy assets.
- Navigation Impairment:Navigation impairment techniques disrupt GPS and other satellite navigation signals, disorienting adversary forces.
- Surveillance Support:Surveillance support applications enhance intelligence gathering by passively monitoring electromagnetic activity in operational areas.
- Electronic Deception:Electronic deception involves transmitting misleading signals to confuse or misdirect adversary sensors and decision-makers.
Applications in threat detection remain critical for immediate operational safety. Electronic deception is gaining importance in strategic warfighting doctrines.
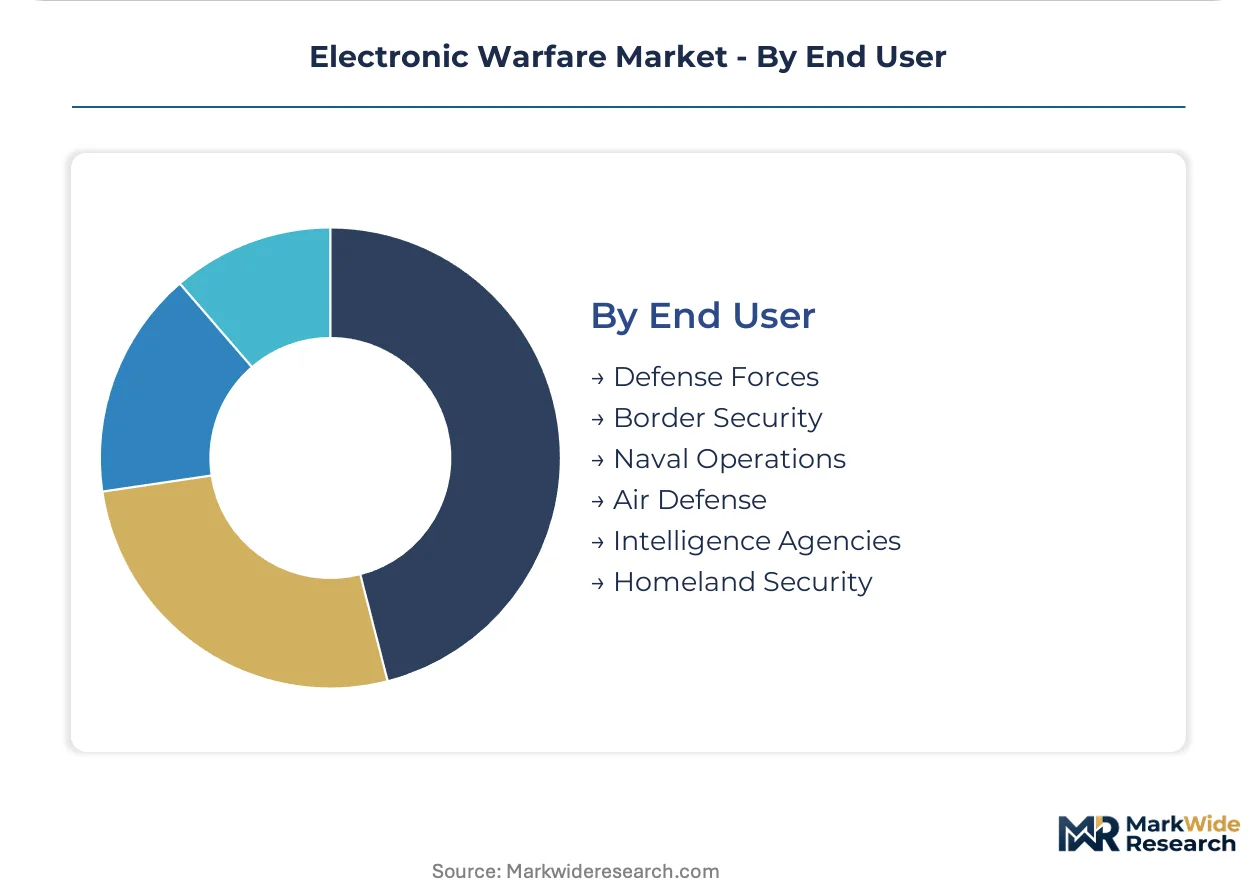
End User:
The end-user segmentation highlights distinct procurement patterns and specific operational needs across various government agencies and military branches.
- Defense Forces:Defense forces encompass traditional military branches, including army, navy, and air force, utilizing electronic warfare for combat and protection. Modernization mandates from NATO members and allies in the Asia-Pacific compel significant investment in advanced electronic warfare suites for these users.
- Intelligence Agencies:Intelligence agencies employ electronic warfare capabilities primarily for signals intelligence gathering and strategic information advantage. Specialized intelligence and homeland security agencies are increasingly fragmenting procurement beyond traditional defense forces, altering the competitive landscape.
- Border Security:Border security agencies deploy electronic warfare for surveillance, unauthorized crossing detection, and communication monitoring.
- Naval Operations:Naval operations utilize electronic warfare for ship self-protection, anti-ship missile defense, and maritime domain awareness.
- Air Defense:Air defense systems integrate electronic warfare to counter airborne threats, including radar jamming and missile deception.
- Homeland Security:Homeland security agencies use electronic warfare for critical infrastructure protection and counter-terrorism applications.
Procurement for defense forces currently dominates budget allocation. Intelligence agencies demonstrate a strategic focus on advanced signal exploitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration within the United States defense industrial base significantly shapes the global electronic warfare market. This procurement focus drives innovation and production for advanced threat detection systems. Geopolitical tensions also compel NATO members and Asia-Pacific allies to accelerate modernization programs.
United States
Modernization mandates from the US Department of Defense drive substantial investment in next-generation electronic warfare systems. The US International Traffic in Arms Regulations (ITAR) governs technology transfers, influencing market access for manufacturers. Silicon Valley and defense industrial hubs in Virginia and California foster advanced research and development for cognitive RF spectrum analysis.
United Kingdom
Heightened geopolitical tensions compel the UK Ministry of Defence to prioritize replacement of legacy electronic warfare suites. NATO STANAGs mandate interoperability, influencing system design for multinational operations. London and the aerospace clusters around Bristol and Farnborough are centers for advanced sensor and platform integration capabilities.
France
The French Ministry of Armed Forces emphasizes advanced sensor and cyber electronic attack technologies for European defense. European Union regulations, including export controls, influence the international sale of sensitive systems. Toulouse and the Île-de-France region serve as key hubs for aerospace and defense technology development.
Israel
Continuous regional security challenges fuel demand for sophisticated electronic countermeasures and signal intelligence systems in Israel. The Israeli Ministry of Defense supports indigenous development through various procurement programs. Tel Aviv and Haifa host a vibrant ecosystem of defense technology companies specializing in advanced EW solutions.
Germany
Germany's commitment to NATO collective defense drives investment in advanced jamming and deception technologies. The German Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support (BAAINBw) oversees procurement standards. The Munich region and northern Germany are significant for radar system development and integration into naval platforms.
Electronic Warfare Market Key Industry Players
United States producers anchor one tier of the electronic warfare market, while European specialists hold significant positions in advanced sensor and cyber electronic attack technologies. The market structure is tiered, with large, integrated defense contractors providing extensive platform integration capabilities. Specialized firms focus on niche areas like signal intelligence and cognitive RF spectrum analysis. Strategic partnerships and technology licensing agreements represent common competitive moves, alongside portfolio diversification to address new domains.
Among integrated defense contractors, L3Harris Technologies Inc. and BAE Systems Plc exemplify firms with deep expertise across various electronic warfare segments. L3Harris Technologies Inc. leverages its signal intelligence capabilities to serve diverse government agencies. BAE Systems Plc sustains its market position through extensive platform integration capabilities across air and naval domains. Thales Group, a European technology firm, competes on the strength of its advanced sensor and cyber electronic attack technologies, particularly within the European market.
| Leading Market Players |
|---|
| RTX Corp. |
| General Dynamics Corp. |
| L3Harris Technologies Inc. |
| Thales Group |
| Elbit Systems Ltd.. |
| Lockheed Martin Corp. |
| BAE Systems Plc |
| Saab AB |
| Northrop Grumman Corp. |
| Others |
Cost & Logistics Intelligence
National defense procurement standards and interoperability mandates like NATO STANAGs gate both qualified supply and premium-tier pricing access within the electronic warfare market. These stringent requirements necessitate significant investment in compliance and advanced capabilities.
Pricing Analysis
Volume-driven demand for established jamming equipment and radar systems often faces intense budget scrutiny, while cutting-edge cognitive RF spectrum analysis commands premium pricing for its strategic value. Contract-based long-term offtake agreements dominate for mature systems, while advanced technologies increasingly adopt value-based models. Price differentiation stems from specialized performance specifications and critical regulatory compliance, particularly with NATO STANAGs. Pricing power remains strong for highly specialized, compliant systems, yet immense research and development costs place systems out of reach for smaller nations. Major military powers also face constrained procurement volumes due to high system costs.
Supply Chain Analysis
Logistics and freight costs are significantly impacted by stringent export control regimes, such as the US International Traffic in Arms Regulations (ITAR), adding complexity and expense to international transfers of sensitive electronic warfare components. Geographic supply concentration heavily centers on the United States defense industrial base, with European specialists in the United Kingdom, France, and Germany also contributing. The market relies on specialized semiconductors and advanced sensor components. Regulatory restrictions from export control regimes represent a critical structural risk. Downstream distribution runs primarily through direct sales to national defense agencies and prime contractors, often involving complex sub-contracting for platform integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic warfare market currently navigates a technology-transition phase, with software-defined, open architectures rapidly displacing static, hardware-defined legacy systems. This shift fundamentally alters system lifecycle management and upgrade pathways.
For Market Incumbents:
Cement leadership by aggressively investing in next-generation cognitive electronic warfare R&D to counter the rapid pace of digital and cognitive technology development. Leverage existing extensive platform integration capabilities to embed advanced software-defined solutions across new and legacy systems. Pursue strategic partnerships with specialized software firms to mitigate the persistent talent scarcity in areas like digital signal processing.
For New Entrants and Emerging Players:
Specialized intelligence units represent an underserved buyer archetype seeking niche, high-performance solutions for rapid threat response. Target the cognitive RF spectrum analysis and cyber electronic attack segments, which offer significant white-space opportunities. A compelling go-to-market angle involves supplying best-of-breed software and hardware modules through modular open architectures, bypassing traditional prime contractor lock-in.
For Investors and Strategic Acquirers:
The formal adoption of electromagnetic spectrum superiority as a core warfighting tenet is the leading indicator that signals robust long-term viability for the electronic warfare market. Target specialized firms with deep expertise in AI/ML for RF systems or advanced cyber electronic attack capabilities. Watch closely for increasing mandates for Modular Open Systems Approaches (MOSA) by major defense agencies as a key inflection point for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Platform Integration Capabilities | This consolidates market share for incumbents by offering seamless interoperability across diverse military domains. |
| Invest in AI/ML for RF Systems | This accelerates the development of cognitive EW systems capable of real-time adaptation to novel threats. |
| Adopt Modular Open Systems Approaches | This reduces vendor lock-in and fosters a more competitive ecosystem for specialized component suppliers. |
| Form International Joint Ventures | This mitigates export control regime friction and expands market access for advanced technologies. |
| Develop Cyber Electronic Attack Capabilities | This addresses the proliferation of electronic threats into the cyber domain, creating new defense requirements. |
Research Approach
US Department of Defense procurement reports, NATO STANAG documentation, and national defense budgets formed the secondary backbone, supplemented by extensive primary interviews. This included discussions with defense contractors' R&D leads, military procurement officers, intelligence agency analysts, and EW system integrators, ensuring comprehensive data triangulation. Both bottom-up and top-down approaches were utilized to validate market size and segment forecasts.
Our analytical framework employed a bottom-up estimation for market volumes, cross-referenced with top-down validation against overall defense spending across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional geopolitical tensions. Compound Annual Growth Rates (CAGRs) were derived from historical data, expert projections, and anticipated technology adoption rates. Key forecast inputs included evolving defense spending trends and the dynamic threat landscape evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts, export control policy changes, and unexpected technological breakthroughs. Forecasts reflect assumptions documented through rigorous primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market