
 High-End Inertial Systems Market | 2026-2036
High-End Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Inertial Systems Market Foresight
The performance gap between premium inertial systems and commodity-grade alternatives is expanding in concrete terms. Honeywell International Inc. leverages its long-standing dominance in ring laser gyroscope manufacturing for strategic defense contracts. Safran Group anchors European aerospace supply chains through specialized fiber optic navigation systems for commercial aviation.
High-end inertial systems integrate precision gyroscopes, accelerometers, and advanced sensors to measure angular velocity and linear acceleration with minimal drift, typically achieving bias stability below 0.01 degrees per hour for navigation-grade applications. These systems serve critical functions in autonomous vehicle guidance, spacecraft attitude control, and submarine inertial navigation where GPS denial resilience is mandatory. Fiber optic technology leads in defense applications due to its immunity to electromagnetic interference and absence of moving parts, while micro-electromechanical systems compete aggressively in automotive OEM channels where cost thresholds dominate procurement criteria. Quantum sensing represents the fastest-growing technology segment as research institutions validate atomic interferometry for gravitational mapping and next-generation inertial measurement units.
The U.S. Department of Defense mandates MIL-STD-1553 and MIL-STD-1760 compliance for embedded inertial systems in tactical aircraft, while the EU Green Deal's sustainable aviation requirements push aerospace companies toward lighter, lower-power sensor architectures. Stakeholders must monitor how export control revisions under the Wassenaar Arrangement reshape cross-border technology transfer for quantum-enhanced navigation platforms.
Market Dynamics
Quantum sensing breakthroughs are fragmenting established technology hierarchies in high-end inertial systems, redirecting R&D budgets from fiber optic and ring laser platforms toward atomic interferometry architectures that promise order-of-magnitude precision gains.
Growth Catalysts
- NATO Modernization Timelines:Defense procurement acceleration in the United States, Germany, and Japan is expanding volume commitments for navigation-grade systems in tactical aircraft and maritime platforms.
- EU Green Deal Aviation Mandates:Sustainable aviation requirements are pushing aerospace manufacturers toward lighter, lower-power sensor architectures that reduce fuel consumption in commercial fleets.
- Quantum Sensing R&D Concentration:Research institutions in Switzerland and Singapore are validating atomic interferometry for gravitational mapping, creating pull-through demand for next-generation inertial measurement units.
Market Restraints
- Specialized Component Scarcity:Precision-grade optical fiber and rare-earth doping materials concentrate among Japanese and German suppliers, exposing buyers to single-source vulnerability.
- Export Control Friction:Wassenaar Arrangement revisions on quantum-enhanced navigation platforms are complicating cross-border technology transfer for dual-use systems.
- MEMS Substitution Pressure:Automotive OEM channels are accepting commodity-grade micro-electromechanical systems for non-safety-critical applications, compressing addressable market for premium tiers.
Strategic Opportunities
- Underpenetrated Space Applications:Satellite constellation operators in Bengaluru and Toulouse corridors are sourcing radiation-hardened inertial units for attitude control in low-earth orbit deployments.
- Autonomous Maritime Navigation:Submarine and unmanned underwater vehicle programs are mandating GPS-denied inertial navigation, opening specialized procurement channels outside commercial aviation.
- Technology Convergence:Integration of quantum sensing with photonic integrated circuits is enabling chip-scale atomic inertial sensors that reduce size, weight, and power constraints.
Industry Challenges
- Atomic Physics Talent Scarcity:Quantum sensing development requires specialized expertise in laser cooling and atomic state manipulation that concentrates among Swiss and Singaporean research institutions.
- MIL-STD Certification Timelines:U.S. Department of Defense compliance with MIL-STD-1553 and MIL-STD-1760 extends qualification cycles for embedded tactical aircraft systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Inertial Systems Market |
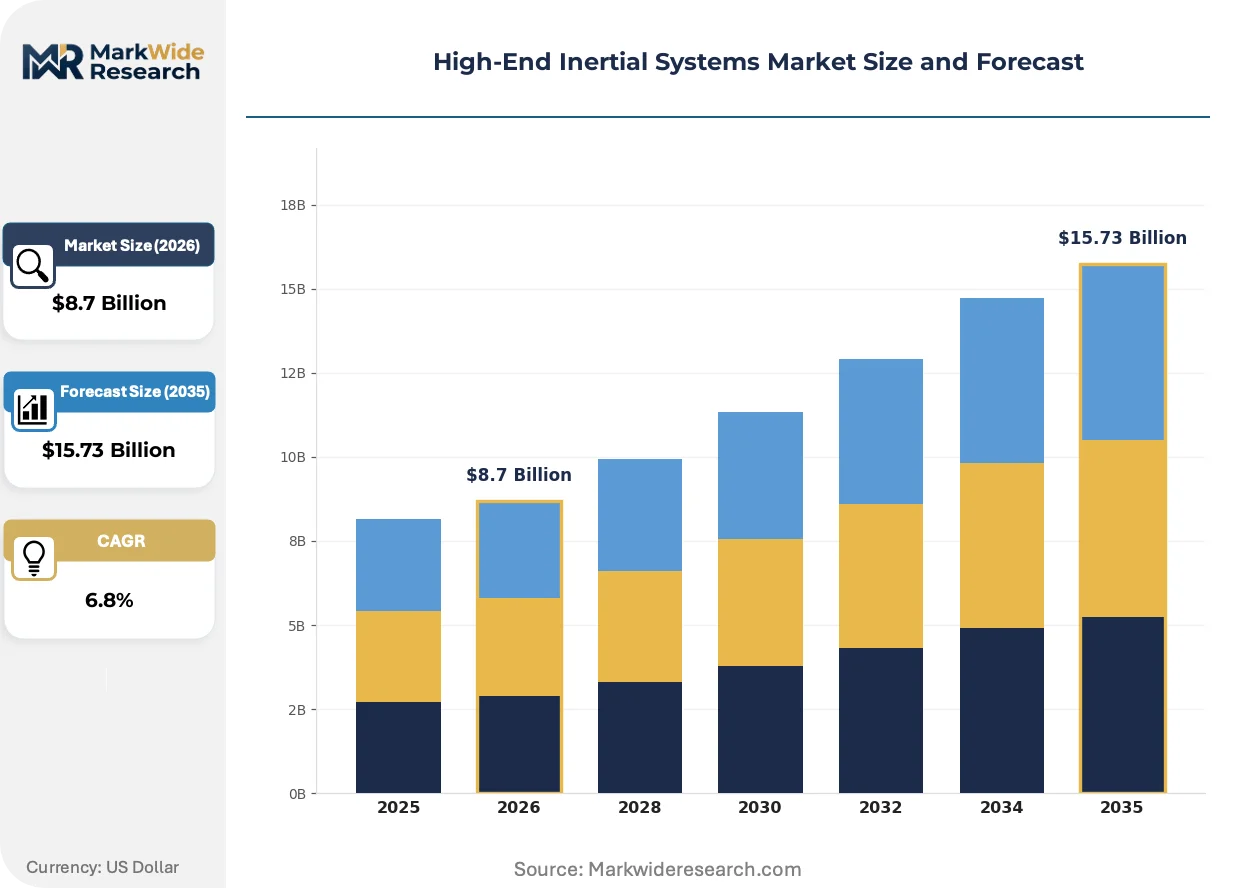
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, MEMS Sensors, Ring Laser Gyroscopes Technology: Fiber Optic, Micro-electromechanical Systems, Quantum, Optical Application: Aerospace, Marine Navigation, Defense Systems, Robotics End User: Automotive OEMs, Military Agencies, Aerospace Companies, Research Institutions |
| Companies Covered | Thales Group, Bosch Sensortec GmbH, Honeywell International Inc., Collins Aerospace, General Electric Company, Northrop Grumman Corp., Analog Devices Inc., Gladiator Technologies Inc., Safran Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Inertial Systems Market Shifts & Advancements
Photonic integration is compressing the traditional trade-off between precision and form factor, enabling new deployment architectures that were previously constrained by mechanical complexity and thermal sensitivity.
Photonic integrated circuits for inertial sensing are unifying laser sources, modulators, and detectors on single substrates. Defense contractors in the United States and Germany are piloting these platforms for tactical-grade applications. The technology is unifying previously separate optical subassemblies into monolithic architectures that reduce alignment sensitivity and manufacturing cost.
REACH and RoHS substance restrictions in Europe are constraining traditional manufacturing processes for ring laser gyroscopes that rely on mercury-containing cathodes and certain rare-earth coatings. Aerospace suppliers are reformulating gas discharge chemistries and electrode materials to maintain performance while achieving compliance. Commercial aviation manufacturers in Toulouse and Hamburg are prioritizing compliant suppliers in procurement specifications.
Platform-as-a-service contracting is displacing traditional capital purchase models for high-end inertial systems in satellite operations. Operators in Bengaluru and Seattle are accessing navigation-grade performance through leasing arrangements that bundle hardware refresh cycles and calibration services. Space launch providers are the most visible adopters, trading upfront capital expenditure for operational flexibility and guaranteed performance thresholds.
High-End Inertial Systems Market Segmentation
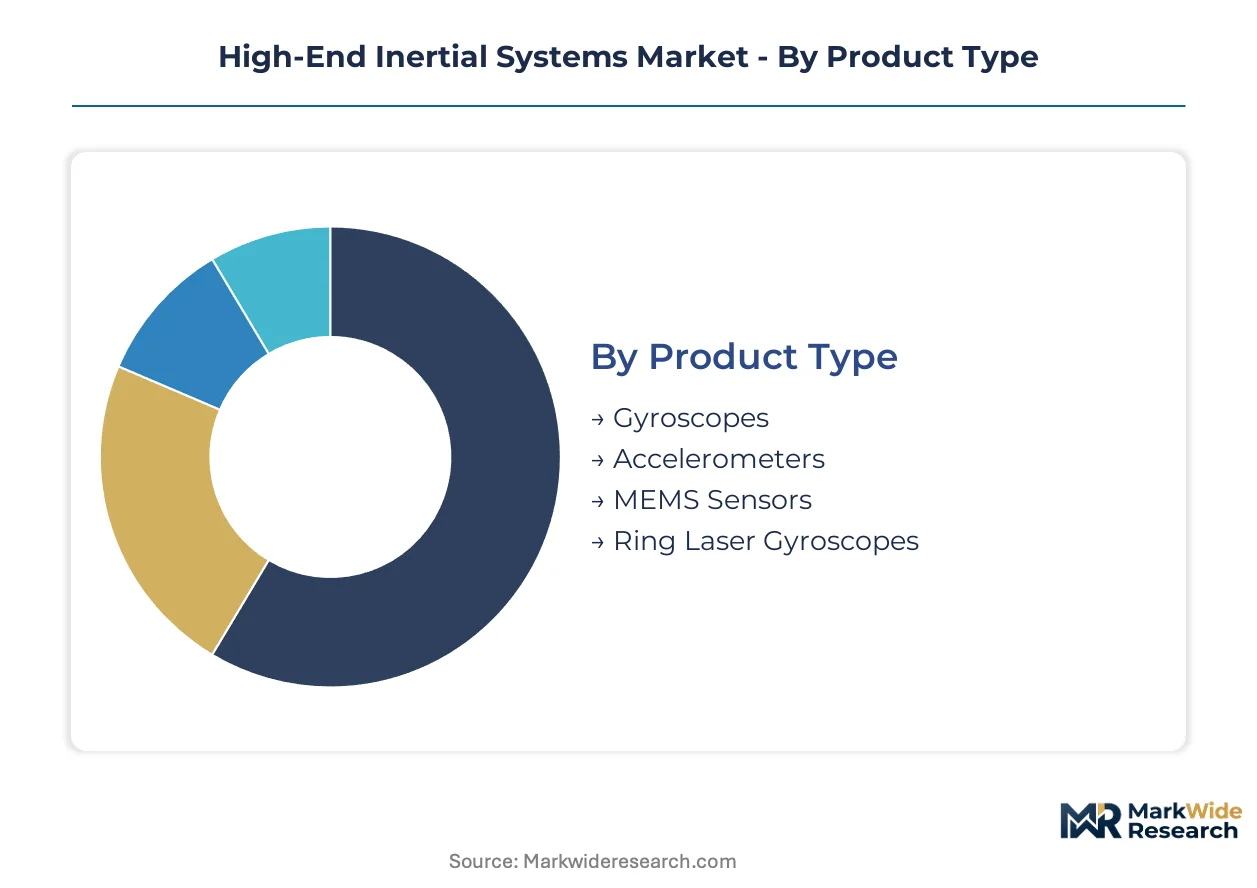
Segmentation in high-end inertial systems reveals how performance requirements fragment across defense, aerospace, and commercial channels. Procurement criteria diverge sharply between navigation-grade platforms demanding bias stability below 0.01 degrees per hour and automotive applications prioritizing cost thresholds over precision.
Product Type:
Supply concentration in precision-grade components concentrates manufacturing expertise among Japanese and German suppliers for optical fiber and rare-earth doping materials.
- Gyroscopes:Ring laser and fiber optic variants dominate navigation-grade applications with bias stability specifications below 0.01 degrees per hour. Defense procurement in the United States and Germany absorbs the majority of high-precision units for tactical aircraft and maritime platforms.
- Accelerometers:Precision quartz and MEMS-based designs measure linear acceleration with minimal drift for inertial navigation units. Aerospace corridors in Toulouse and Seattle source these for commercial aviation attitude control systems.
- MEMS Sensors:Automotive OEMs in Germany and Japan integrate these for non-safety-critical applications where cost compression outweighs precision requirements.
- Ring Laser Gyroscopes:Honeywell's manufacturing dominance persists for strategic defense contracts requiring MIL-STD-1553 compliance.
Ring laser gyroscopes absorb the bulk of installed capacity in defense applications; MEMS sensors are expanding most quickly through automotive channels.
Technology:
Cost tier differentiation separates quantum architectures from commodity MEMS platforms by orders of magnitude in both precision and unit economics.
- Fiber Optic:Immunity to electromagnetic interference and absence of moving parts makes this the preferred defense technology. NATO modernization timelines in Germany and Japan are accelerating procurement for tactical aircraft and submarine navigation.
- Micro-electromechanical Systems:Silicon-based fabrication enables mass production at price points incompatible with navigation-grade specifications. Automotive OEMs accept drift rates orders of magnitude higher than aerospace requirements.
- Quantum:Atomic interferometry architectures promise precision gains that fragment established technology hierarchies. Research institutions in Switzerland and Singapore are validating gravitational mapping applications.
- Optical:Photonic integrated circuits are compressing form factor constraints for tactical-grade deployments.
Fiber optic technology commands the largest share of defense procurement value; quantum sensing is climbing the fastest as R&D budgets redirect toward atomic platforms.
Application:
Volume concentration in aerospace corridors creates procurement gravity centers that shape supplier specialization and certification investments.
- Aerospace:Commercial aviation demands lighter, lower-power sensor architectures under EU Green Deal sustainable aviation mandates. Manufacturers in Toulouse and Hamburg prioritize REACH and RoHS compliant suppliers.
- Marine Navigation:Submarine and unmanned underwater vehicle programs mandate GPS-denied inertial navigation with no external signal dependency.
- Defense Systems:MIL-STD-1553 and MIL-STD-1760 compliance extends qualification cycles for embedded tactical aircraft systems.
- Robotics:Autonomous platforms integrate mid-tier inertial units for localization in GPS-degraded environments.
Aerospace absorbs the bulk of commercial procurement volume; marine navigation is gaining share fastest through submarine modernization programs.
End User:
Customer type determines pricing architecture, with military agencies accepting decade-long qualification cycles and automotive OEMs demanding annual cost reductions.
- Military Agencies:The U.S. Department of Defense mandates stringent embedded system standards that concentrate supplier relationships among established defense contractors.
- Aerospace Companies:Platform-as-a-service contracting is displacing capital purchase models for satellite operators in Bengaluru and Seattle.
- Automotive OEMs:Procurement criteria prioritize cost thresholds that exclude navigation-grade specifications.
- Research Institutions:Swiss and Singaporean universities are redirecting R&D budgets toward quantum sensing breakthroughs.
Military agencies anchor procurement value; research institutions are expanding fastest as quantum validation creates pull-through demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors European aerospace procurement for high-end inertial systems, while Seattle and Bengaluru corridors concentrate satellite operator demand. Defense modernization across NATO allies and quantum sensing validation in Swiss and Singaporean research institutions are redirecting regional investment patterns.
United States
The U.S. Department of Defense drives volume through MIL-STD-1553 and MIL-STD-1760 mandates for tactical aircraft embedded systems. FAA certification requirements shape commercial aviation sensor specifications. Seattle's satellite operators are adopting platform-as-a-service contracting for navigation-grade inertial units.
Germany
Bundeswehr procurement acceleration supports NATO modernization timelines for maritime and aerial navigation platforms. KBA automotive standards influence MEMS sensor integration in German OEM supply chains. Hamburg aerospace manufacturers prioritize REACH and RoHS compliant ring laser gyroscope suppliers under EU Green Deal aviation mandates.
Japan
METI industrial policy directs precision component manufacturing for optical fiber and rare-earth doping materials concentrated among Japanese suppliers. Defense Agency procurement expands for submarine inertial navigation systems. Tokyo-area research institutions collaborate with Swiss counterparts on atomic interferometry validation.
Switzerland
Swissmedic regulatory frameworks govern precision instrument manufacturing standards applicable to navigation-grade sensors. Federal research funding accelerates quantum sensing breakthroughs at ETH Zurich and EPFL. Geneva-area institutions are validating atomic interferometry for gravitational mapping applications.
Singapore
National Research Foundation grants redirect R&D budgets toward next-generation quantum sensing platforms. The country's strategic position connects Asian satellite operators with European aerospace supply chains. Research institutions in the one-north technology corridor are pioneering chip-scale atomic inertial sensor development.
High-End Inertial Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision-grade versus automotive-grade specifications. The market structures around defense contractors with decade-long qualification cycles, aerospace specialists with platform-as-a-service capabilities, and automotive suppliers competing on silicon fabrication scale. Three archetypes dominate: established ring laser gyroscope manufacturers, fiber optic navigation specialists, and emerging quantum sensing developers. Competitive moves concentrate on strategic partnerships for photonic integrated circuit integration and geographic expansion into underpenetrated space applications.
Within the defense contractor archetype, Honeywell International Inc. and Northrop Grumman Corp. occupy positions shaped by MIL-STD certification requirements and long-standing procurement relationships. Safran Group exemplifies the European aerospace specialist model, anchoring supply chains through Toulouse and Hamburg manufacturer networks. Among diversified technology conglomerates, Thales Group and General Electric Company represent scale-driven portfolios spanning multiple precision sensing applications.
| Leading Market Players |
|---|
| Thales Group |
| Bosch Sensortec GmbH |
| Honeywell International Inc. |
| Collins Aerospace |
| General Electric Company |
| Northrop Grumman Corp. |
| Analog Devices Inc. |
| Gladiator Technologies Inc. |
| Safran Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between navigation-tier and automotive-tier specifications fragments both pricing architectures and supplier bases across defense and commercial channels. Defense procurement tethered to MIL-STD-1553 and MIL-STD-1760 mandates sustains premium pricing for bias stability below 0.01 degrees per hour, while automotive OEMs compress supplier margins through silicon-fabrication scale economies.
Pricing Analysis
Value-based pricing anchored to guaranteed uptime and calibration-certainty thresholds dominates satellite operator contracts in Bengaluru and Seattle corridors. Pricing stratifies across navigation-grade, tactical-grade, and automotive-grade certification tiers, with drift-rate specifications and electromagnetic immunity ratings as primary differentiation drivers. Cost compression in MEMS channels is intensifying because German and Japanese automotive OEMs annualize procurement cost-down targets. Research institutions exhibit least price sensitivity, absorbing multi-year development cycles for quantum sensing validation.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German suppliers for precision-grade optical fiber and rare-earth doping materials essential to fiber optic gyroscope manufacturing. Manufacturing draws from concentrated feedstock in Japan, Germany, and select Swiss precision-component corridors. Tariff exposure on quantum-enhanced navigation platforms under Wassenaar Arrangement revisions compounds sourcing risk for dual-use systems. Distribution runs through defense contractor primes with decade-long qualification cycles and aerospace platform-as-a-service aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum sensing R&D concentration is forcing consolidation among fiber optic and ring laser specialists unable to pivot toward atomic interferometry architectures.
For Market Incumbents: Cement dominance in MIL-STD-certified embedded systems through backward integration into precision optical fiber supply and captive rare-earth doping capacity. Anchor procurement relationships with U.S. Department of Defense and Bundeswehr modernization programs to offset MEMS substitution pressure in automotive channels. For New Entrants and Emerging Players: Enter via radiation-hardened inertial units for low-earth orbit satellite constellations in underpenetrated Bengaluru and Toulouse corridors. Target chip-scale atomic sensor development through photonic integrated circuit partnerships as the most penetrable technology convergence point. For Investors and Strategic Acquirers: Re-rating potential sits with quantum sensing developers given atomic interferometry validation at Swiss and Singaporean research institutions. Long-term viability favors specialists with laser cooling expertise and photonic integration capabilities. Watch Wassenaar Arrangement export control revisions as the signal indicating platform-access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Partnership | ETH Zurich and EPFL collaborations compress form factor for tactical-grade atomic sensors. |
| REACH and RoHS Compliance Investment | Hamburg and Toulouse manufacturers prioritize mercury-free ring laser gyroscope suppliers. |
| Platform-as-a-Service Contracting Expansion | Seattle satellite operators trade capital expenditure for guaranteed navigation-grade performance thresholds. |
| Quantum Sensing R&D Concentration | Singapore's one-north corridor redirects budgets toward chip-scale atomic inertial sensor development. |
| Defense Qualification Cycle Acceleration | MIL-STD-1553 and MIL-STD-1760 compliance investments anchor U.S. tactical aircraft procurement. |
Research Methodology
Independent corroboration across defense procurement officers, aerospace platform engineers, and quantum physics researchers underwrites the qualitative findings. Primary fieldwork encompassed inertial navigation unit program managers at NATO military agencies, satellite operator procurement leads in Bengaluru and Seattle, and atomic physics specialists at Swiss and Singaporean research institutions. Secondary validation drew from FAA certification databases, EU Green Deal sustainable aviation filings, and Wassenaar Arrangement dual-use control revisions. Bottom-up segment sizing and top-down macro anchor triangulation resolved volume and value estimates.
Comparable historical performance across ring laser, fiber optic, and MEMS technology generations anchored projection parameters over the analysis window. Segmentation modeling incorporated product type, technology architecture, application severity, and end-user procurement archetype. CAGRs derived from technology substitution curves, defense modernization budget trajectories, and automotive OEM sensor integration rates. Quantum sensing adoption curves and photonic integration cost reduction slopes informed upside scenario construction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or rare-earth supply disruption. Forecasts reflect documented assumptions on NATO procurement acceleration, EU Green Deal aviation mandate enforcement, and atomic interferometry commercialization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market