
 Flat Panel Satellite Antenna Market | 2026-2036
Flat Panel Satellite Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Panel Satellite Antenna Market Analysis
ISO 9001 and ITAR qualification cycles are reorganizing the competitive landscape for flat panel satellite antenna suppliers. Kymeta Corporation leverages its proprietary metamaterials approach to sustain commercial maritime contracts across multiple flag states. ThinKom Solutions anchors its position through Ka-band compatibility with existing GEO and emerging LEO constellations. Hanwha Phasor competes on the strength of South Korean defense procurement channels and government-backed R&D funding.
Flat panel satellite antennas are low-profile, electronically steerable radiating assemblies that replace parabolic dishes through phased array or metamaterial architectures, typically operating across Ku, Ka, and X-band frequencies with beam-switching speeds under one millisecond. Their primary purpose is to maintain satellite connectivity on moving platforms—aircraft, vessels, and vehicles—where mechanical steering proves impractical. Fixed antennas currently dominate installed base economics due to simpler thermal management and lower per-unit cost, while mobile antennas represent the fastest-expanding margin pool as defense and commercial aviation retrofit programs accelerate. Phased array technology leads R&D allocation, though electronic beamforming is displacing mechanical steering in new maritime installations where size and weight constraints are most severe.
The FCC governs terminal authorization and spectrum coordination for U.S. deployments, while ITAR controls restrict technology transfer for defense-grade electronically steered arrays; EAR and State Department licensing thus shape which suppliers can serve allied military customers. The EU's Radio Equipment Directive and RED cybersecurity requirements are adding compliance layers for terminals entering European commercial aviation and maritime channels. Stakeholders must monitor how dual-use export classifications evolve as LEO constellation operators seek to standardize terminal form factors across national boundaries.
Market Dynamics
The FCC's streamlined licensing framework for non-geostationary satellite orbit terminals is compressing equipment certification timelines, while defense procurement channels across NATO member states are accelerating electronically steered array deployments for beyond-line-of-sight communications. This dual-use infrastructure convergence is restructuring supplier qualification hierarchies.
Growth Catalysts
- ITAR-qualified defense channels:Allied military procurement programs are creating captive demand pools for electronically steered arrays with beam-switching speeds under one millisecond.
- Maritime flag state mandates:Commercial vessel operators face mounting connectivity requirements that mechanically steered antennas cannot satisfy on moving platforms.
- LEO constellation density:Emerging low-Earth orbit networks require terminal architectures compatible with multiple orbital planes and rapid handoff protocols.
Market Restraints
- Gallium nitride substrate costs:Phased array fabrication depends on specialized semiconductor materials with concentrated supply chains and volatile pricing.
- ITAR export classification friction:Dual-use technology controls restrict supplier access to allied defense customers outside cleared channels.
- Thermal management complexity:Mobile antenna form factors impose severe constraints on power dissipation that fixed installations avoid.
Strategic Opportunities
- Commercial aviation retrofit programs:Airlines are replacing legacy connectivity hardware with electronically steerable assemblies during scheduled maintenance cycles.
- EU Radio Equipment Directive harmonization:Standardized certification pathways reduce terminal requalification costs for multi-national fleet operators.
- Metamaterial-Ka band convergence:Hybrid architectures combining metamaterial lenses with traditional phased elements enable multi-constellation compatibility.
Industry Challenges
- Phased array calibration expertise:The specialized workforce required for beamformer alignment and thermal compensation remains scarce relative to deployment targets.
- ISO 9001-ITAR audit concurrency:Suppliers must synchronize quality management and defense trade compliance reviews, extending vendor onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Panel Satellite Antenna Market |
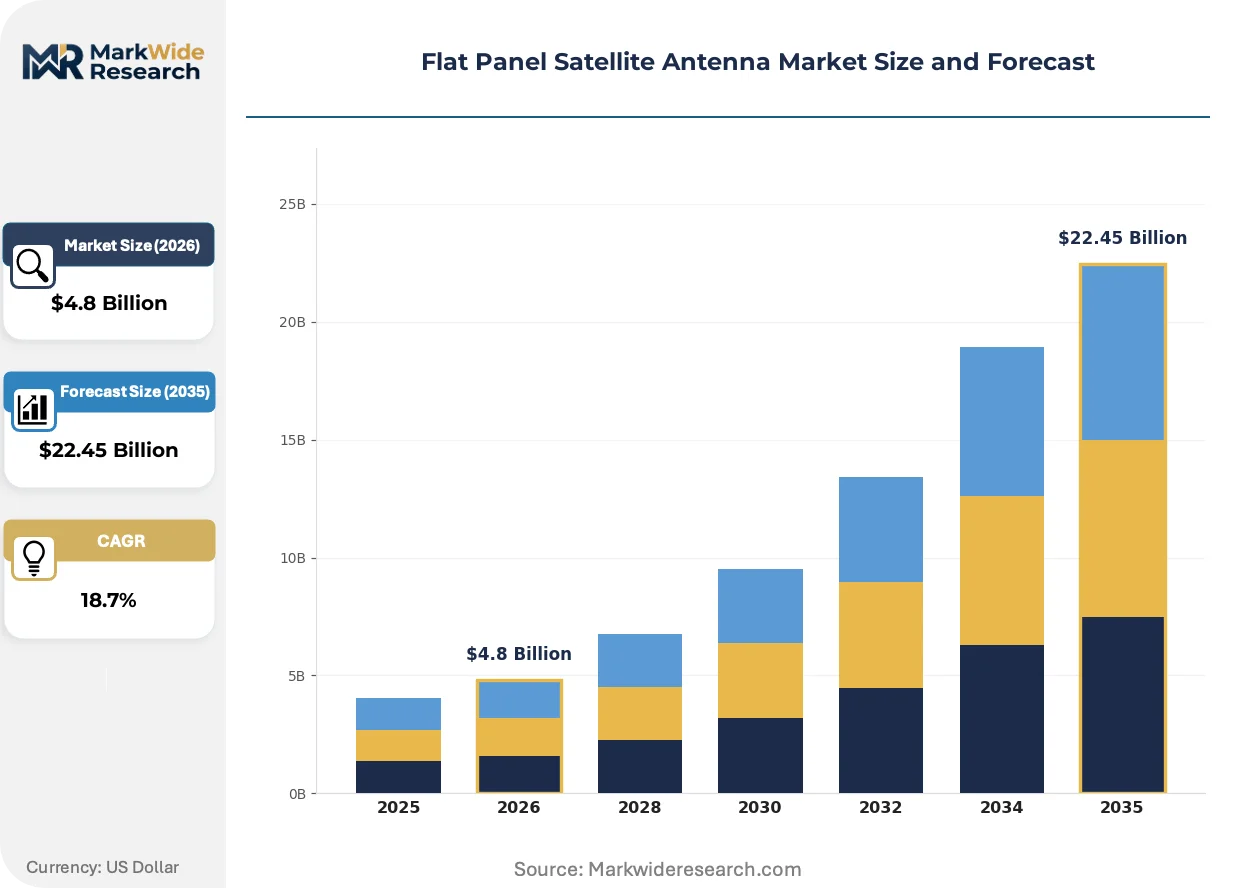
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Antennas, Portable Antennas, Mobile Antennas, Array Antennas End User: Aerospace, Maritime, Telecommunications, Government Technology: Electronic Beamforming, Mechanical Steering, Phased Array, MEMS Application: Broadcasting, Data Communication, Military Operations, Internet Access |
| Companies Covered | Kymeta Corporation, ThinKom Solutions, Hanwha Phasor, Gilat Satellite Networks, TTI Norte, L3Harris Technologies, ALCAN Systems, Ball Aerospace, China Starwin Science & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Panel Satellite Antenna Market Emerging Trajectories
Terminal architectures are fragmenting between defense-grade electronically steered arrays and commercial metamaterial approaches, with regulatory pathways diverging accordingly. This technological schism is reshaping R&D allocation and supplier positioning across maritime, aviation, and ground mobile segments.
Metamaterial-based beamforming is bifurcating the commercial maritime segment from defense procurement channels. Kymeta Corporation's proprietary approach enables continuous connectivity without mechanical steering hardware. The technology is compressing total cost of ownership for commercial vessel operators while creating a capability gap that ITAR-controlled suppliers exploit in adjacent defense markets.
REACH substance restrictions and EU Green Deal procurement criteria are mandating redesigned thermal management materials in terminals entering European commercial aviation and maritime channels. Manufacturers must substitute legacy compounds with compliant alternatives without degrading RF performance. German and French flag state registries are enforcing these requirements most stringently, compressing supplier qualification timelines for continental fleet operators.
Defense procurement offices are consolidating antenna requirements across air, sea, and ground platforms into multi-year framework agreements. This buyer concentration is displacing fragmented spot purchasing that previously characterized military terminal acquisition. The United States Space Force modernization budgets are centralizing most visibly, with allied NATO members beginning similar consolidation patterns.
Flat Panel Satellite Antenna Market Segmentation
Flat panel satellite antenna procurement splits across incompatible technical standards and diverging regulatory pathways. Defense buyers prioritize ITAR-controlled electronically steered arrays while commercial operators optimize for total cost of ownership across maritime and aviation fleets.
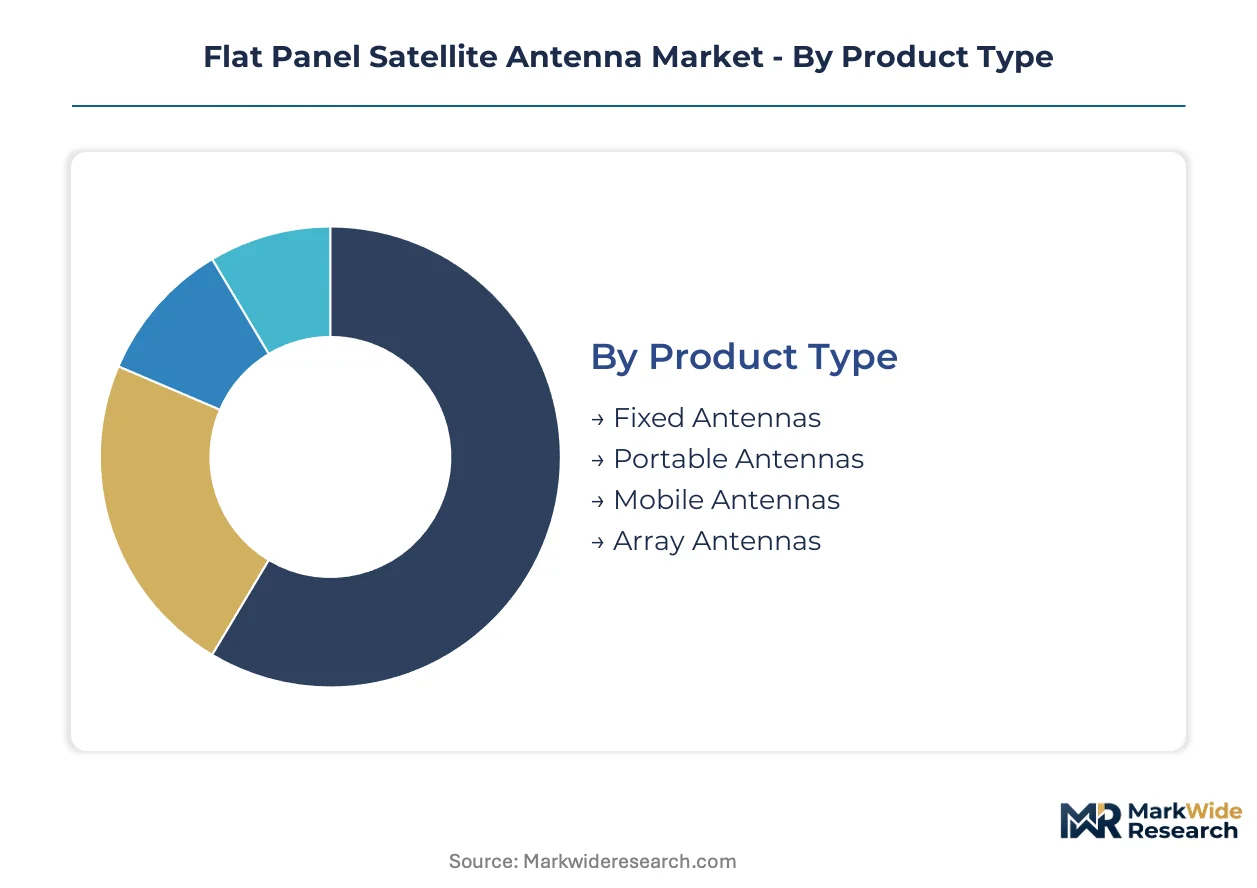
Product Type:
Fixed antennas face the strongest substitution pressure from mechanically steered parabolic dishes in price-sensitive commercial installations where platform mobility is absent.
- Fixed Antennas:Stationary phased array assemblies mounted on terrestrial infrastructure or vessel superstructures. Demand concentrates in United States government ground stations and European maritime port facilities where FCC and EU Radio Equipment Directive compliance costs are amortized across high-utilization deployments.
- Mobile Antennas:Electronically steerable radiating assemblies for aircraft, vessels, and ground vehicles requiring sub-millisecond beam switching. NATO defense procurement channels and commercial aviation retrofit programs in Germany, France, and the United Kingdom are absorbing production capacity as airlines replace legacy connectivity hardware during scheduled maintenance cycles.
- Portable Antennas:Rapidly deployable terminals for expeditionary communications and emergency response.
- Array Antennas:Modular scalable configurations for high-throughput gateway applications.
Fixed antennas retain volume leadership; mobile antennas hold the steepest expansion curve.
End User:
Cost tier stratification separates defense-grade qualification requirements from commercial procurement efficiency.
- Government:ITAR-controlled electronically steered arrays for beyond-line-of-sight military communications. United States Space Force modernization budgets and allied NATO procurement offices are consolidating multi-year framework agreements that displace fragmented spot purchasing.
- Maritime:Commercial vessel operators face mounting flag state connectivity mandates that mechanically steered antennas cannot satisfy on moving platforms. German and French registries enforce REACH-compliant thermal management materials most stringently.
- Aerospace:Commercial aviation retrofit programs and defense airborne platforms.
- Telecommunications:Ground infrastructure for LEO constellation gateways and cellular backhaul.
Government channels dominate revenue concentration; maritime end use is climbing the fastest as flag state mandates proliferate.
Technology:
Application context determines whether electronic or mechanical beam steering delivers viable economics.
- Phased Array:Semiconductor-based beamforming using gallium nitride substrates with beam-switching speeds under one millisecond. Defense procurement across NATO member states and emerging LEO constellation terminal requirements are stretching specialized fabrication capacity.
- Electronic Beamforming:Metamaterial and hybrid architectures enabling multi-constellation compatibility without mechanical steering hardware. Commercial maritime operators in South Korea and Japan are adopting these approaches to compress total cost of ownership.
- Mechanical Steering:Motorized gimbal systems retained in cost-constrained fixed installations.
- MEMS:Micro-electromechanical systems for compact consumer and tactical applications.
Phased array retains technology leadership; electronic beamforming is gaining share fastest as metamaterial-Ka band convergence matures.
Application:
Customer type segmentation separates mission-critical military operations from commercial connectivity services.
- Military Operations:Beyond-line-of-sight communications for airborne, maritime, and ground platforms requiring jam-resistant low-probability-of-intercept waveforms. United States ITAR controls and State Department licensing shape supplier access to allied customers.
- Internet Access:Consumer and enterprise broadband terminals for LEO constellation services. FCC streamlined licensing for non-geostationary satellite orbit terminals is compressing equipment certification timelines for commercial deployments.
- Data Communication:Enterprise and government backhaul networks.
- Broadcasting:Media distribution and content delivery infrastructure.
Military operations anchor premium pricing; internet access applications are expanding most quickly as LEO constellation density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's streamlined licensing for non-geostationary satellite orbit terminals underwrites United States demand leadership, while NATO defense procurement channels and commercial LEO constellation deployments create dual-use infrastructure across allied territories.
United States
Space Force modernization budgets and commercial aviation retrofit programs absorb production capacity for electronically steered arrays. The FCC governs terminal authorization and spectrum coordination, compressing equipment certification timelines for emerging LEO networks. California and Colorado host defense contractor clusters where ITAR-qualified suppliers align beam-switching speeds with military procurement specifications.
Germany
Commercial aviation retrofit programs and maritime flag state mandates drive demand for REACH-compliant thermal management materials. The EU Radio Equipment Directive and RED cybersecurity requirements add certification layers for terminals entering European channels. Bavaria and Hamburg concentrate system integrators serving NATO defense procurement offices and commercial fleet operators simultaneously.
United Kingdom
Commercial aviation retrofit cycles and defense airborne platform requirements create overlapping demand pools for Ka-band compatible terminals. The UK Space Agency coordinates national spectrum policy with EU regulatory alignment post-Brexit. Southwest England hosts satellite manufacturing clusters where suppliers calibrate phased arrays for multi-constellation compatibility.
South Korea
Government-backed R&D funding and defense procurement channels accelerate electronically steered array deployment for maritime and airborne platforms. The MFDS and national space development frameworks guide dual-use technology commercialization. Seoul Capital Area and Busan-Ulsan regions concentrate metamaterial research facilities and defense contractor integration sites.
Japan
Commercial maritime operators adopt metamaterial architectures to compress total cost of ownership across flag state fleets. METI coordinates national space policy with spectrum allocation for LEO constellation terminals. Tokyo and Nagoya regions host precision manufacturing clusters where suppliers align hybrid beamforming systems with multi-orbital plane handoff protocols.
Flat Panel Satellite Antenna Market Vendor Landscape
Listed leaders compete with private specialists across qualification hierarchies, with ITAR certification and ISO 9001 compliance separating accessible tiers. The supplier base concentrates around three strategic archetypes: defense-grade electronically steered array specialists, commercial metamaterial approach providers, and hybrid architecture integrators serving dual-use channels. Competitive moves center on multi-year framework agreement capture and metamaterial-Ka band convergence R&D allocation.
Among defense-qualified suppliers, L3Harris Technologies and Ball Aerospace occupy positions within ITAR-controlled procurement channels, while Kymeta Corporation exemplifies the commercial metamaterial archetype through proprietary approaches sustaining maritime contracts. ThinKom Solutions anchors the hybrid architecture tier, with Ka-band compatibility spanning existing GEO and emerging LEO constellations. Hanwha Phasor represents government-backed R&D funding models, leveraging South Korean defense procurement channels against concentrated supply chain constraints.
| Leading Market Players |
|---|
| Kymeta Corporation |
| ThinKom Solutions |
| Hanwha Phasor |
| Gilat Satellite Networks |
| TTI Norte |
| L3Harris Technologies |
| ALCAN Systems |
| Ball Aerospace |
| China Starwin Science & Technology |
| Others |
Supply Flow & Price Mechanics
Twenty-six-week lead times for gallium nitride substrates concentrate pricing power with ITAR-qualified defense contractors, while commercial maritime buyers compress procurement cycles through metamaterial alternatives that bypass semiconductor bottlenecks.
Pricing Analysis
Three-tier pricing structure across ITAR-certified defense, commercial aviation-qualified, and economy maritime segments separates procurement channels by compliance burden. Price differentiation hinges on ISO 9001 audit concurrency and beam-switching performance thresholds. Pricing pressure stems from gallium nitride substrate volatility that squeezes phased array margins. Defense buyers exhibit lowest price sensitivity; commercial vessel operators demand total cost of ownership transparency.
Supply Chain Analysis
United States and South Korea anchor defense-grade electronically steered array fabrication, while Japan and Germany concentrate metamaterial lens production for commercial channels. The supply chain draws from concentrated gallium nitride wafer foundries, specialized thermal management compound suppliers, and ITAR-cleared assembly facilities. Single-source vulnerability in semiconductor substrates threatens production continuity. Distribution runs through defense procurement offices, aviation system integrators, and maritime fleet operators with diverging qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat panel satellite antenna adoption sits in early-cycle expansion as LEO constellation density forces terminal architecture upgrades across maritime and aviation fleets.
For Market Incumbents: Consolidate ITAR qualification hierarchies through captive gallium nitride substrate partnerships that lock defense procurement channels. Deepen backward integration into thermal management materials to satisfy REACH mandates compressing supplier timelines. Threat substitution from metamaterial approaches demands certification investment in Ka-band multi-constellation compatibility. For New Entrants and Emerging Players: Differentiate on electronic beamforming architectures that bypass phased array calibration bottlenecks constraining incumbent capacity. Target commercial maritime retrofit programs where flag state mandates outpace qualified supplier availability. Go-to-market leverage rests on EU Radio Equipment Directive pre-certification that accelerates fleet operator onboarding. For Investors and Strategic Acquirers: Long-term, this sits as a dual-use infrastructure play because defense and commercial LEO terminal requirements are converging on electronically steerable form factors. Acquisition profiles favor metamaterial-Ka band hybrid specialists with cleared defense channel access. Watch gallium nitride substrate pricing inflections as capacity expansion signals.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Qualification Expansion | Unlocks NATO defense procurement channels with multi-year framework agreement capture. |
| Metamaterial-Ka Band Convergence | Enables multi-constellation compatibility without mechanical steering hardware. |
| Backward Integration into Substrates | Secures gallium nitride supply against concentrated foundry bottlenecks. |
| EU RED Pre-Certification | Compresses requalification costs for multi-national aviation and maritime fleet operators. |
| Phased Array Calibration Automation | Addresses workforce scarcity constraining beamformer alignment throughput. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, commercial aviation connectivity directors, maritime fleet technical managers, and phased array manufacturing engineers; and secondary validation through FCC equipment authorization databases, EU Radio Equipment Directive filings, SEC defense contractor disclosures, and customs import records for gallium nitride substrates. Bottom-up terminal deployment estimates triangulated against top-down LEO constellation operator capex disclosures.
Across the analysis window, the forecasting framework modeled demand by product type, end user, technology architecture, and application context, with regional regulatory cluster overlays. CAGRs derived from terminal shipment trajectories calibrated against constellation launch schedules and defense budget appropriation patterns. Industry-specific inputs included ITAR export classification friction indices and REACH substance restriction implementation timelines.
Material uncertainties — gallium nitride supply disruptions, ITAR reclassification events, LEO constellation operator consolidation — sit outside the modeled envelope. Forecasts reflect assumptions about beam-switching performance standardization and dual-use technology transfer policy continuity. Recalibration cycles align with material shifts in NATO procurement consolidation patterns and FCC spectrum allocation rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Mexico Satellite Connectivity Market
Satellite
Satellite Photography Service Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Satellite Manufacturing Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Israel Satellite Communications Market
Satellite
Global Enterprise VSAT System Market
Satellite
Medium and Large Satellite Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Satellite Services Market
Satellite
All-Electric Satellites Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
4K Satellite Broadcasting Market
Satellite
North America Small Satellite Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
US Satellite-Based Earth Observation Market