
 Anti Rolling Gyro (ARG) Market | 2026-2036
Anti Rolling Gyro (ARG) Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Rolling Gyro (ARG) Market Insights
Marine-grade stabilization specifications is bifurcating the competitive landscape into precision-engineered premium suppliers and cost-optimized volume manufacturers. Seakeeper leverages its proprietary vacuum-sealed flywheel architecture to dominate the recreational yacht segment across North American and European waterways. Mitsubishi Heavy Industries anchors the commercial vessel category with integrated ARG systems engineered for naval and ferry operators requiring continuous heavy-sea operations.
An Anti Rolling Gyro is a rotational inertia device comprising a high-speed spinning mass—typically a steel or composite flywheel enclosed in a vacuum chamber—mounted on gimbals to generate counter-torque against vessel roll motion, with operational speeds often exceeding 10,000 RPM and angular momentum ratings scaled to vessel displacement. The technology's primary purpose is real-time stabilization without external water fins or drag-inducing appendages, enabling retrofit installation and zero-speed effectiveness. Mechanical Gyros retain the largest installed base among mature commercial fleets, while MEMS-based compact units represent the fastest-growing category as autonomous surface vessels and unmanned marine systems demand miniaturized attitude control. Fiber Optic technology commands premium pricing in defense navigation applications where drift tolerance below 0.01 degrees per hour justifies procurement outlays.
The International Maritime Organization (IMO) stability criteria, the US Coast Guard passenger vessel regulations, and the EU Marine Equipment Directive collectively mandate roll reduction performance documentation for vessels carrying more than 12 passengers, directly shaping ARG specification requirements in newbuild contracts. Classification societies including Lloyd's Register and DNV now require sea-trial validation of active stabilization systems before final certification issuance. Stakeholders must monitor evolving unmanned vessel codes and autonomous shipping liability frameworks, as these will determine whether compact ARG systems become mandatory redundancy for navigation-critical drone ships.
Market Dynamics
Marine-grade stabilization specifications is bifurcating the competitive landscape into precision-engineered premium suppliers and cost-optimized volume manufacturers. The IMO's revised stability guidelines for passenger vessels are tightening roll-motion requirements worldwide, forcing specification upgrades across newbuild contracts.
Growth Catalysts
- IMO Stability Guidelines:The International Maritime Organization's revised criteria mandate roll reduction performance documentation for vessels carrying more than 12 passengers, directly embedding ARG requirements into newbuild specifications.
- Autonomous Surface Vessels:Unmanned marine systems demand miniaturized attitude control, driving MEMS-based compact unit adoption where continuous stabilization replaces human-operated fin systems.
- Florida Boatbuilding Clusters:High-value vessel output is rising fastest in this concentration of yacht and superyacht builders, expanding ARG installations to meet passenger comfort standards.
Market Restraints
- Vacuum-Sealed Flywheel Cost Structure:Precision-engineered steel and composite flywheels requiring operational speeds exceeding 10,000 RPM impose material and manufacturing cost premiums that constrain mid-market penetration.
- Classification Society Validation:Lloyd's Register and DNV sea-trial certification requirements for active stabilization systems extend project timelines and increase pre-delivery compliance expenditure.
- Hydrodynamic Fin Stabilizers:Water-fin systems retain installed base advantages in commercial retrofit markets where drag tolerance exists and capital budgets prioritize lower first-cost solutions.
Strategic Opportunities
- Drone Ship Redundancy Mandates:Evolving unmanned vessel codes and autonomous shipping liability frameworks will determine whether compact ARG systems become mandatory backup for navigation-critical systems.
- EU Marine Equipment Directive:Roll reduction performance documentation requirements create specification pull for certified ARG installations across Mediterranean shipyards serving passenger vessel operators.
- Fiber Optic-ARG Convergence:Defense navigation applications demanding drift tolerance below 0.01 degrees per hour are opening premium pricing tiers for integrated stabilization-navigation systems.
Industry Challenges
- Sea-Trial Certification Bottlenecks:Classification society validation of active stabilization systems before final certification issuance compresses delivery schedules and strains testing capacity at major shipyards.
- Retrofit Integration Complexity:Legacy vessel architectures lack structural provisions for high-mass flywheel housing and gimbal mounting, requiring engineered foundation modifications that extend installation duration.
- Vacuum Chamber Maintenance Skill Gap:Specialized technician training for sealed flywheel systems remains concentrated among OEM service networks, limiting third-party maintenance competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Rolling Gyro (ARG) Market |
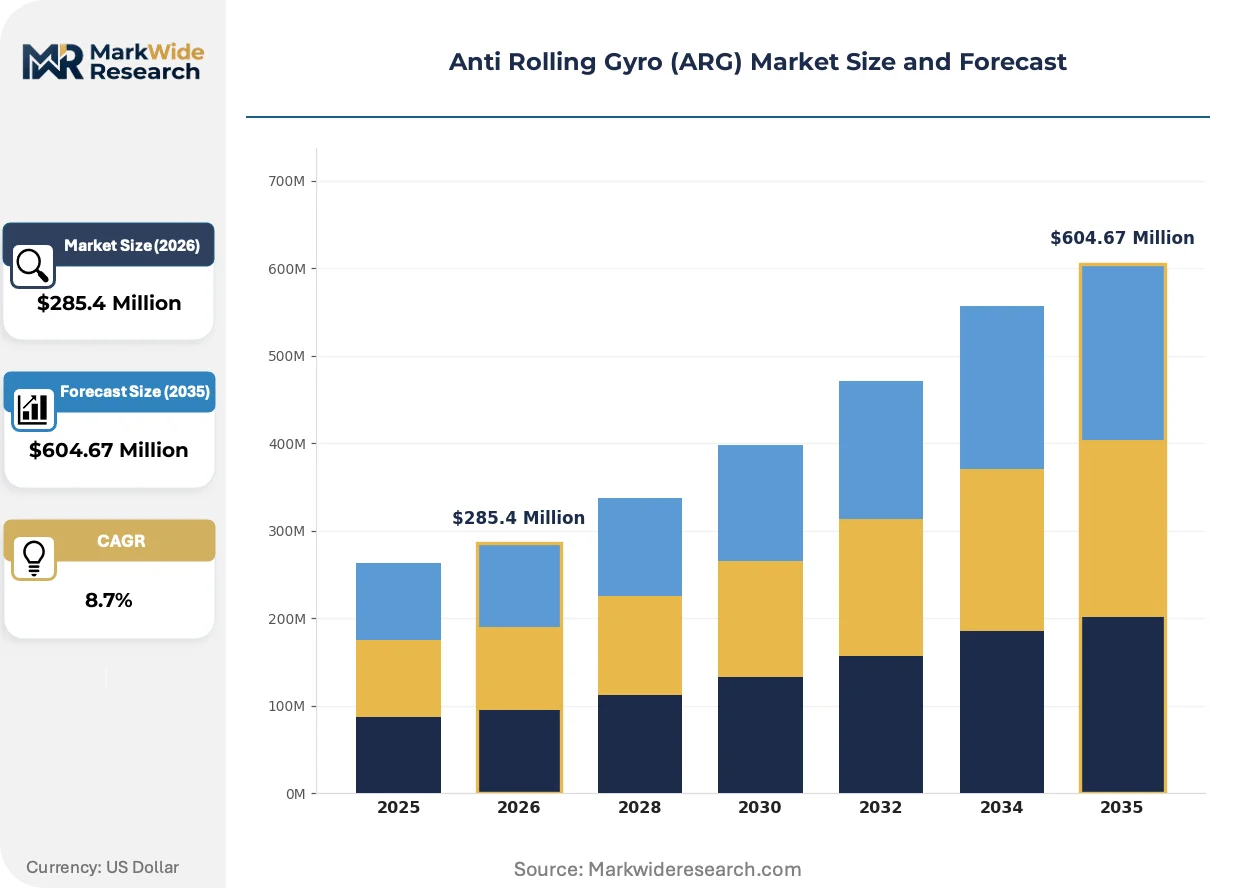
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Gyros, Optical Gyros, Vibrating Structure Gyros, Micro-Electro-Mechanical Systems Application: Aerospace, Automotive, Marine, Robotics Technology: Fiber Optic, Ring Laser, Capacitive, MEMS End User: Defense, Aviation, Consumer Electronics, Navigation Systems |
| Companies Covered | Mitsubishi Heavy Industries, Seakeeper, TOHMEI Industries, Ocean Electrics, Natheer Technical, DMS Holland, American Spindoctors, Fluid in Motion Marine, Quick SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Rolling Gyro (ARG) Market Trends and Innovations
Active stabilization architectures are undergoing fundamental transformation as solid-state sensing converges with rotational inertia systems. Three developments are restructuring how counter-torque generation is specified, procured, and deployed across vessel categories.
MEMS-based compact gyros are supplanting mechanical flywheel systems in autonomous surface vessels and unmanned marine platforms. Naval architects specifying attitude control for drone ships prioritize solid-state reliability over vacuum-sealed mechanical complexity. This displacement is compressing the addressable market for conventional ARG units below 500 kg angular momentum ratings.
The EU Marine Equipment Directive's roll reduction documentation mandates are reshaping newbuild contracting practices. Shipyards in Mediterranean clusters now embed ARG specifications into base vessel configurations rather than treating stabilization as optional outfitting. Passenger ferry operators in Greece, Italy, and Spain are responding by standardizing active gyro installations across series builds.
Yacht owners are unbundling after-sales service contracts from initial equipment procurement. Mediterranean and Florida-based superyacht managers now source third-party maintenance for vacuum-sealed flywheel systems independent of builder arrangements. This channel disintermediation is most visible in the 40-80 meter yacht segment where operational uptime requirements exceed builder warranty periods.
Anti Rolling Gyro (ARG) Market Segmentation
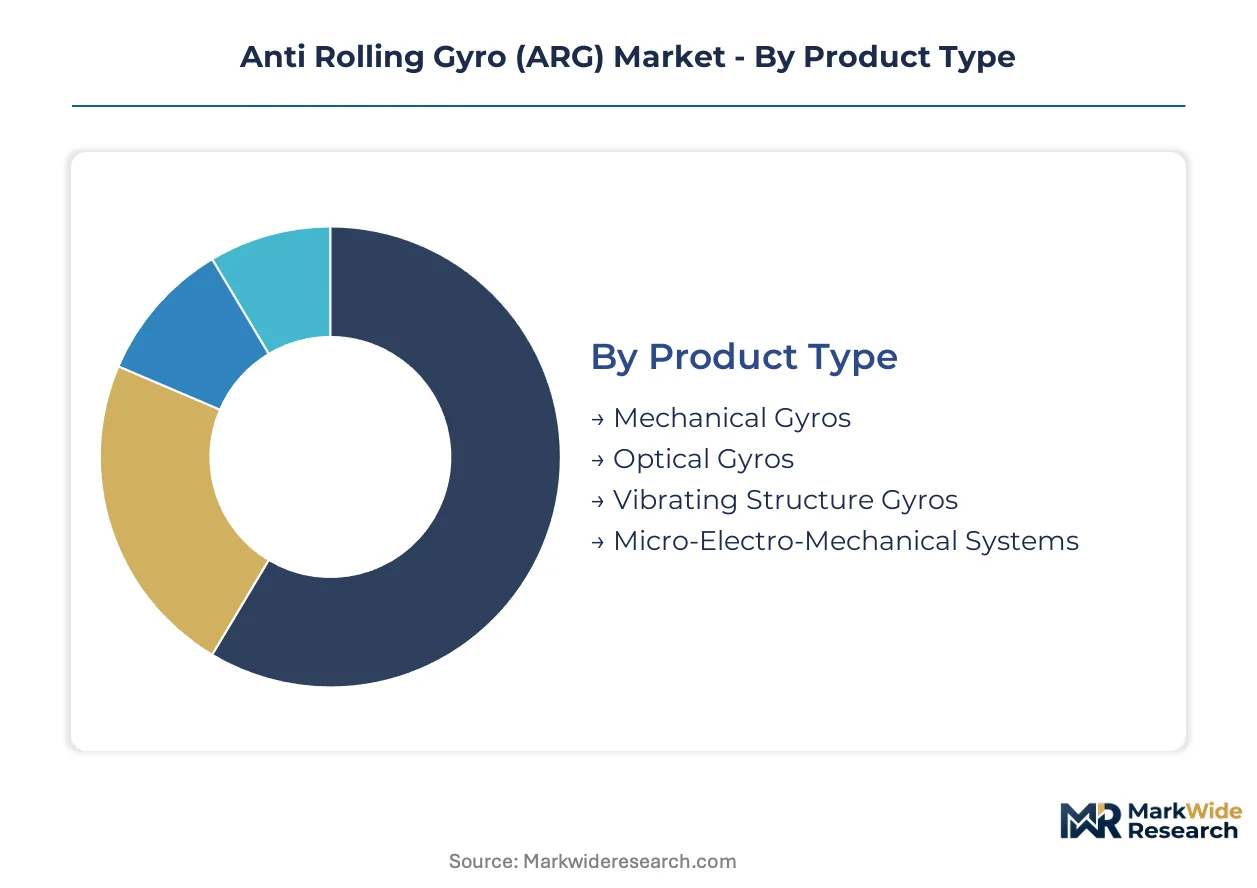
ARG technology segments diverge sharply in regulatory treatment, with marine applications facing IMO stability mandates while defense procurement prioritizes drift tolerance specifications. Understanding these segmentation boundaries enables targeted product positioning across certification regimes.
Product Type:
IMO stability guidelines and defense navigation standards create divergent certification pathways for each gyro architecture.
- Mechanical Gyros:Vacuum-sealed steel or composite flywheels operating above 10,000 RPM generate counter-torque through rotational inertia. Commercial ferry operators in Mediterranean shipyards specify these for passenger vessels exceeding 12-person capacity under IMO roll-reduction mandates.
- Optical Gyros:Fiber optic and ring laser configurations measure angular velocity through Sagnac effect interference patterns. Defense navigation systems demanding drift tolerance below 0.01 degrees per hour concentrate procurement in this category, justifying premium pricing tiers.
- Vibrating Structure Gyros:Piezoelectric resonators detect Coriolis forces through vibrating mass displacement.
- Micro-Electro-Mechanical Systems:Silicon-fabricated sensors enable miniaturized attitude control for autonomous surface vessels.
Established volume favors Mechanical Gyros; emerging adoption favors Micro-Electro-Mechanical Systems.
Application:
Cost tier differentiation separates capital-intensive marine installations from price-sensitive consumer electronics integration.
- Marine:Yacht and superyacht builders in Florida boatbuilding clusters embed ARG specifications into base configurations. The US Coast Guard passenger vessel regulations and EU Marine Equipment Directive collectively mandate roll reduction documentation, forcing specification upgrades across newbuild contracts.
- Aerospace:Aircraft attitude reference systems require gyroscopic stabilization for flight control redundancy. FAA certification timelines and DO-178C software standards extend development cycles for integrated navigation-stabilization platforms.
- Automotive:Autonomous vehicle platforms deploy compact gyros for dead-reckoning backup during GPS signal loss.
- Robotics:Industrial automation and unmanned ground vehicles leverage MEMS units for platform stabilization.
Marine applications command highest unit value; MEMS penetration is expanding most quickly in Robotics.
Technology:
Supply concentration in precision optics manufacturing shapes regional production patterns for high-performance categories.
- Fiber Optic:Light propagation through coiled fiber detects rotation-induced phase shifts with exceptional accuracy. Defense contractors specify these for submarine navigation and strategic missile guidance where drift tolerance requirements exceed commercial thresholds.
- MEMS:Batch-fabricated silicon structures enable volume production at cost points inaccessible to mechanical alternatives. Drone ship developers prioritize solid-state reliability over vacuum-sealed complexity, compressing addressable demand for conventional units below 500 kg angular momentum ratings.
- Ring Laser:Counter-propagating laser beams in closed cavities measure rotation through frequency differential detection.
- Capacitive:Electrostatic sensing of proof mass displacement provides intermediate performance at moderate cost.
Fiber Optic dominates precision navigation; MEMS shows steepest expansion trajectory in unmanned systems.
End User:
Maturity gradients separate defense procurement cycles from rapid consumer electronics refresh rates.
- Defense:Naval and military operators require continuous heavy-sea operational capability with redundant stabilization architectures. Classification societies including Lloyd's Register and DNV mandate sea-trial validation before certification issuance, extending procurement timelines.
- Navigation Systems:Integrated gyrocompass and attitude heading reference systems serve commercial shipping fleets. Mediterranean ferry operators standardize active gyro installations across series builds in response to EU Marine Equipment Directive documentation requirements.
- Aviation:Commercial and general aviation platforms specify attitude indicators and turn coordinators.
- Consumer Electronics:Smartphone and wearable device manufacturers integrate compact gyros for image stabilization and motion sensing.
Defense procurement anchors premium tier pricing; Navigation Systems drive marine segment standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Mediterranean yacht markets exhibit low price elasticity for precision stabilization, while Asian commercial ferry operators prioritize total cost of ownership over premium specifications. This demand-elasticity contrast shapes regional procurement patterns and technology tier selection across marine segments.
United States
Florida boatbuilding clusters drive recreational yacht demand as superyacht builders embed ARG specifications into base configurations. The US Coast Guard passenger vessel regulations mandate roll reduction documentation for vessels carrying more than 12 passengers. Fort Lauderdale and Palm Beach marine districts concentrate high-value vessel output where operational uptime requirements exceed builder warranty periods.
Italy
Passenger ferry operators in Greece, Italy, and Spain standardize active gyro installations across series builds responding to comfort mandates. The EU Marine Equipment Directive requires roll reduction performance documentation for certified marine equipment. Mediterranean shipyards in Liguria and Tuscany embed ARG specifications into newbuild contracts rather than treating stabilization as optional outfitting.
Japan
Naval and commercial vessel operators demand continuous heavy-sea operational capability with redundant stabilization architectures. METI maritime safety standards align with IMO stability criteria for domestic passenger vessel certification. Nagoya and Kobe industrial corridors anchor integrated ARG system production for regional ferry and naval operators.
Germany
Precision-engineered premium suppliers serve North European yacht builders requiring classification society validation before certification issuance. The country's national maritime regulator enforces Lloyd's Register and DNV sea-trial requirements for active stabilization systems. Hamburg and Bremen shipbuilding districts concentrate specification engineering for Baltic and North Sea passenger vessels.
United Arab Emirates
Superyacht management companies source third-party maintenance for vacuum-sealed flywheel systems independent of builder arrangements. MOHAP marine equipment standards reference IMO stability guidelines for vessels operating in Gulf waters. Dubai Maritime City and Abu Dhabi yacht manufacturing zones attract Mediterranean and Florida-based builders establishing regional service presence.
Anti Rolling Gyro (ARG) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where precision-engineered premium suppliers compete alongside cost-optimized volume manufacturers. The competitive landscape concentrates around vacuum-sealed flywheel specialists and integrated system providers serving distinct vessel categories. Three archetypes dominate: proprietary architecture holders, commercial fleet integrators, and regional service specialists. Dominant competitive moves include technology licensing agreements and geographic service network expansion.
Among Japanese industrial conglomerates, Mitsubishi Heavy Industries anchors the commercial vessel category with integrated system capabilities. Seakeeper occupies a position exemplifying proprietary vacuum-sealed flywheel architecture dominance in recreational yacht segments. TOHMEI Industries represents the specialist tier serving regional Asian markets with focused marine stabilization expertise.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Seakeeper |
| TOHMEI Industries |
| Ocean Electrics |
| Natheer Technical |
| DMS Holland |
| American Spindoctors |
| Fluid in Motion Marine |
| Quick SpA |
| Others |
Pricing and Supply Chain Analysis
Composite flywheel substitution for precision-machined steel rotors is redrawing supplier maps from Japanese heavy-industrial corridors toward Chinese carbon-fiber manufacturing zones while compressing material cost premiums by half. This displacement simultaneously erodes incumbent vacuum-sealing expertise advantages and forces price repositioning across Mediterranean and Florida yacht markets where hull-value-to-stabilization ratios drive specification decisions.
Pricing Analysis
After-sales service contracts for vacuum-chamber maintenance and flywheel bearing replacement generate lifetime value exceeding original equipment margins by wide multiples. The dominant structure is project-based transactional pricing for newbuild installation, with three-tier pricing stratification across IMO-certified premium units, commercial-grade standard systems, and retrofit economy configurations. Price differentiation rests on Lloyd's Register certification tier and geographic delivery cost from Nagoya or Hamburg production hubs. Pricing pressure stems from MEMS-based compact units displacing mechanical gyros in autonomous vessel applications below 500 kg angular momentum ratings. Asian commercial ferry operators exhibit highest price sensitivity; Mediterranean superyacht builders show lowest elasticity for precision-engineered specifications.
Supply Chain Analysis
Inbound logistics costs from Shanghai-to-Rotterdam container congestion and Red Sea route disruptions are elevating landed cost for precision-machined gimbal housings sourced from German industrial districts. Supply concentrates in Japan for vacuum-sealed flywheel systems, Germany for precision gimbal engineering, and China for composite rotor fabrication. Raw material dependencies include high-grade bearing steel, carbon-fiber prepreg for lightweight rotors, and specialized vacuum greases for chamber sealing. Single-source vulnerability pervades the precision gyro bearing segment where NSK and SKF dominate naval-grade specifications. Distribution runs through OEM-direct channels for newbuild yacht contracts and specialized marine service networks for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sustains defensive moats through regulatory entrenchment: IMO stability mandates and classification society certification requirements embed incumbent expertise into contract specifications that new entrants cannot replicate without multi-year sea-trial track records.
For Market Incumbents: Consolidate service network density in Mediterranean and Florida yacht clusters to capture third-party maintenance contracts disintermediating builder arrangements. Acquire MEMS sensing capabilities through technology licensing to defend against solid-state displacement in autonomous vessel segments below 500 kg ratings. Priority rests on backward integration into composite rotor manufacturing to neutralize Chinese carbon-fiber cost advantages.
For New Entrants and Emerging Players: Anchor in the drone ship redundancy mandate opportunity where evolving unmanned vessel codes will specify compact ARG backup systems for navigation-critical autonomous platforms. Target Asian commercial ferry operators with cost-optimized mechanical gyro configurations that undercut Mitsubishi Heavy Industries pricing while meeting METI maritime safety standards. Go-to-market angle: direct technical sales to naval architects specifying attitude control for series-build ferry contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine equipment specialists holding Seakeeper-type proprietary vacuum-sealed architectures but lacking autonomous vessel technology exposure. Long-term viability hinges on regulatory expansion into unmanned shipping liability frameworks and drone ship code adoption. Acquisition target archetype: mid-cap specialists with Lloyd's Register certification depth and underdeveloped MEMS product pipelines. Signal to watch: IMO publication of interim guidelines for autonomous surface vessel stability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | MEMS sensing partnerships enable incumbents to counter solid-state displacement in drone ship segments. |
| Certification Investment | Lloyd's Register sea-trial validation creates specification barriers that extend procurement timelines for unqualified entrants. |
| Geographic Service Expansion | Dubai Maritime City presence captures superyacht maintenance contracts from Mediterranean and Florida owners. |
| Backward Integration | In-house composite rotor production neutralizes Chinese carbon-fiber cost premiums and secures supply continuity. |
| Joint Venture | Asian ferry builder partnerships embed ARG specifications into series-build contracts responding to EU Marine Equipment Directive. |
Research Methodology
Desk research of IMO stability guideline amendments, Lloyd's Register certification databases, and EU Marine Equipment Directive technical files preceded structured interviews with yacht builder procurement directors, naval architect specification engineers, and marine aftermarket service managers. Secondary validation drew from classification society sea-trial records, Mediterranean shipyard order books, and Florida boatbuilding cluster output data. Bottom-up vessel installation estimates triangulated against top-down market value projections.
Variance decomposition across product type, application, and end-user segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include gyro architecture tier, vessel displacement category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to installed base replacement cycles and newbuild penetration assumptions. Industry-specific forecast inputs encompass autonomous vessel code development timelines and classification society certification capacity constraints.
Decision-makers should treat outputs as directional under assumptions of stable IMO stability guideline enforcement and uninterrupted classification society sea-trial capacity; material deviation would warrant model refresh. Specific risk factors include unmanned vessel code delays, composite rotor supply disruptions, and MEMS technology performance breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America General Aviation Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
North America Helicopters Market
Aircraft
Australia Aviation Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Amphibious Aircraft Market
Aircraft
Commercial Aircraft Leasing Market
Aircraft
Aircraft Cables Market
Aircraft
Military Helicopters Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Aircraft Leasing Market