
 Global Small Arms and Light Weapons (SALW) Market | 2026-2036
Global Small Arms and Light Weapons (SALW) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Arms and Light Weapons (SALW) Market Intelligence
Adoption of MIL-SPEC+ performance standards for law enforcement and paramilitary units is unwinding the traditional separation between military-grade and civilian-use weapon designs. Heckler & Koch GmbH leverages its deep engineering expertise in polymer and metal manufacturing to meet these stringent requirements. SIG Sauer Inc. specializes in integrated weapon systems, including optics and suppressors. General Dynamics Corp competes in the crew-served light weapons segment with its established production scale.
Small arms and light weapons encompass man-portable lethal armaments designed for individual or small crew operation. These weapons, typically chambered for cartridges below 20mm caliber, utilize gas-operated or recoil-operated actions. Their primary purpose is to provide direct fire capability for military forces and paramilitary units in combat operations. The assault rifles product type remains the largest segment by volume, while pistols see sustained procurement from law enforcement end-users.
International frameworks like the UN Programme of Action (UNPoA) and the Wassenaar Arrangement guide export controls and transfer documentation for SALW. In the United States, the Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) enforces domestic manufacturing and sales regulations. Future investment decisions for manufacturers will hinge on balancing compliance with these complex regulations against the performance demands of next-generation defense programs.
Market Dynamics
The convergence of military-grade performance requirements and law enforcement modernization programs is the central force shaping the market. This trend dissolves traditional design boundaries, demanding weapons with enhanced modularity and lethality for a wider range of paramilitary and police units.
Growth Catalysts
- Modular Weapon Platforms:Increased military demand for weapon systems that can be rapidly reconfigured for different mission profiles, such as changing calibers or barrel lengths in the field, drives innovation and procurement.
- Indian Defense Modernization:India's large-scale programs to equip its army and border security forces with modern assault rifles and carbines create significant, sustained volume demand for manufacturers.
- Law Enforcement Upgrades:A global trend among police forces to adopt patrol rifles and advanced pistols, moving away from traditional sidearms for greater tactical capability in critical incidents.
Market Restraints
- Export Control Complexity:The Wassenaar Arrangement and UNPoA impose strict documentation and end-user verification requirements, delaying international transfers and adding significant administrative costs for exporters.
- Less-Lethal Substitution:Political pressure encourages the use of advanced less-lethal alternatives in policing, potentially reducing the addressable market for firearms in certain public order roles.
- Specialty Material Costs:Price volatility for high-strength steel alloys and specialized polymers essential for lightweight components can compress manufacturer margins on fixed-price government contracts.
Strategic Opportunities
- Emerging Defense Markets:Nations in Southeast Asia and Eastern Europe are building domestic production capabilities, creating opportunities for technology transfer, licensing, and joint ventures with established firms.
- Integrated Fire Control:The convergence of microelectronics and optics offers a frontier for smart rifles that integrate ballistic computation and target tracking directly into the weapon system.
- Counter-UAS Applications:Development of specialized light weapons, including rifles with specific ammunition, designed to disable small unmanned aerial systems at close range opens a new niche market.
Industry Challenges
- Lengthy Certification Cycles:Gaining qualification for new weapon designs against stringent military standards like MIL-SPEC can take years, delaying revenue generation and increasing research and development costs.
- Supply Chain Qualification:Securing and validating suppliers for critical components like barrels and bolt carrier groups is a time-consuming process, hindering production scalability and speed to market.
- Intellectual Property Licensing:Navigating complex international patent agreements for local production of foreign designs presents significant legal and administrative hurdles for manufacturers entering new markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Arms and Light Weapons (SALW) Market |
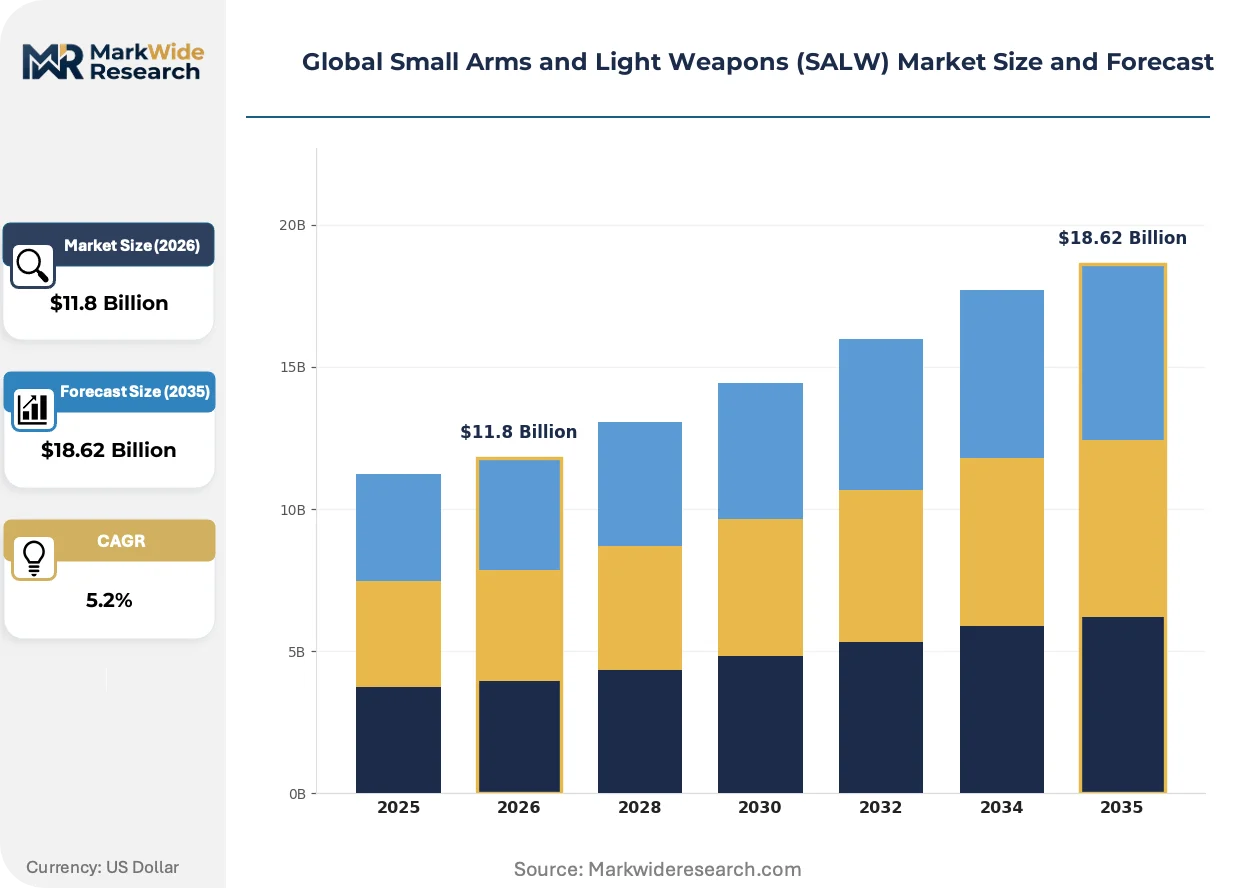
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.62 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assault Rifles, Sniper Rifles, Submachine Guns, Machine Guns, Pistols End User: Military Forces, Paramilitary Units, Law Enforcement, Security Contractors, Peacekeeping Troops Application: Combat Operations, Counterterrorism, Defense Training, Border Control, Tactical Missions Deployment: Infantry Units, Special Operations, Airborne Forces, Naval Infantry, Urban Warfare Teams |
| Companies Covered | SIG Sauer Inc., FN Herstal SA, Smith & Wesson Brands Inc., Colt’s Manufacturing Company LLC, Beretta S.p.A., Sturm, Ruger & Co., Heckler & Koch GmbH, GLOCK Gesellschaft m.b.H., General Dynamics Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Arms and Light Weapons (SALW) Market Strategic Shifts & Innovations
A fundamental shift toward system-level performance is redefining weapon design. This evolution prioritizes the integration of digital technologies and advanced materials, compelling manufacturers to move beyond standalone firearm development and toward complete, mission-oriented platforms.
Advanced fire control systems (FCS) integrate laser rangefinders and ballistic computers into a single sighting unit. Special operations forces and designated marksman units are the primary adopters, seeking to increase first-round hit probability at extended ranges. The integration of these functions is miniaturizing the engagement sequence, embedding complex calculations that were once done manually directly into the weapon's aiming process.
European Union directives like the Corporate Sustainability Reporting Directive (CSRD) are extending supply chain transparency requirements into the defense sector. This compels manufacturers to document the provenance of critical raw materials like tungsten and cobalt, which are often used in ammunition and weapon components. Defense firms operating in the EU are now investing in traceability systems to ensure compliance and maintain market access.
Military acquisition bodies are increasingly adopting a disaggregated sourcing model for small arms platforms. This approach moves away from single-vendor rifle contracts, allowing for separate procurement of best-in-class components like barrels, triggers, and handguards from different specialized manufacturers. This modular procurement strategy is most visible within US Special Operations Command and is now being emulated by several NATO allies.
Global Small Arms and Light Weapons (SALW) Market Segmentation
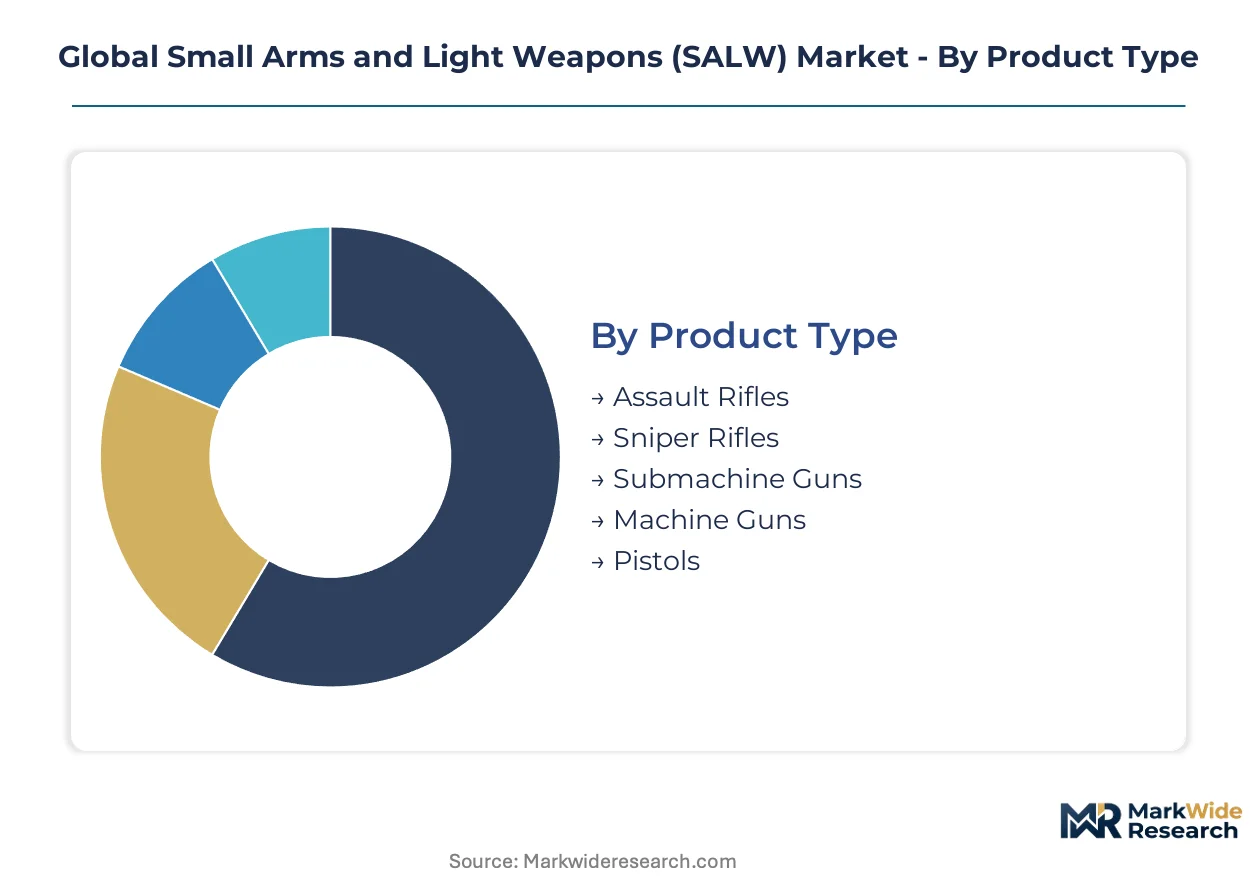
The Global Small Arms and Light Weapons (SALW) Market segmentation reveals distinct demand patterns and procurement drivers across various product types, end-users, applications, and deployment scenarios. Understanding these segments helps manufacturers tailor offerings to specific operational requirements and regulatory environments. Market dynamics vary significantly between military-grade systems and those designed for law enforcement agencies.
Product Type:
The threat of less-lethal alternatives and advanced surveillance technologies pressures the traditional market for certain product types, forcing manufacturers to innovate.
- Assault Rifles:These gas-operated or recoil-operated firearms are chambered for intermediate cartridges, providing a balance of range, rate of fire, and portability. Military forces globally, including India's defense modernization programs, drive substantial procurement for standard infantry equipment.
- Pistols:Handheld firearms, typically semi-automatic, designed for personal defense and close-quarters combat. Law enforcement agencies worldwide are upgrading their pistol fleets, often adopting advanced models with enhanced ergonomics and higher capacity magazines for greater tactical capability.
- Sniper Rifles:High-precision, long-range firearms designed for designated marksmen and special operations units. These weapons prioritize accuracy and range over sustained fire.
- Submachine Guns:Compact, automatic firearms chambered for pistol-caliber ammunition, favored for close-quarters battle and personal protection details. Paramilitary units and specialized police forces utilize these weapons for urban combat.
- Machine Guns:Fully automatic firearms providing sustained suppressive fire, typically crew-served or vehicle-mounted for area denial. Military forces deploy these weapons in various support roles.
Assault Rifles anchors the volume base while Pistols gains share at the steepest rate.
End User:
Customer-specific procurement models dictate design and volume requirements across the end-user landscape.
- Military Forces:National armies and defense establishments acquire a wide range of SALW for combat operations, training, and border security. These forces prioritize ruggedness, reliability, and interoperability with existing weapon systems.
- Law Enforcement:Police departments and federal agencies procure pistols, carbines, and patrol rifles for public order maintenance and critical incident response. Modernization programs emphasize advanced features and enhanced tactical capabilities.
- Paramilitary Units:Specialized armed forces operating alongside or in support of military or law enforcement, often engaged in internal security or counter-insurgency. These units require robust and adaptable weapon systems.
- Security Contractors:Private military and security companies provide armed protection and support services in complex environments. Their procurement often mirrors military or law enforcement standards.
- Peacekeeping Troops:International forces deployed to maintain peace and security in conflict zones. These troops require reliable and standardized small arms for self-defense and mission execution.
Procurement by Military Forces drives significant volume, while Law Enforcement represents a specialized but growing demand.
Application:
The primary purpose of small arms and light weapons defines the volume distribution across various operational applications.
- Combat Operations:Direct engagement of enemy forces in conventional and unconventional warfare scenarios. This application demands high lethality, reliability, and modularity from weapon systems.
- Border Control:Securing national borders against illegal crossings, smuggling, and incursions. India's extensive border security requirements generate substantial demand for modern small arms in this application.
- Counterterrorism:Specialized operations aimed at neutralizing terrorist threats and cells. This application requires highly accurate and adaptable weapon platforms for close-quarters and precision engagements.
- Defense Training:Instruction and practice for military and law enforcement personnel in weapon handling, marksmanship, and tactical procedures. This application drives demand for training variants and ammunition.
- Tactical Missions:Diverse operational tasks including reconnaissance, special insertions, and target interdiction. These missions often require customized weapon configurations and integrated systems.
The necessity of Combat Operations remains foundational, with Border Control seeing increased strategic importance.
Deployment:
Specialized tactical roles and unit structures influence the specific weapon configurations required for effective deployment.
- Infantry Units:Standard ground combat forces forming the backbone of military operations. These units deploy a wide array of assault rifles, machine guns, and pistols.
- Special Operations:Elite military units trained for unconventional warfare, direct action, and special reconnaissance. These forces demand highly modular and technologically advanced weapon systems.
- Urban Warfare Teams:Specialized units operating in densely populated areas, requiring compact and maneuverable weapon systems. Submachine guns and short-barreled rifles are common for these teams.
- Airborne Forces:Troops deployed by parachute or air assault, prioritizing lightweight and compact weapon systems for mobility. These forces require durable and easily transportable firearms.
- Naval Infantry:Marine forces operating in amphibious environments, demanding corrosion-resistant and robust weapon systems. Their equipment must withstand harsh maritime conditions.
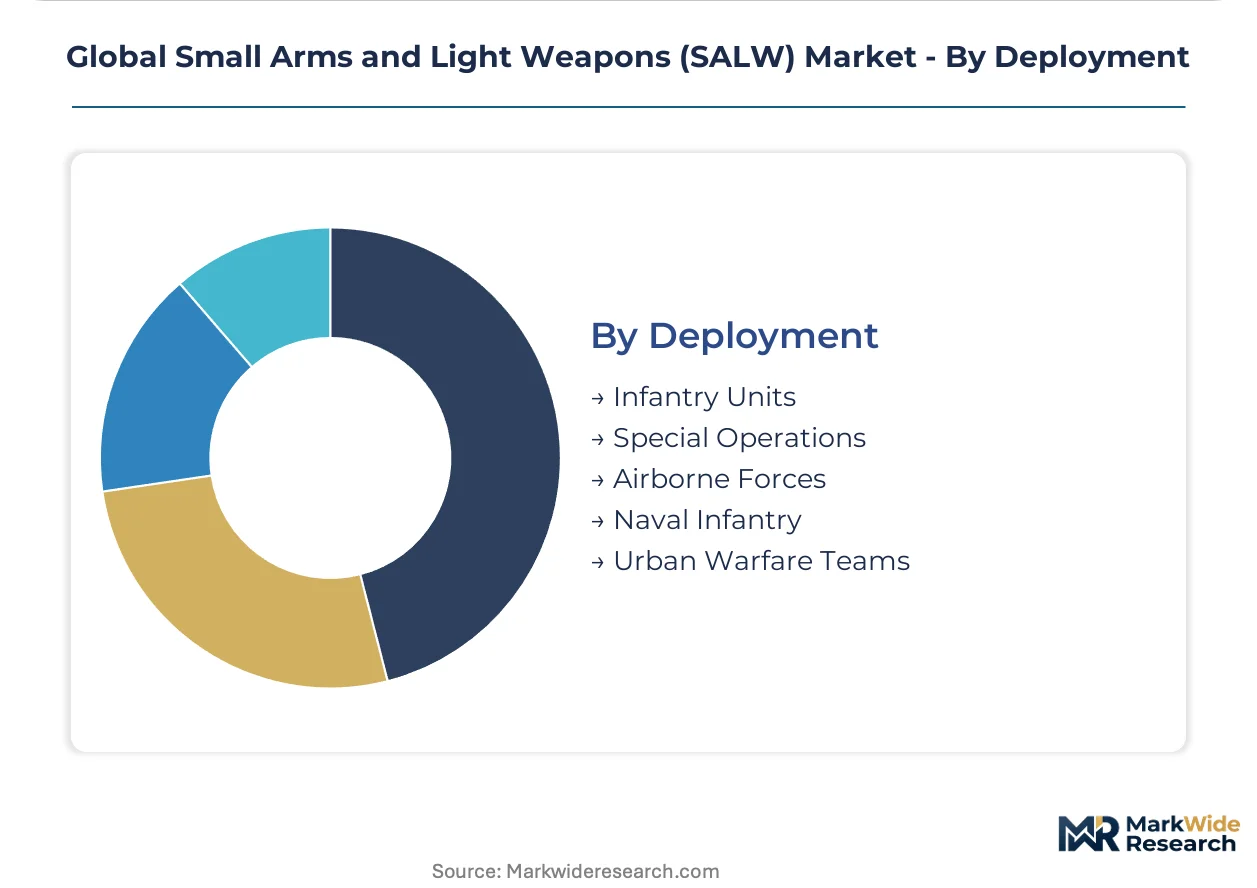
Broad deployment within Infantry Units ensures consistent demand, as Special Operations drives innovation in weapon system capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global SALW market exhibits varying demand elasticity across regions. Military forces in established defense markets often prioritize performance and interoperability over cost. Emerging defense markets balance capability with budget constraints, while law enforcement seeks advanced features within defined fiscal limits.
United States
United States demand stems from extensive military procurement cycles and ongoing law enforcement equipment upgrades. The Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) enforces strict domestic manufacturing and sales regulations. Springfield, Massachusetts, maintains a historical concentration of small arms manufacturing, driving innovation in weapon systems.
India
India's market is characterized by substantial defense modernization programs and critical border security requirements. The PLI scheme actively supports domestic manufacturing capabilities for defense equipment. Ordnance Factory Board facilities, including those near Kanpur, serve as key production hubs for military-grade small arms.
Germany
Germany sees consistent demand from its military for advanced infantry weapons and from police forces for high-performance pistols. The nation adheres to stringent export controls, shaped by the Wassenaar Arrangement. The Baden-Württemberg region, particularly Oberndorf am Neckar, forms a core hub for precision small arms manufacturing.
France
France's military procures modern small arms for its expeditionary forces, alongside upgrades for national gendarmerie units. French defense policy emphasizes domestic sourcing to ensure strategic autonomy. The historic Saint-Étienne region continues its legacy as a significant center for arms manufacturing and design.
United Kingdom
United Kingdom forces require enhanced lethality and modularity in their infantry weapons, with special forces driving innovation. The UK operates a robust export licensing regime, governing international military equipment transfers. Defense contractors in the South East of England concentrate on small arms research, development, and system integration.
Global Small Arms and Light Weapons (SALW) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the SALW market. The industry structure is tiered, reflecting a spectrum from large, diversified defense conglomerates to highly specialized small arms manufacturers. Strategic archetypes include established global players offering comprehensive systems, niche innovators focusing on advanced materials or integrated electronics, and emerging regional producers building domestic capabilities. Dominant competitive moves involve strategic partnerships for technology transfer and continuous portfolio diversification to meet evolving military and law enforcement requirements.
Among established global players, SIG Sauer Inc. exemplifies integrated weapon systems development, combining firearms with advanced optics and suppressors for enhanced user capability. German-based Heckler & Koch GmbH leverages its deep engineering expertise in polymer and metal manufacturing, consistently meeting stringent MIL-SPEC+ performance standards for both military and law enforcement clients. General Dynamics Corp, a US-based entity, occupies a significant position in the crew-served light weapons segment, benefiting from its extensive production scale and long-standing government contracts. These companies collectively anchor significant market segments through their distinct operational and technological strengths, influencing broader industry benchmarks.
| Leading Market Players |
|---|
| SIG Sauer Inc. |
| FN Herstal SA |
| Smith & Wesson Brands Inc. |
| Colt’s Manufacturing Company LLC |
| Beretta S.p.A. |
| Sturm, Ruger & Co. |
| Heckler & Koch GmbH |
| GLOCK Gesellschaft m.b.H. |
| General Dynamics Corp |
| Others |
Cost & Logistics Intelligence
Lengthy certification cycles for new weapon designs influence pricing power, directly impacting the supply chain's ability to respond to demand fluctuations for advanced small arms and light weapons. This dynamic links manufacturing lead times to market competitiveness.
Pricing Analysis
After-sales support for modular weapon systems constitutes a significant revenue tier, complementing initial weapon sales. The dominant pricing model for military forces involves contract-based long-term offtake agreements, while law enforcement often utilizes per-unit transactional purchases. Price differentiation stems from MIL-SPEC+ compliance and the integration of advanced fire control systems. Pricing pressure arises from price volatility for high-strength steel alloys and specialized polymers. Law enforcement agencies typically exhibit higher price sensitivity compared to special operations units prioritizing performance.
Supply Chain Analysis
Qualification of specialized component suppliers represents a critical chokepoint within the small arms and light weapons supply chain. Geographic supply concentration includes manufacturing hubs in Germany, the United States, and India. The industry relies heavily on high-strength steel alloys, specialized polymers, and advanced optical components. Supply chain risk primarily involves the lengthy and complex qualification process for new component suppliers. Distribution for military and law enforcement end-users primarily occurs through direct government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Small Arms and Light Weapons market is undergoing a platform-economics inflection, driven by the increasing demand for integrated weapon systems ecosystems that combine firearms with advanced digital technologies.
For Market Incumbents: Shield against niche innovators by doubling down on system integration and modular platform development. Invest heavily in R&D for advanced fire control systems to maintain performance leadership against emerging digital threats. Expanding manufacturing capacity in key strategic geographies through technology transfer agreements will mitigate export control complexities. Continuous investment in MIL-SPEC+ certification ensures compliance with stringent global performance standards.
For New Entrants and Emerging Players: Service-layer gaps in integrated fire control maintenance and specialized ammunition logistics offer penetrable entry points. Target emerging defense markets in Southeast Asia and Eastern Europe, where domestic production capabilities are actively being built. A strategic go-to-market angle involves forming joint ventures with local manufacturers for licensed production, leveraging regional demand for modern assault rifles and carbines.
For Investors and Strategic Acquirers: Carve-out targets emerge from large defense conglomerates seeking to divest non-core small arms divisions or specialized component manufacturers. The market demonstrates long-term viability given ongoing global defense modernization programs and persistent border security requirements. A key signal to watch for inflection is increased merger and acquisition activity focused on firms specializing in advanced materials or integrated electronics for weapon systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Enhances mission flexibility for military forces globally. |
| Integrated Fire Control R&D | Increases first-round hit probability for special operations units. |
| Technology Transfer Agreements | Facilitates domestic production in emerging defense markets. |
| MIL-SPEC+ Certification Investment | Meets stringent performance standards for law enforcement agencies. |
| Specialized Counter-UAS Weaponry | Addresses a new niche market for drone neutralization capabilities. |
Research Approach
The analysis maps small arms and light weapons sub-sectors, each validated through primary interviews with military procurement officers, law enforcement tactical unit leaders, defense R&D engineers, and export control specialists. Secondary data sources, including UN Programme of Action reports, Wassenaar Arrangement documents, national defense budgets, and company annual reports, provided additional validation. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Consistency checks against national defense spending outlooks and published procurement plans informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end-user, application, deployment, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected demand drivers like India's defense modernization. Defense spending forecasts and law enforcement modernization budgets served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in UNPoA and Wassenaar Arrangement frameworks; material policy shifts would require re-modeling. This analysis acknowledges that geopolitical instability, new export control regimes, and rapid technological disruption are specific risk factors. Practitioners should keep alternative scenarios live as geopolitical tensions and defense budgets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Middle East and Africa Ammunition Market