
 Aircraft Sequencing System Market | 2026-2036
Aircraft Sequencing System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Sequencing System Market Analysis
A capability gap between full-stack avionics integrators and software-focused sequencing specialists is redrawing competitive boundaries in the aircraft sequencing system space. Thales Group leverages its vertically integrated sensor-to-display architecture to dominate European airport retrofit programs. L3Harris Technologies anchors its position through deep relationships with FAA modernization contracts, while Frequentis AG specializes in voice-communication-integrated sequencing platforms for mid-tier air navigation service providers.
An aircraft sequencing system coordinates the temporal and spatial ordering of aircraft movements across arrival, departure, and surface operations using algorithms that process flight plans, weather data, and real-time surveillance feeds to optimize runway throughput and minimize fuel burn. These systems typically operate within 15-second update cycles and integrate with surface movement radar and ADS-B transponder networks to maintain safe separation standards. Traffic Management Systems command the largest installed base among product categories, while AI Solutions within the technology dimension are capturing disproportionate R&D investment as operators seek predictive delay mitigation. Ground Control Systems retain stable replacement demand from military end users requiring hardened, sovereign infrastructure.
The FAA mandates NextGen performance standards for all new sequencing deployments in US airspace, while EASA's regulatory framework governs European interoperability requirements through its Single European Sky initiative. Military procurement across NATO member states follows STANAG 4586 protocols for unmanned systems integration, creating a parallel certification pathway for defense-oriented sequencing platforms. Stakeholders must weigh the capital requirements of cloud-native architectures against the operational continuity demands of on-premise deployments as procurement criteria evolve.
Market Dynamics
The FAA's NextGen modernization mandate is compressing replacement cycles for radar-based air traffic infrastructure, forcing airport authorities and air navigation service providers to reallocate capital toward satellite-dependent trajectory management platforms that optimize runway throughput and gate turnaround efficiency.
Growth Catalysts
- NextGen Performance Standards:The FAA mandates satellite-based surveillance and data-sharing protocols for all new sequencing deployments in US airspace, accelerating procurement of integrated arrival and departure scheduling systems at hub airports.
- Surface Congestion Mitigation:Airport authorities in Atlanta, Chicago, and Dallas are deploying AI-enhanced sequencing platforms to manage rising domestic and international traffic volumes and reduce tarmac delays.
- Single European Sky Interoperability:EASA's regulatory framework governs European airspace integration requirements, driving cross-border standardization of sequencing algorithms and surveillance feed protocols.
Market Restraints
- Legacy System Interoperability Costs:Proprietary data formats in existing radar-based infrastructure create expensive middleware requirements for satellite-dependent sequencing upgrades.
- Semiconductor Supply Concentration:Specialized FPGA and ASIC components for real-time signal processing face sourcing constraints from concentrated East Asian foundry capacity.
- Certification Timeline Friction:FAA airworthiness certification for safety-critical software updates extends deployment schedules by 18-36 months beyond hardware installation.
Strategic Opportunities
- Mid-Tier Airport Digitization:Secondary airports in India and Southeast Asia lack sequencing infrastructure entirely, creating greenfield deployment opportunities for cloud-native platforms.
- Unmanned Systems Integration:NATO STANAG 4586 protocols for military drone coordination are creating parallel certification pathways for defense-oriented sequencing modules.
- Voice-Communication Convergence:Integration of digital voice switching with sequencing algorithms opens new product categories for air navigation service providers managing mixed legacy-digital environments.
Industry Challenges
- Real-Time Systems Engineering Talent Scarcity:The specialized skill set combining avionics safety standards with machine learning pipeline development commands premium compensation and extends hiring timelines.
- Operational Continuity Requirements:Air traffic control systems demand 99.999% uptime, forcing redundant on-premise architectures that conflict with cloud-native cost optimization roadmaps.
- Multi-Stakeholder Data Sovereignty:Military, civilian, and private airport operators impose conflicting classification and access protocols on shared airspace surveillance feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Sequencing System Market |
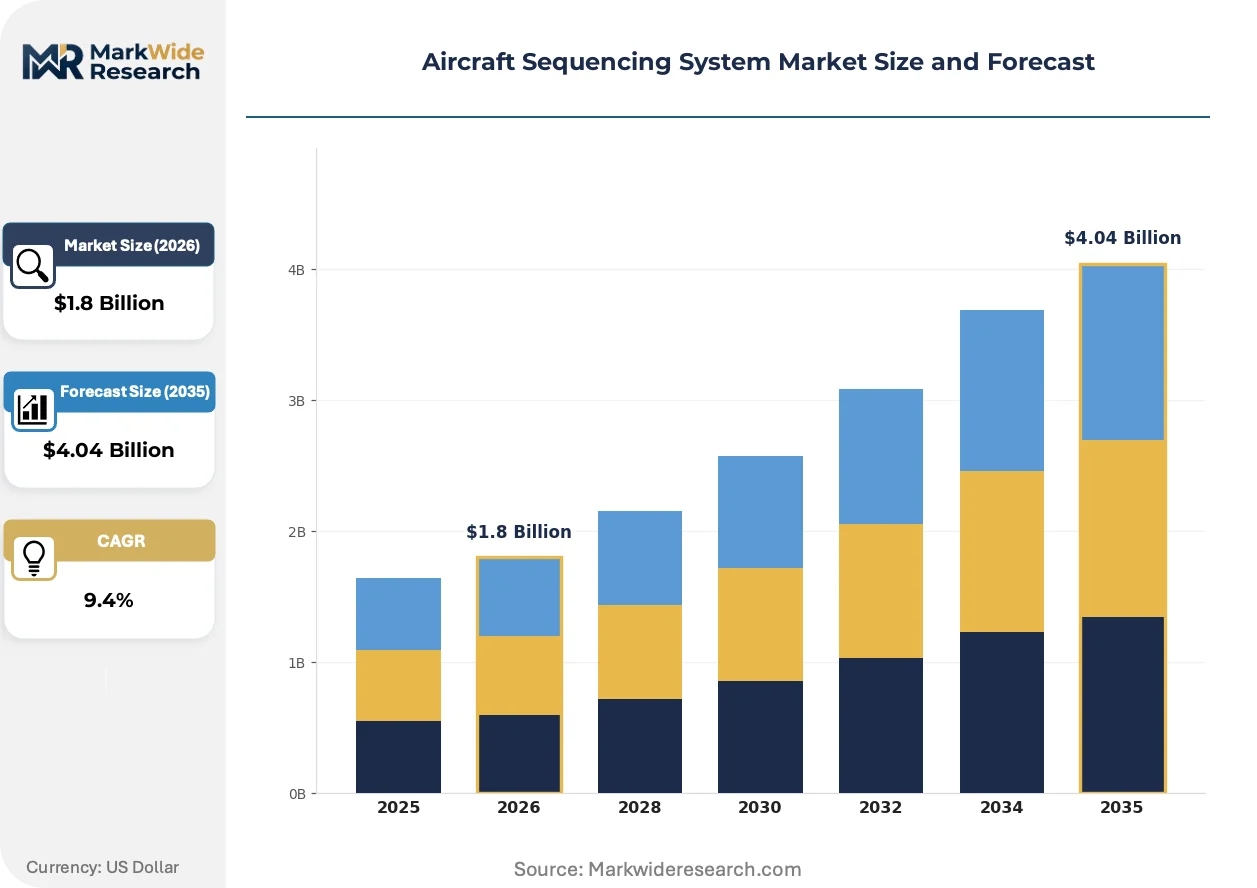
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
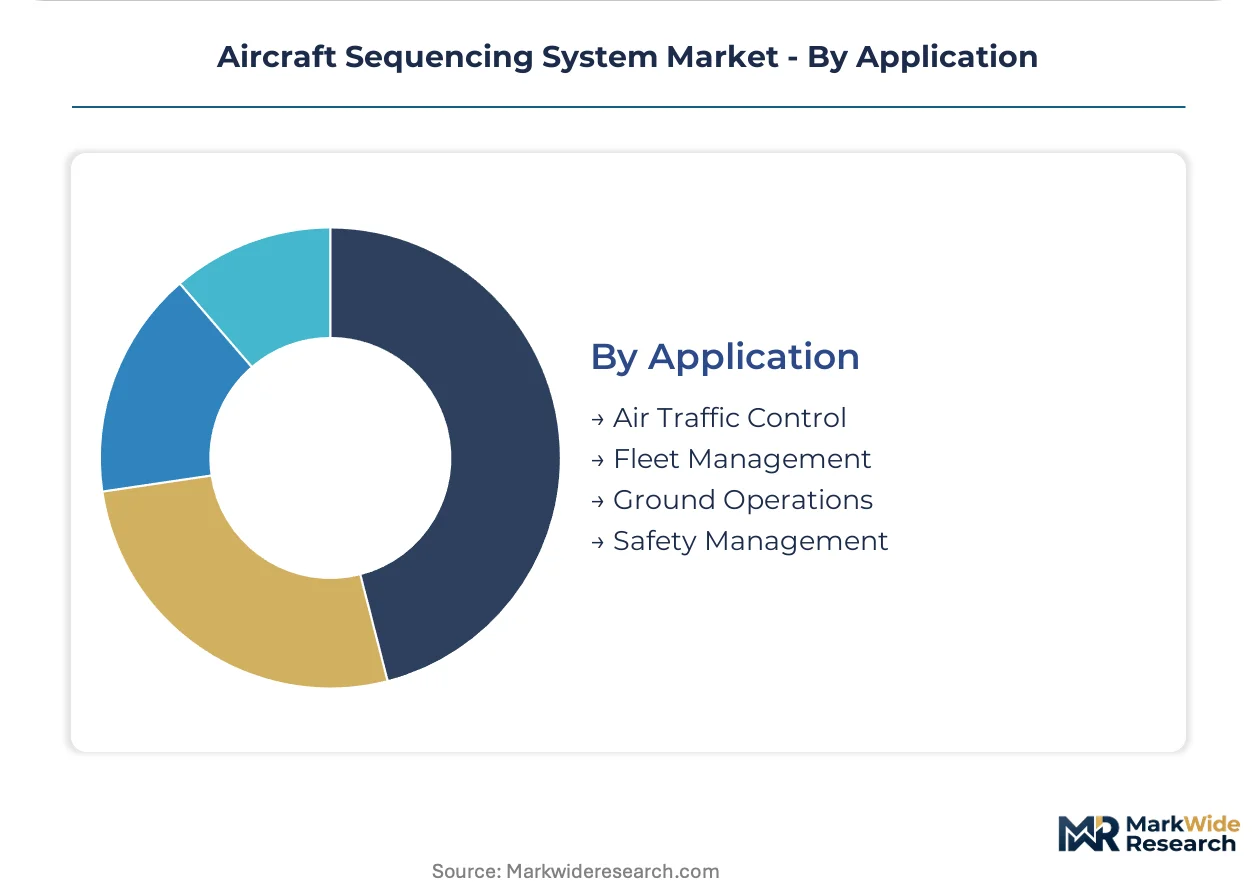
| Segmentation | Product Type: Ground Control Systems, Flight Management Systems, Traffic Management Systems, Automation Tools End User: Airlines, Airport Authorities, Military, Private Operators Technology: AI Solutions, Cloud-Based Platforms, IoT Integration, Data Analytics Application: Air Traffic Control, Fleet Management, Ground Operations, Safety Management |
| Companies Covered | Thales Group, Indra Sistemas, L3Harris Technologies, Collins Aerospace, Saab AB, Leonardo, Honeywell International, Raytheon Technologies, Frequentis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Sequencing System Market Emerging Trajectories
Algorithmic decision-support tools are fragmenting traditional hardware-centric competitive boundaries, as software specialists capture value previously held by full-stack avionics integrators through modular, API-first sequencing platforms.
Machine learning-based predictive delay models are fragmenting conventional rule-based sequencing architectures. These systems ingest weather radar, airline operational data, and historical traffic patterns to generate probabilistic arrival time forecasts. Major hub airports in the United States are piloting these platforms for 15-second update cycle optimization. The technology is fragmenting procurement patterns by separating algorithm licensing from sensor hardware contracts.
The EU AI Act's risk classification framework for safety-critical artificial intelligence is reshaping European sequencing system development pathways. High-risk system designations impose mandatory human oversight, data governance, and transparency requirements on automated arrival scheduling. European air navigation service providers are responding by segmenting product portfolios into assistive decision-support and full-automation tiers to manage compliance scope.
Airport authorities are unbundling long-term sequencing system contracts into discrete software subscription and hardware lease components. This procurement model shift disrupts traditional ten-year integrated system sales by enabling mid-cycle capability upgrades without full platform replacement. The transformation is most visible in United States hub airports where FAA modernization funding flows through separate capital and operational expenditure channels.
Aircraft Sequencing System Market Segmentation
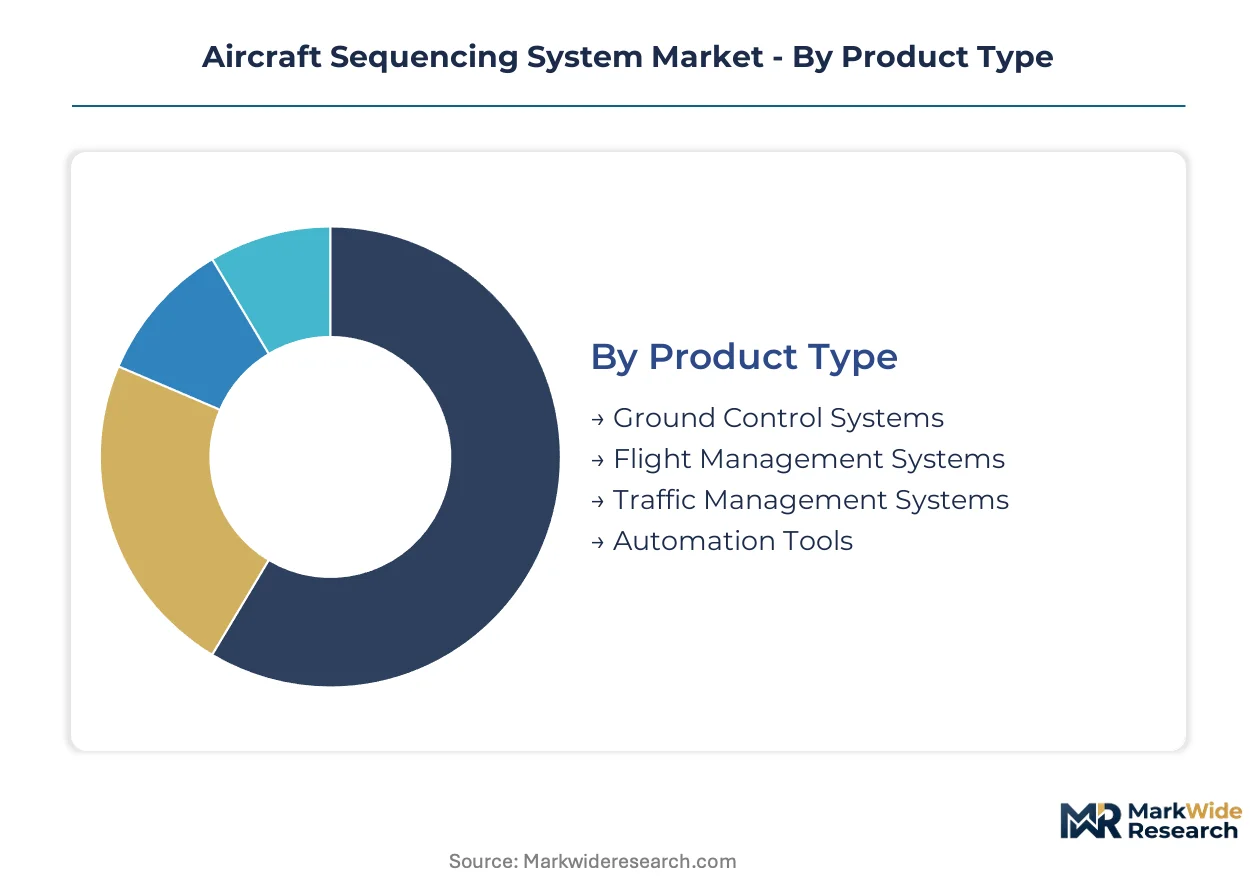
Sequencing system procurement patterns diverge sharply across operational contexts, with military end users prioritizing sovereign infrastructure while commercial airports optimize for throughput metrics. Technology architecture choices—on-premise versus cloud-native—further fragment vendor selection criteria across these segments.
Product Type:
Margin pools concentrate in integrated platforms that bundle hardware, software, and maintenance contracts, though modular procurement is eroding this structure at mid-tier airports.
- Traffic Management Systems:These platforms coordinate arrival and departure scheduling across multiple runways using real-time surveillance feeds and flight plan data. Hub airports in Atlanta and Chicago are deploying these systems to manage rising domestic traffic volumes under FAA NextGen mandates. The dominant share belongs to Traffic Management Systems, while Automation Tools is closing the gap fastest.
- Ground Control Systems:Surface movement management platforms integrate with radar and ADS-B networks to maintain safe separation during taxi operations. Military end users across NATO member states drive stable replacement demand for hardened, sovereign infrastructure meeting STANAG 4586 protocols.
- Flight Management Systems:Onboard trajectory optimization modules interface with ground-based sequencing platforms through datalink protocols.
- Automation Tools:Algorithmic decision-support components enable predictive delay mitigation and dynamic runway allocation.
Procurement concentration in Traffic Management Systems reflects hub airport modernization cycles, though Automation Tools vendors are capturing disproportionate R&D investment.
End User:
Application requirements vary dramatically by operational mission, with airlines prioritizing fuel burn reduction while airport authorities optimize gate turnaround efficiency.
- Airport Authorities:Public and quasi-public entities managing hub and regional facilities deploy sequencing platforms to reduce tarmac congestion and improve passenger throughput. Dallas-Fort Worth and Chicago O'Hare represent significant deployment sites under FAA modernization funding flows. Airport Authorities command the largest installed base, though Military procurement is expanding most quickly.
- Military:Defense-oriented operators require hardened infrastructure with sovereign data governance and unmanned systems integration capabilities. NATO STANAG 4586 protocols create parallel certification pathways distinct from civilian FAA or EASA frameworks.
- Airlines:Carriers leverage sequencing data for fuel optimization and crew scheduling integration.
- Private Operators:Corporate aviation and charter services adopt lighter, cloud-native platforms for fixed-base operations.
Airport Authorities dominate current procurement volumes, though Military segments show steepest expansion trajectory driven by drone coordination requirements.
Technology:
Architecture choices determine total cost of ownership, with cloud-native platforms offering operational flexibility against on-premise systems' continuity guarantees.
- AI Solutions:Machine learning pipelines ingest weather radar, airline operational data, and historical traffic patterns to generate probabilistic arrival forecasts. Major United States hub airports pilot these platforms for 15-second update cycle optimization. AI Solutions attracts the heaviest R&D allocation, while Cloud-Based Platforms is gaining adoption fastest.
- Cloud-Based Platforms:Subscription-model deployments enable mid-cycle capability upgrades without full platform replacement. Secondary airports in India and Southeast Asia represent greenfield opportunities lacking legacy infrastructure constraints.
- IoT Integration:Sensor networks feed real-time aircraft position and environmental data into sequencing algorithms.
- Data Analytics:Retrospective performance analysis tools support regulatory reporting and operational improvement initiatives.
AI Solutions captures disproportionate vendor investment, though Cloud-Based Platforms is climbing the fastest as procurement unbundles hardware from software contracts.
Application:
Functional scope determines integration complexity, with air traffic control requiring safety-critical certification while fleet management emphasizes interoperability.
- Air Traffic Control:Safety-critical sequencing platforms demand 99.999% uptime and redundant architectures certified under FAA or EASA frameworks. The EU AI Act's high-risk system designation imposes mandatory human oversight requirements on automated arrival scheduling in European airspace. Air Traffic Control retains the deepest installed base, though Fleet Management is expanding most rapidly.
- Ground Operations:Surface movement coordination integrates with gate management and baggage handling systems.
- Fleet Management:Airline-centric platforms optimize aircraft routing and crew pairing across hub-and-spoke networks.
- Safety Management:Incident prevention and risk mitigation modules support regulatory compliance and insurance requirements.
Air Traffic Control maintains dominant deployment share, though Fleet Management is gaining share fastest as airlines seek operational data integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States airport authorities face compressed procurement timelines under FAA mandates with limited price negotiation leverage, while secondary airports in India and Southeast Asia exhibit high price sensitivity and extended vendor evaluation cycles.
United States
Hub airports in Atlanta, Chicago, and Dallas drive concentrated procurement volumes for integrated arrival and departure scheduling systems. The FAA's NextGen modernization mandate accelerates replacement of radar-based infrastructure with satellite-dependent trajectory management platforms. Dallas-Fort Worth International Airport represents a significant deployment site where AI-enhanced sequencing platforms manage rising domestic and international traffic volumes.
Germany
Frankfurt and Munich airports anchor European demand for voice-communication-integrated sequencing platforms serving dense continental airspace. EASA's Single European Sky initiative governs cross-border standardization requirements for sequencing algorithms and surveillance feed protocols. The country's national aviation regulator enforces interoperability standards that shape procurement specifications for mid-tier air navigation service providers.
United Kingdom
Heathrow and Gatwick airports prioritize surface congestion mitigation through predictive delay modeling and dynamic runway allocation systems. The country's civil aviation authority aligns certification requirements with EU AI Act risk classifications for safety-critical automated scheduling. London's hub airports are piloting machine learning-based probabilistic arrival time forecasts within 15-second update cycles.
France
Paris Charles de Gaulle and Orly airports deploy sequencing infrastructure optimized for high-density mixed-traffic operations across Schengen and non-Schengen flows. The country's national aviation safety authority implements EASA framework requirements for high-risk AI system designations with mandatory human oversight. Thales Group leverages its vertically integrated sensor-to-display architecture to dominate domestic airport retrofit programs.
India
Secondary airports in Mumbai, Delhi, and Bangalore lack legacy sequencing infrastructure entirely, creating greenfield deployment opportunities for cloud-native platforms. The country's Directorate General of Civil Aviation establishes certification pathways for imported safety-critical avionics systems. Indira Gandhi International Airport represents an emerging concentration where subscription-model procurement enables mid-cycle capability upgrades without full platform replacement.
Aircraft Sequencing System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the aircraft sequencing system space. Full-stack avionics integrators compete against software-focused sequencing specialists through divergent technology architectures. Three archetypes dominate: vertically integrated sensor-to-display providers, FAA-contract-anchored defense-electronics conglomerates, and voice-communication-integrated platform specialists. Competitive moves concentrate on strategic partnerships for cloud-native capability expansion and portfolio diversification into unmanned systems integration modules.
Within the integrated-systems tier, Thales Group and L3Harris Technologies exemplify contrasting geographic anchoring strategies. Thales occupies a position representing European vertically integrated architecture dominance, while L3Harris sits within the specialist tier of FAA modernization contract holders. Frequentis AG represents the voice-communication convergence archetype, anchoring positioning for mid-tier air navigation service providers managing mixed legacy-digital environments.
| Leading Market Players |
|---|
| Thales Group |
| Indra Sistemas |
| L3Harris Technologies |
| Collins Aerospace |
| Saab AB |
| Leonardo |
| Honeywell International |
| Raytheon Technologies |
| Frequentis AG |
| Others |
Supply Flow & Price Mechanics
Satellite-dependent trajectory management platforms displacing radar-based infrastructure simultaneously concentrate procurement leverage with FAA-contract holders and compress pricing premiums for legacy hardware vendors. This substitution dynamic redistributes margin pools toward software licensing and recurring service contracts while stranding proprietary radar component inventories.
Pricing Analysis
Extended service and software maintenance contracts generate lifetime value exceeding initial system deployment revenue. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and integration complexity, with airport authorities in Atlanta and Dallas showing lowest price sensitivity due to FAA modernization funding availability. Cost compression in mid-tier airport segments intensifies because cloud-native entrants unbundle hardware-software contracts. Military end users exhibit least price sensitivity due to sovereign infrastructure mandates.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for specialized FPGA and ASIC components sourced from Taiwan, South Korea, and Japan. Real-time signal processing hardware draws from concentrated East Asian foundry capacity, with ADS-B transponder modules and surface movement radar arrays feeding from US and European defense-electronics suppliers. Single-source vulnerability in semiconductor fabrication creates procurement risk for 15-second update cycle systems. Distribution runs through direct OEM relationships with airport authorities and military procurement offices, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce combinations of avionics safety certification expertise and machine learning pipeline engineering, creating acute talent competition between full-stack integrators and modular software specialists.
For Market Incumbents: Consolidate around FAA NextGen contract anchoring and voice-communication integration capabilities to defend against modular API-first entrants. Deepen backward integration into sensor hardware production to capture margin pools eroding at the software layer. Lock in ten-year service contracts with airport authorities before procurement unbundling accelerates. For New Entrants and Emerging Players: Differentiate on cloud-native deployment speed and subscription-model flexibility to penetrate secondary airports in India and Southeast Asia lacking legacy infrastructure. Target mid-tier air navigation service providers managing mixed legacy-digital environments with voice-communication convergence modules. Lead with pilot-to-production timelines under 18 months versus incumbent certification cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed voice-communication platform specialists holding Frequentis-like positioning in European mid-tier markets. Five-to-ten-year viability hinges on unmanned systems integration capabilities under NATO STANAG 4586 protocols. Watch for EU AI Act high-risk system designations triggering mandatory human oversight requirements as inflection indicator for automation tier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Unmanned Systems Integration Module Development | STANAG 4586 protocol compliance opens parallel defense certification pathways beyond FAA frameworks. |
| Cloud-Native Platform Migration | Subscription-model procurement at Indira Gandhi International Airport demonstrates mid-cycle upgrade viability. |
| Voice-Communication Convergence Partnership | Frequentis AG's positioning shows value capture potential in mixed legacy-digital airspace environments. |
| AI-Enhanced Predictive Delay Licensing | Machine learning algorithm separation from sensor hardware contracts fragments traditional integrated-system pricing. |
| Secondary Airport Greenfield Deployment | Absence of legacy radar infrastructure in Mumbai and Bangalore eliminates middleware interoperability costs. |
Methodological Framework
Cross-validation between FAA procurement disclosure databases and EASA Single European Sky implementation reports anchors the qualitative findings. Primary interviews with air traffic control system engineers, airport authority procurement directors, ANSP operations managers, and defense electronics program officers combined with secondary validation against customs records, SEC 10-K filings, and NATO standardization documents. Bottom-up deployment tracking at named hub airports triangulates against top-down regulatory mandate timelines.
Sensitivity analysis around semiconductor supply constraints and certification timeline friction shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology architecture, and application scope, with additional granularity on sovereign versus commercial data governance requirements. CAGRs derive from installation base replacement cycles and greenfield penetration rates, incorporating NextGen mandate compliance deadlines and EU AI Act implementation phases as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FAA modernization funding flows or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect assumptions on semiconductor supply normalization and certification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Ailerons Market
Aircraft
Flight Management Systems Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Electric Aircraft Market
Aircraft
Winglets Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Global Business Aircraft Market
Aircraft
Global Business Jets Market
Aircraft
Evtol Aircraft Market
Aircraft
Freighter Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Firefighting Aircraft Market