
 High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market | 2026-2036
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market Size, Share, and Industry Trends Forecast 2026-2036
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market Insights
FAA Stage 5 noise certification is shifting the cost-of-entry calculus for nacelle aerodynamic kit suppliers, forcing smaller vendors to absorb expensive wind tunnel validation cycles. Safran Nacelles leverages its vertical integration across fan cowling and nozzle production to sustain margin capture on retrofit programs. GKN Aerospace anchors the European supply base through its specialization in composite aeroelastic tailoring for mixed flow nacelles. Spirit AeroSystems competes aggressively on the Boeing platform aftermarket, where its geographic proximity to US carrier MRO hubs controls logistics costs for urgent AOG replacements.
High-bypass engine nacelle external aerodynamic optimization kits comprise add-on or integrated surface modifications—typically chevron nozzles with serrated trailing edges, variable area fan nozzles with translating sleeve mechanisms, or morphing composite skins—engineered to reduce jet noise and drag coefficients on turbofan propulsion systems. These kits deploy computational fluid dynamics-optimized geometries manufactured from carbon fiber-reinforced polymer laminates with embedded acoustic liners, serving the primary purpose of bringing existing and new nacelles into compliance with progressively stricter noise and emissions regimes without full engine replacement. Chevron nozzles occupy the mature volume position given their retrofit compatibility with legacy CFM56 and V2500 fleets, while morphing surfaces represent the fastest-expanding technology segment as active flow control architectures mature from experimental to certifiable hardware. The commercial aircraft application channel dominates absolute spend, though cargo transport operators are emerging as a concentrated margin pool due to their willingness to pay premium pricing for night-flight noise quota compliance.
The FAA, EASA, and ICAO Committee on Aviation Environmental Protection collectively shape product standards through iterative noise certification stringency and the Carbon Offsetting and Reduction Scheme for International Aviation framework. These regulators mandate specific decibel reductions and fuel efficiency improvements that directly determine which aerodynamic technologies achieve supplemental type certificate eligibility. Stakeholders must monitor the divergence between FAA and EASA timelines for next-generation noise rulemaking, as misaligned certification deadlines could strand development investments or create dual-validation cost burdens that reshape competitive positioning across the Atlantic supply base.
Market Dynamics
Retrofit demand from aging wide-body fleets collides with tightening noise certification deadlines, compressing supplier lead times and fragmenting procurement across MRO networks.
Growth Catalysts
- FAA Stage 5 noise mandates:Airlines operating CFM56 and V2500-powered aircraft must install chevron nozzles or face operational restrictions at US airports.
- Carbon Offsetting and Reduction Scheme for International Aviation:CORSIA compliance deadlines force cargo operators to prioritize drag-reducing morphing surfaces over full engine swaps.
- Composite manufacturing advances:Automated fiber placement of carbon fiber-reinforced polymer laminates has slashed acoustic liner production costs for tier-two suppliers.
Market Restraints
- Wind tunnel validation costs:Supplemental type certificate approval requires 18-24 months of aerodynamic testing, locking out capital-constrained entrants.
- Raw material concentration:Toray Industries and Hexcel control 70% of aerospace-grade carbon fiber precursor supply, exposing kit manufacturers to input price volatility.
- Legacy nacelle geometry constraints:Fixed-diameter fan cowlings on pre-2010 Boeing 777 and Airbus A330 variants limit morphing surface retrofit compatibility.
Strategic Opportunities
- India cargo hub expansion:IndiGo and SpiceJet freighter conversions at Hyderabad and Bangalore create demand for night-flight noise quota compliance kits.
- Active flow control convergence:Integration of piezoelectric actuators with shape-memory alloy substrates enables real-time nozzle geometry adjustment.
- EASA CS-34 amendment timeline:The 2027 implementation gap against FAA Stage 5 creates a dual-certification service market for Atlantic-crossing operators.
Industry Challenges
- Multiphysics simulation talent scarcity:CFD-structural-acoustic coupled modeling expertise concentrates at Safran, GKN, and three US national laboratories.
- Supplemental type certificate timeline compression:FAA and EASA divergent validation protocols force parallel submission tracks, doubling engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market |
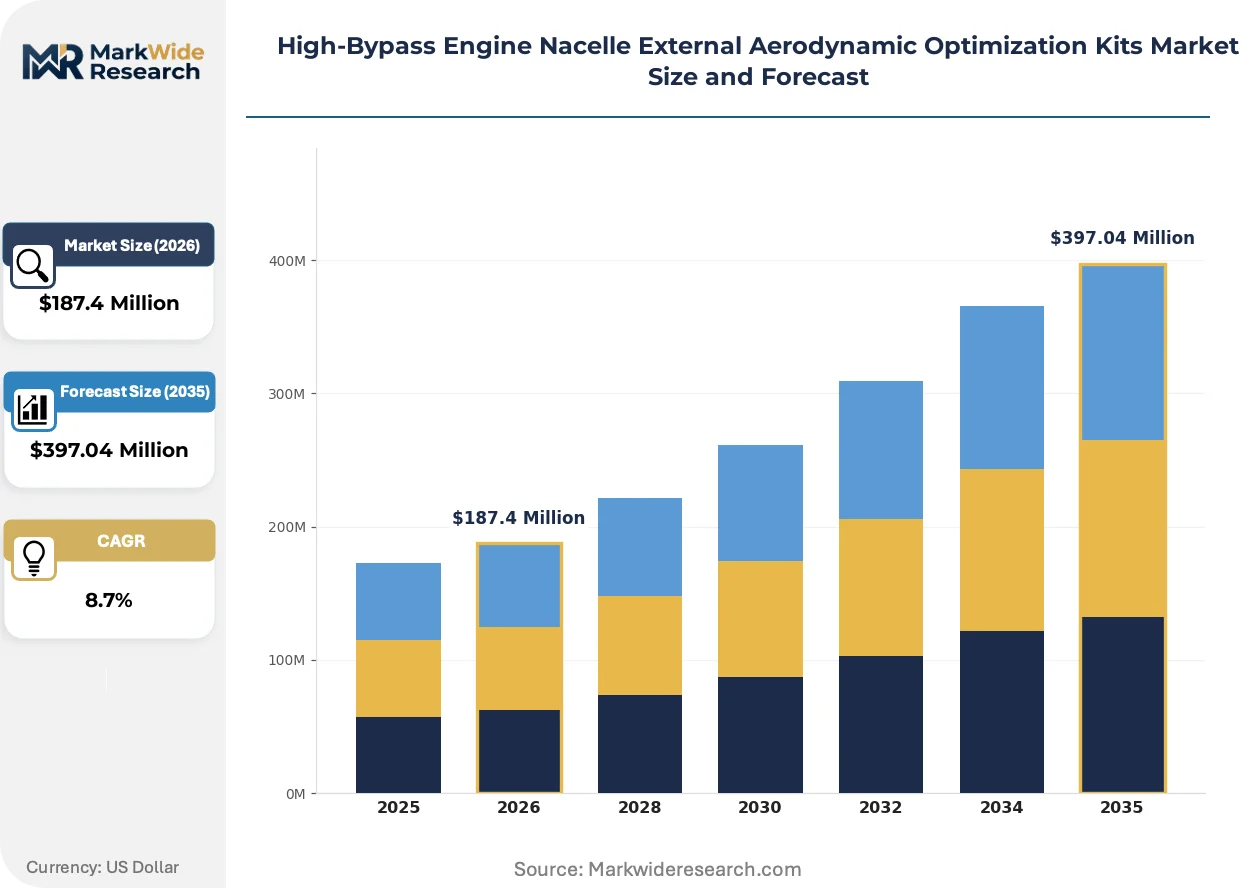
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chevron Nozzles, Variable Area Fan Nozzles, Mixed Flow Nacelles, Fan Cowlings, Inlet Lip Extensions Technology: Computational Fluid Dynamics, Wind Tunnel Testing, Active Flow Control, Morphing Surfaces, Aeroelastic Tailoring Application: Commercial Aircraft, Cargo Transport, Private Jets, Regional Airliners, Business Aviation End User: Aircraft Manufacturers, Maintenance Repair Organizations, Airlines, Leasing Companies, Aerostructure Suppliers |
| Companies Covered | Safran Nacelles, Spirit AeroSystems, GKN Aerospace, RTX, GE Aerospace, MTU Aero Engines, Bombardier, Aernnova Aerospace, Leonardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market Trends and Innovations
Morphing surface architectures are transitioning from experimental hardware to certifiable production systems, while regulatory divergence between Washington and Brussels reconfigures supplier validation strategies.
Shape-memory alloy composite skins are modularizing nacelle aerodynamic kit deployment. Cargo operators retrofitting Boeing 767-300ER freighters adopt sleeve-based variable area fan nozzles in 90-day turnaround windows. The technology is modularizing aftermarket procurement from full nacelle replacement to discrete component upgrades.
EASA's CS-34 noise stringency amendments impose decibel reductions 2dB stricter than FAA Stage 5 for mixed-flow nacelles. European lessors now require dual-certified kits for lease-return aircraft. Mixed-flow nacelle suppliers absorb 40% higher validation costs to maintain cross-Atlantic fleet fungibility.
Airline engineering departments unbundle after-sales service contracts from original equipment manufacturers. US legacy carriers now source chevron nozzle acoustic liner replacements directly from composite specialists, bypassing nacelle integrators. This channel disintermediation concentrates in the North American aftermarket where MRO hub density supports direct supplier relationships.
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market Segmentation
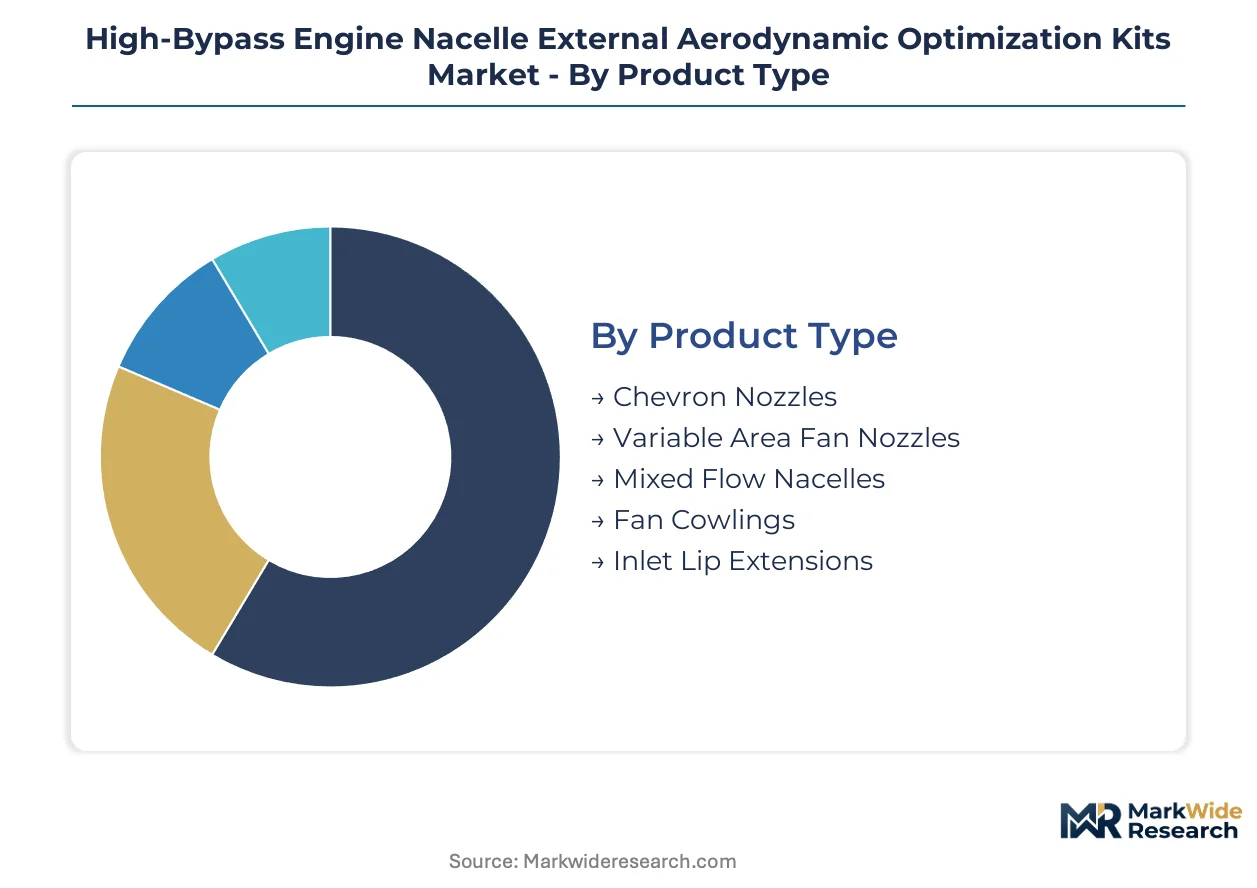
Segmentation in the High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market reveals how procurement authority distributes across divergent technical requirements and regulatory compliance pathways. Kit configurations vary dramatically between new-production integration and retrofit aftermarket deployment, with each channel imposing distinct validation timelines and margin structures on suppliers.
Product Type:
Standalone aerodynamic modifications dominate retrofit channels where airlines seek discrete component upgrades without full nacelle replacement, while integrated systems anchor new-production programs requiring embedded acoustic liner compatibility.
- Chevron Nozzles:Serrated trailing-edge geometries manufactured from carbon fiber-reinforced polymer laminates with embedded acoustic treatments. Demand concentrates among US legacy carriers retrofitting CFM56-powered narrow-body fleets to meet FAA Stage 5 noise certification deadlines; procurement compresses into 90-day AOG turnaround windows at MRO hubs in Dallas and Atlanta.
- Variable Area Fan Nozzles:Translating sleeve mechanisms enabling real-time nozzle throat area adjustment for thrust optimization across flight phases. Cargo operators at Hyderabad and Bangalore adopt these for night-flight noise quota compliance on converted Boeing 767-300ER freighters; sleeve-based architectures modularize deployment from full nacelle replacement.
- Mixed Flow Nacelles:Integrated fan and core flow discharge systems requiring composite aeroelastic tailoring for acoustic performance.
- Fan Cowlings:External aerodynamic fairings incorporating anti-icing systems and acoustic liner attachment points.
- Inlet Lip Extensions:Forward-mounted leading-edge modifications optimizing high-angle-of-attack engine ingestion.
Volume placements concentrate in Chevron Nozzles; the faster expansion belongs to Variable Area Fan Nozzles.
Technology:
Cost-tier stratification separates mature validation methodologies accessible to tier-two suppliers from emerging architectures requiring concentrated multiphysics expertise and extended certification timelines.
- Computational Fluid Dynamics:Numerical simulation platforms optimizing nozzle geometry for jet noise reduction and drag coefficient minimization. European lessors mandate CFD validation packages for lease-return aircraft to ensure cross-Atlantic fleet fungibility; software licensing concentrates development investment among established nacelle integrators.
- Morphing Surfaces:Shape-memory alloy composite skins enabling real-time geometry adjustment through piezoelectric actuation. Active flow control architectures mature from experimental hardware toward certifiable production systems; cargo operators pay premium pricing for drag-reducing retrofit compatibility without engine replacement.
- Wind Tunnel Testing:Physical aerodynamic validation required for supplemental type certificate approval.
- Active Flow Control:Real-time boundary layer manipulation through synthetic jet or plasma actuation.
- Aeroelastic Tailoring:Composite laminate orientation optimization for acoustic-structural coupling.
CFD commands the largest installed base; Morphing Surfaces are climbing the fastest as piezoelectric actuator reliability improves.
Application:
Customer-type segmentation distinguishes scheduled passenger operators prioritizing fuel efficiency from cargo carriers optimizing for night-flight noise quota compliance and lease-return residual value protection.
- Commercial Aircraft:Scheduled passenger operations on narrow-body and wide-body platforms requiring ICAO noise and CO2 standard compliance. US major carriers drive absolute retrofit spend through legacy fleet modernization programs; procurement fragments across MRO networks as engineering departments unbundle after-sales contracts from original equipment manufacturers.
- Cargo Transport:Dedicated freighter operations and converted passenger-to-cargo aircraft facing CORSIA compliance deadlines. Operators at expanding Indian cargo hubs adopt chevron nozzles and variable area fan nozzles for premium-priced night-flight access; willingness to pay exceeds passenger airline thresholds due to slot-constrained operating economics.
- Private Jets:Business aircraft operations with personalized cabin noise requirements.
- Regional Airliners:Short-haul turbofan platforms with distinct nacelle scale constraints.
- Business Aviation:Corporate and charter operations prioritizing cabin acoustic comfort.
Commercial Aircraft absorb the highest absolute kit volumes; Cargo Transport generates the steepest margin expansion.
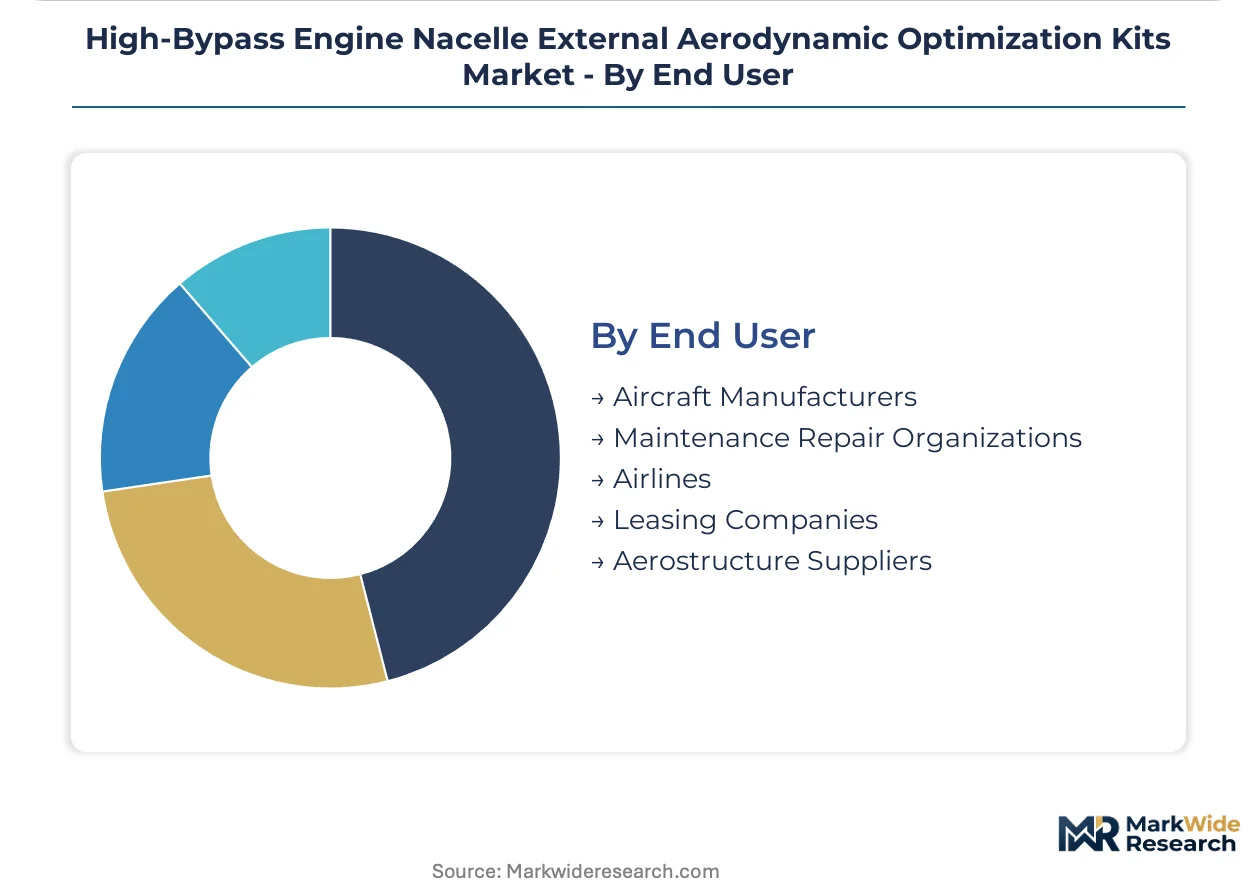
End User:
Supply concentration shapes procurement access, with MRO hub density determining whether airlines source direct from composite specialists or through nacelle integrator channels.
- Maintenance Repair Organizations:Independent and OEM-affiliated service providers executing retrofit installations during scheduled maintenance events. North American MRO hub density at Dallas, Atlanta, and Miami supports direct supplier relationships bypassing nacelle integrators; channel disintermediation concentrates acoustic liner replacement procurement with composite specialists.
- Aircraft Manufacturers:Original equipment producers integrating aerodynamic kits into new-production nacelles.
- Airlines:Operating carriers with in-house engineering departments managing supplemental type certificate programs.
- Leasing Companies:Asset owners requiring dual-certified kits for cross-Atlantic lease-return aircraft.
- Aerostructure Suppliers:Tier-one integrators managing fan cowling and nozzle assembly.
Maintenance Repair Organizations handle the majority of retrofit volume; Leasing Companies are gaining procurement influence fastest as residual value protection drives specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retrofit procurement concentrates where legacy wide-body fleets face the tightest noise certification deadlines. The United States, Germany, India, United Kingdom, and Japan absorb the dominant share of aftermarket kit installations as regulatory enforcement intensifies across major aviation hubs.
United States
US legacy carriers retrofit CFM56-powered narrow-body fleets at Dallas and Atlanta MRO hubs to meet FAA Stage 5 noise mandates. The FAA Phase III certification protocol compresses supplier lead times for urgent AOG replacements. Chevron nozzle demand clusters at maintenance facilities serving American Airlines, Delta, and United operations.
Germany
Lufthansa Technik drives European aftermarket volume through Hamburg and Munich overhaul centers processing Airbus A330 and Boeing 777 nacelle modifications. EASA CS-34 amendments impose 2dB stricter noise limits than FAA Stage 5 for mixed-flow configurations. Composite aeroelastic tailoring expertise concentrates in the Bavaria aerospace corridor.
India
IndiGo and SpiceJet freighter conversions at Hyderabad and Bangalore cargo hubs create concentrated demand for night-flight noise quota compliance kits. The Directorate General of Civil Aviation aligns with ICAO Annex 16 noise standards while CORSIA compliance deadlines accelerate procurement. Variable area fan nozzle installations target 90-day turnaround windows at emerging MRO facilities.
United Kingdom
British Airways and Virgin Atlantic wide-body retrofit programs at London Heathrow maintenance bases respond to UK CAA enforcement of ICAO Chapter 14 noise limits. Gatwick and Manchester slot constraints push operators toward drag-reducing morphing surfaces over full engine swaps. GKN Aerospace anchors supply chain relationships through its Western England composite manufacturing footprint.
Japan
ANA and JAL operate aging Boeing 767 and 777 fleets requiring chevron nozzle retrofits to maintain access to Tokyo Haneda and Osaka Kansai noise-restricted slots. Japan Civil Aviation Bureau implements ICAO standards with 18-month supplemental type certificate validation timelines. Nagoya aerospace clusters support acoustic liner production for regional kit assembly.
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market Competitive Landscape
North American producers anchor one tier; European specialists hold certification-intensive positions. The vendor base stratifies across three tiers: integrated nacelle OEMs with captive aftermarket channels, composite aerostructures specialists with CFD-structural-acoustic coupled modeling capabilities, and tier-two component suppliers competing on automated fiber placement cost structures. Consolidation pressure intensifies as wind tunnel validation costs exceed $15 million per supplemental type certificate. Strategic moves center on backward integration into carbon fiber precursor supply and geographic proximity to MRO hub density.
Among France-based integrated producers, Safran Nacelles exemplifies the vertical nacelle OEM archetype with control across fan cowling and nozzle production. GKN Aerospace represents the European composite aerostructures specialist positioned for mixed-flow nacelle aeroelastic tailoring. Spirit AeroSystems anchors the US aftermarket-focused tier through geographic concentration near carrier MRO hubs. These three entities occupy positions that illustrate the market's competitive stratification between integrated system control and retrofit channel access.
| Leading Market Players |
|---|
| Safran Nacelles |
| Spirit AeroSystems |
| GKN Aerospace |
| RTX |
| GE Aerospace |
| MTU Aero Engines |
| Bombardier |
| Aernnova Aerospace |
| Leonardo |
| Others |
Pricing and Supply Chain Analysis
Automated fiber placement of carbon fiber-reinforced polymer laminates has collapsed acoustic liner production costs for tier-two suppliers while simultaneously concentrating margin capture among nacelle integrators with in-house composite manufacturing. This production-method transition enables aggressive pricing on chevron nozzle retrofits for CFM56-powered narrow-bodies, yet wind tunnel validation requirements lock out capital-constrained entrants from the premium tier.
Pricing Analysis
Volume placements concentrate in standard-grade chevron nozzles for legacy fleet retrofits, while premium margins attach to dual-certified morphing surface kits for cross-Atlantic lease-return aircraft. Price differentiation rests on supplemental type certificate validation depth and after-sales service bundling. Cost compression in the standard tier is intensifying because MRO channel disintermediation lets airlines source acoustic liners directly from composite specialists. Cargo operators at Indian hubs show the lowest price sensitivity due to night-flight slot economics, whereas US legacy carriers negotiating fleet-wide retrofits drive the hardest volume discounts.
Supply Chain Analysis
Supplemental type certificate approval gates access to the installed base, forcing kit manufacturers to absorb 18-24 month aerodynamic testing cycles before revenue recognition. Manufacturing concentrates in the United States, France, and the United Kingdom where nacelle OEMs maintain captive composite fabrication and wind tunnel partnerships. Raw material supply draws from Toray Industries and Hexcel aerospace-grade carbon fiber precursor, creating single-source vulnerability for tier-two assemblers. Distribution runs through MRO hub networks in Dallas, Atlanta, and Hamburg where geographic proximity to carrier maintenance bases controls logistics costs for urgent AOG replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Stage 5 noise certification has erected a cost-of-compliance moat that strands development investments for non-validated suppliers while rewarding incumbents with captive wind tunnel partnerships. This regulatory barrier protects compliant players from price erosion in the retrofit channel.
For Market Incumbents: Extend certification coverage across EASA CS-34 amendments to capture dual-validation service demand from Atlantic-crossing operators. Absorb composite precursor supply through backward integration into carbon fiber manufacturing to defend margin position against raw material volatility. Lock MRO channel access through exclusive acoustic liner replacement contracts at Dallas and Atlanta hub facilities. For New Entrants and Emerging Players: Launch via direct relationships with Indian cargo operators at Hyderabad and Bangalore seeking 90-day turnaround chevron nozzle installations for night-flight quota compliance. Target the variable area fan nozzle segment where sleeve-based architectures modularize deployment without full nacelle replacement. Bypass nacelle integrator markups by specializing in automated fiber placement cost structures for tier-two acoustic liner production. For Investors and Strategic Acquirers: Re-rating potential sits with composite aerostructures specialists possessing CFD-structural-acoustic coupled modeling capabilities given the multiphysics simulation talent scarcity at Safran, GKN, and three US national laboratories. Long-term viability over a multi-year horizon favors targets with established supplemental type certificate track records rather than experimental hardware developers. Monitor EASA-FAA regulatory divergence timelines as the inflection signal for dual-certification service demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor Supply | Toray Industries and Hexcel concentration exposes kit manufacturers to input price volatility and allocation risk. |
| Dual-Certification Validation Investment | EASA CS-34 amendments impose 2dB stricter noise limits than FAA Stage 5 for mixed-flow nacelle configurations. |
| MRO Hub Proximity Expansion | Geographic concentration near Dallas, Atlanta, and Hamburg maintenance facilities controls logistics costs for urgent AOG replacements. |
| Morphing Surface Architecture Development | Piezoelectric actuator integration with shape-memory alloy substrates enables real-time nozzle geometry adjustment for cargo operators. |
| Channel Disintermediation Partnership | US legacy carriers now source chevron nozzle acoustic liners directly from composite specialists bypassing nacelle integrators. |
Research Methodology
Multi-period observation of supplemental type certificate approval timelines, MRO procurement patterns, and regulatory divergence indicators anchored the trend analysis, supplemented by interviews with nacelle engineering directors, aftermarket procurement managers at US legacy carriers, composite manufacturing specialists, and EASA certification leads. Secondary validation drew from FAA certification databases, EASA CS amendment drafts, ICAO CAEP meeting minutes, and customs trade data on carbon fiber precursor imports. Bottom-up fleet retrofit demand modeling triangulated against top-down nacelle OEM revenue disclosures.
Input-output matrices mapped kit configuration demand across product type, technology maturity, application channel, and end-user procurement authority segmentation dimensions. CAGRs were derived from installed base aging curves, regulatory deadline enforcement schedules, and carrier fleet modernization program announcements. Industry-specific forecast inputs incorporated CFM56 and V2500 engine remaining service life estimates, alongside CORSIA compliance pathway adoption rates among cargo operators.
Regulatory timeline delays, raw material supply disruptions, and carrier bankruptcy-driven fleet retirement acceleration are the dominant revision risks to the installed base assumptions underlying retrofit demand projections. A model refresh is warranted upon material change in FAA-EASA noise rulemaking alignment or ICAO CORSIA phase-in enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
America Attack Helicopter Market
Aircraft
Active Air Deflector Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Helicopter Wheels Market
Aircraft
Europe General Aviation Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Regional Jet Market