
 Space-Based Solar Power Market | 2026-2036
Space-Based Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Space-Based Solar Power Market Analysis
Energy-as-a-service contracting for orbital power delivery is rebalancing how satellite operators procure electricity, shifting capital expenditure into operational subscription models. Northrop Grumman leverages its heritage in space systems integration to anchor long-term government service agreements. Airbus competes through European consortium structures that spread development risk across member states. Boeing sustains lobbying presence in Washington to secure defense-linked power-beaming contracts.
Space-based solar power harvests sunlight in geostationary orbit and converts it into microwave or laser beams for transmission to terrestrial rectennas, with photovoltaic conversion efficiencies exceeding terrestrial panels due to unfiltered solar flux and continuous illumination. Microwave transmission systems currently occupy the largest development share because decades of radar and communications engineering have matured phased-array hardware at relevant frequencies. Thermal conversion segments attract renewed research interest for hybrid architectures that buffer energy through heat engines before electrical generation. Among end users, government agencies dominate near-term procurement while private sector participation expands through venture-backed demonstration missions.
The Federal Aviation Administration coordinates launch licensing for power satellite deployments, while the Federal Communications Commission governs spectrum allocation for microwave downlink beams. Japan's Ministry of Economy, Trade and Industry funds orbital demonstration roadmaps through public-private partnerships with domestic aerospace manufacturers. Stakeholders must monitor how national security classifications affect technology export controls and whether emerging debris mitigation standards constrain constellation scale-up.
Market Dynamics
Wireless power transmission maturation is compressing the cost-per-kilogram barrier for orbital energy systems, forcing a fundamental reallocation of R&D capital from launch vehicles to in-orbit manufacturing and beam-forming electronics.
Growth Catalysts
- Phased-array microwave hardware:Decades of radar engineering heritage from defense applications now transfers directly to power-beaming rectennas, collapsing development timelines for space-to-ground transmission systems.
- Japan's METI orbital demonstration roadmaps:Public-private partnerships channel sustained funding toward extraterrestrial energy validation missions, de-risking capital deployment for private satellite operators.
- Continuous illumination physics:Geostationary positioning eliminates terrestrial intermittency constraints, enabling baseload-equivalent power profiles that terrestrial renewables cannot replicate.
Market Restraints
- Launch cost volatility:Heavy-lift capacity constraints and propellant supply fluctuations concentrate pricing power with a limited set of commercial launch providers, inflating deployment budgets.
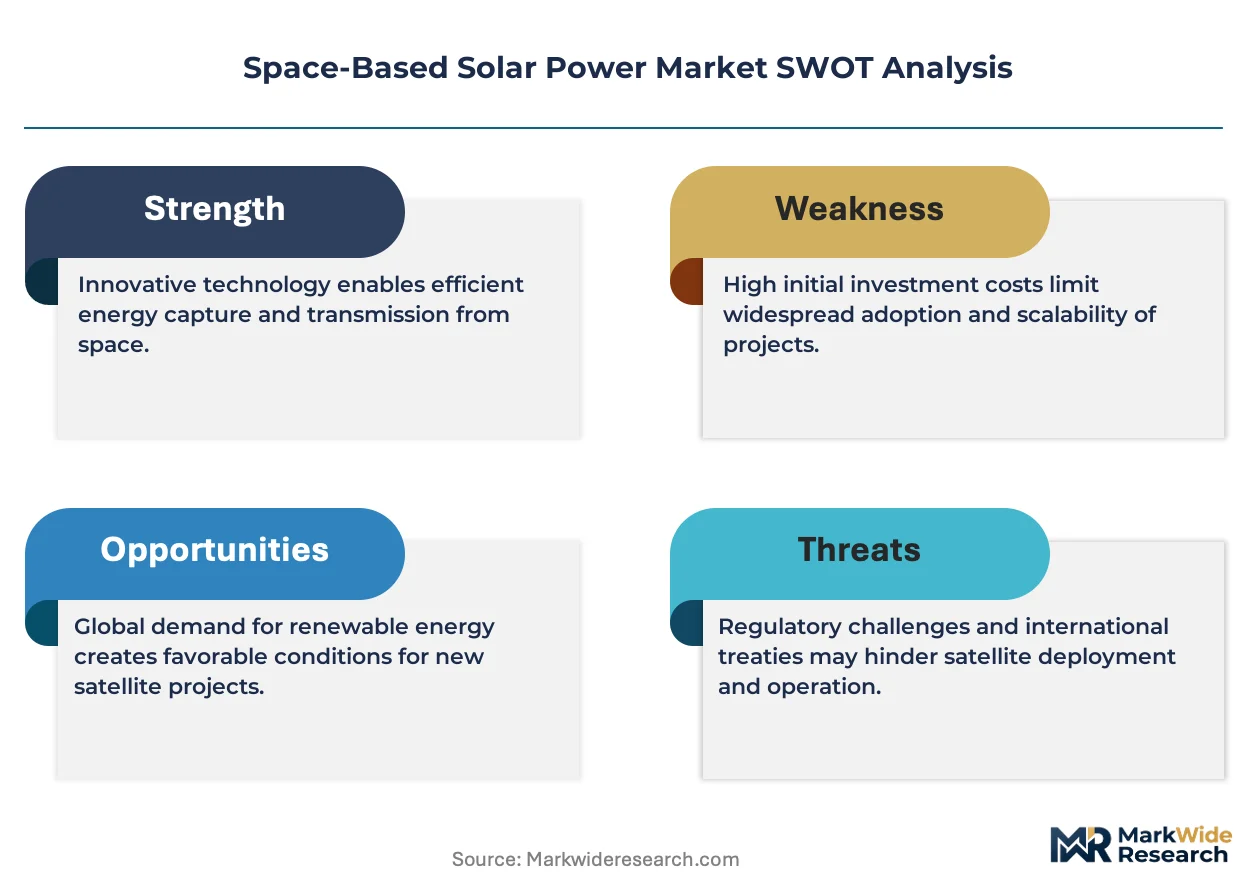
- Atmospheric attenuation losses:Microwave beam scattering through weather systems imposes fundamental efficiency ceilings on power delivery regardless of orbital generation capacity.
- Spectrum allocation friction:FCC licensing timelines for downlink frequencies extend 18-36 months, delaying revenue recognition for deployed systems.
Strategic Opportunities
- Remote island electrification:Pacific territories with diesel-dependent grids present captive demand for orbital power-beaming demonstration contracts.
- Hybrid thermal-electric architectures:Heat-engine buffering systems enable dispatchable output profiles that pure photovoltaic systems cannot achieve.
- Defense microgrid integration:Forward operating bases require resilient power sources beyond contested supply lines, creating classified procurement channels.
Industry Challenges
- Orbital debris mitigation compliance:Emerging constellation-scale deployment standards impose end-of-life disposal requirements that inflate system mass and complexity.
- Terrestrial rectenna siting:Land-use conflicts and electromagnetic exposure regulations constrain ground infrastructure placement near load centers.
- Cross-domain workforce scarcity:Simultaneous expertise in aerospace engineering and high-power microwave systems remains concentrated within defense contractor labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space-Based Solar Power Market |
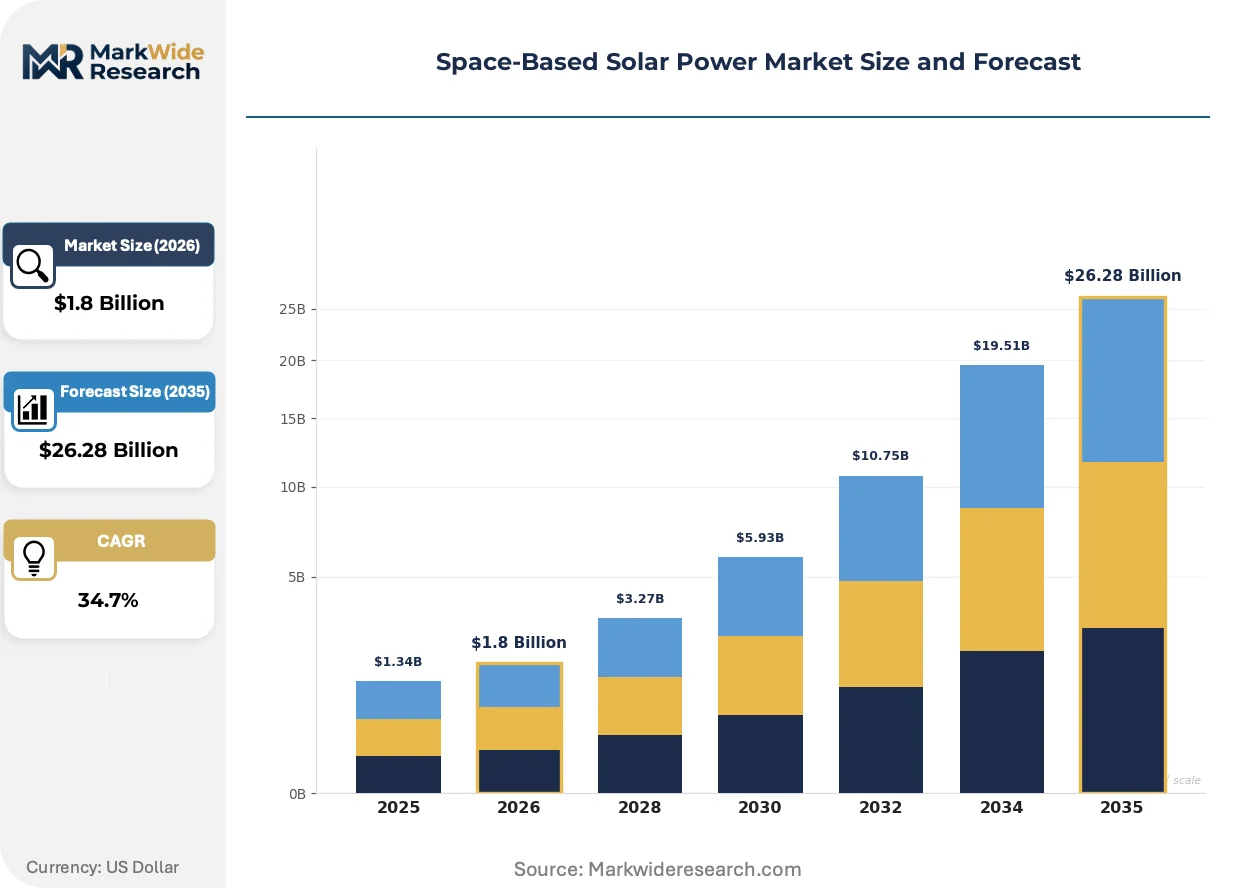
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaics, Microwave Transmission, Thermal Conversion, Energy Storage Application: Satellite Power, Military Operations, Disaster Relief, Commercial Use End User: Government, Defense Agencies, Research Institutions, Private Sector Deployment Type: On-orbit, Ground Station, Mobile Platforms, Stationary Facilities |
| Companies Covered | Northrop Grumman, Airbus, Boeing, Thales Alenia Space, OHB SE, Space Solar Group Holdings Ltd., SpaceTech GmbH, Japan Aerospace Exploration Agency, China Academy of Space Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space-Based Solar Power Market Emerging Trajectories
Orbital manufacturing capabilities and autonomous assembly robotics are collapsing the payload mass constraints that historically governed power satellite economics, enabling architectures previously dismissed as physically infeasible.
Thin-film photovoltaic substrates with integrated power management electronics are rewriting the mass-to-power ratio calculus for geostationary platforms. JAXA and domestic aerospace consortia in Japan are deploying these arrays on demonstration missions planned through 2028. The structural consequence is a compression in launch frequency requirements, shifting competitive advantage toward in-orbit servicing capabilities rather than heavy-lift access.
REACH chemical safety protocols in Europe are constraining the terrestrial supply chain for certain semiconductor substrates used in microwave generation components. Industrial consequence manifests as dual-sourcing mandates and accelerated qualification of alternative III-V compound suppliers. Satellite integrators serving European government customers are responding by front-loading material certification budgets and locking multi-year supply agreements.
Defense agencies are consolidating electricity procurement for classified space assets under centralized service agreements rather than capital acquisition programs. This displaces traditional hardware ownership models with availability-based contracting. The shift is most visible in United States national security space budgets, where operational expenditure lines now capture orbital power generation as a utility service rather than platform procurement.
Space-Based Solar Power Market Segmentation
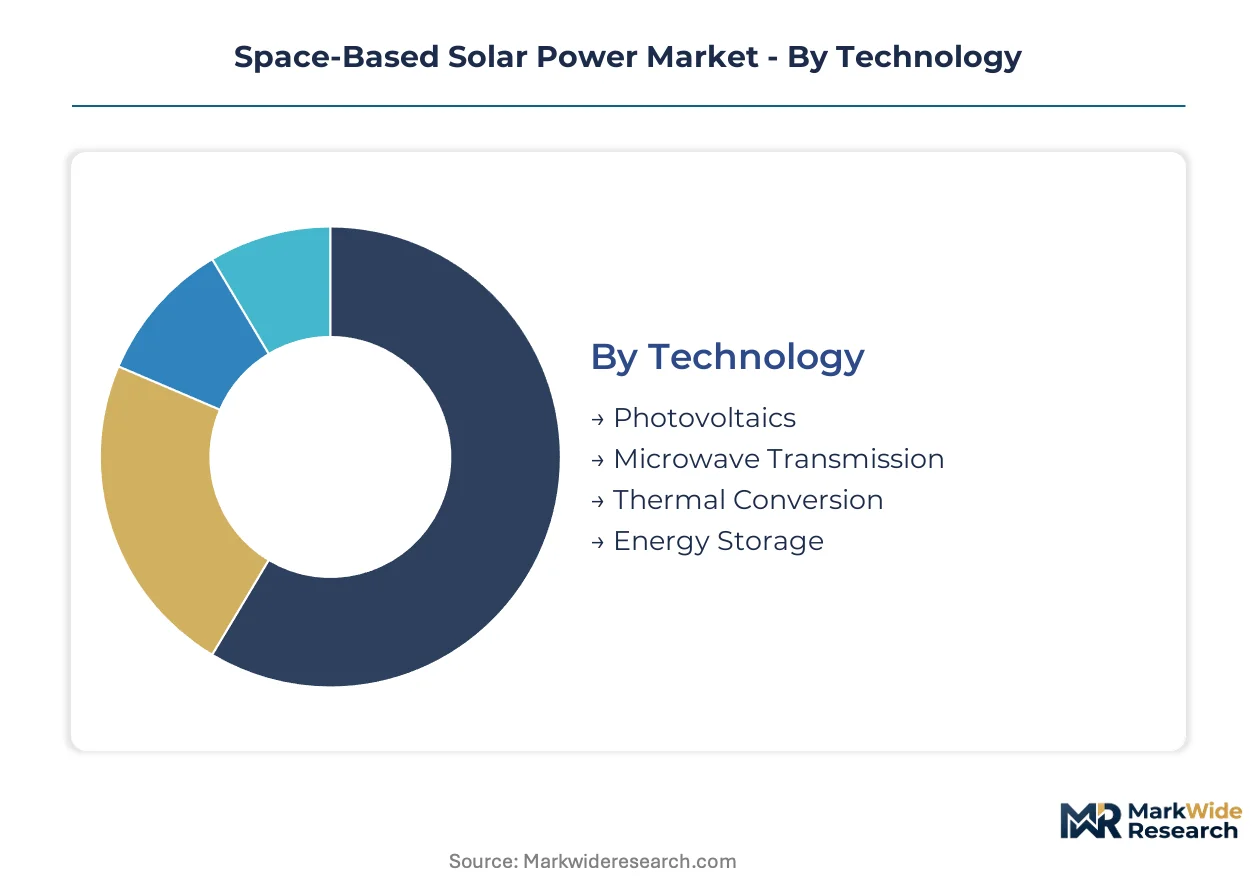
Technology heterogeneity in orbital power generation demands granular segmentation to map capital allocation patterns. Procurement strategies diverge sharply across transmission modalities and deployment architectures, with defense agencies and commercial satellite operators pursuing fundamentally different performance specifications.
Technology:
Supply concentration in microwave phased-array components concentrates procurement leverage with defense-heritage contractors possessing radar engineering depth.
- Photovoltaics:Thin-film substrates with integrated power management electronics dominate geostationary platform designs. JAXA demonstration missions validate mass-to-power ratios that compress launch frequency requirements for Japanese aerospace consortia.
- Microwave Transmission:Phased-array rectennas leverage decades of radar engineering heritage, collapsing development timelines for space-to-ground power delivery. Atmospheric attenuation through weather systems imposes efficiency ceilings regardless of orbital generation scale.
- Thermal Conversion:Heat-engine buffering architectures enable dispatchable output profiles unavailable to pure photovoltaic systems.
- Energy Storage:Orbital battery systems bridge eclipse periods and stabilize beam transmission duty cycles.
Microwave Transmission absorbs the bulk of installed capacity; Photovoltaics is expanding most quickly.
Application:
Cost tier stratification separates premium defense contracts from commercial demonstration missions with constrained capital envelopes.
- Satellite Power:Continuous illumination physics eliminates terrestrial intermittency constraints for geostationary platforms. FCC licensing timelines extending 18-36 months delay revenue recognition for commercial operators.
- Military Operations:Forward operating bases require resilient power beyond contested supply lines, creating classified procurement channels. Availability-based contracting displaces traditional hardware ownership in United States national security space budgets.
- Disaster Relief:Rapid-deploy rectenna systems target Pacific territories with diesel-dependent grids.
- Commercial Use:Venture-backed demonstration missions expand private sector participation through operational expenditure models.
Military Operations absorbs the bulk of installed capacity; Commercial Use is climbing the fastest.
End User:
Customer type fragmentation concentrates capability scarcity within defense contractor labor pools possessing simultaneous aerospace and high-power microwave expertise.
- Government:Centralized service agreements for classified space assets displace capital acquisition programs with utility-based operational expenditure. FAA launch licensing and FCC spectrum allocation govern deployment timelines.
- Defense Agencies:Resilient power requirements for forward bases drive procurement through classified channels beyond standard acquisition frameworks.
- Research Institutions:JAXA and domestic aerospace consortia validate orbital demonstration roadmaps through public-private partnerships funded by Japan's METI.
- Private Sector:Venture-backed satellite operators pursue energy-as-a-service contracting to shift capital expenditure into subscription models.
Defense Agencies absorbs the bulk of installed capacity; Private Sector is gaining share fastest.
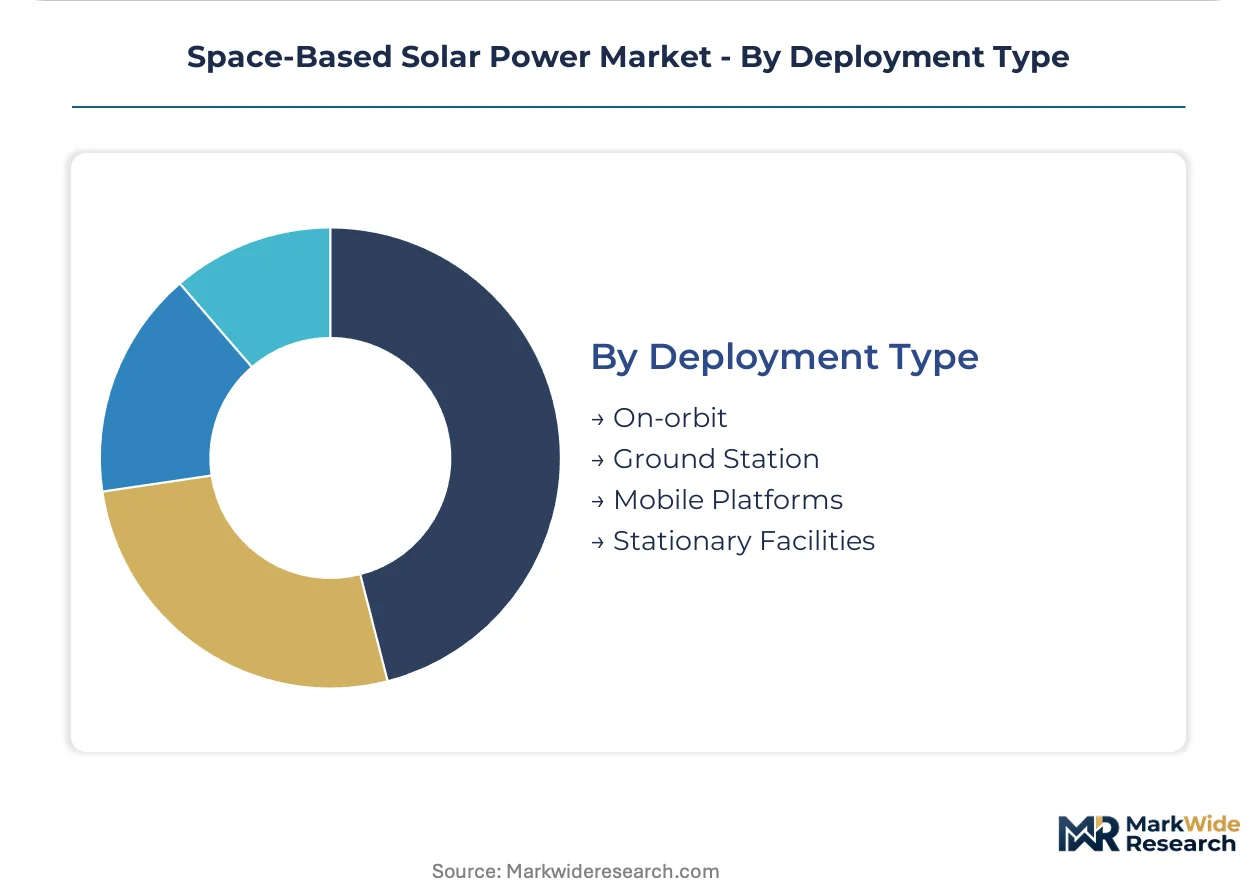
Deployment Type:
Volume concentration in on-orbit manufacturing reflects payload mass constraints collapsing through autonomous assembly robotics.
- On-orbit:Autonomous assembly capabilities enable architectures previously dismissed as physically infeasible. REACH chemical safety protocols in Europe constrain terrestrial semiconductor supply chains for microwave generation components.
- Ground Station:Terrestrial rectenna siting faces land-use conflicts and electromagnetic exposure regulations near load centers.
- Mobile Platforms:Rapid-deploy systems target disaster relief and expeditionary military applications.
- Stationary Facilities:Fixed installations anchor baseload-equivalent power profiles for grid-connected demand.
On-orbit absorbs the bulk of installed capacity; Mobile Platforms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the global development corridor for orbital power demonstration missions, with JAXA and domestic aerospace consortia validating thin-film photovoltaic arrays through 2028 deployment schedules. Government space agencies in the United States, Japan, and China currently allocate the largest dedicated funding pools for extraterrestrial energy validation.
United States
Defense microgrid integration and classified procurement channels for forward operating bases drive concentrated demand within national security space budgets. The Federal Aviation Administration coordinates launch licensing for power satellite deployments while the Federal Communications Commission governs spectrum allocation for microwave downlink beams. Washington lobbying corridors sustain Boeing's presence in defense-linked power-beaming contract competitions.
Japan
Public-private partnerships channel sustained funding toward orbital demonstration roadmaps through METI-coordinated initiatives with domestic aerospace manufacturers. JAXA validates mass-to-power ratios that compress launch frequency requirements for geostationary platform designs. Tokyo-Yokohama industrial clusters concentrate thin-film photovoltaic substrate development and integrated power management electronics qualification.
China
National space programs allocate dedicated funding for extraterrestrial energy demonstration missions through state-backed aerospace development frameworks. The country's national space technology academy governs orbital power generation system procurement and validation timelines. Beijing-Tianjin technology corridors concentrate microwave transmission hardware development and phased-array rectenna manufacturing capabilities.
Germany
European consortium structures spread development risk across member states through Airbus-led integration platforms serving government service agreements. REACH chemical safety protocols constrain terrestrial supply chains for semiconductor substrates used in microwave generation components, accelerating dual-sourcing mandates and alternative III-V compound supplier qualification. Munich-Stuttgart aerospace clusters concentrate autonomous assembly robotics and in-orbit manufacturing capability development.
Space-Based Solar Power Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the orbital power generation value chain, with defense-heritage contractors possessing radar engineering depth holding procurement leverage in microwave phased-array components. The market structure concentrates capability scarcity within labor pools possessing simultaneous aerospace engineering and high-power microwave systems expertise. Three strategic archetypes dominate: vertically integrated space systems integrators anchoring long-term government service agreements; European consortium structures distributing development risk across national boundaries; and venture-backed demonstration mission operators pursuing operational expenditure models. Competitive moves center on strategic partnerships for in-orbit servicing capabilities and portfolio diversification into thermal-electric hybrid architectures.
Among United States-based defense contractors, Northrop Grumman and Boeing exemplify the vertically integrated archetype, occupying positions sustained by heritage in space systems integration and Washington lobbying presence respectively. Airbus represents the European consortium model, anchoring risk-distributed development frameworks across member state aerospace manufacturers. These three entities sit within the tier of contractors capable of securing availability-based contracting arrangements that displace traditional hardware ownership models in national security space procurement.
| Leading Market Players |
|---|
| Northrop Grumman |
| Airbus |
| Boeing |
| Thales Alenia Space |
| OHB SE |
| Space Solar Group Holdings Ltd. |
| SpaceTech GmbH |
| Japan Aerospace Exploration Agency |
| China Academy of Space Technology |
| Others |
Supply Flow & Price Mechanics
Launch propellant costs cascade through orbital power satellite economics, concentrating pricing power with heavy-lift providers in the United States and China while compressing margins for system integrators serving commercial demonstration missions.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for government service agreements, with availability thresholds dictating premium tier placement for defense-linked procurement. Three-tier pricing structure across mission-assurance, standard demonstration, and experimental validation levels separates Northrop Grumman and Boeing from venture-backed entrants. Cost compression in commercial launch access is intensifying because SpaceX reusable capacity expansion resets price benchmarks across the sector. Defense agencies exhibit lowest price sensitivity due to classified budget lines, while Pacific island utilities face acute capital constraints.
Supply Chain Analysis
Freight costs for oversized fairing payloads concentrate procurement leverage with launch providers operating from Cape Canaveral, Vandenberg, and Wenchang facilities. Gallium arsenide substrates for microwave generation components draw from Japan and Germany, while thin-film photovoltaic cells source from Japanese domestic aerospace consortia. Single-source vulnerability pervades phased-array rectenna engineering talent pools concentrated within defense contractor labor bases. Distribution runs through prime contractor-led integration platforms rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Launch cost volatility and spectrum allocation friction are accelerating consolidation, forcing venture-backed demonstration operators into strategic exits or acquisition by vertically integrated space systems integrators.
For Market Incumbents: Extend in-orbit servicing capabilities through autonomous assembly robotics investments, capturing margin from payload mass constraint relaxation. Anchor long-term government service agreements before FCC licensing timelines compress competitive windows. Threat substitution from terrestrial battery storage cost declines demands hybrid thermal-electric architecture diversification as defensive positioning. For New Entrants and Emerging Players: Japan's METI orbital demonstration roadmaps in Tokyo open a window for public-private partnership participation without full capital burden. Target Pacific island disaster relief electrification as the most penetrable application, leveraging rapid-deploy rectenna specifications outside defense classification constraints. Pursue energy-as-a-service contracting as the go-to-market angle to shift satellite operator procurement from capital acquisition to operational subscription. For Investors and Strategic Acquirers: JAXA thin-film photovoltaic validation mission completion is the leading indicator that mass-to-power ratio economics have crossed commercial viability thresholds. Frame long-term positioning around availability-based contracting displacement of hardware ownership models across national security space budgets. Acquisition targets should possess simultaneous aerospace engineering and high-power microwave systems expertise concentrated within defense-heritage labor pools.| Strategic Initiative | Industry Significance |
|---|---|
| In-Orbit Manufacturing Scale-Up | Autonomous assembly robotics collapse payload mass constraints previously governing satellite economics. |
| Defense Service Agreement Conversion | Availability-based contracting with Pentagon displaces traditional platform procurement capital lines. |
| Hybrid Thermal-Electric Development | Heat-engine buffering architectures enable dispatchable output profiles unavailable to pure photovoltaic systems. |
| Pacific Island Demonstration Deployment | Diesel-dependent grids in territorial markets present captive demand for power-beaming validation contracts. |
| REACH Compliance Supply Restructuring | Dual-sourcing mandates for III-V compound suppliers front-load material certification budgets for European government customers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving satellite systems engineers, FCC spectrum allocation specialists, METI program officers, and defense procurement leads. FAA launch licensing databases, JAXA mission disclosure filings, ECHA REACH substance restriction updates, and heavy-lift provider manifest records supplied quantitative benchmarks. Bottom-up segment sizing triangulated against top-down government budget appropriation analysis.
Data-stream reconciliation across technology, application, end user, and deployment type dimensions shaped the analytical framework over the projection horizon. CAGRs derived from installed capacity build-out trajectories modeled against launch frequency constraints and beam transmission efficiency assumptions. Microwave phased-array hardware maturation curves and thin-film photovoltaic mass reduction coefficients served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for laser-based power transmission would alter the outlook if atmospheric attenuation engineering solutions advance faster than projected. Forecasts reflect documented assumptions regarding launch cost decline slopes and spectrum allocation timeline standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
France Space Electronics Market
Space
Space Blanket Market
Space
Germany Space Electronics Market
Space
Mexico Space Electronics Market
Space
Suborbital Space Tourism Market
Space
UK Space Electronics Market
Space
Africa Space Propulsion System Market
Space
Space Sensors Market
Space
Space Tourism Market
Space
Space Ground Station Equipment Market
Space
Space As a Service Market
Space
Space on Board Computing Platform Market
Space
Space Robots Market
Space
Japan Space Electronics Market
Space
Space Management Solutions Market
Space
Space Traffic Management Market