
 Global Aircraft Electric Brake Control System Market | 2026-2036
Global Aircraft Electric Brake Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Electric Brake Control System Market Intelligence
The rise of performance-based leasing models for high-value components is fragmenting the traditional aftermarket supply chain for aircraft electric brake control systems. This shift allows Maintenance Repair Organizations to compete more effectively against OEMs. Safran Landing Systems leverages its deep integration with airframers to secure long-term service contracts. Meanwhile, Parker-Hannifin differentiates through specialized electromechanical component expertise for a wide range of platforms, challenging incumbent positions.
An aircraft electric brake control system is a critical flight control unit that translates pilot or autopilot brake commands into precisely modulated electrical signals for wheel braking actuators. These systems typically operate on a 28V DC or 270V DC power bus and incorporate anti-skid, autobrake, and locked-wheel protection logic. Fully electric systems are gaining share over legacy electrohydraulic designs, particularly in new aircraft production. Within applications, commercial airliners represent the largest segment, while the business jets category shows strong growth in retrofit upgrades.
Certification from bodies like the FAA in the United States and compliance with European CE marking standards are mandatory for market entry. These regulations dictate stringent requirements for system reliability, failure analysis, and software assurance under DO-178C guidelines. Component supplier selection will increasingly hinge on demonstrated compliance with evolving cybersecurity mandates for interconnected aircraft systems.
Market Dynamics
The fundamental transition toward more-electric aircraft architectures is the central force shaping the market. This shift prioritizes weight reduction and fuel efficiency, directly favoring fully electric brake control systems over legacy hydraulic and electrohydraulic alternatives on new aircraft platforms.
Growth Catalysts
- More-Electric Aircraft Adoption:The push for reduced hydraulic system complexity and lower aircraft weight to improve fuel burn drives the primary demand for electric brakes in new commercial airliner programs.
- Aerospace Manufacturing Hubs:Concentrated aircraft production activities in the United States and France create a strong, localized demand pull from major airframers for advanced braking system technologies.
- Emissions Reduction Mandates:Global frameworks like ICAO's CORSIA indirectly support the adoption of lighter components, as every kilogram of weight saved contributes to lower CO2 emissions per flight.
Market Restraints
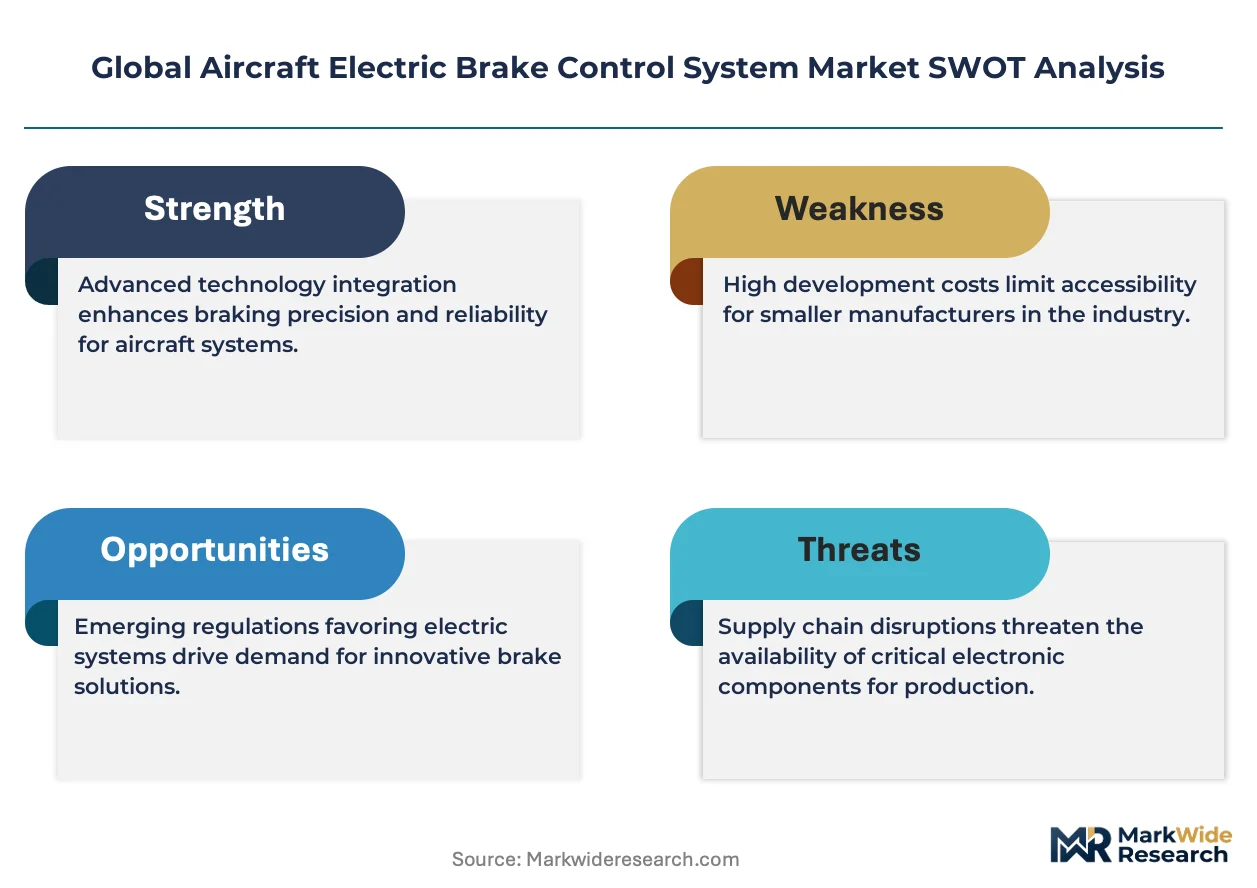
- High Development Costs:The significant upfront investment required for research, development, and rigorous testing of new electric brake control systems presents a high barrier to entry compared to mature hydraulic technologies.
- Thermal Management Complexity:Electric brakes generate substantial heat during operation, necessitating sophisticated and often heavy thermal management solutions that can offset some of the system's weight savings.
- Specialized Component Scarcity:A constrained supply chain for aerospace-grade high-power semiconductors and electronic components creates production bottlenecks and increases lead times for system manufacturers.
Strategic Opportunities
- Retrofit Market Expansion:Upgrading the braking systems of in-service business jets and regional aircraft from hydraulic to electric offers a substantial aftermarket growth avenue for component suppliers and MRO providers.
- Predictive Maintenance Integration:Incorporating health monitoring sensors and AI-driven analytics into brake control units allows for predictive maintenance, reducing unscheduled downtime and lowering airline operational costs.
- MRO Service Growth in Asia:Establishing certified repair and overhaul capabilities in rapidly expanding aviation hubs across Southeast Asia and the Middle East can capture demand from growing regional airline fleets.
Industry Challenges
- Stringent Certification Timelines:Navigating the extensive software and hardware verification processes mandated by regulations like DO-178C from the FAA and EASA often results in protracted development cycles.
- Legacy System Integration:Ensuring backward compatibility and seamless communication between modern electric brake controllers and older aircraft power distribution and avionics architectures poses a significant engineering challenge.
- Evolving Cybersecurity Threats:Protecting interconnected flight control systems from cyber attacks requires continuous investment in threat modeling and resilient design, adding complexity and cost to system development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Electric Brake Control System Market |
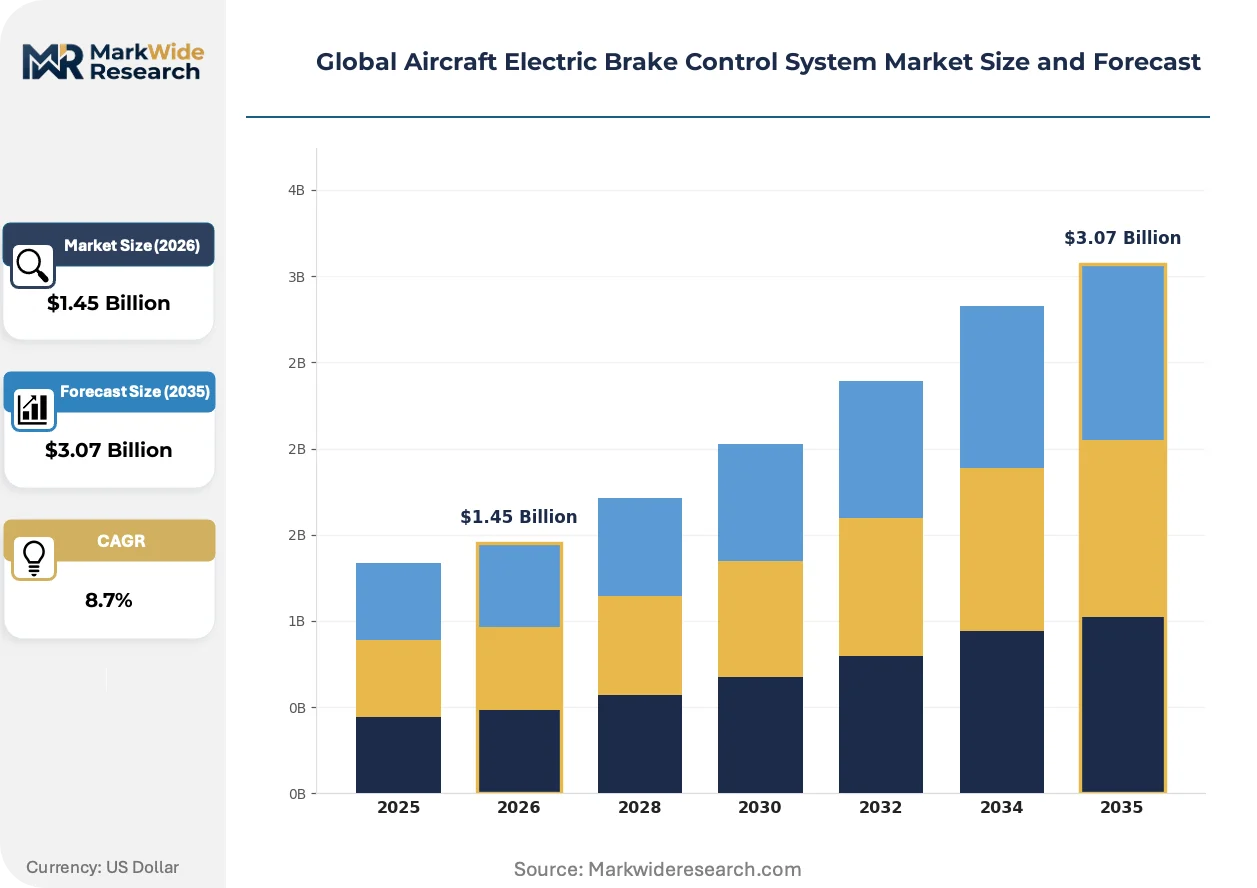
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
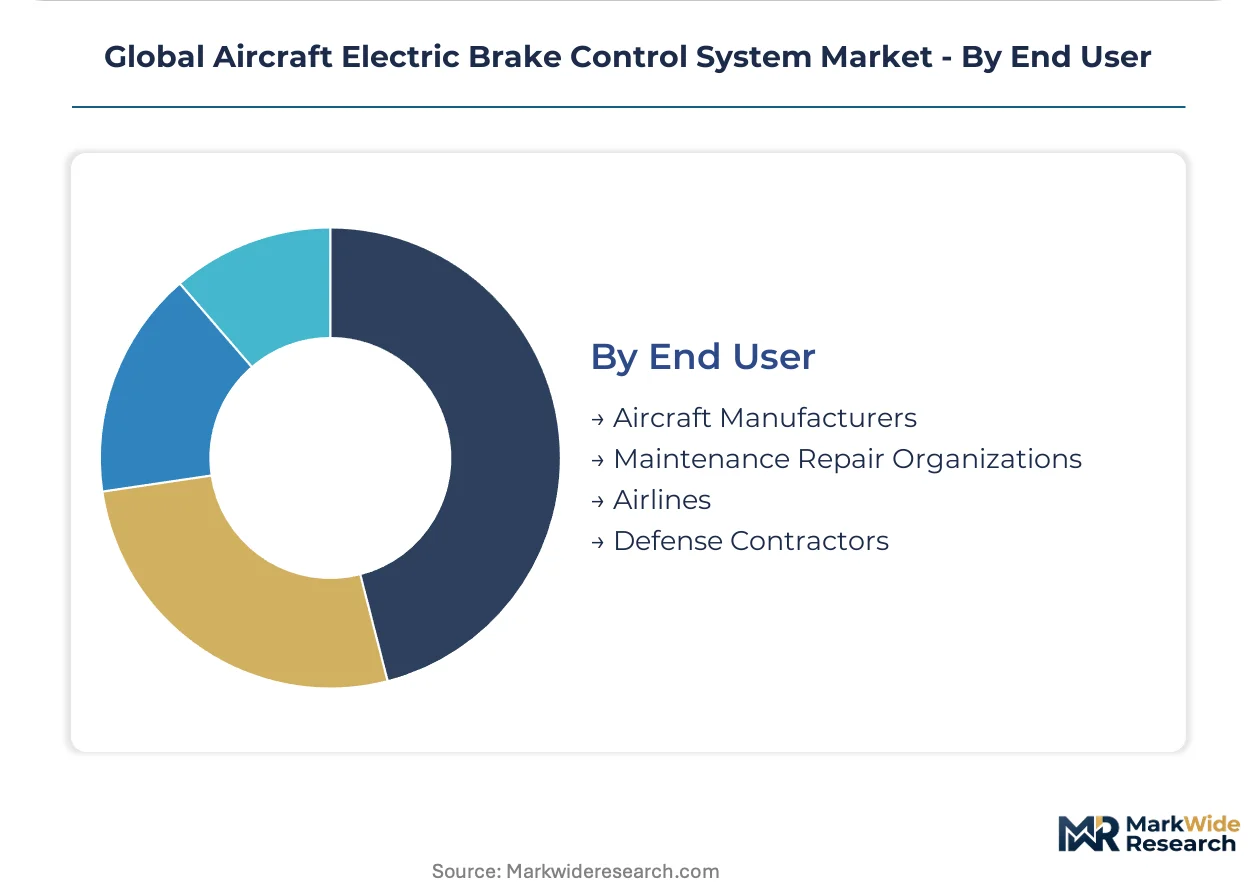
| Segmentation | Product Type: Electromechanical, Electrohydraulic, Fully Electric, Hybrid Electric, Regenerative Systems Application: Commercial Airliners, Military Aircraft, Business Jets, Regional Aircraft, Helicopters Installation Type: New Aircraft Production, Retrofit Upgrades, OEM Integration, Aftermarket Installation End User: Aircraft Manufacturers, Maintenance Repair Organizations, Airlines, Defense Contractors |
| Companies Covered | Honeywell International Inc., Safran Landing Systems, Collins Aerospace, Parker-Hannifin Corporation, Crane Aerospace & Electronics, UTC Aerospace Systems, Meggitt plc, Thales, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Electric Brake Control System Market Strategic Shifts & Innovations
System intelligence and high-voltage electrification are defining the next generation of aircraft brake controls. The focus is shifting from simple hydraulic replacement to creating integrated, data-rich systems that enhance aircraft safety, efficiency, and maintainability.
High-voltage 270V DC power architectures are a key enabler for more powerful and compact braking systems. New-generation commercial and military aircraft are rapidly adopting this standard to support power-hungry onboard systems. The superior power density and reduced wiring weight of 270V DC systems is rendering obsolete the less efficient, bulkier power distribution schemes of older aircraft.
New cybersecurity mandates, including guidelines like DO-326A/ED-202A, are fundamentally altering system design priorities. These regulations from bodies like the FAA and EASA compel manufacturers to embed robust security features from the initial design phase to protect against digital threats. The commercial airliners segment, with its highly integrated avionics, is most affected, now requiring exhaustive verification of system resilience.
A shift toward performance-based leasing and unbundled maintenance for high-value components is fragmenting the aftermarket. Airlines increasingly source brake system overhaul services directly from specialized providers, bypassing broader airframer service agreements to optimize cost and turnaround time. This trend is particularly visible in North America and Europe, driven by a competitive ecosystem of independent MROs.
Global Aircraft Electric Brake Control System Market Segmentation
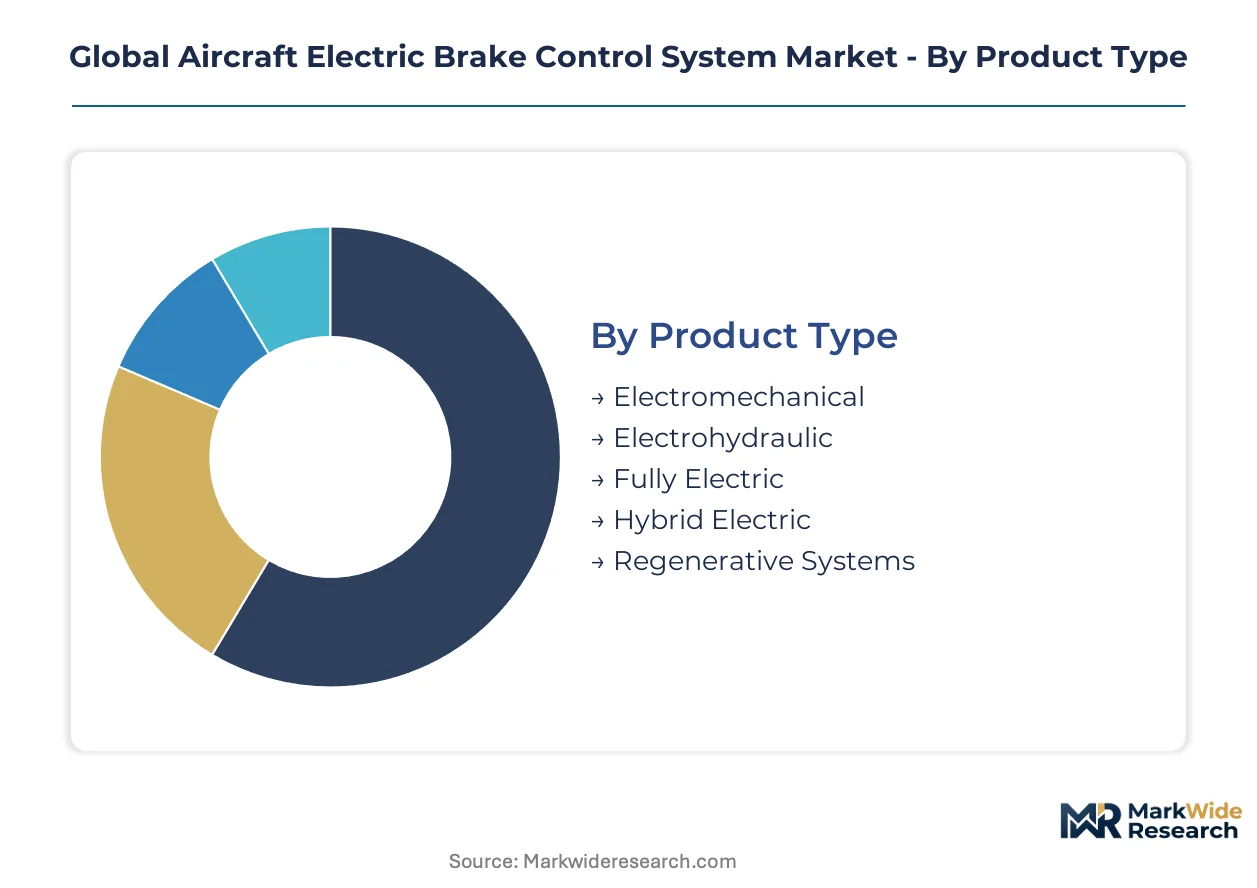
The Global Aircraft Electric Brake Control System Market is dissected across key dimensions to reveal distinct demand patterns and technological preferences. Understanding these segments clarifies the varying adoption rates of advanced braking solutions across different aviation sectors. This granular analysis supports strategic planning for component suppliers and service providers.
Product Type:
The product type segmentation illustrates the evolution from established electrohydraulic systems to advanced, fully electric architectures, reflecting varying levels of technological maturity.
- Fully Electric:These systems represent the cutting edge, operating on high-voltage 270V DC power buses to provide precise braking control without hydraulic fluid. Demand concentrates in new commercial airliner programs in the United States and France due to their weight reduction and fuel efficiency benefits.
- Electromechanical:Electromechanical systems convert electrical signals into mechanical force, often found in lighter aircraft or as components within larger systems. Their robustness and simpler integration drive adoption in specialized military aircraft applications.
- Electrohydraulic:These legacy systems combine electrical control with hydraulic actuation, offering a proven solution for many existing aircraft fleets.
- Hybrid Electric:Hybrid electric systems blend electric and hydraulic power, providing redundancy and optimized performance for specific aircraft designs.
- Regenerative Systems:Regenerative braking systems capture kinetic energy during deceleration, converting it into electrical power for storage or immediate use.
Electrohydraulic systems handle the majority of throughput in the existing fleet; Fully Electric systems are the fastest mover on share in new aircraft.
Application:
The application segment reveals how different aircraft categories prioritize electric braking systems based on operational requirements and production volumes.
- Commercial Airliners:This segment represents the largest volume market, driven by the strong demand for new aircraft production lines and the push for more-electric architectures. Airlines prioritize fuel efficiency and reduced maintenance costs, making electric brakes attractive for their large fleets.
- Business Jets:Business jets show strong growth, particularly in retrofit upgrades, as operators seek enhanced performance and reduced maintenance compared to older hydraulic systems. The premium segment in North America values the advanced features and reliability.
- Military Aircraft:Military aircraft demand robust and reliable braking systems, often incorporating specialized electromechanical components for diverse mission profiles.
- Regional Aircraft:Regional aircraft increasingly adopt electric braking solutions to improve operational economics and reduce system complexity.
- Helicopters:Helicopters require precise braking for ground operations and specialized landing scenarios, favoring compact and reliable electric control units.
Commercial Airliners remain the dominant application segment; Business Jets exhibit significant growth in aftermarket upgrades.
Installation Type:
Installation types reflect distinct value propositions, ranging from high-value new aircraft integration to cost-effective aftermarket solutions.
- New Aircraft Production:This segment involves the direct integration of electric brake control systems into newly manufactured aircraft, primarily in major aerospace hubs like the United States and France. Manufacturers aim for optimal weight reduction and system efficiency from the design phase.
- Retrofit Upgrades:Retrofit upgrades involve replacing existing hydraulic systems with electric ones on in-service aircraft, offering a substantial aftermarket growth avenue. This trend is particularly strong in the business jets category seeking operational improvements.
- OEM Integration:OEM integration covers systems supplied directly to aircraft manufacturers for assembly into their production lines.
- Aftermarket Installation:Aftermarket installation includes component replacements and upgrades performed by MROs or airlines on operational aircraft.
New Aircraft Production forms the largest segment by initial volume; Retrofit Upgrades are rapidly expanding in scope.
End User:
The end user analysis highlights the diverse procurement patterns and direct customers for aircraft electric brake control systems.
- Aircraft Manufacturers:These entities are primary customers, integrating electric brake control systems into new aircraft designs and production lines. Their procurement decisions are heavily influenced by stringent certification requirements and long-term supply agreements.
- Airlines:Airlines procure systems for fleet maintenance, upgrades, and replacement parts, increasingly favoring solutions that offer lower operational costs and enhanced reliability. Their focus on performance-based leasing models impacts purchasing decisions.
- Maintenance Repair Organizations:MROs purchase electric brake components for repair, overhaul, and service contracts for various aircraft operators.
- Defense Contractors:Defense contractors integrate electric braking systems into military aircraft, prioritizing ruggedness and specific mission capabilities.
Aircraft Manufacturers are the key decision-makers for initial system adoption; Airlines exert growing influence on aftermarket service requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aircraft electric brake control system market exhibits a complex interplay of manufacturing capabilities and end-user demand. While certain nations establish themselves as primary exporters of advanced aerospace components, others serve as significant importers due to large domestic airline fleets or maintenance needs. This dynamic shapes investment in research and production across different regions.
United States
The United States drives substantial demand for electric brake control systems, propelled by extensive new commercial aircraft production lines. FAA certification mandates rigorous testing and compliance for all flight-critical components. Major aerospace clusters in Seattle, Wichita, and Southern California are actively engaged in developing and integrating these advanced systems into next-generation aircraft.
France
France serves as a significant hub for aircraft electric brake control system innovation, supported by robust European airframer demand. Compliance with European CE marking standards and EASA regulations is paramount for market entry and product deployment. Toulouse, a primary aerospace manufacturing region, sees continuous investment in electric braking solutions for its large-scale aircraft assembly operations.
Germany
German aerospace manufacturers increasingly integrate electric brake systems into their components and aircraft, driven by efficiency mandates. EASA regulations, alongside national industrial standards, ensure high safety and performance criteria. Hamburg's aerospace industry, focused on aircraft assembly and MRO, is a key adopter of these lighter, more fuel-efficient braking technologies.
Japan
Japanese aerospace firms are investing in electric brake control systems, particularly for regional aircraft and military platforms. METI guidelines encourage technological advancement and collaboration within the aerospace supply chain. Nagoya, a central area for Japan's aerospace manufacturing, supports research and development into advanced electric braking components.
Global Aircraft Electric Brake Control System Market Key Industry Players
On the supply side, the industry is moderately concentrated, with a few large aerospace system integrators dominating the market for new aircraft production. Strategic archetypes include established original equipment manufacturers (OEMs) providing integrated solutions, specialized component suppliers focusing on specific technologies, and independent Maintenance Repair Organizations (MROs) offering aftermarket services. Dominant competitive moves involve strategic partnerships with airframers and continuous portfolio diversification into advanced electric technologies.
Global integrators like Safran Landing Systems exemplify the OEM-driven approach, leveraging deep airframer relationships for securing long-term service contracts and system integration. Parker-Hannifin Corporation represents a specialized component supplier, differentiating through its electromechanical expertise for a wide range of aircraft platforms, challenging incumbent positions with targeted solutions. Collins Aerospace, a large US-based aerospace systems provider, occupies a significant position in offering comprehensive electric brake control solutions across various commercial and military aircraft types.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran Landing Systems |
| Collins Aerospace |
| Parker-Hannifin Corporation |
| Crane Aerospace & Electronics |
| UTC Aerospace Systems |
| Meggitt plc |
| Thales |
| Eaton |
| Others |
Cost & Logistics Intelligence
Constrained supply chains for high-power semiconductors and specialized electronic components drive supplier behavior and pricing posture within the aircraft electric brake control system market. This scarcity allows manufacturers to maintain pricing power for advanced systems, influencing procurement strategies among airframers and MROs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for electric brake control systems. Price differentiation stems from stringent FAA and EASA certification levels, coupled with the customization required for specific aircraft platforms. Pricing pressure on new fully electric systems remains moderate, driven by high development costs. Airlines, focused on operational efficiencies, exhibit higher price sensitivity for aftermarket service contracts compared to aircraft manufacturers procuring for new production lines.
Supply Chain Analysis
Upstream sourcing of critical aerospace-grade semiconductors and specialized electronic components primarily draws from manufacturing hubs in the United States, East Asia, and Europe. The supply chain for electric brake control systems depends heavily on these specialized inputs. Single-source vulnerability for certain high-power components presents a structural risk. Downstream distribution runs directly to aircraft manufacturers for new production, and through MROs or direct airline channels for aftermarket installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global aircraft electric brake control system market is experiencing a cyclical recovery, propelled by renewed global air travel demand and subsequent new aircraft orders.
For Market Incumbents: Insulate core market share by deepening integration with major airframers in the United States and France, securing long-term service contracts. Invest heavily in R&D for next-generation 270V DC fully electric systems to counter emerging specialized component suppliers. Expand certification investment into evolving cybersecurity mandates under DO-326A/ED-202A, strengthening competitive barriers against new entrants. Reinforce channel control through strategic partnerships with established MRO networks.
For New Entrants and Emerging Players: Build out specialized electromechanical component expertise, targeting the retrofit market for business jets and regional aircraft. Penetrate the aftermarket service segment in rapidly expanding aviation hubs across Southeast Asia. Offer AI-driven predictive maintenance solutions for existing electrohydraulic systems, providing a clear value proposition for operational cost reduction. Focus on niche military aircraft applications requiring robust, specialized braking solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO providers and specialized component suppliers offering long-term service agreements. Long-term viability for this market hinges on the continued transition to more-electric aircraft architectures and stringent regulatory compliance. Target acquisition archetypes include firms with proprietary high-voltage electrification IP or strong regional MRO presence in Asia. The signal to watch is the adoption rate of 270V DC power architectures in new commercial aircraft programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen OEM Integration | Secures long-term supply agreements with major airframers, ensuring consistent demand for electric brake systems. |
| Invest in 270V DC Technology | Positions manufacturers at the forefront of high-voltage electrification, aligning with next-generation aircraft designs. |
| Expand Predictive Maintenance Offerings | Reduces airline operational costs and unscheduled downtime through AI-driven health monitoring solutions. |
| Strengthen Cybersecurity Compliance | Meets evolving regulatory mandates like DO-326A/ED-202A, critical for flight control system integrity. |
| Target Regional MRO Growth in Asia | Captures substantial aftermarket demand from growing airline fleets across Southeast Asia and the Middle East. |
Research Approach
Desk research of aerospace industry reports, regulatory filings from the FAA and EASA, and technical specifications from component manufacturers preceded structured interviews with aircraft manufacturers, airline procurement officers, MRO technical leads, and aerospace component engineers. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation methods were applied to derive market sizing and growth projections.
Assumptions regarding global economic growth, new aircraft production rates, and the pace of more-electric aircraft adoption were held fixed across the analysis window. The analytical framework modeled market segmentation across product type, application, installation type, end user, and regional market dynamics. Compound annual growth rates were derived from historical growth trends, projected technological advancements, and anticipated regulatory shifts. Key forecast inputs included global commercial aircraft order backlogs and projected MRO spending patterns.
Stress conditions across raw material price volatility, geopolitical tensions impacting supply chains, and unforeseen regulatory shifts in aviation safety were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these underlying assumptions. Cross-checking against ICAO emissions targets and major airframer production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Window Frame Market
Aircraft
Global Business Aircraft Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Hybrid Aircraft Market
Aircraft
America Freighter Aircraft Market
Aircraft
Civil Helicopter Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Utility Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Helicopter Lighting Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Global Aircraft De-Icing Market