
 Aerospace Winglet System Market | 2026-2036
Aerospace Winglet System Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Winglet System Market Outlook
North American composite fabrication capacity is hardening as OEMs secure long-term supply agreements for next-generation winglet programs. GKN Aerospace leverages its automated fiber placement expertise to dominate high-rate production lines for blended winglet variants. Aviation Partners sustains market presence through its proprietary split-scimitar designs that anchor retrofit demand among legacy fleet operators. Tamarack Aerospace competes with active winglet technology that reduces structural load factors without reinforcing wing boxes.
An aerospace winglet system comprises aerodynamic surfaces mounted at wingtips to reduce induced drag and improve fuel efficiency, typically constructed from carbon fiber reinforced polymer composites or aluminum alloys with tolerances measured in thousandths of an inch for laminar flow preservation. The device extends effective wingspan without increasing airport gate footprint constraints, delivering operational cost savings through reduced engine thrust requirements during climb and cruise phases. Passive winglets remain the volume leader across commercial aviation applications where proven durability supports airline fleet planning cycles, while active winglets represent the fastest-growing category as electrically actuated load-alleviation mechanisms enable retrofit on older airframes without structural modification. Composite materials command premium positioning in the material stack due to fatigue resistance and weight savings, though aluminum alloys retain significant share in military aviation programs where ballistic damage tolerance and field repairability override mass reduction priorities.
FAA airworthiness standards under Part 25 and EASA CS-25 certification frameworks govern winglet structural integrity, flutter characteristics, and ice protection system integration for commercial transport category aircraft. The EPA's aircraft emissions guidelines and ICAO Carbon Offsetting and Reduction Scheme for International Aviation create compliance pathways where winglet installations count toward fleet average efficiency improvements. Stakeholders must monitor evolving noise certification trade-offs as extended wingspan designs interact with airport operational constraints and gate compatibility requirements.
Market Dynamics
Retrofit economics for narrow-body fleets now dominate aerospace winglet system investment calculus, with fuel price volatility compressing payback period thresholds below three years for blended winglet installations across aging Boeing 737NG and Airbus A320ceo platforms.
Growth Catalysts
- ICAO CORSIA compliance pathways:Carbon offsetting obligations under the international aviation framework position winglet retrofits as verified emission reduction instruments, accelerating airline fleet modification schedules.
- Composite manufacturing automation:Automated fiber placement and resin transfer molding advances cut production cycle times for carbon fiber winglet structures, expanding OEM capacity for high-rate narrow-body programs.
- United States fleet concentration:Dense operational populations of eligible aircraft at major carriers create concentrated demand pockets for upgrade service providers and installation stations.
Market Restraints
- Prepreg carbon fiber supply concentration:Toray and Hexcel dominate aerospace-grade carbon fiber supply, creating input cost volatility exposure for composite winglet fabricators during capacity allocation cycles.
- Wing box reinforcement requirements:Passive winglet installations on legacy airframes frequently require structural modification to root attachments, extending downtime and eroding retrofit economics for older aircraft.
- Aluminum alloy substitution in military programs:Ballistic damage tolerance requirements in defense aviation sustain demand for metallic wingtip devices, fragmenting material standardization across customer segments.
Strategic Opportunities
- India narrow-body fleet expansion:IndiGo and Air India order backlogs for A320neo and 737 MAX families create greenfield winglet specification opportunities without retrofit complexity.
- Active winglet load alleviation:Electrically actuated morphing surfaces eliminate structural reinforcement needs, opening retrofit addressability to aircraft previously excluded from passive winglet economics.
- FAA STC streamlining initiatives:Supplemental type certification process reforms for fuel-saving modifications reduce approval timelines, compressing revenue realization for retrofit service providers.
Industry Challenges
- Aerospace composites technician scarcity:Automated fiber placement and autoclave operation skills face demographic retirement waves, constraining production scaling for high-rate winglet programs.
- Flutter certification complexity:Extended wingspan configurations require extensive flight test programs for aeroelastic stability validation, lengthening development timelines for novel winglet geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Winglet System Market |
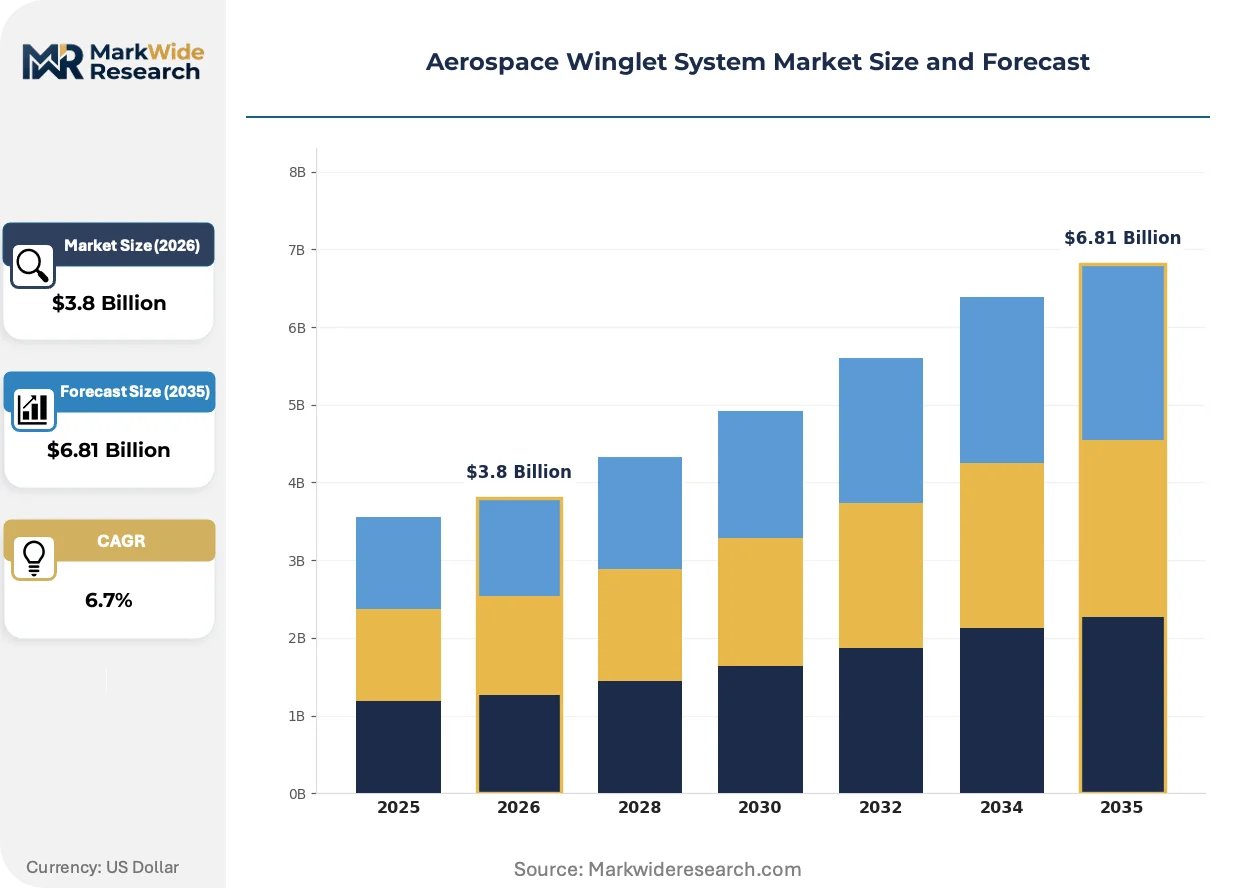
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Winglets, Passive Winglets, Hybrid Winglets, Blended Winglets Material: Aluminum Alloys, Composite Materials, Titanium Alloys, Steel Alloys Application: Commercial Aviation, Military Aviation, Cargo Transport, Business Aviation End User: OEMs, Aftermarket Providers, Aircraft Manufacturers, Airlines |
| Companies Covered | Aviation Partners, BLR Aerospace, FACC AG, GKN Aerospace, RUAG Group, Tamarack Aerospace, Winglet Technology, Daher, Korean Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Winglet System Market Strategic Shifts
Electrification of wingtip aerodynamic control surfaces is restructuring competitive positioning between passive and active winglet architectures, while regulatory carbon accounting frameworks reshape airline capital allocation toward verified fuel efficiency technologies.
Active winglet systems with integrated load alleviation mechanisms are overtaking passive blended designs in retrofit feasibility assessments for aging narrow-body fleets. Tamarack Aerospace's certified installations on Cessna Citation and Boeing 737 platforms demonstrate structural modification avoidance. This technological trajectory is compressing addressable market boundaries that previously excluded wing-strength-limited airframes from winglet economics.
EASA CS-25 Amendment 25-157 introduced strengthened ice protection requirements for extended wingtip devices, mandating integrated thermal or pneumatic systems for new certifications. European operators face compliance-driven replacement cycles for pre-amendment winglet installations. The regulatory pressure concentrates retrofit demand in EASA-member states with large A320ceo and 737NG populations.
Airline technical procurement teams now bundle winglet retrofits with engine upgrade programs and airframe heavy maintenance checks, consolidating vendor relationships and downtime windows. This pattern displaces standalone winglet sales through independent modification shops. The consolidation trend is most visible among United States ultra-low-cost carriers optimizing fleet unit economics across multiple efficiency interventions.
Aerospace Winglet System Market Segmentation
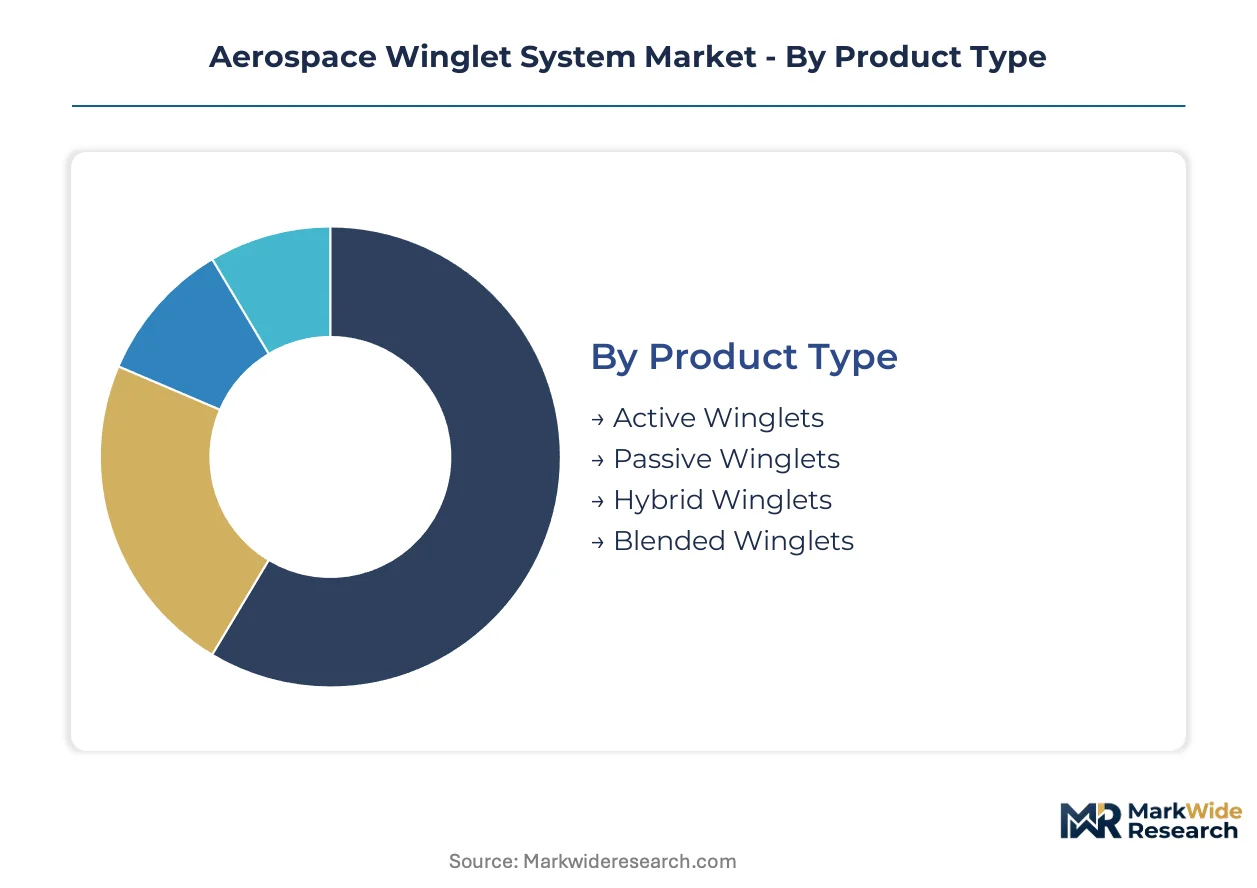
Winglet specification varies sharply across operator economics and airframe integration constraints. Procurement teams segment demand by retrofit feasibility, certification pathways, and fleet renewal timelines rather than aerodynamic performance alone.
Product Type:
Customization spans from bolt-on passive devices to electrically actuated active systems requiring flight control integration.
- Active Winglets:Electrically actuated surfaces with load alleviation mechanisms eliminate wing box reinforcement requirements. Airlines operating aging Boeing 737NG fleets in the United States prioritize these for retrofit feasibility where passive alternatives demand structural modification.
- Passive Winglets:Fixed aerodynamic surfaces constructed from composite laminates dominate current installation volumes. Major carriers with established maintenance programs favor proven durability and predictable certification timelines under FAA Part 25 standards.
- Hybrid Winglets:Dual-mode architectures combining passive geometry with limited active elements for gust response.
- Blended Winglets:Continuous wingtip transitions optimized for laminar flow preservation on clean-sheet designs.
Leading the category by volume: Passive Winglets. Expanding most quickly: Active Winglets.
Material:
Material selection trades mass reduction against damage tolerance and field repairability across military and commercial programs.
- Composite Materials:Carbon fiber reinforced polymer structures deliver fatigue resistance and weight savings critical for extended-range narrow-body operations. Automated fiber placement capacity at GKN Aerospace and other tier-one suppliers concentrates output for high-rate commercial programs.
- Aluminum Alloys:Metallic wingtip devices retain substantial share in defense aviation where ballistic damage tolerance overrides mass priorities. Military operators specify aluminum for expeditionary repairability without autoclave infrastructure.
- Titanium Alloys:High-strength fasteners and attachment hardware resist galvanic corrosion at composite interfaces.
- Steel Alloys:Legacy attachment fittings persist in retrofit applications requiring backward compatibility.
Composite Materials command premium positioning. Aluminum Alloys anchor military procurement.
Application:
Application segmentation reflects divergent certification rigor and operational duty cycles across fleet types.
- Commercial Aviation:Narrow-body retrofit programs concentrate demand as fuel price volatility compresses payback thresholds. United States ultra-low-cost carriers bundle winglet installations with engine upgrades and heavy maintenance checks.
- Military Aviation:Damage tolerance specifications and electromagnetic hardening requirements sustain metallic construction preferences. Defense procurement prioritizes field repairability over incremental fuel savings.
- Cargo Transport:High-cycle freighter operations prioritize durability for overnight hub-and-spoke networks.
- Business Aviation:Tamarack Aerospace's active winglet certifications on Cessna Citation platforms demonstrate retrofit addressability for smaller airframes.
Commercial Aviation generates dominant revenue share. Business Aviation climbs fastest on active technology penetration.
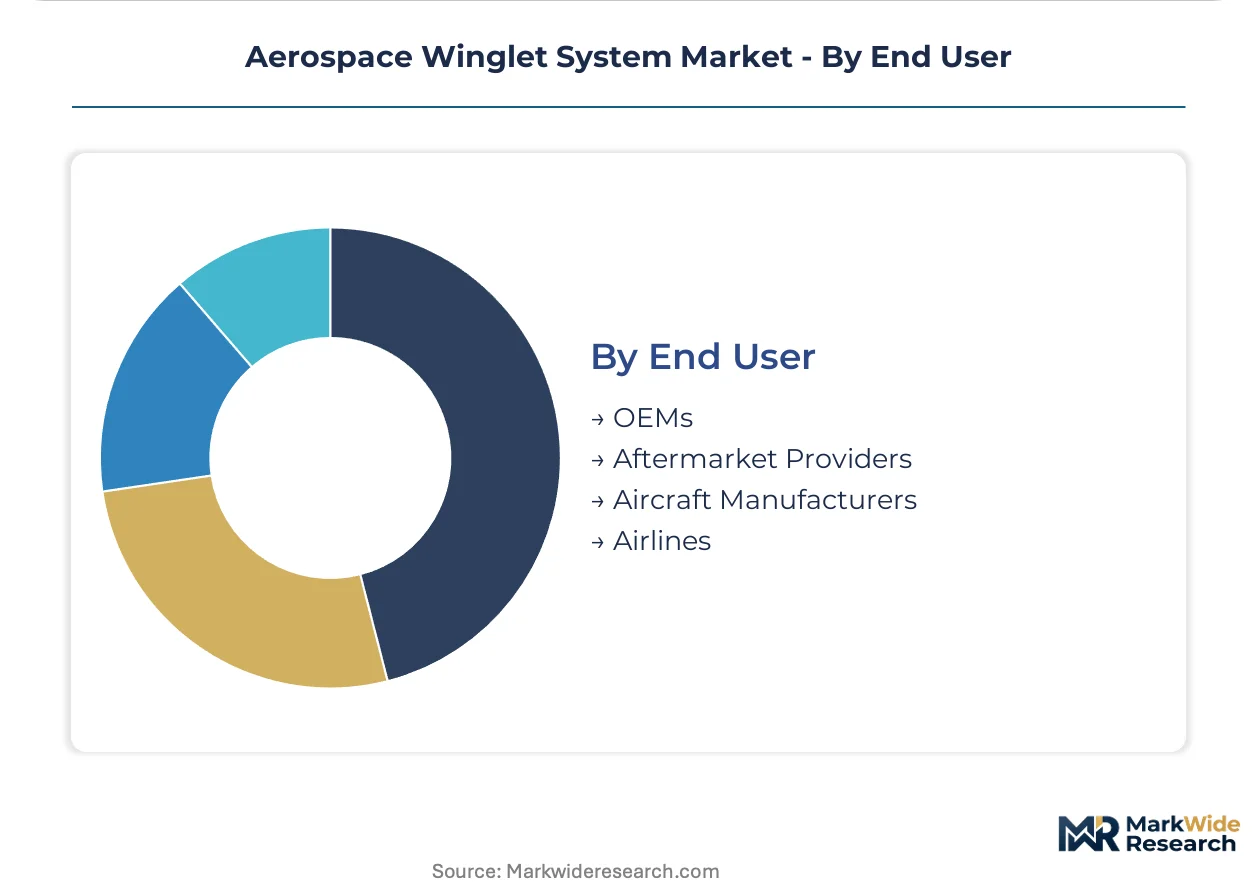
End User:
End user structure reflects divergent technical authority and integration depth across the value chain.
- OEMs:Boeing and Airbus specify winglet architectures at program launch, locking supplier relationships for production runs spanning decades. Factory-installed blended winglets on 737 MAX and A320neo families establish baseline fleet configurations.
- Aftermarket Providers:Supplemental type certification specialists capture retrofit demand from legacy fleet operators. Aviation Partners sustains market presence through proprietary split-scimitar designs and STC portfolio breadth.
- Aircraft Manufacturers:Regional jet and turboprop OEMs integrate winglets for competitive fuel efficiency claims.
- Airlines:Technical procurement teams evaluate winglet economics against alternative efficiency interventions including engine upgrades and operational improvements.
OEMs control specification for new aircraft. Aftermarket Providers capture retrofit volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber prepreg supply from Toray's Spartanburg facility and Hexcel's Salt Lake City operations anchors North American winglet fabrication capacity. These feedstock localities concentrate composite manufacturing expertise for commercial aviation programs.
United States
Major carriers including Southwest Airlines and United Airlines operate large Boeing 737NG and Airbus A320ceo fleets eligible for winglet retrofits. FAA Part 25 airworthiness standards govern supplemental type certification pathways for fuel-saving modifications. Wichita, Kansas hosts Aviation Partners' engineering operations serving the narrow-body retrofit market.
Germany
Lufthansa Group's technical divisions evaluate active winglet installations for aging A320ceo subfleets seeking CORSIA compliance. EASA CS-25 Amendment 25-157 mandates strengthened ice protection for extended wingtip devices. Hamburg's aviation cluster concentrates MRO capabilities handling bundled engine and winglet upgrade programs.
France
Air France-KLM procurement teams assess winglet economics against alternative fleet efficiency interventions. The country's national aviation regulator enforces EU emissions trading scheme compliance where winglet installations count toward verified carbon reductions. Toulouse's aerospace corridor integrates winglet specification into A320neo family production planning.
China
China Eastern and China Southern operate expanding narrow-body fleets creating greenfield winglet specification opportunities. The Ministry of Industry and Information Technology promotes domestic composite manufacturing capacity for aviation applications. Tianjin's Airbus final assembly line specifies factory-installed blended winglets for regional delivery aircraft.
Japan
ANA Holdings and Japan Airlines prioritize fuel efficiency technologies meeting corporate sustainability commitments. The Ministry of Economy, Trade and Industry supports carbon fiber research through public-private partnerships with Toray Industries. Nagoya's Chubu region concentrates aerospace supplier networks serving Boeing and Airbus tier-one contracts.
Aerospace Winglet System Market Competitive Environment
Global majors compete with regional champions across certification breadth and production automation depth. The market structure concentrates around tier-one aerospace suppliers with long-term OEM relationships and specialized retrofit houses with proprietary STC portfolios. Two strategic archetypes dominate: integrated composite fabricators leveraging automated fiber placement for high-rate production, and engineering specialists commercializing active load-alleviation technologies. Capacity expansion and strategic licensing agreements represent the dominant competitive moves reshaping supplier positioning.
Among North American specialists, Aviation Partners exemplifies the retrofit-focused archetype through its split-scimitar design portfolio, while Tamarack Aerospace occupies a position representing active winglet innovation with electrically actuated load alleviation. European fabricator GKN Aerospace anchors the integrated composite tier with automated production capabilities. These three companies illustrate the geographic and technological segmentation defining competitive boundaries across passive and active winglet architectures.
| Leading Market Players |
|---|
| Aviation Partners |
| BLR Aerospace |
| FACC AG |
| GKN Aerospace |
| RUAG Group |
| Tamarack Aerospace |
| Winglet Technology |
| Daher |
| Korean Air |
| Others |
Value Chain & Pricing Dynamics
Automated fiber placement technician pools in Kansas and Washington State concentrate scarce composite fabrication skills, widening labor-cost spreads between premium OEM-integrated winglets and standard aftermarket retrofits. FAA Part 25 supplemental type certification complexity adds service-bundling premiums that separate turnkey installation packages from hardware-only transactions.
Pricing Analysis
Warranty and installation support bundling distinguishes premium-tier active winglet offerings from unbundled passive hardware sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from major carriers. Price erosion runs through passive retrofit segments as Aviation Partners and competing STC holders compress margins on legacy Boeing 737NG installations. Ultra-low-cost carriers exhibit highest price sensitivity, while flagship network carriers prioritize performance guarantees and regulatory compliance over unit cost minimization.
Supply Chain Analysis
Carbon fiber prepreg supply rests on Toray's Spartanburg facility and Hexcel's Salt Lake City operations, with Japanese precursor feedstock anchoring upstream material flows. Aerospace-grade epoxy resin formulations and autoclave curing infrastructure constitute critical production dependencies. Single-source vulnerability concentrates in Toray's aerospace carbon fiber allocation cycles, where capacity prioritization toward defense programs constrains commercial winglet fabricator access. Distribution runs through tier-one supplier direct contracts with Boeing and Airbus, supplemented by aftermarket channel partners serving retrofit modification stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace winglet system market sits in active-passive technology transition, with electrically actuated load alleviation displacing structural reinforcement requirements that previously excluded aging narrow-body fleets from retrofit economics.
For Market Incumbents: Hedge against active winglet displacement by securing long-term composite supply agreements with Toray and Hexcel while accelerating automated fiber placement capacity expansion in Wichita and Bristol. Passive winglet specialists face margin compression from Tamarack Aerospace's structural-modification-free retrofit addressability; vertical integration into STC certification services preserves installer relationships against bundled engine-upgrade competition.
For New Entrants and Emerging Players: Capture white-space opportunity in Indian narrow-body greenfield specifications, where IndiGo and Air India order backlogs for A320neo and 737 MAX families bypass retrofit complexity entirely. Business aviation active winglet retrofits offer penetrable entry point given lower certification barriers and concentrated Cessna Citation operator bases. Go-to-market positioning should emphasize CORSIA compliance verification and bundled maintenance support.
For Investors and Strategic Acquirers: The window for entry favors active winglet technology specialists with certified load-alleviation platforms and established FAA STC portfolios. Long-term viability hinges on electrification integration depth and airline technical procurement team relationships. Monitor FAA supplemental type certification streamlining progress as inflection signal for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Manufacturing Automation | GKN Aerospace's automated fiber placement capacity secures high-rate production lines for Boeing and Airbus narrow-body programs. |
| Active Winglet Certification Expansion | Tamarack Aerospace's FAA STC portfolio for Boeing 737 platforms demonstrates structural-modification-free retrofit feasibility. |
| Long-term Carbon Fiber Supply Agreement | OEM locked pricing with Toray and Hexcel insulates against aerospace-grade prepreg allocation volatility. |
| Supplemental Type Certification Streamlining | FAA process reforms for fuel-saving modifications compress approval timelines for retrofit service providers. |
| Indian Narrow-body Fleet Partnership | Greenfield winglet specification opportunities at IndiGo and Air India bypass retrofit complexity and structural reinforcement costs. |
Study Parameters
Document review covered FAA Part 25 airworthiness directives, EASA CS-25 amendment filings, and ICAO CORSIA technical documentation, complemented by interviews with airline fleet planning directors, MRO station managers, composite fabrication engineers, and STC certification specialists. Secondary validation drew from SEC 10-K disclosures of tier-one suppliers, Boeing and Airbus production forecasts, and carbon fiber trade flow data. Bottom-up installation volume estimates triangulated against top-down fleet eligibility assessments.
Segmented outputs across product type, material composition, application category, and end-user channel informed the analytical framework over the projection horizon. CAGRs derived from installation run-rate modeling incorporating fuel price elasticity, retrofit payback period thresholds, and regulatory compliance timelines. Industry-specific forecast inputs included narrow-body fleet age distributions and EASA ice protection mandate compliance schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to composite material cost volatility and active winglet technology adoption curves. Forecasts reflect documented assumptions regarding fuel price trajectories, certification timeline reforms, and airline capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Aircraft Leasing Market
Aircraft
Freighter Aircraft Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Aviation Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Utility Aircraft Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Aircraft Cables Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
France Aviation Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market