
 Online in-Flight Shopping Market | 2026-2036
Online in-Flight Shopping Market Size, Share, and Industry Trends Forecast 2026-2036
Online in-Flight Shopping Market Analysis
Asset-light leasing of onboard retail systems is narrowing the competitive field for smaller carriers seeking turnkey shopping platforms. Panasonic Avionics Corporation leverages its integrated IFE-to-retail pipeline to control the full passenger touchpoint. Deutsche Lufthansa AG sustains margin-rich duty-free operations through its captive European hub network. EasyJet PLC anchors its low-cost model with pre-order digital channels that reduce onboard inventory weight.
Online in-flight shopping denotes the transactional ecosystem enabling passengers to browse, order, and pay for retail goods during air travel through seatback screens, personal devices, or crew-assisted interfaces, typically operating on satellite or air-to-ground connectivity with payment tokenization for offline transaction completion. The system's primary commercial purpose is to unlock ancillary revenue streams for airlines while capturing passenger attention during captive flight durations. Duty-free items and electronics dominate product-type revenue pools, with accessories showing the fastest expansion as airlines curate compact, high-margin SKUs for constrained cabin storage. Mobile payments now lead payment-method growth, displacing cash and loyalty-point redemptions as carriers prioritize frictionless, digitally native checkout experiences.
The US FAA mandates specific fire-safety testing for lithium-powered electronics sold onboard, shaping product eligibility and inventory planning for carriers operating in American airspace. EASA's CE marking requirements for consumer goods sold by EU-registered airlines standardize quality thresholds across European routes. Japan's METI guidelines on cross-border e-commerce taxation influence how Japanese carriers structure duty-free pricing for international segments. Stakeholders must monitor evolving passenger-data privacy rules as biometric payment authentication and personalized retail targeting expand across airline digital platforms.
Market Dynamics
Satellite-to-cabin connectivity upgrades are compressing transaction latency from minutes to seconds, enabling real-time inventory synchronization and biometric payment authentication that transforms duty-free retail from a static catalog into a dynamic, personalized commerce layer.
Growth Catalysts
- IFE-to-retail integration:Seatback screen ecosystems now embed shopping interfaces within entertainment workflows, capturing passenger attention during captive flight durations and converting browsing into transactions without device switching.
- FAA fire-safety protocols:Standardized lithium-battery testing for onboard electronics creates predictable product eligibility frameworks that streamline inventory planning for carriers operating in American airspace.
- East Asian hub concentration:Singapore, Dubai, and Seoul generate disproportionate premium-cabin traffic where business travelers exhibit elevated propensity for luxury accessories and duty-free electronics purchases.
Market Restraints
- Connectivity infrastructure cost:Satellite bandwidth leasing and air-to-ground network maintenance impose recurring operational expenditures that compress margins on low-yield routes.
- Cabin storage physics:Limited galley and overhead compartment volume restricts SKU breadth, forcing carriers toward compact, high-margin categories and excluding bulky merchandise.
- EASA CE marking friction:Quality certification requirements for consumer goods sold by EU-registered airlines extend procurement timelines and exclude non-compliant suppliers from European route networks.
Strategic Opportunities
- Pre-order digital channels:Ground-based browsing and payment with gate-side or seat delivery eliminates onboard inventory weight while expanding product selection beyond physical cabin constraints.
- METI cross-border tax frameworks:Japan's evolving e-commerce duty structures create pricing optimization pathways for Japanese carriers on international segments.
- Mobile payment convergence:Integration of tokenized wallets with loyalty program currencies enables seamless checkout experiences that displace cash and manual card processing.
Industry Challenges
- Biometric data governance:Passenger privacy regulations governing facial recognition and payment authentication create compliance complexity across multi-jurisdictional flight networks.
- Legacy IFE integration:Retrofitting older seatback systems with modern retail interfaces demands hardware upgrades and software certification cycles that disrupt fleet deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online in-Flight Shopping Market |
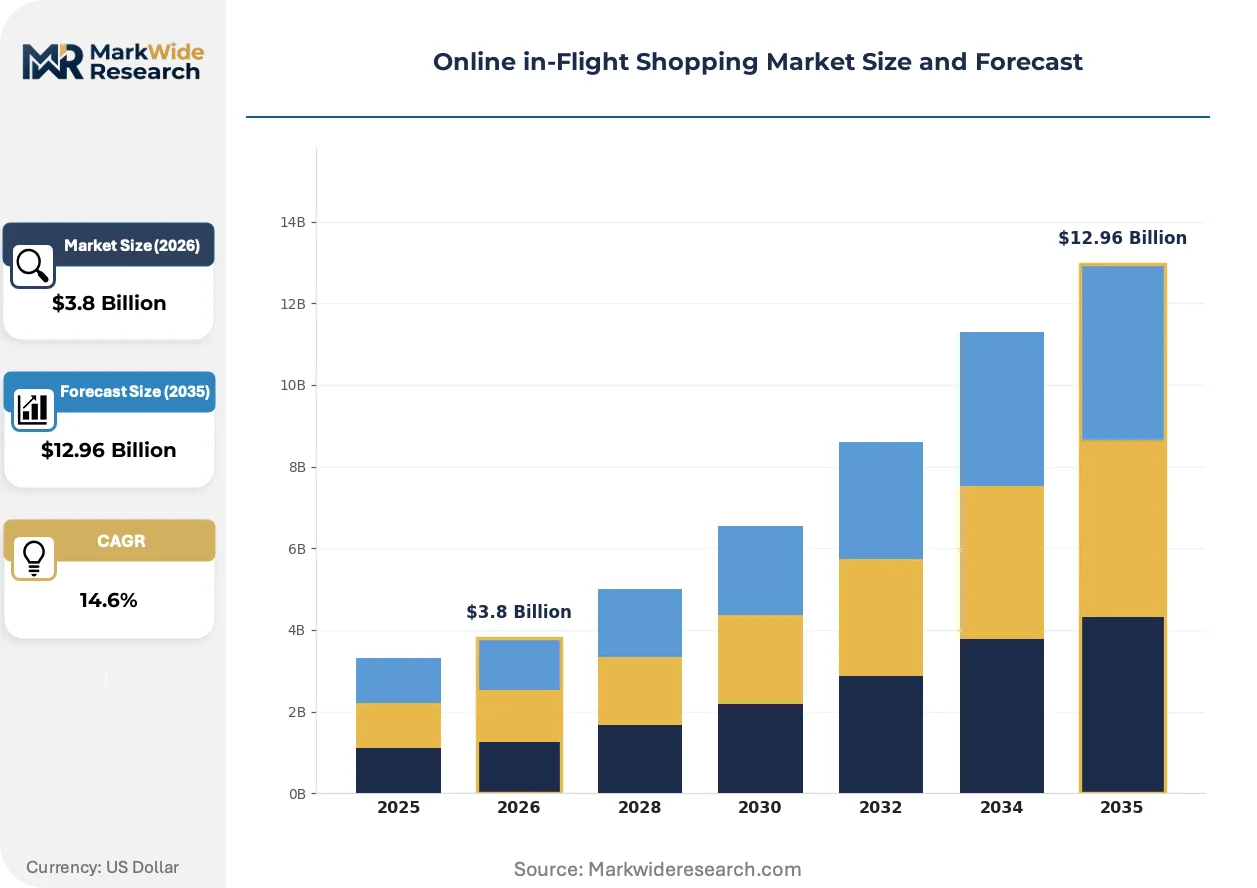
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Accessories, Duty-Free Items Customer Segment: Business Travelers, Tourists, Frequent Flyers, Families Payment Method: Credit Cards, Mobile Payments, Loyalty Points, Cash Sales Channel: Airline Websites, Mobile Apps, In-Flight Catalogs, Third-Party Platforms |
| Companies Covered | The Emirates Group, Deutsche Lufthansa AG, EasyJet PLC, Capital A Berhad, British Airways PLC, Panasonic Avionics Corporation, Thales Group, Anuvu, SITA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online in-Flight Shopping Market Emerging Trajectories
Retail technology stacks are fragmenting across proprietary airline platforms and third-party middleware, creating interoperability pressures that favor modular, API-first architectures over monolithic legacy systems.
Edge computing nodes deployed within aircraft cabins are hybridizing transaction processing, enabling payment tokenization and inventory queries to execute locally while synchronization occurs asynchronously with ground systems. Full-service carriers retrofitting wide-body fleets adopt these distributed architectures fastest. This hybridizing infrastructure compresses checkout latency and reduces satellite bandwidth consumption.
GDPR and emerging biometric privacy frameworks in Europe impose data-localization requirements on passenger purchasing histories and authentication records. Airlines must architect region-specific data residency for retail platforms serving EU routes. Premium carriers with transatlantic networks face the steepest compliance retrofit costs.
Business traveler procurement preferences are gravitating toward pre-flight digital selection with seamless fulfillment, displacing traditional impulse browsing at cruise altitude. Corporate travel policies increasingly mandate pre-approved expense categories that favor structured pre-order channels over discretionary onboard purchases. This behavioral pivot is most pronounced in East Asian carrier hubs where mobile-first commerce penetration exceeds other regions.
Online in-Flight Shopping Market Segmentation
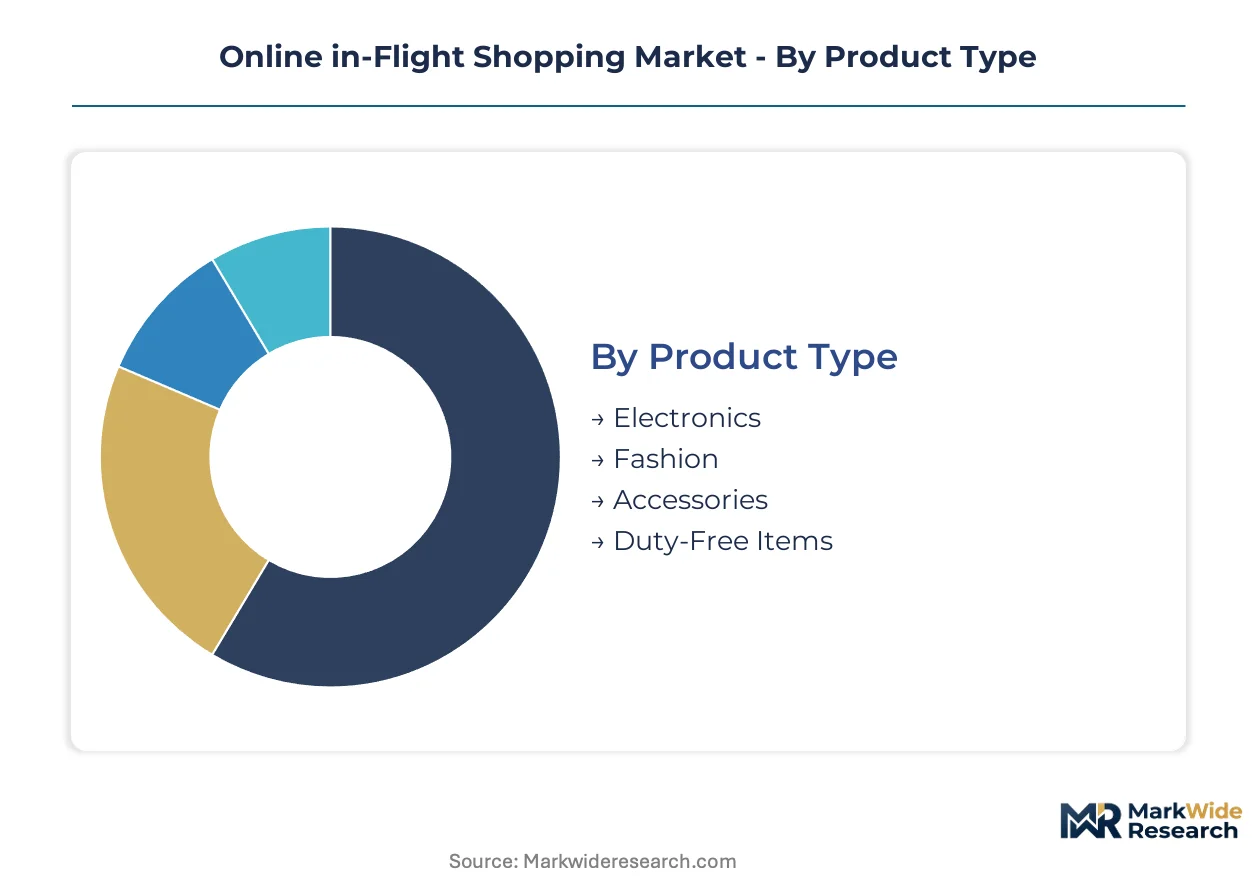
Segmentation in online in-flight shopping reveals how passenger demographics, transaction preferences, and fulfillment constraints shape inventory curation and platform design. Airlines calibrate product mix and interface complexity against cabin storage limits and connectivity bandwidth. Each dimension carries distinct margin profiles and operational requirements that influence carrier strategy.
Product Type:
Use-case spectrum spans impulse convenience purchases to planned luxury acquisitions, with physical constraints and duty regulations filtering eligible merchandise.
- Electronics:Compact, high-value devices with lithium power sources dominate revenue per cubic meter of galley storage. Demand concentrates on East Asian carrier routes where business travelers prioritize noise-canceling headphones and portable chargers during long-haul segments. FAA fire-safety testing requirements filter supplier eligibility for US-registered fleets.
- Accessories:Leather goods, eyewear, and compact jewelry offer the highest margin-to-weight ratio among physical inventory categories. Singapore and Dubai hub traffic drives disproportionate volume for luxury accessories in premium cabins. Airlines curate SKUs specifically for constrained overhead compartment dimensions.
- Duty-Free Items:Tax-advantaged fragrances and spirits remain staple categories with established passenger recognition.
- Fashion:Apparel faces steeper cabin storage constraints, limiting selection to foldable, compact items.
The dominant share belongs to Electronics, while Accessories is closing the gap fastest.
Customer Segment:
Cost tier differentiation separates high-frequency corporate travelers from discretionary leisure purchasers, with loyalty status and booking class correlating to transaction value.
- Business Travelers:Time-constrained passengers with elevated disposable income and employer expense policies favor pre-order digital channels and premium SKU categories. Corporate procurement policies increasingly mandate structured pre-approval workflows that favor ground-based selection over discretionary cruise-altitude browsing.
- Frequent Flyers:Loyalty program members with accumulated points represent the most digitally engaged segment, driving mobile payment and redemption transaction volume. Japanese carriers leverage METI cross-border tax frameworks to optimize point-based pricing for this cohort on international segments.
- Tourists:Leisure passengers exhibit higher price sensitivity and duty-free bargain-seeking behavior.
- Families:Group travelers prioritize convenience items and entertainment products for children during flight durations.
Business Travelers command the premium tier by spend per transaction, though Frequent Flyers generate the highest purchase frequency.
Payment Method:
Application context ranges from offline tokenized processing at cruise altitude to real-time ground-based settlement, with connectivity availability determining viable options.
- Mobile Payments:Tokenized wallet integration enables seamless checkout without physical card handling, compressing transaction time and crew workload. Demand concentrates in East Asian markets where smartphone-native commerce penetration exceeds other geographies. GDPR compliance requirements shape data handling for EU route networks.
- Credit Cards:Traditional card-present and tokenized card-not-present methods retain dominance on legacy IFE systems lacking biometric authentication capability. European routes face extended procurement timelines due to EASA CE marking friction for payment terminal hardware.
- Loyalty Points:Program currency redemption attracts price-sensitive segments and drives engagement with airline co-branded financial products.
- Cash:Physical currency handling persists on short-haul routes with limited connectivity infrastructure and older fleet configurations.
Mobile Payments is displacing legacy methods fastest, while Credit Cards retain the largest transaction volume base.
Sales Channel:
Volume concentration varies by fleet connectivity maturity, with pre-flight digital channels reducing onboard inventory weight while expanding SKU breadth.
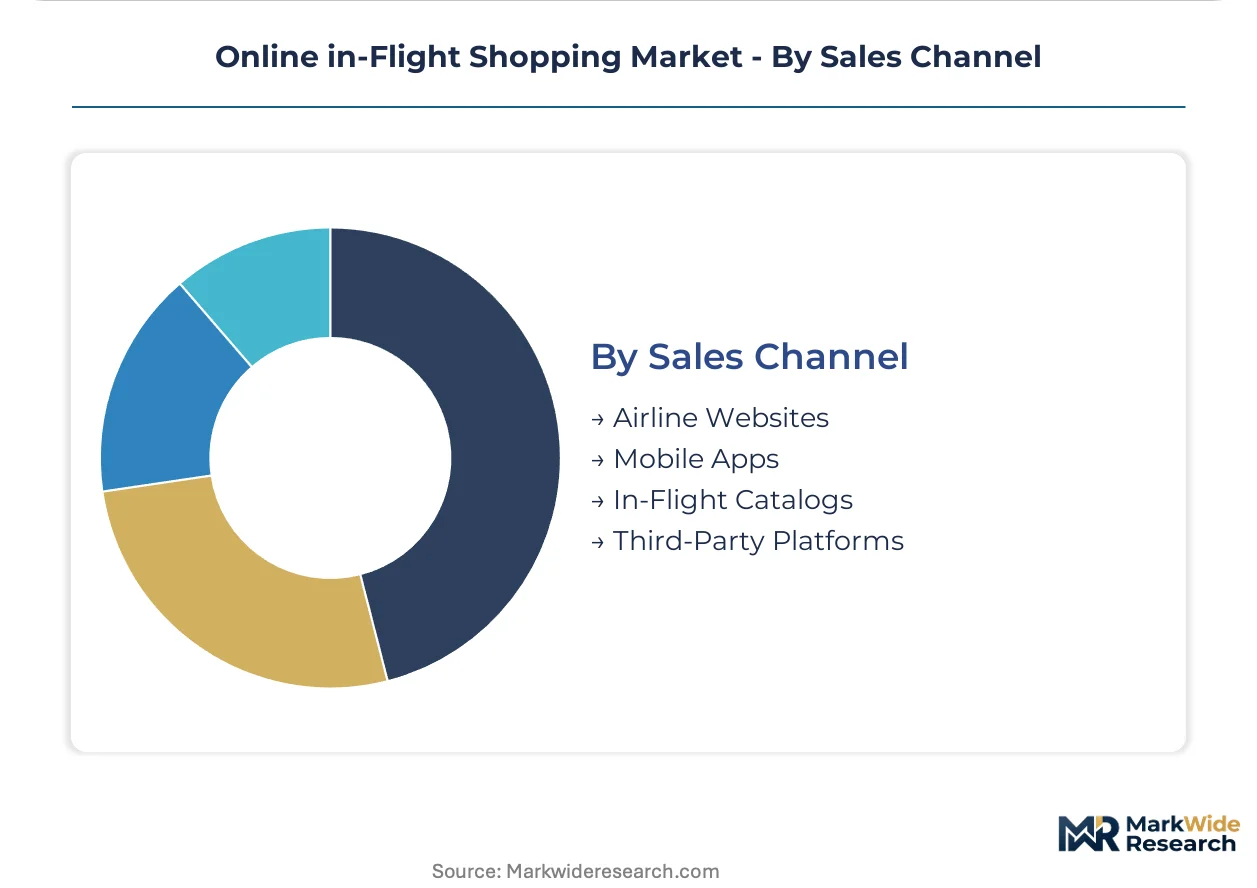
- Mobile Apps:Ground-based browsing with gate-side or seat delivery eliminates cabin storage constraints and enables dynamic personalization based on passenger history. EasyJet anchors its low-cost operational model on this channel to minimize onboard inventory weight. Pre-order penetration is most pronounced in East Asian carrier hubs.
- Airline Websites:Web-based platforms capture advance purchase intent during booking and check-in workflows, integrating with loyalty program authentication. Full-service carriers with wide-body retrofit programs prioritize website-to-IFE data synchronization.
- In-Flight Catalogs:Seatback screen and printed material interfaces retain relevance for captive attention capture during flight durations.
- Third-Party Platforms:Aggregator and middleware solutions enable smaller carriers to access turnkey retail infrastructure without proprietary development.
Mobile Apps are expanding most quickly by transaction growth rate, while Airline Websites maintain the broadest passenger reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation regulators in multiple jurisdictions are mandating upgraded connectivity standards that enable real-time payment processing, reshaping where carriers invest in retail infrastructure. Hub concentration patterns follow premium passenger density and satellite bandwidth availability.
United States
FAA fire-safety testing protocols for lithium-powered electronics create standardized product eligibility frameworks that streamline inventory planning for US-registered carriers. The FAA mandates specific testing thresholds that filter supplier participation. Dallas-Fort Worth and Atlanta hubs host concentrated retail technology deployments as American and Delta retrofit wide-body fleets with integrated IFE-to-shopping platforms.
Germany
EASA CE marking requirements for consumer goods sold by EU-registered airlines extend procurement timelines and exclude non-compliant suppliers from European route networks. GDPR data-localization rules impose passenger purchasing history residency requirements. Frankfurt anchors Lufthansa's margin-rich duty-free operations through its captive hub network and premium-cabin traffic concentration.
Singapore
Changi Airport's status as a premium transfer hub generates disproportionate business traveler volume with elevated propensity for luxury accessories purchases. The Civil Aviation Authority of Singapore coordinates with carriers on cross-border payment authentication standards. Singapore Airlines leverages its hub position to curate high-margin SKUs specifically for constrained cabin storage on long-haul segments.
Japan
METI guidelines on cross-border e-commerce taxation influence how Japanese carriers structure duty-free pricing for international segments. Business traveler procurement policies increasingly mandate pre-approved expense categories. Tokyo-Narita and Haneda clusters concentrate mobile payment integration as ANA and JAL optimize loyalty-point redemption workflows for frequent flyers.
United Arab Emirates
Dubai's position as a global premium travel hub drives demand for luxury accessories and duty-free electronics among transfer passengers. The General Civil Aviation Authority facilitates harmonized payment processing standards across UAE-registered carriers. Emirates Group sustains retail operations through its Dubai hub concentration where premium cabin ratios remain elevated on long-haul routes.
Online in-Flight Shopping Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Full-service carriers with captive hub networks and integrated IFE systems occupy the premium tier, while low-cost operators rely on asset-light third-party middleware. Technology providers supplying connectivity and payment infrastructure form a concentrated supplier layer. Competitive moves center on fleet retrofit programs for legacy IFE integration and pre-order digital channel expansion that reduces onboard inventory weight.
Within the integrated systems tier, Panasonic Avionics Corporation and Thales Group exemplify technology providers controlling the full passenger touchpoint from entertainment through retail. Deutsche Lufthansa AG anchors the full-service carrier archetype through its captive European hub network and margin-rich duty-free operations. These three entities occupy positions that reflect divergent strategic pathways: hardware-integrated platform control versus hub-network retail monetization.
| Leading Market Players |
|---|
| The Emirates Group |
| Deutsche Lufthansa AG |
| EasyJet PLC |
| Capital A Berhad |
| British Airways PLC |
| Panasonic Avionics Corporation |
| Thales Group |
| Anuvu |
| SITA |
| Others |
Supply Flow & Price Mechanics
The Hong Kong-Singapore air freight corridor shapes cost dynamics for compact electronics inventory, concentrating supply planning around East Asian manufacturing clusters while forcing carriers toward premium-mid-economy pricing differentiation based on connectivity tier and cabin class.
Pricing Analysis
Certification level creates the primary spread, with FAA fire-safety tested lithium devices commanding premium placement against non-tested alternatives. Pricing stratifies across premium, standard, and economy tiers based on connectivity bandwidth allocation and loyalty program integration depth. Cost compression in the standard tier is intensifying because satellite bandwidth leasing expenses outpace ancillary revenue growth on thin-margin routes. Leisure tourists exhibit highest price sensitivity, while corporate travelers with pre-approved expense policies show lowest sensitivity to SKU premiums.
Supply Chain Analysis
Electronics manufacturing services in China, South Korea, and Taiwan hold dominant capacity for noise-canceling headphones, portable chargers, and compact accessories. Production draws from lithium battery cell suppliers in Japan and South Korea, semiconductor components from Taiwanese foundries, and precision plastics from Guangdong province. Single-source vulnerability concentrates in satellite connectivity hardware, where two vendors control inflight network infrastructure. Distribution runs through airline procurement consortia and direct OEM relationships, with third-party middleware platforms serving budget carrier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ground-based airport retail and e-commerce platforms pose a direct substitution threat to inflight shopping, capturing passenger attention during dwell time with superior product breadth and immediate fulfillment.
For Market Incumbents: Entrench hub-network retail monetization by deepening captive passenger flow control at Singapore, Dubai, and Frankfurt transfer terminals. Integrate pre-order digital channels with loyalty program authentication to displace discretionary cruise-altitude browsing. Satellite bandwidth cost inflation threatens margin sustainability on long-haul routes without pre-flight transaction migration. For New Entrants and Emerging Players: Pursue asset-light middleware deployment for regional carriers lacking proprietary IFE development resources. Southeast Asian low-cost operators represent the most penetrable segment, with underserved fleets seeking turnkey retail platforms. A white-label pre-order app with gate-side fulfillment integration offers the cleanest go-to-market angle against established hardware-integrated competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from full-service carrier retail divisions seeking operational focus on core aviation services. Long-term viability hinges on whether inflight shopping captures sufficient passenger wallet share against airport retail and mobile commerce alternatives. Watch biometric payment authentication adoption curves as the signal for platform technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IFE-to-Retail Platform Integration | Panasonic Avionics controls full passenger touchpoints from entertainment through checkout, locking in carrier exclusivity. |
| Pre-Order Digital Channel Expansion | EasyJet's ground-based browsing model eliminates onboard inventory weight while expanding SKU selection beyond cabin constraints. |
| Satellite Connectivity Upgrade | Real-time inventory synchronization and biometric payment authentication transform static catalogs into dynamic commerce layers. |
| Biometric Payment Infrastructure | Tokenized wallet integration with loyalty currencies displaces cash handling and compresses transaction latency for crew efficiency. |
| Regulatory Compliance Investment | EASA CE marking and GDPR data-localization requirements filter supplier eligibility and impose retrofit costs on transatlantic networks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across airline ancillary revenue directors, inflight retail category managers, IFE platform engineers, and satellite connectivity procurement leads. Secondary validation incorporated FAA certification databases, EASA regulatory filings, airline annual reports, and customs trade data for duty-free electronics flows. Bottom-up passenger transaction modeling triangulated against top-down carrier ancillary revenue disclosures.
Calibration anchored volume projections to fleet retrofit schedules and connectivity deployment timelines across the analysis window. Segmentation dimensions spanned product type, customer segment, payment method, and sales channel, with additional modeling for regional regulatory cluster effects. CAGRs derived from historical ancillary revenue trajectories and passenger volume growth assumptions, incorporating satellite bandwidth cost curves and mobile payment penetration rates as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in jet fuel pricing, business travel recovery rates, or cross-border e-commerce tax regimes would shift the trajectory. Forecasts reflect documented assumptions regarding connectivity infrastructure rollout and passenger behavioral persistence. Quarterly review of fleet retrofit announcements and regulatory guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Global Business Jets Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
General Aviation Market
Aircraft
Helicopter Wheels Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
US Military Aviation Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Evtol Aircraft Market
Aircraft
Air Starter Market
Aircraft
Aviation Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Military Rotorcraft Market