
 Europe Business Jet Market | 2026-2036
Europe Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Business Jet Market Foresight
Corporate flight departments and ultra-high-net-worth private individuals is bifurcating demand across the Europe business jet landscape, with charter operators capturing incremental share from traditional whole-aircraft ownership. Bombardier Inc. leverages its Global family manufacturing footprint in Northern Ireland to sustain delivery leadership across the heavy jet category. Dassault Aviation SA anchors French aerospace heritage through Falcon platform specialization in intercontinental range performance. Gulfstream Aerospace Corporation competes on cabin altitude and speed benchmarks that differentiate transatlantic-capable offerings.
A business jet denotes a fixed-wing aircraft configured for private or executive transport, typically pressurized to cabin altitudes below 6,000 feet at cruise and powered by turbofan engines delivering thrust-to-weight ratios optimized for 40,000- to 51,000-foot operational ceilings. These aircraft serve time-sensitive executive mobility, medical evacuation, and government transport missions where schedule control outweighs commercial airline economics. Light jet and mid-size jet categories attract fleet renewal investment from charter operators seeking fuel efficiency per seat-mile, while heavy jet configurations command premium positioning among corporate end users prioritizing cabin connectivity and range. The technology dimension concentrates margin pools in avionics and cabin connectivity upgrades rather than airframe production.
EASA type certification standards and EU Green Deal aviation decarbonization targets constrain powertrain development timelines while creating compliance-based market access filters for non-European OEMs. REACH chemical regulations and the F-Gas Regulation govern materials selection and cabin climate system refrigerant specifications across European-registered fleets. Stakeholders must monitor SAF infrastructure buildout at Le Bourget, Geneva, and Farnborough against airframe retrofit certification cycles to align fleet planning with emerging operational constraints.
Market Dynamics
EASA certification protocols for sustainable aviation fuel compatibility are reshaping OEM engineering priorities across the continent, forcing airframe manufacturers to accelerate retrofit cycles and recalibrate supply chain specifications for drop-in fuel readiness.
Growth Catalysts
- EU Green Deal aviation decarbonization targets:Mandates for fleet emissions intensity reductions are pulling forward replacement demand for newer, more efficient airframes among corporate flight departments.
- Charter operator fleet renewal:Fractional ownership platforms in France, Switzerland, and the United Kingdom are expanding managed aircraft pools to capture price-sensitive executive mobility demand.
- SAF infrastructure buildout:Dedicated fueling capabilities at Le Bourget, Geneva, and Farnborough are enabling operational compliance for early-adopter fleet operators.
Market Restraints
- REACH chemical regulations:Restrictions on composite matrix resins and surface treatments are constraining material substitution pathways for cabin interior retrofits.
- F-Gas Regulation refrigerant phase-down:Cabin climate system redesigns face extended recertification timelines as hydrofluorocarbon alternatives require new thermal engineering validation.
- Powertrain development cost concentration:Hybrid-electric propulsion research expenditures cluster among a narrow set of airframers with captive R&D budgets.
Strategic Opportunities
- Medical evacuation mission expansion:Specialized aeromedical configurations for Eastern European healthcare networks remain underserved by existing charter capacity.
- CSRD sustainability disclosure mandates:Corporate flight departments face new reporting requirements that favor outsourced fleet management over in-house operations.
- Avionics-cabin connectivity convergence:Integration of satellite communications with flight management systems opens aftermarket upgrade revenue pools for third-party integrators.
Industry Challenges
- EASA type certification timeline compression:SAF compatibility approvals for legacy airframes are colliding with airworthiness directive backlogs at the agency's Cologne headquarters.
- Specialized MRO technician scarcity:Turbofan engine overhaul capacity for specific thrust classes concentrates in Northern Italy and Southern Germany repair stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Business Jet Market |
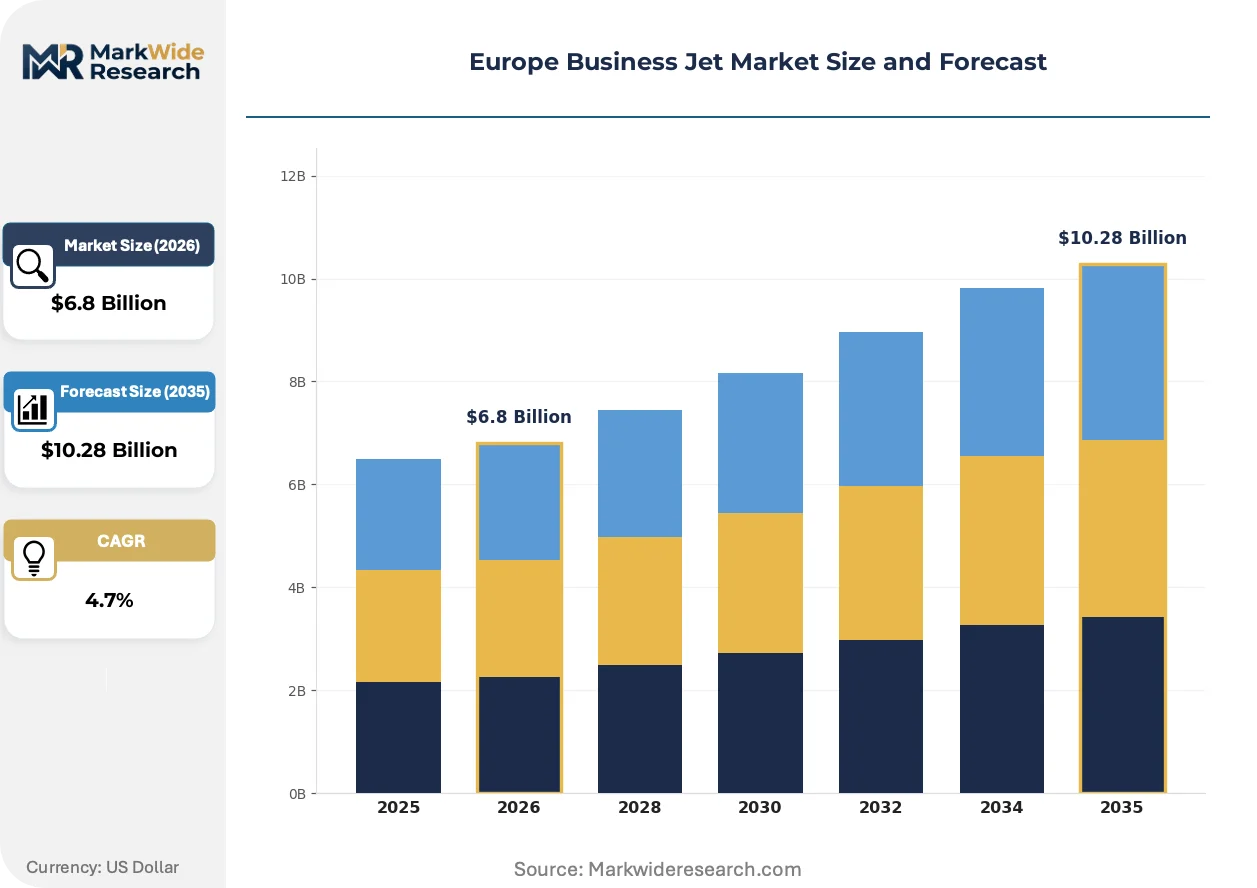
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Single Engine, Light Jet, Mid-Size Jet, Heavy Jet End User: Corporate, Government, Charter Operators, Private Individuals Service Type: Maintenance, Charter, Management, Brokerage Technology: Avionics, Engine, Cabin Connectivity, Safety Systems |
| Companies Covered | Bombardier Inc., Gulfstream Aerospace Corporation, Dassault Aviation SA, Textron Inc., Embraer S.A., Pilatus Aircraft Ltd, Airbus Corporate Jets, Honda Aircraft Company, Cirrus Design Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Business Jet Market Shifts & Advancements
Aviation connectivity architectures are undergoing fundamental restructuring as satellite constellation density enables new service models. Three distinct vectors are compressing technology adoption cycles across the European business jet installed base.
Next-generation cabin management systems is miniaturizing processor footprints and fiber-optic distribution weights. Charter operators retrofitting mid-size jet fleets are adopting these systems at twelve-to-eighteen-month refresh intervals. The technology is compressing upgrade economics for aircraft aged fifteen to twenty years.
EU F-Gas Regulation refrigerant specifications are forcing climate system OEMs to validate hydrofluoroolefin alternatives under accelerated EASA environmental qualification protocols. Industrial consequence includes eighteen-to-twenty-four-month extension of supplemental type certificate timelines for cabin modifications. Heavy jet configurations with complex multi-zone climate control face the most severe compliance cost inflation.
Flight departments are unbundling aircraft management from crew provisioning and maintenance execution. Third-party platform operators in the United Kingdom and Switzerland are displacing traditional fixed-base operator bundles with itemized service menus. This pattern concentrates among corporate users with existing in-house aviation expertise seeking cost transparency.
Europe Business Jet Market Segmentation
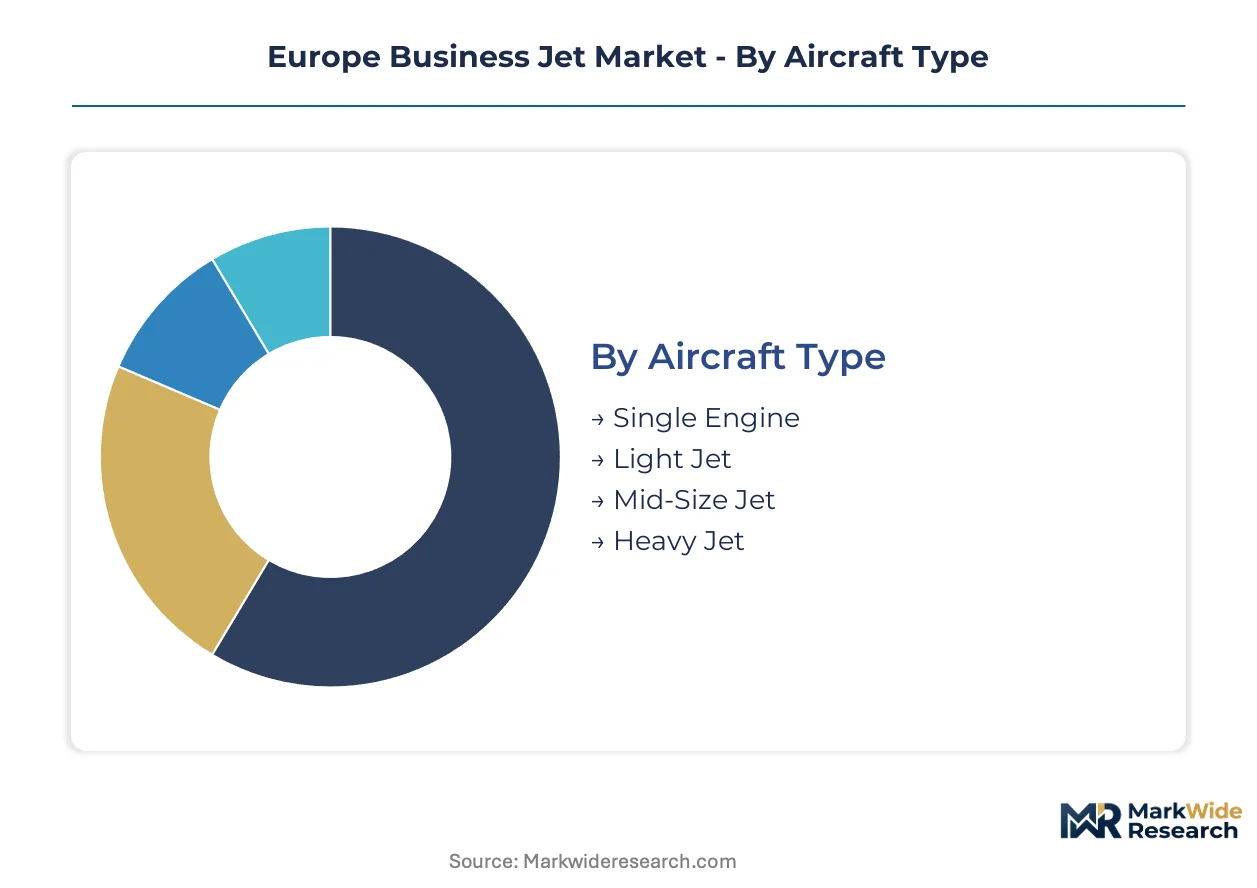
Segmentation in the Europe business jet market reveals how regulatory pressure and operational economics fragment purchasing behavior across user types. EASA certification tiers and EU Green Deal compliance costs create divergent investment patterns that reshape fleet planning priorities.
Aircraft Type:
EASA type certification complexity and SAF retrofit timelines vary substantially across weight classes, concentrating engineering resources on platforms with the longest remaining service lives.
- Heavy Jet:Pressurized cabins with intercontinental range capability carry the highest EASA environmental qualification burdens for climate system refrigerant transitions. Corporate flight departments in France and Switzerland prioritize these configurations for transatlantic missions where cabin altitude specifications justify premium positioning.
- Mid-Size Jet:Turbofan engines in this class balance thrust-to-weight ratios against fuel efficiency per seat-mile, attracting charter operator fleet renewal programs. United Kingdom fractional ownership platforms are expanding managed pools of these aircraft to capture price-sensitive executive mobility demand.
- Light Jet:Compact airframes serve short-haul point-to-point routes with lower EASA compliance overhead for drop-in SAF compatibility.
- Single Engine:Reduced operational complexity appeals to private individuals in Germany and Austria seeking cost-controlled entry into business aviation.
Heavy Jet handles the majority of throughput; Mid-Size Jet is expanding most quickly on share.
End User:
Customer procurement patterns split between capital-intensive in-house operations and outsourced fleet management models.
- Charter Operators:Fleet utilization economics drive aircraft selection toward configurations with rapid turnaround capability and standardized cabin layouts. These operators in the United Kingdom and France are capturing incremental share from traditional whole-aircraft ownership through fractional platforms.
- Corporate:In-house flight departments face CSRD sustainability disclosure mandates that favor newer airframes with verified emissions intensity data. German and Swiss manufacturing headquarters concentrate corporate fleet investment.
- Private Individuals:Ultra-high-net-worth buyers in Monaco and Geneva prioritize cabin customization and range flexibility over operating cost optimization.
- Government:Specialized transport missions require security-hardened communications and medical evacuation configurations for Eastern European healthcare networks.
Charter Operators now drive the steepest fleet expansion trajectory; Corporate remains the dominant revenue anchor.
Service Type:
Margin pools are migrating from physical asset provision toward software-enabled coordination layers.
- Management:Third-party platform operators in Switzerland and the United Kingdom are unbundling aircraft oversight from crew provisioning and maintenance execution. Itemized service menus displace traditional fixed-base operator bundles among corporate users with existing in-house aviation expertise.
- Charter:Digital booking interfaces compress customer acquisition costs while expanding addressable demand beyond traditional broker relationships.
- Maintenance:Turbofan engine overhaul capacity for specific thrust classes concentrates in Northern Italy and Southern Germany repair stations, creating geographic scarcity premiums.
- Brokerage:Transaction facilitation faces margin compression as direct charter platforms reduce information asymmetry between aircraft availability and traveler demand.
Management commands the highest margin expansion; Charter is climbing the fastest on transaction volume.
Technology:
Aftermarket upgrade cycles concentrate value capture in avionics and connectivity rather than airframe production.
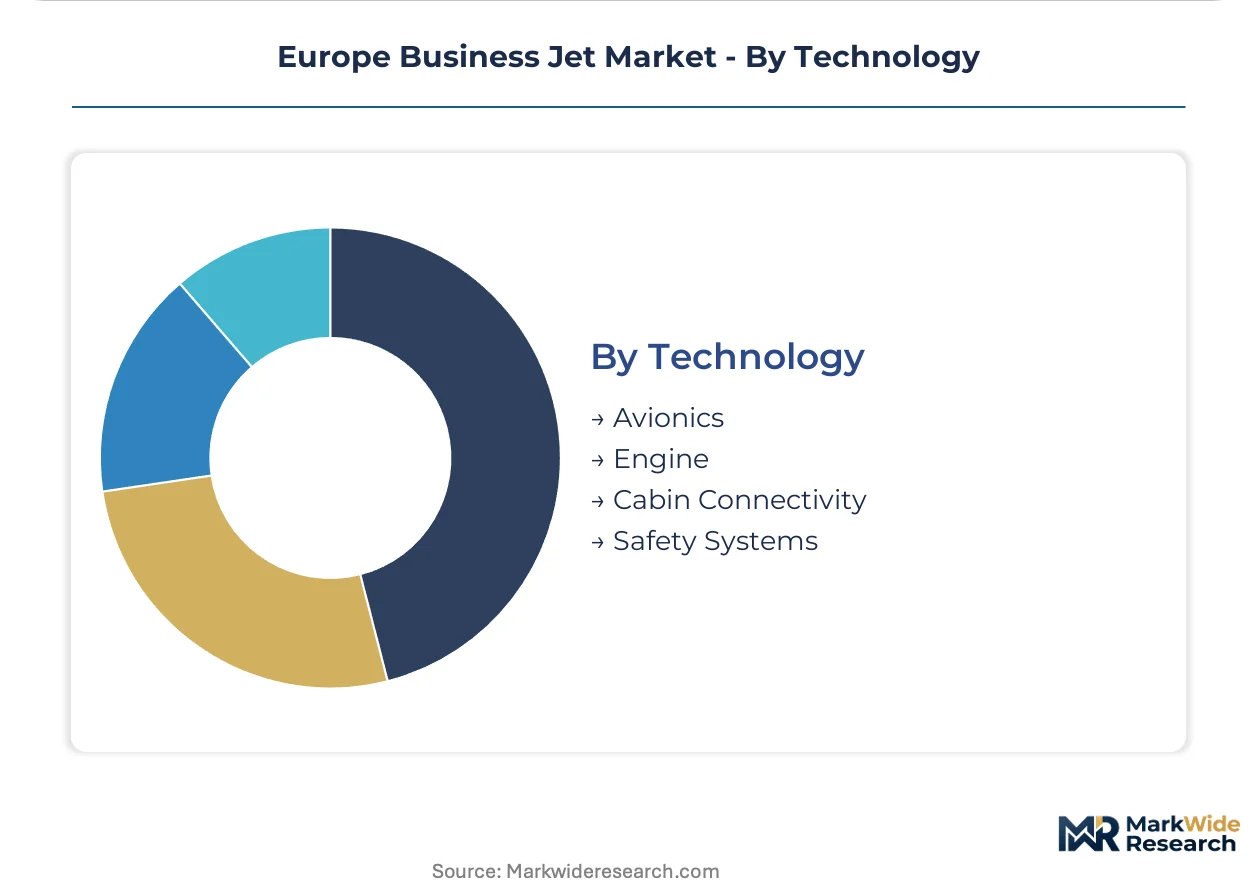
- Cabin Connectivity:Satellite communications integration with flight management systems opens revenue pools for third-party integrators. Charter operators retrofitting mid-size jet fleets adopt these systems at twelve-to-eighteen-month refresh intervals.
- Avionics:Next-generation processor footprints and fiber-optic distribution weights enable fifteen-to-twenty-year airframes to compete on cabin technology parity with new deliveries.
- Engine:SAF compatibility certification for legacy turbofan designs collides with EASA airworthiness directive backlogs at the agency's Cologne headquarters.
- Safety Systems:Enhanced flight vision and terrain awareness mandates from EASA drive retrofit demand across European-registered fleets.
Cabin Connectivity captures the most rapid upgrade intensity; Avionics maintains the largest installed base for recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French business jet deliveries flow predominantly to Swiss fractional ownership platforms and United Kingdom charter operators, establishing a cross-border demand corridor that concentrates premium heavy jet configurations in Western European hubs.
France
Dassault Aviation SA anchors domestic manufacturing through Falcon platform specialization, while Le Bourget maintains Europe's densest SAF infrastructure for early-adopter fleet compliance. EASA environmental qualification protocols for climate system refrigerants are extending supplemental type certificate timelines for cabin retrofits. The Île-de-France cluster concentrates corporate flight department headquarters and third-party management platforms serving transatlantic missions.
Switzerland
Geneva's fractional ownership platforms are expanding managed aircraft pools to capture price-sensitive executive mobility demand from private banking clients. Swissmedic and national aviation regulators align with EASA REACH chemical restrictions on composite matrix resins for interior refits. The Zurich-Geneva corridor hosts the continent's densest concentration of third-party aircraft management operators unbundling services from traditional fixed-base operator bundles.
United Kingdom
Farnborough's dedicated SAF fueling capabilities enable operational compliance for charter operators retrofitting mid-size jet fleets at twelve-to-eighteen-month intervals. CSRD sustainability disclosure mandates are pulling corporate flight departments toward outsourced fleet management over in-house operations. London and Southeast England concentrate digital booking platform development that compresses customer acquisition costs for charter services.
Germany
Manufacturing headquarters in Bavaria and Baden-Württemberg sustain corporate fleet investment despite REACH chemical regulations constraining material substitution pathways for cabin retrofits. The F-Gas Regulation refrigerant phase-down forces extended recertification timelines for climate system redesigns in heavy jet configurations. Northern Italy and Southern Germany repair stations concentrate turbofan engine overhaul capacity for specific thrust classes, creating geographic scarcity premiums for German-registered fleets.
Italy
Specialized MRO technician scarcity for turbofan engine overhaul concentrates capacity in Northern Italy repair stations serving Central European demand. EASA type certification timeline compression for SAF compatibility approvals collides with airworthiness directive backlogs affecting legacy airframe retrofits. The Lombardy-Veneto industrial corridor hosts avionics integration specialists capturing aftermarket upgrade revenue from cabin connectivity convergence trends.
Europe Business Jet Market Competitive Landscape
Listed leaders compete with private specialists across airframe manufacturing and aftermarket service layers, producing a tiered structure where scale-driven OEMs dominate heavy jet deliveries while regional specialists capture mid-size and light jet niches. The vendor base separates into three archetypes: integrated airframers with captive manufacturing footprints, platform operators unbundling aircraft management services, and third-party integrators capturing avionics-cabin connectivity convergence revenue. Competitive moves concentrate on SAF retrofit certification acceleration and geographic expansion of fractional ownership platforms into underserved Eastern European healthcare networks.
Among North American-listed airframers, Bombardier Inc. and Gulfstream Aerospace Corporation exemplify the integrated heavy jet archetype with established European delivery channels. Dassault Aviation SA occupies a distinct position as a family-controlled French manufacturer leveraging aerospace heritage for intercontinental range performance positioning. These three entities represent divergent strategic postures on EASA environmental qualification timelines and SAF infrastructure alignment.
| Leading Market Players |
|---|
| Bombardier Inc. |
| Gulfstream Aerospace Corporation |
| Dassault Aviation SA |
| Textron Inc. |
| Embraer S.A. |
| Pilatus Aircraft Ltd |
| Airbus Corporate Jets |
| Honda Aircraft Company |
| Cirrus Design Corporation |
| Others |
Supply & Pricing Matrix
EASA SAF compatibility certification gates both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb retrofit engineering costs while tiering offerings by environmental compliance tier. Corporate flight departments in France and Switzerland pay premiums for verified drop-in fuel readiness, whereas charter operators in the United Kingdom select mid-size configurations where certification burden falls lighter on per-seat economics.
Pricing Analysis
Current-generation heavy jets with factory-certified SAF compatibility command substantial premiums over prior-generation airframes requiring supplemental type certificates, while next-generation hybrid-electric prototypes remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels tracks EASA environmental qualification tier, cabin altitude specification, and range capability. Cost compression in the mid-size segment is intensifying because charter operators standardize cabin layouts for rapid turnaround. Corporate flight departments exhibit lowest price sensitivity, prioritizing intercontinental range and connectivity integration over per-hour operating economics.
Supply Chain Analysis
Turbofan engine overhaul capacity chokepoints in Northern Italy and Southern Germany concentrate MRO technician scarcity premiums for European-registered fleets. Airframe assembly draws from French composite manufacturing clusters, Northern Irish final assembly lines, and United States avionics integration facilities. Supply chain risk rests on single-source vulnerability for specific thrust-class engine components. Distribution runs through fractional ownership platforms in Switzerland and direct manufacturer relationships with corporate flight departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal aviation decarbonization targets are accelerating fleet replacement cycles faster than OEM engineering timelines can accommodate, compressing competitive windows for compliance-ready platforms.
For Market Incumbents: Compound delivery leadership through captive SAF retrofit certification pipelines at EASA Cologne headquarters, while accelerating backward integration into composite matrix resin supply to offset REACH chemical regulation constraints. Bombardier's Northern Irish manufacturing footprint and Dassault's French aerospace heritage provide defensive moats against emerging electric propulsion entrants. For New Entrants and Emerging Players: Anchor in Eastern European medical evacuation mission expansion, where specialized aeromedical configurations remain underserved by existing charter capacity. The German and Austrian private individual segment offers the most penetrable entry point for single-engine cost-controlled configurations. Go-to-market execution should emphasize digital booking platform partnerships with United Kingdom charter operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed third-party management platforms in the Zurich-Geneva corridor that have unbundled aircraft oversight from traditional fixed-base operator bundles. Long-term viability over a five-to-ten year window hinges on CSRD sustainability disclosure mandate compliance capabilities. Monitor SAF infrastructure buildout velocity at Le Bourget, Geneva, and Farnborough as the inflection indicator for fleet planning alignment.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Retrofit Certification Acceleration | EASA environmental qualification timelines determine competitive market access for legacy airframe operators. |
| Fractional Ownership Platform Expansion | Geneva and London hubs capture price-sensitive executive mobility demand from private banking clients. |
| Avionics-Cabin Connectivity Convergence | Satellite communications integration with flight management systems opens aftermarket upgrade revenue pools. |
| Medical Evacuation Configuration Specialization | Eastern European healthcare networks remain underserved by existing charter capacity. |
| Third-Party Management Unbundling | Switzerland and United Kingdom operators displace traditional fixed-base operator bundles with itemized service menus. |
Research Methodology
Cross-validation between primary interviews with flight department directors, charter operator fleet managers, MRO station heads, and EASA certification specialists anchors the qualitative findings against secondary validation from EASA type certificate databases, EU Green Deal policy documentation, and corporate sustainability disclosure filings. Bottom-up triangulation across aircraft delivery records and top-down reconciliation against fleet utilization metrics ensure dimensional consistency.
Sensitivity analysis on fuel price trajectories and SAF availability schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include aircraft type, end user archetype, service tier, and technology upgrade cycle, with CAGRs derived from replacement demand elasticity against regulatory compliance deadlines. Forecast inputs incorporate EASA airworthiness directive backlogs and REACH chemical restriction implementation timelines.
Material uncertainties — SAF infrastructure buildout delays, EASA certification timeline extensions, and REACH chemical substitution pathway failures — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU Green Deal aviation decarbonization target enforcement evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
Active Air Deflector Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
India Winglets Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Commercial Aerospace Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market