
 LAMEA Aircraft Band Clamps Market | 2026-2036
LAMEA Aircraft Band Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Aircraft Band Clamps Market Insights
Aerospace distributor networks across Latin America and the Middle East are reshaping procurement patterns for aircraft band clamps as flag carriers consolidate vendor lists and regional MROs seek shorter lead times. TransDigm Group Inc. leverages its broad aerospace components portfolio to sustain long-term supply agreements with major airlines in the Gulf states. Clampco Products Inc. anchors its position through specialized stainless steel clamp manufacturing for high-vibration engine applications. Parker Hannifin Corporation competes across multiple material grades while extending its distribution footprint into North African aviation hubs.
LAMEA aircraft band clamps are circular fastening devices, typically manufactured from corrosion-resistant alloys with widths ranging from 0.25 to 2.0 inches, designed to secure hoses, ducts, and wiring bundles against pressure differentials and thermal cycling in airframe and propulsion systems. Precision clamps command premium positioning due to tighter tolerances required in modern turbofan engine compartments where leakage thresholds have tightened. Custom clamps represent the fastest-growing product category as regional MRO facilities adapt legacy fleets with non-standard configurations. Titanium material grades are displacing legacy aluminum in high-temperature zones near exhaust manifolds across military aviation platforms.
ANAC in Brazil, GCAA in the United Arab Emirates, and South Africa's SACAA enforce airworthiness directives that mandate traceable material certifications and fatigue-testing documentation for all structural fastening hardware, effectively screening out uncertified suppliers. These regulatory frameworks elevate compliance costs but protect incumbent manufacturers with established quality management systems. Stakeholders must monitor evolving bilateral aviation safety agreements between LAMEA jurisdictions and major OEM home countries, as mutual recognition shifts could redirect procurement flows toward certified local producers or consolidated international distributors.
Market Dynamics
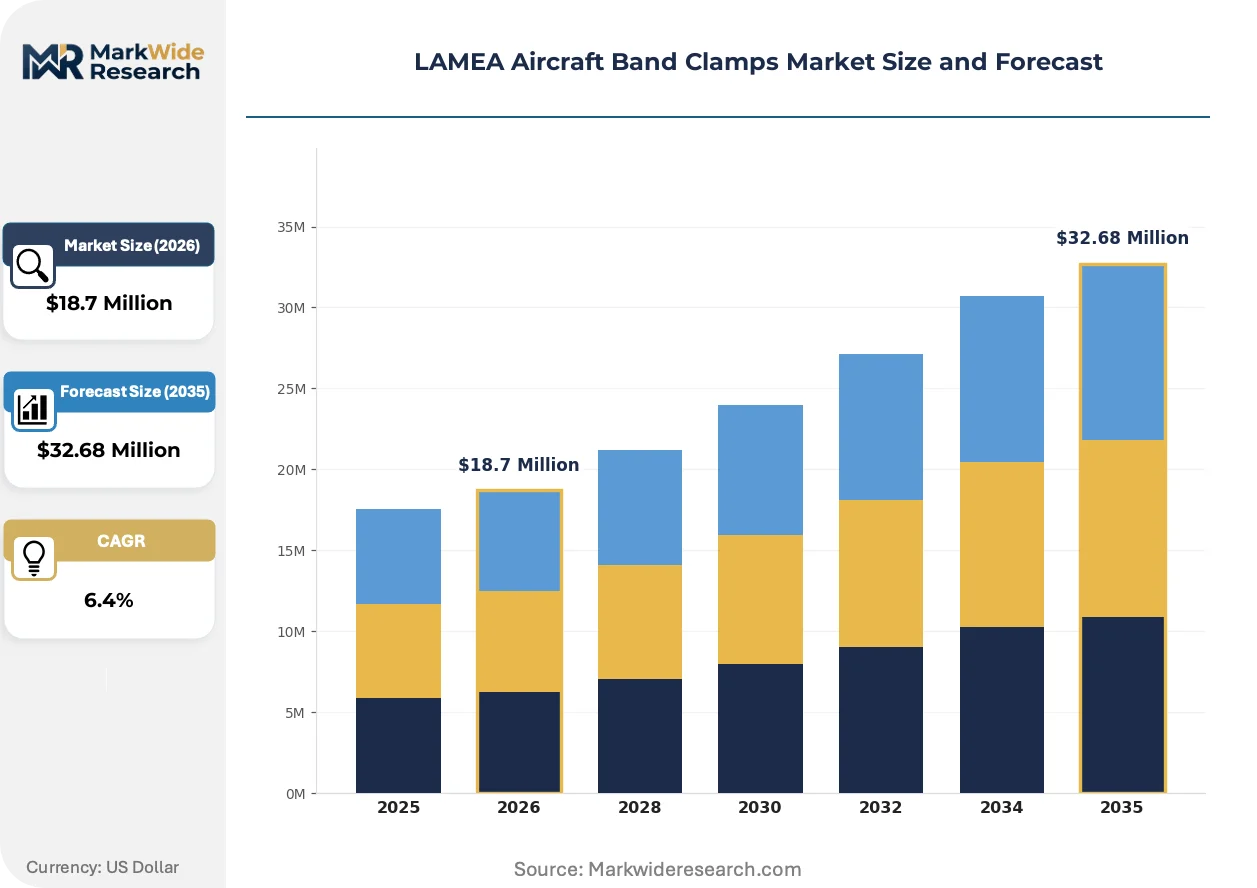
Fleet modernization mandates across Latin American flag carriers are compressing procurement cycles for certified clamp assemblies while ANAC's tightened import certification rules favor established domestic distributors with traceable quality systems.
Growth Catalysts
- Commercial Fleet Renewal:Latin American carriers are accelerating narrowbody replacements, expanding aftermarket demand for engine-grade clamp assemblies in high-vibration zones.
- ANAC Certification Standards:Brazil's tightened airworthiness directives for imported hardware are screening out uncertified suppliers and consolidating procurement through verified domestic channels.
- Titanium Alloy Adoption:Military aviation platforms across the Middle East are specifying corrosion-resistant titanium grades for exhaust-adjacent applications, displacing legacy aluminum specifications.
Market Restraints
- Raw Material Volatility:Aerospace-grade titanium and stainless steel pricing fluctuations are compressing margin buffers for precision clamp manufacturers serving price-sensitive regional MROs.
- Supplier Concentration Risk:Specialty fastener production for wide-body engine applications concentrates among a handful of European and North American certified foundries, exposing LAMEA buyers to extended lead times.
- Substitution Pressure:Spring-loaded constant-tension clamps are displacing traditional worm-drive designs in certain low-pressure ducting applications, eroding volume for legacy product lines.
Strategic Opportunities
- Leased Aircraft Transition Hubs:South Africa's MRO corridor serving cargo operators and lessor fleet rotations offers underpenetrated demand for rapid-turnaround clamp kit provisioning.
- GCAA Regulatory Alignment:The UAE's aviation safety framework is converging with EASA standards, creating certification pathways for suppliers already qualified under European directives.
- Digital Inventory Integration:Gulf-state carriers are adopting vendor-managed inventory systems for consumable fasteners, enabling direct-to-hangar replenishment models bypassing traditional distribution tiers.
Industry Challenges
- Specialized Welding Certification:Aerospace-grade TIG welding for titanium clamp fabrication requires scarce technician qualifications, constraining production scaling across LAMEA manufacturing facilities.
- SACAA Documentation Burden:South Africa's fatigue-testing and traceability requirements for structural hardware are extending certification timelines for new product introductions, delaying revenue recognition.
- Legacy Fleet Configuration Drift:Non-standard clamp specifications accumulated across decades of operator modifications complicate kit standardization efforts for regional MROs managing mixed-generation fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Aircraft Band Clamps Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Clamps, Precision Clamps, Custom Clamps, Quick-Release Clamps Material: Aluminum, Stainless Steel, Composite, Titanium End User: Civil Aviation, Military Aviation, Maintenance, Repair and Overhaul Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Caillau, Clampco Products Inc., TransDigm Group Inc., United Aircraft Technologies Inc., J&M Products Inc., Eaton Corporation, Destaco, LAS Aerospace Ltd, Parker Hannifin Corporation, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Aircraft Band Clamps Market Trends and Innovations
Additive manufacturing of titanium clamp brackets is compressing prototyping cycles while enabling geometries impossible through conventional machining, though qualification timelines for flight-critical printed components remain extended.
Plasma-enhanced chemical vapor deposition of diamond-like carbon coatings onto stainless steel band surfaces is rendering obsolete traditional cadmium plating for corrosion protection in marine-environment deployments. Regional carriers operating coastal routes in Brazil and the UAE are specifying these coated clamps for landing gear and engine nacelle applications, eliminating hexavalent chromium disposal liabilities while extending service intervals.
SACAA's 2024 harmonization with EASA Part 21 design organization requirements is forcing structural hardware suppliers to restructure quality management systems or exit the South African market. The directive elevates documentation burdens for fatigue-test protocols and material lot traceability, disproportionately affecting smaller distributors lacking dedicated regulatory affairs functions. Certified incumbent manufacturers are absorbing compliance costs into long-term supply agreements with state-owned carriers.
Consolidated vendor-list policies at major Gulf-state flag carriers are compressing the supplier base for consumable fasteners, rewarding distributors with integrated logistics capabilities and multi-site stocking agreements. Procurement teams are unbundling after-sales technical support from hardware pricing, creating transparent cost structures for MRO budgeting. This behavior shift is most pronounced at Dubai and Abu Dhabi hubs, where lessor technical asset managers demand real-time consumption visibility across multiple line maintenance stations.
LAMEA Aircraft Band Clamps Market Segmentation
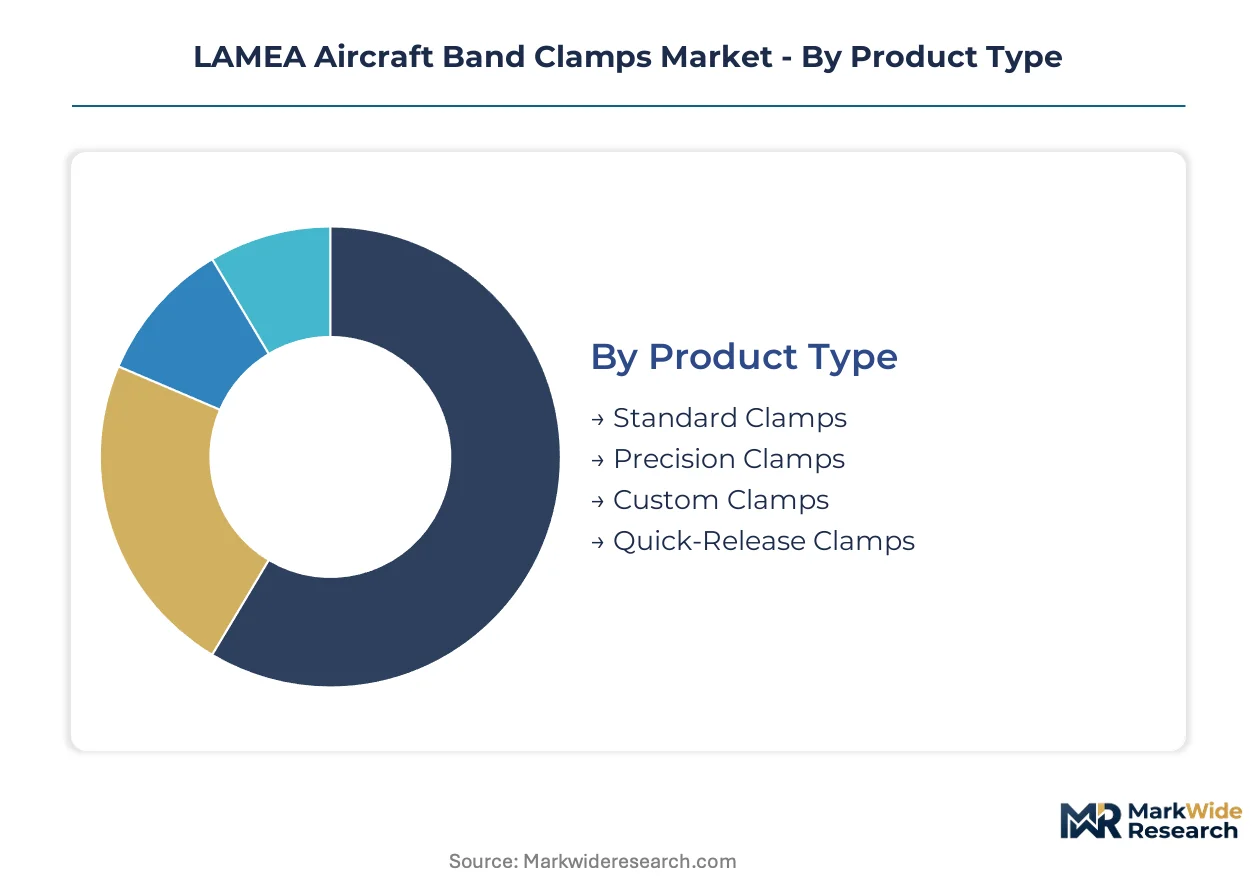
Aircraft band clamps serve distinct functional roles across airframe, engine, and aftermarket applications. Segmentation reveals how material specifications, precision requirements, and procurement channels diverge between OEM installations and MRO replenishment cycles.
Product Type:
Mature worm-drive designs coexist with emerging quick-release formats as fleet complexity drives specification diversity.
- Precision Clamps:These devices maintain tighter tolerances for high-vibration turbofan engine compartments where leakage thresholds have tightened. ANAC-certified Brazilian distributors concentrate procurement for narrowbody engine programs undergoing renewal.
- Custom Clamps:Non-standard configurations adapt legacy fleets with accumulated operator modifications. Regional MRO facilities across South Africa's cargo corridor specify these for rapid-turnaround leased aircraft transitions.
- Standard Clamps:Conventional worm-drive assemblies dominate high-volume line maintenance for routine hose and duct securing.
- Quick-Release Clamps:Tool-free designs accelerate turnaround times for inspection-intensive nacelle applications.
Precision clamps retain volume leadership; custom clamps hold the steepest expansion curve.
Material:
Cost tiers separate legacy aluminum from premium titanium grades as thermal requirements intensify near exhaust zones.
- Titanium:Corrosion-resistant grades specified for military aviation platforms across Middle Eastern defense programs displace legacy aluminum in high-temperature exhaust-adjacent applications. SACAA documentation requirements extend certification timelines for new titanium product introductions.
- Stainless Steel:Marine-environment deployments favor diamond-like carbon coated variants eliminating hexavalent chromium disposal liabilities for Brazilian coastal operators.
- Aluminum:Lightweight legacy specifications persist in low-temperature airframe ducting where thermal cycling remains moderate.
- Composite:Emerging polymer-reinforced formats target weight reduction in next-generation regional jet programs.
Titanium commands the premium tier; composite grades are climbing the fastest.
End User:
Customer type determines certification burden and procurement rhythm across fleet acquisition and sustainment cycles.
- Maintenance, Repair and Overhaul:South Africa's MRO corridor serving regional cargo operators and lessor fleet rotations generates underpenetrated demand for rapid-turnaround clamp kit provisioning. Digital inventory integration at Gulf-state hubs enables direct-to-hangar replenishment models.
- Civil Aviation:Latin American flag carriers compress procurement cycles through consolidated vendor-list policies favoring distributors with multi-site stocking agreements.
- Military Aviation:Defense platforms across the Middle East specify corrosion-resistant grades with extended service intervals for expeditionary operations.
MRO channels retain volume leadership; civil aviation holds the steepest expansion curve.
Distribution Channel:
Supply concentration favors established domestic channels where traceable quality systems satisfy tightening airworthiness directives.
- Distributors:ANAC's tightened import certification rules screen out uncertified suppliers and consolidate procurement through verified Brazilian domestic channels with established quality management systems.
- Direct Sales:Gulf-state flag carriers unbundle after-sales technical support from hardware pricing through transparent cost structures for MRO budgeting.
- Resellers:Secondary channels serve price-sensitive regional operators with extended lead time tolerance.
- Online Retail:Digital platforms emerge for non-critical consumable fasteners with standardized specifications.
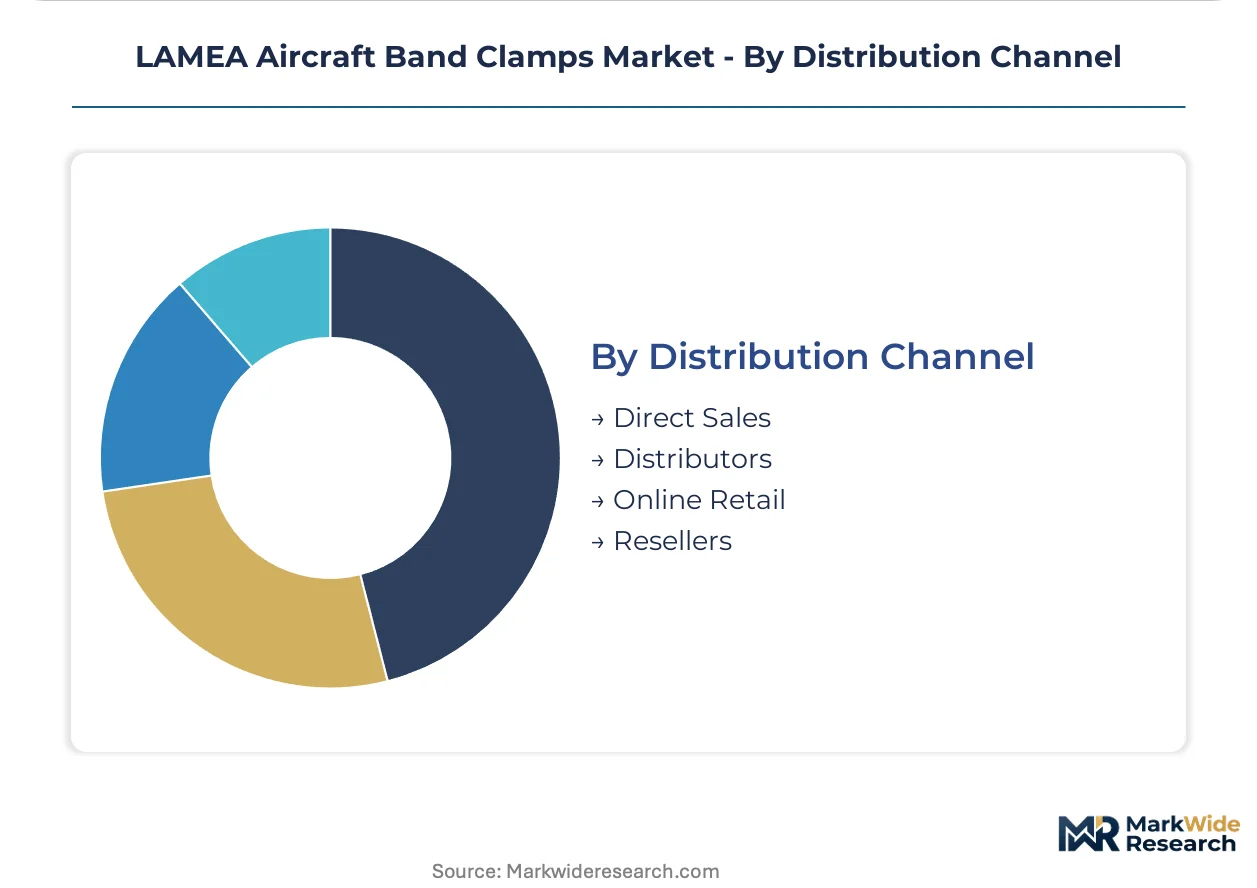
Distributor networks retain volume leadership; direct sales hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LAMEA region's aviation infrastructure networks—spanning Brazil's São Paulo-Guarulhos cargo hub, the UAE's Dubai-Al Maktoum dual-airport system, and South Africa's OR Tambo maintenance corridor—underwrite divergent procurement patterns for aircraft band clamps across commercial, military, and aftermarket channels.
Brazil
Narrowbody fleet renewal at LATAM Airlines and Azul drives engine-grade clamp demand through ANAC-certified domestic distributors. Brazil's national aviation regulator tightened import certification rules in 2023, screening uncertified hardware suppliers and consolidating procurement through São Paulo-based channels with established quality management systems. São Paulo's Guarulhos International Airport anchors the regional distribution network for aftermarket clamp assemblies.
United Arab Emirates
Gulf-state flag carriers at Dubai and Abu Dhabi hubs compress supplier lists while adopting vendor-managed inventory systems for consumable fasteners. The UAE's General Civil Aviation Authority aligns certification standards with EASA Part 21 requirements, creating pathways for European-qualified suppliers. Dubai's Al Maktoum International Airport serves as the primary consolidation point for lessor technical asset managers demanding real-time consumption visibility.
South Africa
The OR Tambo International Airport maintenance corridor generates underpenetrated demand for rapid-turnaround clamp kit provisioning serving regional cargo operators and leased aircraft transitions. South Africa's Civil Aviation Authority enforces fatigue-testing documentation and traceable material certifications that extend timelines for new product introductions. Johannesburg's MRO cluster specializes in mixed-generation fleet configurations requiring non-standard clamp specifications.
Saudi Arabia
Military aviation platforms across Royal Saudi Air Force programs specify corrosion-resistant titanium grades for expeditionary operations in high-temperature exhaust zones. The Saudi Food and Drug Authority and national aviation safety frameworks enforce material certification standards for structural hardware imports. Riyadh's King Khalid International Airport district hosts emerging distribution capabilities for defense-procured fastener systems.
LAMEA Aircraft Band Clamps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The LAMEA aircraft band clamps market exhibits moderate consolidation, with aerospace conglomerates holding long-term supply agreements against a fragmented base of regional distributors and specialized fabricators. Two strategic archetypes dominate: diversified aerospace component houses leveraging portfolio breadth, and precision fastener specialists anchoring narrow technical positions. Competitive maneuvering concentrates on certification acquisition for regulatory alignment and distribution footprint expansion into high-growth MRO corridors.
Among diversified aerospace component houses, TransDigm Group Inc. and Eaton Corporation exemplify the platform-integrator archetype through broad hardware portfolios and established airline relationships. Clampco Products Inc. and Parker Hannifin Corporation occupy positions within the precision-specialist tier, with the former representing stainless steel fabrication expertise and the latter extending multi-material capabilities across distribution networks. Caillau and Destaco sit within the European-origin specialist segment, serving as reference points for quality-system benchmarking in LAMEA procurement evaluations.
| Leading Market Players |
|---|
| Caillau |
| Clampco Products Inc. |
| TransDigm Group Inc. |
| United Aircraft Technologies Inc. |
| J&M Products Inc. |
| Eaton Corporation |
| Destaco |
| LAS Aerospace Ltd |
| Parker Hannifin Corporation |
| Others |
Pricing and Supply Chain Analysis
São Paulo's Guarulhos distribution cluster concentrates certified clamp inventory for narrowbody engine programs, translating ANAC-mandated quality verification into pricing power for verified domestic channels serving LATAM Airlines and Azul. Raw material volatility in aerospace-grade titanium and stainless steel compresses margin buffers for precision fabricators, forcing tiered pricing structures that separate ANAC-certified premium assemblies from uncertified economy alternatives.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating ANAC-certified precision clamps from standard worm-drive assemblies and uncertified economy alternatives. Price differentiation hinges on material certification grade and after-sales technical support bundling, with distributors absorbing SACAA documentation costs into long-term supply agreements. Pricing pressure stems from raw material volatility in titanium feedstocks, compressing margins for regional MROs least able to pass through cost increases. Civil aviation flag carriers exhibit lowest price sensitivity due to consolidated vendor-list policies, while independent South African cargo operators negotiate aggressively on rapid-turnaround clamp kit provisioning.
Supply Chain Analysis
Aerospace-grade titanium sponge feeds primarily from Chinese and Russian smelters, with specialty stainless steel coil sourcing concentrated in German and Japanese mills certified for AS9100 aerospace quality systems. Raw material dependencies center on titanium sponge, precipitation-hardened stainless grades, and corrosion-resistant superalloys for exhaust-zone applications. Supply chain risk concentrates in single-source vulnerability for wide-body engine-grade clamp forgings, where European and North American certified foundries control specialty production. Distribution runs through São Paulo-based ANAC-verified channels for Brazilian carriers, Dubai-Al Maktoum consolidation hubs for Gulf-state lessors, and Johannesburg's OR Tambo corridor for sub-Saharan MRO demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
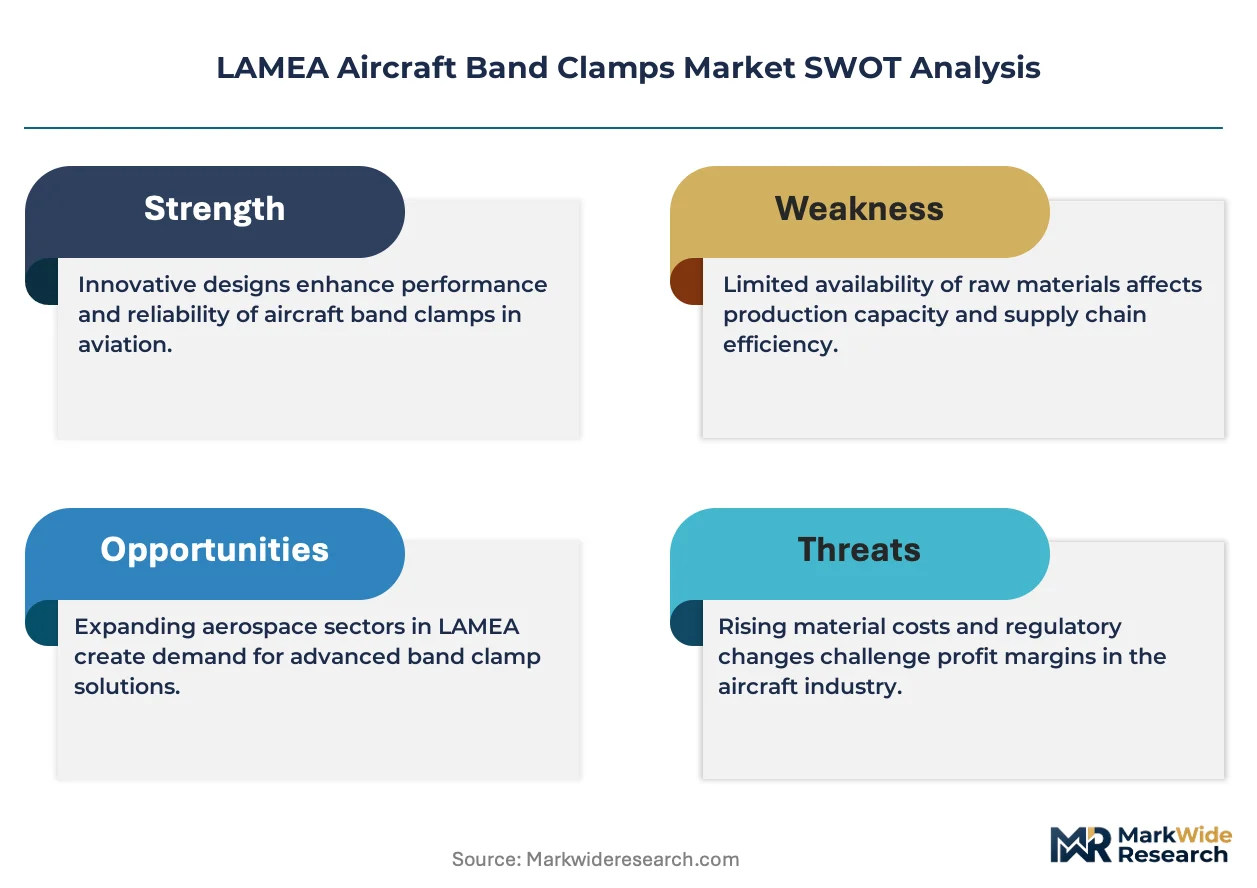
Specialized TIG welding certification for titanium aerospace fabrication represents the critical capability gap constraining production scaling across LAMEA manufacturing facilities, with fewer than twelve qualified technicians available regionally for flight-critical clamp welding protocols.
For Market Incumbents: Harden quality management systems against SACAA's EASA Part 21 harmonization requirements by investing in fatigue-test documentation infrastructure and material lot traceability capabilities. Absorb compliance costs into multi-year supply agreements with state-owned carriers to lock out emerging competitors lacking dedicated regulatory affairs functions. Defend position through backward integration into titanium bracket additive manufacturing, compressing prototyping cycles for custom clamp configurations demanded by mixed-generation fleet MROs. For New Entrants and Emerging Players: Build out digital inventory integration capabilities targeting Gulf-state carrier vendor-managed inventory programs, where real-time consumption visibility commands premium positioning. South Africa's OR Tambo leased aircraft transition corridor offers the most penetrable white space, with underdeveloped rapid-turnaround clamp kit provisioning for cargo operators. Establish go-to-market presence through partnerships with Dubai-based lessor technical asset managers seeking alternative sourcing for consumable fasteners. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ANAC and SACAA regulatory alignment with EASA standards is systematically screening out uncertified distributors, concentrating procurement through quality-verified incumbents with established airline relationships. Acquisition targets should display AS9100 certification, established ANAC or GCAA regulatory pathways, and multi-site stocking agreements with flag carriers. Watch for bilateral aviation safety agreement announcements between LAMEA jurisdictions and OEM home countries as the signal indicating procurement flow redirection toward certified local producers.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Quality System Certification | ANAC and SACAA screening processes systematically eliminate uncertified competitors from approved vendor lists. |
| Titanium Additive Manufacturing Qualification | Flight-critical printed clamp brackets enable geometries impossible through conventional machining for legacy fleet adaptations. |
| Vendor-Managed Inventory Partnership | Gulf-state carrier direct-to-hangar replenishment models bypass traditional distribution tiers for consumable fasteners. |
| EASA Part 21 Design Organization Alignment | SACAA harmonization forces structural hardware suppliers to restructure quality management systems or exit South Africa. |
| Multi-Site Stocking Agreement | Consolidated vendor-list policies at Dubai and Abu Dhabi hubs reward distributors with integrated logistics capabilities. |
Research Methodology
A standing panel of MRO procurement directors, airline fleet engineers, ANAC regulatory compliance officers, and distributor operations managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with aftermarket clamp kit buyers at São Paulo, Dubai, and Johannesburg hubs with secondary validation against ANAC certification databases, SACAA airworthiness directives, and GCAA regulatory filings. Customs records for aerospace fastener imports into Brazil, UAE, and South Africa supplied trade-flow triangulation against bottom-up carrier fleet renewal schedules and top-down OEM delivery projections.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type (precision, custom, standard, quick-release), material grade (titanium, stainless steel, aluminum, composite), and end-user channel (MRO, civil aviation, military). CAGRs derived from installed base depreciation curves, fleet renewal timelines, and aftermarket consumable replacement rates. Industry-specific forecast inputs incorporated ANAC certification timeline extensions, SACAA fatigue-test documentation burdens, and GCAA-EASA regulatory convergence assumptions.
Stress conditions across titanium feedstock pricing volatility, ANAC import certification rule tightening, and Gulf-state carrier vendor-list consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet renewal acceleration and regulatory harmonization pace. Cross-checking against OEM delivery schedules and lessor technical asset manager procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aeronautic Propeller Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Europe Aviation Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Wind Tunnel Market
Aircraft
Tanker Aircraft Market
Aircraft
Fighter Aircraft Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Ailerons Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Latin America Business Jet Market
Aircraft
Military Aircraft Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Global Business Aircraft Market
Aircraft
Commercial Aircraft Leasing Market