
 Aircraft Elevator Market | 2026-2036
Aircraft Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Elevator Market Analysis
Carbon fiber reinforced polymer is shifting from secondary structures into primary flight control surfaces including elevator torque boxes and hinge fittings, reducing weight penalties versus legacy aluminum assemblies. Moog Inc. leverages its fly-by-wire actuator integration to dominate electrohydraulic elevator control channels for narrowbody platforms. Honeywell International Inc. sustains aftermarket positioning through proprietary health monitoring algorithms that predict hinge bearing wear. Liebherr Group anchors European supply chains with vertically controlled machining of titanium elevator brackets for Airbus A320 and A350 programs.
An aircraft elevator is a hinged, aerodynamic control surface mounted on the horizontal stabilizer that generates pitch moment through deflection angles typically ranging from 30 degrees trailing-edge-up to 20 degrees trailing-edge-down, with primary construction from aluminum alloys, titanium fittings, or carbon-epoxy composites depending on load spectrum and fatigue requirements. Its commercial purpose is to provide longitudinal stability and maneuver authority during all flight phases from rotation through flare. Electric elevators lead product type segments due to Boeing and Airbus preferences for all-electric architectures that eliminate central hydraulic systems. Fly-by-wire technology commands the technology segment as digital flight control laws replace mechanical linkages, while maintenance installations represent the fastest-growing installation type as aging fleets trigger elevator spar inspections and hinge replacement cycles under enhanced airworthiness directives.
FAA airworthiness directives mandate repetitive inspections of elevator balance weights and hinge bearings, while EASA CS-25 certification standards govern flutter clearance and structural integrity for European-registered aircraft. The EU Green Deal's sustainable aviation fuel mandates indirectly pressure elevator redesigns that reduce parasitic drag and improve fuel efficiency per nautical mile. Stakeholders must monitor evolving MRO network consolidation and decide whether to deepen captive repair capabilities or outsource to specialized FAA Part 145 stations.
Market Dynamics
Fleet renewal cycles and airworthiness directive compliance are restructuring demand toward maintenance-intensive retrofit programs rather than new-build consumption alone.
Growth Catalysts
- FAA Airworthiness Directives:Mandated repetitive inspections of elevator balance weights and hinge bearings generate sustained aftermarket demand from aging narrowbody fleets.
- Carbon-Epoxy Composites:Material substitution into primary torque boxes reduces parasitic drag penalties, compelling OEM specification updates across next-generation programs.
- Wichita MRO Cluster:Concentrated Part 145 repair station capacity in Kansas creates regional pull for specialized elevator spar inspection services.
Market Restraints
- Titanium Input Volatility:Sponge price fluctuations and Russian supply disruption compress margin predictability for bracket and hinge fitting manufacturers.
- EASA CS-25 Certification Friction:Extended flutter clearance validation timelines delay new elevator design introductions by 18-24 months versus historical baselines.
- Single-Source Actuator Dependency:Fly-by-wire electrohydraulic channel concentration creates supply vulnerability for narrowbody platform integrators.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India order backlogs create greenfield demand for electric elevator architectures on A320neo-family deliveries.
- EU Green Deal Tailwind:Sustainable aviation fuel mandates indirectly incentivize drag-reducing elevator redesigns that improve fuel efficiency per nautical mile.
- Predictive Health Monitoring Convergence:Sensor fusion with machine learning algorithms enables unbundled aftermarket service contracts separate from hardware sales.
Industry Challenges
- Specialized NDT Technician Scarcity:Ultrasonic and eddy-current inspection certification requirements outpace training pipeline output for elevator spar assessment.
- Legacy Mechanical Linkage Integration:Hybrid fly-by-wire retrofits onto aging 737NG and A320ceo platforms demand custom actuator mounting solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Elevator Market |
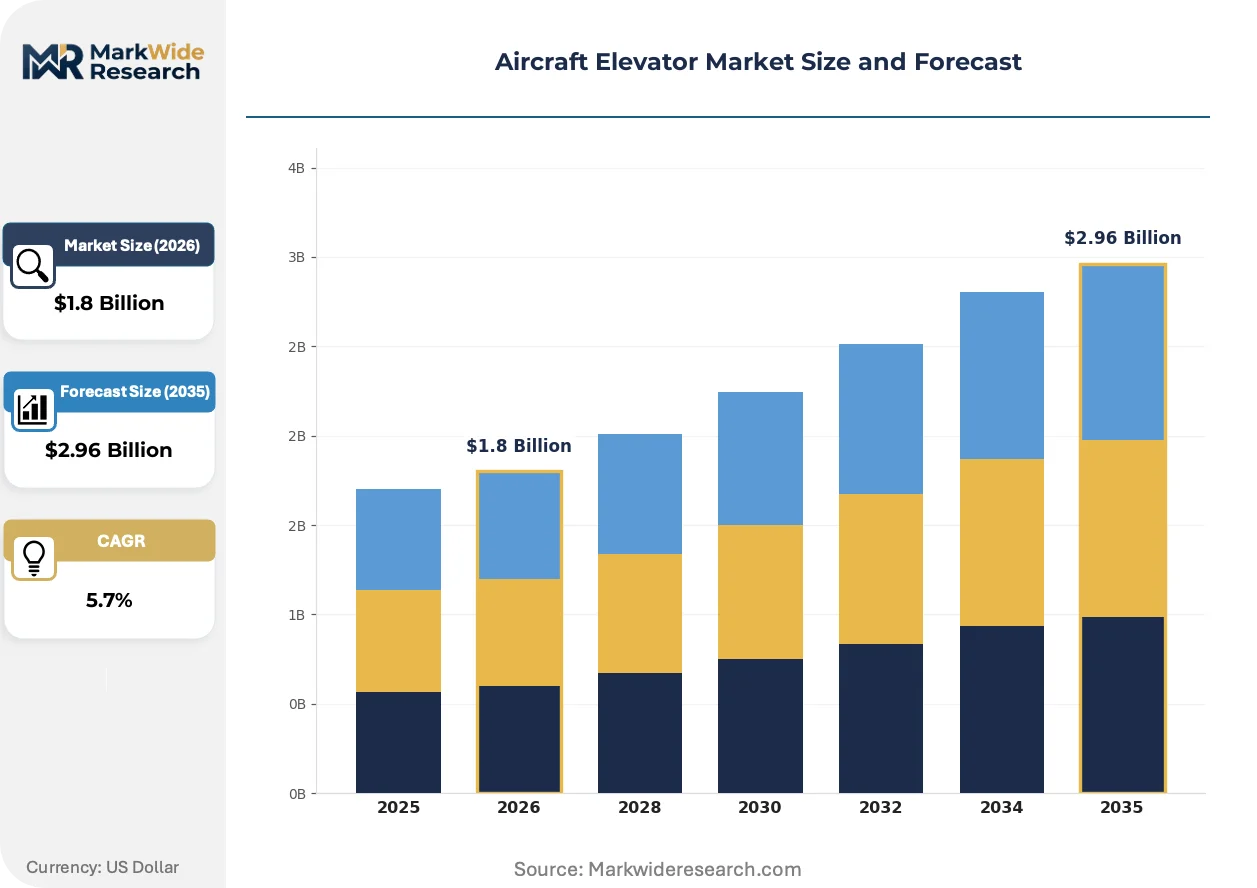
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Elevators, Hydraulic Elevators, Electric Elevators, Aircraft Lift Systems End User: Commercial Aviation, Military Aviation, Cargo Transport, Private Jets Installation Type: New Installation, Retrofit, Maintenance, Replacement Technology: Fly-by-Wire, Mechanical Control, Digital Control, Automated Systems |
| Companies Covered | Moog Inc., BAE Systems, Honeywell International Inc., Nabtesco Corporation, Liebherr Group, Airbus S.A.S., PaR Systems, Otis Elevator Company, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Elevator Market Emerging Trajectories
Digital flight control architectures and material science advances are compressing development cycles while fragmenting supplier roles between hardware and software domains.
Carbon fiber reinforced polymer is absorbing structural loads previously assigned to aluminum torque boxes in primary elevator assemblies. Boeing and Airbus engineering teams specify thermoset prepregs for A350 and 787 horizontal stabilizer attachments, with adoption rates climbing fastest on widebody programs where weight penalties compound over long-haul stage lengths. The shift is absorbing engineering hours from legacy metallurgy specialists toward composite process engineers.
EASA CS-25 Amendment 25-148 tightens flutter clearance demonstration requirements for flight control surfaces with modified mass properties. European-registered operators must submit expanded ground vibration test data for elevator balance weight alterations, extending certification timelines for aftermarket modifiers. Regional MRO providers in France and Germany are responding by captive-hiring flutter analysis capabilities previously outsourced to airframe OEMs.
Airline procurement teams unbundle elevator actuator overhaul contracts from airframe heavy maintenance checks, negotiating direct relationships with component OEMs. The disintermediation compresses turnaround times for hinge bearing replacement cycles but fragments liability allocation between airframe and component suppliers. This pattern concentrates in North American carrier fleets where FAA Part 145 certificate holders compete on cycle-time guarantees.
Aircraft Elevator Market Segmentation
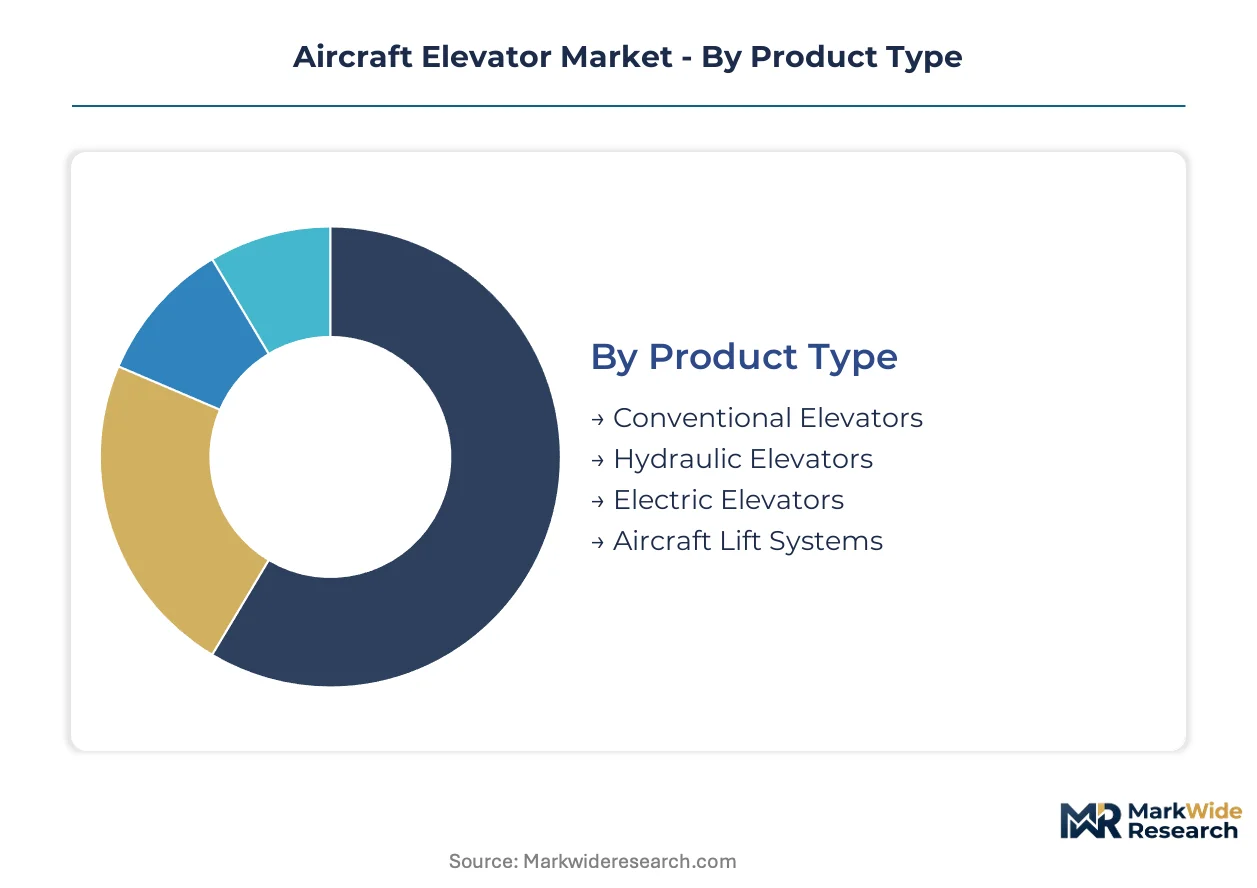
Aircraft elevator procurement patterns fragment sharply between OEM new-build specifications and aftermarket retrofit cycles. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes returns.
Product Type:
Supply concentration for primary flight control actuation channels determines which architectures OEM engineering teams specify for platform development programs.
- Electric Elevators:All-electric architectures eliminate central hydraulic distribution systems through distributed electromechanical actuators. Boeing and Airbus narrowbody programs in the United States and France drive specification dominance for this architecture as fuel efficiency targets harden.
- Hydraulic Elevators:Conventional power transfer units deliver high force density through pressurized fluid circuits, retaining specification on legacy widebody platforms and military transports where proven failure modes matter more than weight optimization. Aging fleet bases in Germany and the United Kingdom sustain aftermarket demand for seal replacement and actuator overhaul services.
- Conventional Elevators:Cable-pulley mechanical linkages persist on general aviation and regional turboprop categories where certification cost minimization outweighs performance optimization.
- Aircraft Lift Systems:Integrated cargo deck elevators for freighter conversions represent a specialized subclass with distinct Part 25 certification pathways.
Today's leader: Electric Elevators. Tomorrow's challenger: Hydraulic Elevators in hybrid retrofit configurations.
End User:
Customer procurement sophistication varies dramatically between scheduled carriers with captive engineering staff versus owner-operators relying on MRO intermediaries.
- Commercial Aviation:Scheduled carriers and low-cost operators in India and the United States negotiate fleet-level actuator service agreements with direct OEM relationships, bypassing traditional airframe heavy maintenance channels. IndiGo and Air India order backlogs for A320neo-family aircraft concentrate demand for electric elevator architectures.
- Military Aviation:Defense procurement offices in the United States and France prioritize ruggedized hydraulic systems with redundant mechanical backup modes for tactical transport and tanker platforms. MIL-STD-810 environmental qualification requirements extend development timelines versus commercial equivalents.
- Cargo Transport:Dedicated freighter operators and passenger-to-freighter conversion houses demand specialized elevator tuning for aft-heavy center-of-gravity envelopes.
- Private Jets:Business aircraft OEMs in Wichita, Kansas specify compact electric actuators for cabin-size constraints on super-midsize platforms.
Commercial Aviation commands current volume. Military Aviation offers steadiest program funding visibility through defense budget cycles.
Installation Type:
Regulatory inspection mandates are restructuring revenue mix toward recurring maintenance events rather than one-time new-build hardware sales.
- Maintenance:FAA airworthiness directives mandate repetitive hinge bearing and balance weight inspections for aging narrowbody fleets, generating sustained aftermarket demand from Part 145 repair stations clustered in Kansas and Texas. Sensor fusion with predictive algorithms is unbundling service contracts from hardware sales.
- Retrofit:Fly-by-wire system upgrades onto 737NG and A320ceo platforms demand custom actuator mounting solutions and expanded ground vibration test data for flutter clearance. EASA CS-25 Amendment 25-148 extended certification timelines for these modifications.
- New Installation:OEM final assembly lines in Seattle, Toulouse, and Mobile, Alabama specify next-generation electric architectures for greenfield production.
- Replacement:Catastrophic damage and corrosion findings drive unscheduled component exchanges outside planned maintenance windows.
Maintenance installations are expanding most quickly as fleet age profiles deepen. Retrofit programs face regulatory friction that compresses near-term volume realization.
Technology:
Digital flight control law sophistication is fragmenting supplier roles between hardware fabrication and software verification competencies.
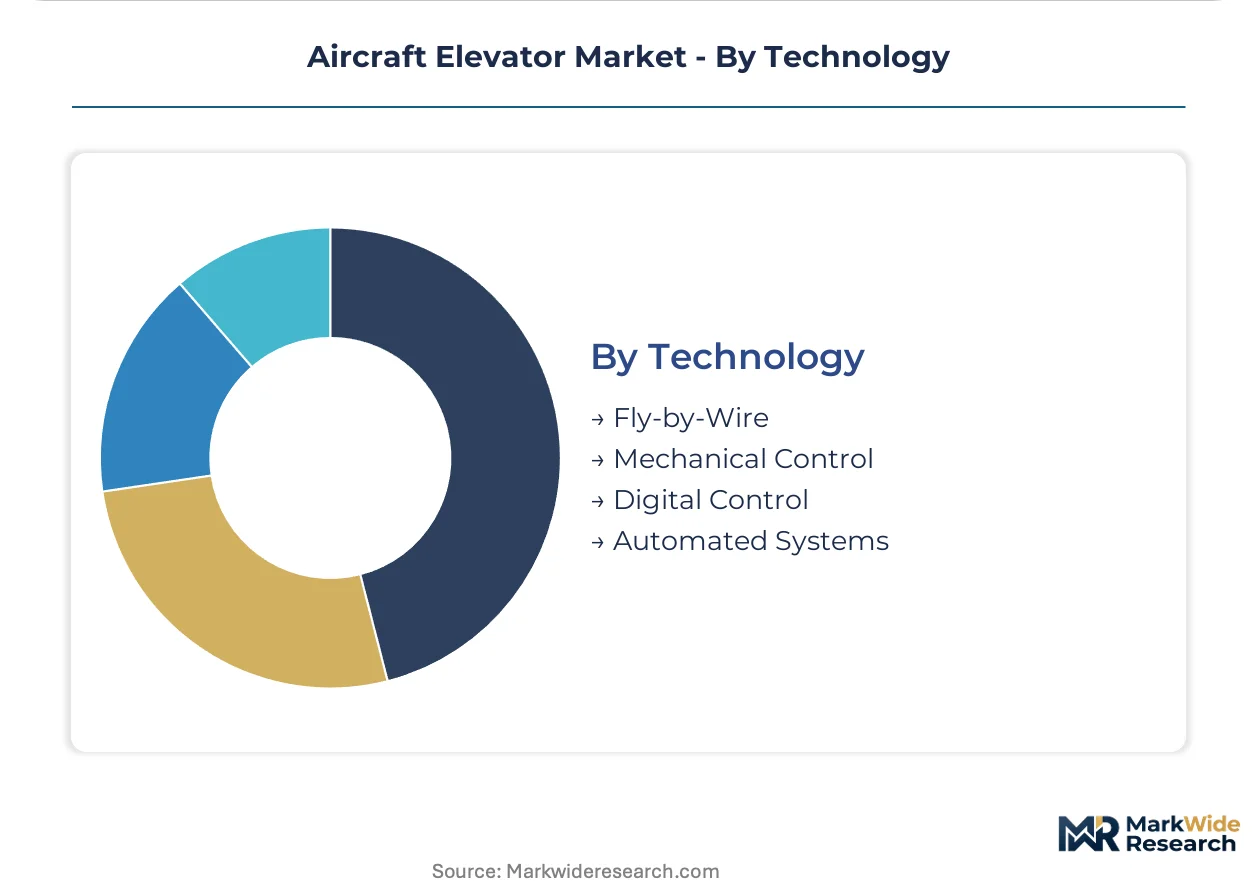
- Fly-by-Wire:Digital flight control computers replace mechanical linkages with electrical signaling to electrohydraulic actuators, enabling envelope protection and load alleviation functions. Moog Inc. dominates narrowbody electrohydraulic channel integration for Boeing and Airbus programs.
- Digital Control:Standalone digital processing units for secondary flight control axes reduce wiring mass through data bus consolidation.
- Mechanical Control:Pushrod and cable systems persist on light sport and legacy general aviation categories where type certificate continuity blocks architecture migration.
- Automated Systems:Autoland and automatic trim functions impose additional certification rigor on elevator servo loop stability margins.
Fly-by-Wire anchors current specification share. Digital Control architectures are gaining share fastest on next-generation urban air mobility prototypes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Wichita MRO cluster anchors North American elevator maintenance capacity, while Toulouse-connected supply chains and Seattle-area final assembly lines concentrate OEM specification authority across three continents.
United States
Boeing final assembly lines in Seattle and Renton drive electric elevator specification for narrowbody programs, while FAA airworthiness directives mandate repetitive hinge bearing inspections for aging 737NG fleets. The Wichita, Kansas Part 145 repair station cluster specializes in elevator spar assessment and balance weight modification services.
France
Airbus S.A.S. engineering teams in Toulouse specify carbon-epoxy composite torque boxes for A320neo and A350 horizontal stabilizer attachments. EASA CS-25 Amendment 25-148 governs flutter clearance validation timelines for European-registered aircraft modifications. The Toulouse-Blagnac aerospace cluster hosts specialized ground vibration test facilities for elevator certification.
Germany
Liebherr Group's vertically controlled machining operations in Lindenberg produce titanium elevator brackets for Airbus programs. Aging A320ceo fleet bases in Frankfurt and Munich sustain aftermarket demand for hydraulic actuator overhaul services. The country's national aviation regulator enforces structural integrity standards for flight control surface modifications.
India
IndiGo and Air India order backlogs for A320neo-family aircraft concentrate greenfield demand for electric elevator architectures. The country's national aviation regulator mandates compliance with EASA-equivalent certification standards for imported flight control components. Bangalore and Hyderabad maintenance facilities are developing captive elevator inspection capabilities for expanding narrowbody fleets.
United Kingdom
BAE Systems defense procurement sustains ruggedized hydraulic elevator specification for tactical transport platforms. The country's national aviation regulator enforces airworthiness directives aligned with FAA and EASA standards for commercial fleet compliance. Southwest England aerospace clusters specialize in military flight control system integration and environmental qualification testing.
Aircraft Elevator Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers position for fly-by-wire system integration contracts. The vendor base organizes around three tiers: diversified aerospace conglomerates controlling full flight control channels, specialized actuator manufacturers captive to single platforms, and composite fabricators supplying structural components under OEM specification. Two competitive moves define current positioning: technology licensing agreements that transfer digital flight control law competencies, and geographic co-location with final assembly lines to compress logistics lead times.
Among diversified system integrators, Moog Inc., Honeywell International Inc., and Liebherr Group exemplify distinct strategic archetypes. Moog Inc. represents the electrohydraulic channel integration specialist, anchoring narrowbody fly-by-wire actuator supply relationships. Honeywell International Inc. occupies a position emphasizing aftermarket health monitoring algorithms that predict component degradation. Liebherr Group anchors European supply chain positioning through in-house production of titanium structural fittings for Airbus programs.
| Leading Market Players |
|---|
| Moog Inc. |
| BAE Systems |
| Honeywell International Inc. |
| Nabtesco Corporation |
| Liebherr Group |
| Airbus S.A.S. |
| PaR Systems |
| Otis Elevator Company |
| Raytheon Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
OEM procurement teams at Boeing and Airbus final assembly lines negotiate multi-year actuator service agreements that anchor contract-based long-term offtake pricing across electric elevator architectures. This buyer concentration compresses margin pools for component suppliers while rewarding scale-advantaged manufacturers with captive titanium machining capabilities.
Pricing Analysis
Titanium sponge and carbon-epoxy prepreg cost pass-through clauses dominate contract structures for primary torque box assemblies. Pricing stratifies across OEM-certified, Part 145 repair station, and aftermarket distributor tiers based on FAA certification level and volume scale commitments. Cost compression in hydraulic actuator overhaul services is intensifying because MRO providers compete on cycle-time guarantees for aging narrowbody fleets. Low-cost carriers in India exhibit highest price sensitivity, while defense procurement offices in France and the United States demonstrate lowest sensitivity due to MIL-STD-810 qualification requirements.
Supply Chain Analysis
Regional distribution centers in Wichita, Kansas and Toulouse, France operate hub-and-spoke patterns for elevator spar inspection equipment and hinge bearing replacement kits. Manufacturing concentration rests on the United States, France, and Germany, where Moog Inc., Liebherr Group, and Honeywell International Inc. maintain captive production of electrohydraulic actuators and titanium brackets. Raw material dependencies draw from Russian titanium sponge, Japanese carbon fiber precursors, and German high-speed steel cutting tools. Single-source actuator vulnerability for narrowbody fly-by-wire channels creates structural supply risk. Distribution runs through OEM direct channels for new-build programs and specialized Part 145 stations for aftermarket maintenance events.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Elevator Market represents a late-cycle quality story as fleet renewal programs shift procurement emphasis toward premium electric architectures with integrated health monitoring capabilities. Carbon-epoxy composite specification for primary flight control surfaces is displacing legacy aluminum assemblies across next-generation narrowbody and widebody programs.
For Market Incumbents: Deploy predictive health monitoring algorithms as the primary defensive lever against emerging sensor fusion specialists. Moog Inc. and Honeywell International Inc. should deepen captive repair capabilities in Wichita to defend against MRO network consolidation threatening actuator overhaul margins. Certification investment in EASA CS-25 Amendment 25-148 flutter clearance capabilities protects against European MRO providers captive-hiring engineering talent. For New Entrants and Emerging Players: Capture unmet demand for specialized elevator spar inspection services in the Bangalore and Hyderabad maintenance cluster as IndiGo and Air India fleet expansion outpaces training pipeline output for NDT-certified technicians. The most penetrable segment lies in hybrid fly-by-wire retrofits for 737NG and A320ceo platforms requiring custom actuator mounting solutions. A direct contracting angle with low-cost carriers bypassing traditional airframe heavy maintenance channels accelerates market entry. For Investors and Strategic Acquirers: Tier 1 aerospace suppliers seeking fly-by-wire system integration capabilities are the most active acquirer in this space, particularly those lacking electrohydraulic channel expertise. Acquisition targets should display in-house production of titanium structural fittings paired with EASA certification track records. The signal to watch is MRO network consolidation velocity in North America, which indicates pricing power inflection for component OEMs with direct airline relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Machining | Liebherr Group's Lindenberg operations supply Airbus A350 hinge brackets, reducing Russian sponge price volatility exposure. |
| Predictive Health Monitoring Platform Launch | Honeywell International Inc. unbundles sensor fusion algorithms from hardware sales, creating recurring aftermarket revenue streams. |
| Joint Venture for Composite Torque Box Production | Boeing and Airbus engineering teams specify thermoset prepregs that reduce parasitic drag penalties on long-haul stage lengths. |
| Long-term Actuator Service Agreement | Commercial carriers in India negotiate fleet-level contracts for A320neo-family electric elevator architectures, bypassing traditional MRO intermediaries. |
| EASA Certification Capability Investment | Regional MRO providers in France captive-hire flutter analysis capabilities previously outsourced to Toulouse engineering teams. |
Methodological Framework
Bottom-up commercial aviation fleet modeling reconciled against top-down actuator production tracking forms the analytical core of this study. Primary interviews with MRO station managers, OEM procurement executives, FAA certification engineers, and composite process engineers were combined with secondary validation from EASA CS-25 amendment filings, FAA airworthiness directive databases, and customs trade data for titanium sponge and carbon fiber imports. Triangulation between supply-side capacity announcements and demand-side fleet maintenance schedules ensures cross-verification of installation type projections.
Input-output matrix framing connects raw material flow assumptions through tiered supplier networks to end-use consumption across OEM new-build, retrofit, and maintenance channels. Segmentation dimensions modeled include product type, end user category, installation type, and technology architecture across the projection horizon. CAGRs were derived from fitted trend lines incorporating fleet age profiles, regulatory inspection mandate timelines, and material substitution elasticities. Industry-specific forecast inputs include narrowbody delivery backlogs from Airbus and Boeing order books and EASA certification timeline extensions under Amendment 25-148.
Underlying measurement precision varies by segment; electric elevator architectures and fly-by-wire technology deployments carry tighter precision than conventional mechanical linkage retrofits due to clearer OEM specification visibility. Forecasts reflect documented assumptions regarding titanium supply chain stability and MRO technician training pipeline expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
North America Helicopters Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Fighter Aircraft Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Afterburner Market
Aircraft
Aircraft Door Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Firefighting Aircraft Market
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Search and Rescue Aircraft Market