
 Light Sport Aircraft (LSA) Market | 2026-2036
Light Sport Aircraft (LSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Light Sport Aircraft (LSA) Market Insights
Recreational private owners is collapsing as the dominant buyer archetype while flight schools and tourism operators capture incremental share. Pipistrel leverages composite manufacturing expertise to dominate electric-hybrid propulsion development for the LSA category. CubCrafters, Inc. sustains premium positioning through handcrafted aluminum construction and backcountry specialization. Diamond Aircraft Industries anchors European demand with its Austro Engine diesel platforms and integrated glass cockpit systems.
Light Sport Aircraft denotes factory-built, ready-to-fly aircraft certified to ASTM consensus standards with maximum takeoff weight of 1,320 pounds and top calibrated airspeed of 120 knots, designed primarily for recreational flight and ab initio pilot training. Fixed-wing configurations occupy the mature volume core of the market while composite structures technology captures expanding margin pools through reduced airframe weight and improved fuel efficiency. Powered parachute segments compete at the entry price tier where private owners seek minimal certification burden.
The FAA governs LSA airworthiness through ASTM F2245 standards and sport pilot certificate limitations, while EASA's CS-LSA framework governs European market access with divergent weight and speed parameters. ASTM International updates consensus standards annually, forcing manufacturers to maintain active compliance engineering. Stakeholders must monitor battery energy density thresholds and electric propulsion certification precedents as regulatory bodies weigh novel powertrain architectures against existing airworthiness frameworks.
Market Dynamics
Electric propulsion architectures are decomposing the traditional reciprocating engine supply chain, forcing airframers to reconfigure weight distribution, thermal management, and battery integration protocols across new LSA development programs.
Growth Catalysts
- FAA Part 23 Modernization:Streamlined certification pathways reduce type approval timelines for innovative airframe designs, lowering barriers for new market entrants.
- Composite manufacturing scale:Automated fiber placement and resin transfer molding cut airframe production costs while improving strength-to-weight ratios for flight school operators.
- Flight school fleet expansion:Training institutions across the United States are replacing legacy trainers with LSAs to reduce hourly operating costs and maintenance downtime.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel compress margins on electric-hybrid propulsion systems.
- European certification divergence:EASA CS-LSA weight and speed parameters differ from ASTM F2245 standards, fragmenting design compliance costs.
- Aviation gasoline supply concentration:Refinery capacity for 100LL avgas concentrates in a handful of North American suppliers, exposing operators to fuel availability risk.
Strategic Opportunities
- Brazilian recreational aviation:Underdeveloped private airstrip infrastructure and rising middle-class disposable income create whitespace for entry-level LSA penetration.
- Battery-swapping networks:Ground infrastructure innovation enables electric LSAs to bypass charging downtime constraints, unlocking tourism and rental applications.
- EU Green Deal aviation incentives:Member state subsidies for low-emission aircraft tilt procurement decisions toward electric-hybrid platforms in continental Europe.
Industry Challenges
- Composite repair technician scarcity:Certified airframe mechanics trained in carbon fiber damage assessment remain concentrated at OEM service centers, limiting field repair capacity.
- ASTM compliance engineering burden:Annual consensus standard updates force manufacturers to maintain active redesign cycles, diverting R&D resources from next-generation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Sport Aircraft (LSA) Market |
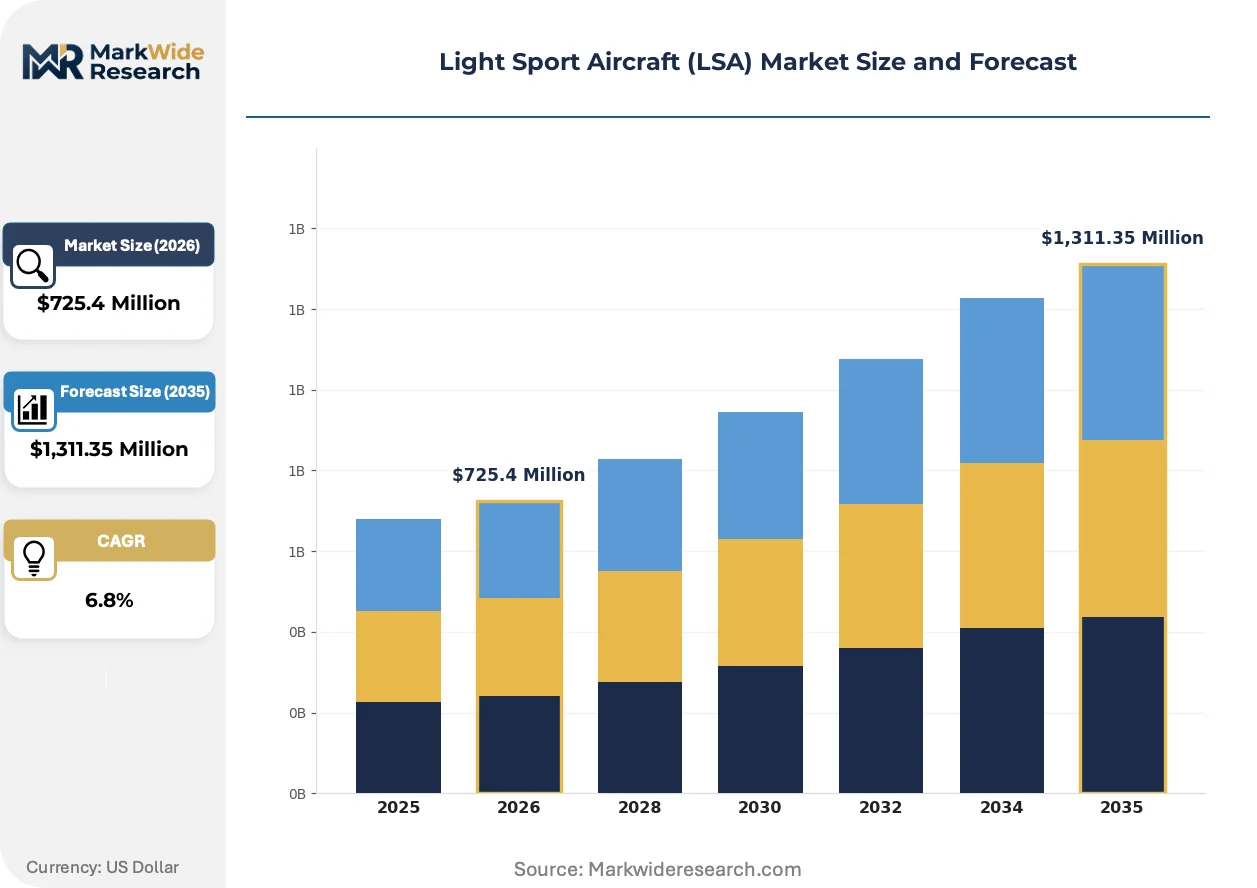
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,311.35 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Weight-Shift Control, Powered Parachute, Powered Glider Technology: Avionics, Composite Structures, Engine Type, Flight Control Systems Application: Recreational Flying, Pilot Training, Aerial Photography, Agricultural Surveying End User: Flight Schools, Private Owners, Aerial Survey Companies, Tourism Operators |
| Companies Covered | Pipistrel, Evektor-Aerotechnik a.s., Cirrus Aircraft, Jabiru Aircraft Pty Ltd., Diamond Aircraft Industries, Textron Inc., Costruzioni Aeronautiche TECNAM S.p.A, CubCrafters, Inc., Flight Design General Aviation GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Sport Aircraft (LSA) Market Trends and Innovations
Propulsion electrification, regulatory harmonization efforts, and shifting buyer demographics are restructuring how light aircraft are designed, certified, and operated across recreational and training segments.
Electric-hybrid powertrains are decomposing the conventional engine-airframe integration model. Battery-electric systems eliminate reciprocating engine vibration profiles, enabling lighter airframe structures and reduced maintenance intervals. Flight schools in California and Florida are piloting these platforms for pattern work and primary instruction, compressing total cost of ownership calculations against legacy Rotax-powered alternatives.
EASA's CS-LSA framework revision is narrowing certification gaps with ASTM standards, reducing dual-compliance costs for manufacturers serving transatlantic markets. The harmonization effort specifically addresses weight allowances for electric propulsion systems and ballistic parachute installations. European OEMs with US distribution networks are restructuring engineering teams to capture simplified type approval pathways.
Recreational buyers are fragmenting into specialized subsegments with divergent equipment demands. Backcountry enthusiasts prioritize STOL performance and tundra tire compatibility, while cross-country tourers demand integrated glass cockpit systems and autopilot capability. This bifurcation is visible in United States sales data, where CubCrafters and Pipistrel serve minimally overlapping customer profiles despite shared LSA certification.
Light Sport Aircraft (LSA) Market Segmentation
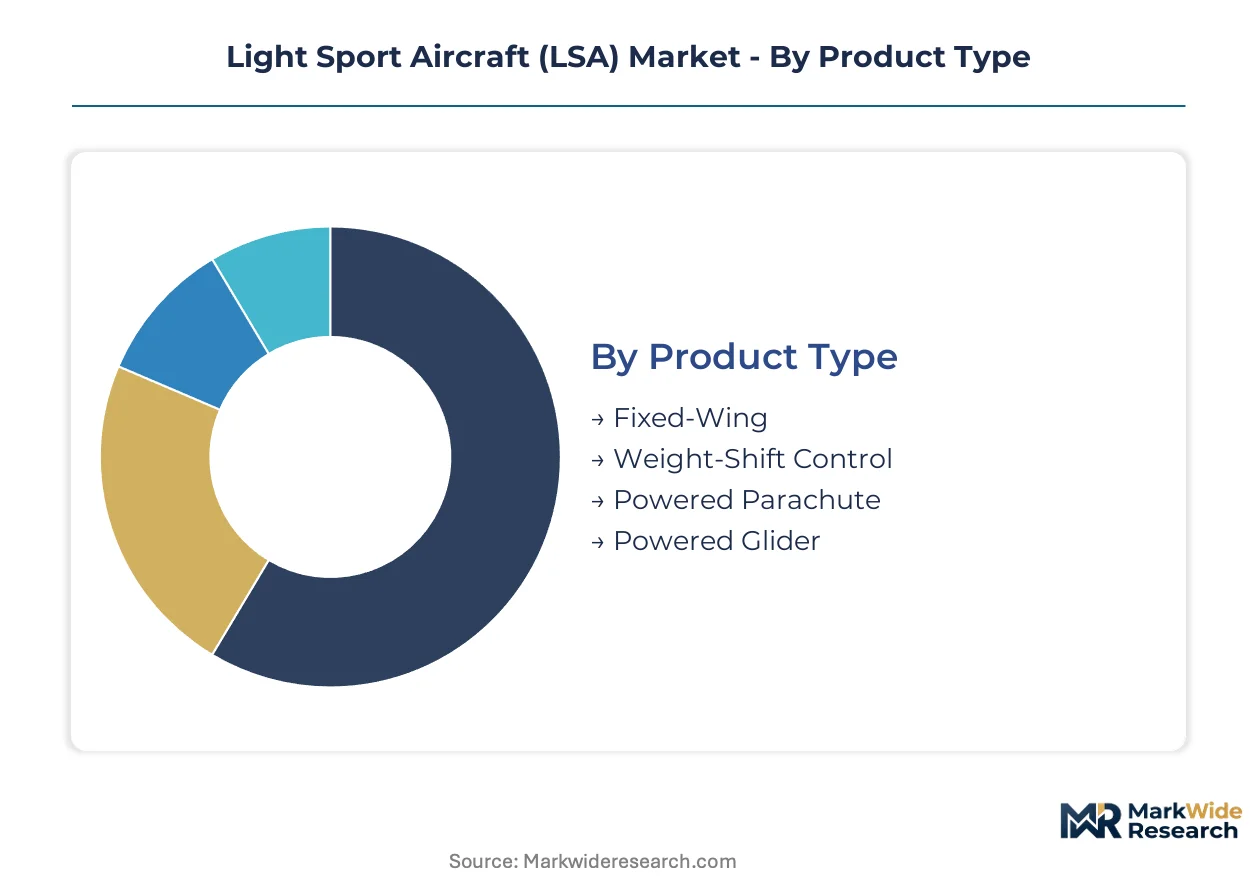
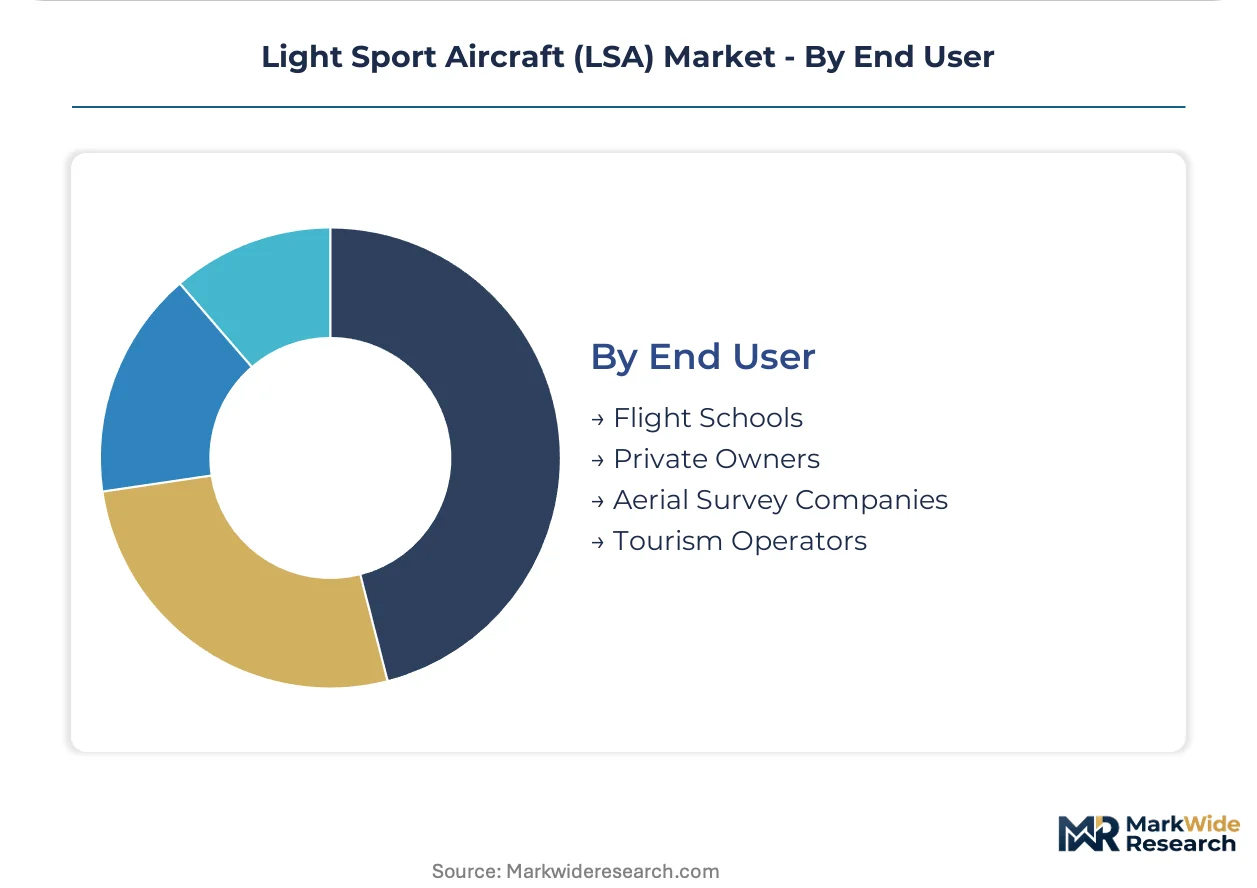
Segmentation in the LSA market reveals how regulatory constraints, operational economics, and buyer sophistication split demand across divergent equipment specifications. Flight schools prioritize hourly operating costs and maintenance simplicity, while private owners weight acquisition price against customization potential.
Product Type:
Fixed-wing configurations dominate factory-direct sales through established dealer networks, while weight-shift and parachute variants concentrate in direct-to-consumer online channels and recreational expos.
- Fixed-Wing:Conventional high-wing and low-wing designs with tricycle or tailwheel landing gear configurations. Demand concentrates in United States flight schools replacing aging Cessna 150/152 fleets, driven by ASTM F2245 certification streamlining and reduced insurance premiums versus standard category trainers.
- Weight-Shift Control:Trike-style aircraft with flexible wing structures and weight-shift steering mechanisms. Recreational buyers in Florida and Arizona coastal regions favor these for portability and storage efficiency, constrained by limited crosswind capability and restricted utility in commercial training applications.
- Powered Parachute:Parachute canopy propulsion systems with minimal airframe structure. Entry-level private owners seeking lowest certification burden and storage footprint.
- Powered Glider:Self-launching motor gliders with retractable propulsion. Cross-country tourers demanding thermal soaring capability with engine backup.
By volume, Fixed-Wing leads. By growth pace, Powered Parachute is ahead.
Technology:
Cost tiers separate avionics and composite investments, with flight schools accepting basic glass panels while private owners upgrade to integrated autopilot suites.
- Avionics:Integrated glass cockpit displays, GPS navigation, and ADS-B transponder systems. Flight schools in California specify Garmin G3X Touch configurations for standardized training fleets, balancing acquisition cost against reduced student transition time to commercial aircraft.
- Composite Structures:Carbon fiber and fiberglass airframe construction using resin transfer molding. European OEMs serving United States export markets leverage automated fiber placement to meet ASTM F2245 weight limits while accommodating ballistic parachute installations.
- Engine Type:Rotax piston, Austro Engine diesel, and emerging electric-hybrid architectures. Diesel platforms dominate European flight schools seeking Jet-A fuel compatibility.
- Flight Control Systems:Mechanical pushrod, cable-actuated, and fly-by-wire configurations. Backcountry specialists prioritize manual systems for field repairability.
Composite Structures command margin premiums. Avionics shows steepest expansion trajectory as training fleets modernize.
Application:
Maturity curves diverge sharply: recreational and training segments operate on replacement cycles, while aerial work applications demand payload-optimized configurations.
- Recreational Flying:Weekend and vacation-oriented private aviation with minimal payload requirements. United States buyers in Mountain West states prioritize STOL performance for backcountry airstrip access, driving tundra tire and extended slat specifications.
- Pilot Training:Ab initio instruction through sport pilot and private pilot certificate preparation. Flight schools in Texas and Florida expanding LSA fleets cite 40% hourly operating cost reduction versus legacy trainers.
- Aerial Photography:Camera platform missions requiring stable slow-flight characteristics. Tourism operators in Hawaiian and Alaskan markets.
- Agricultural Surveying:Crop monitoring and livestock counting with sensor payload integration. Aerial survey companies in Midwest grain belt regions.
Pilot Training anchors volume. Aerial Photography climbs the fastest as drone regulations tighten.
End User:
Customer type determines procurement channel: flight schools purchase through fleet lease programs, private owners through factory direct or dealer inventory, commercial operators through specialized aerial work configurators.
- Flight Schools:Certificated training institutions operating under FAA Part 61 or Part 141. United States schools in Arizona and Florida sunbelt regions replace high-time legacy trainers, constrained by insurance requirements for dual instruction and maintenance logbook documentation standards.
- Private Owners:Individual recreational pilots holding sport pilot or higher certificates. Backcountry enthusiasts in Idaho and Montana prioritize CubCrafters STOL designs, while cross-country tourers specify Diamond Aircraft diesel platforms for fuel efficiency.
- Aerial Survey Companies:Commercial operators performing mapping, inspection, and monitoring missions. Payload-optimized configurations with hardpoint mounts.
- Tourism Operators:Scenic flight and experience providers in destination markets. Hawaiian and Alaskan operators favor open-cockpit weight-shift designs for passenger experience differentiation.
Flight Schools dominate procurement volume. Tourism Operators gain share fastest as experience economy spending recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airframe manufacturing concentrates in Slovenia, the Czech Republic, and the United States, where ASTM F2245 compliance infrastructure and recreational aviation culture sustain production clusters. FAA certification pathways anchor North American demand, while EASA's CS-LSA framework governs European market access with divergent weight parameters.
United States
Flight schools in Arizona and Florida sunbelt regions drive fleet replacement cycles, citing hourly operating cost advantages over legacy trainers. FAA Part 23 Modernization streamlines type approval timelines for innovative airframe designs. California and Texas host the densest concentrations of sport pilot certificate holders and private airstrip infrastructure.
Germany
Diesel propulsion platforms dominate flight school procurement decisions, leveraging Jet-A fuel compatibility to reduce operating expenditure. EASA CS-LSA weight allowances for electric powertrains are under active revision. Baden-Württemberg and Bavaria host engineering clusters specializing in composite airframe manufacturing and glass cockpit integration.
Slovenia
Electric-hybrid propulsion development anchors national industrial strategy, with battery energy density gains enabling certified production timelines. ASTM F2245 compliance engineering supports transatlantic export positioning. The Ajdovščina manufacturing corridor concentrates composite fabrication expertise for light aircraft serial production.
Czech Republic
Metal airframe traditions persist alongside carbon fiber adoption, serving European recreational buyers and flight training institutions. EASA certification harmonization efforts with ASTM standards reduce dual-compliance engineering burdens. The Kunovice aviation cluster maintains specialized tooling for low-wing LSA configurations.
Australia
Recreational aviation culture supports kit-built and factory-built aircraft demand across vast interior territories with limited commercial air service. The country's national aviation regulator maintains alignment with ASTM consensus standards for type acceptance. Queensland and New South Wales host the highest density of sport pilot activity and private airstrip development.
Light Sport Aircraft (LSA) Market Competitive Landscape
Concentration sits with specialized airframers leveraging composite manufacturing expertise or metal construction heritage to defend segment positioning. The vendor base spans Slovenian electric propulsion innovators, Czech metalworking specialists, and American backcountry configuration experts. Three archetypes dominate: composite-centric electric developers, handcrafted aluminum traditionalists, and integrated avionics platform providers. Competitive moves center on certification pathway optimization and propulsion technology licensing rather than capacity expansion.
Within the electric-hybrid tier, Pipistrel anchors Slovenian output and exemplifies battery-electric certification advancement. Among American fabricators, CubCrafters, Inc. occupies a position aligned with backcountry specialization and STOL performance optimization. Diamond Aircraft Industries represents the European diesel-integrated archetype, with Austrian engineering supporting glass cockpit platform development. These three sit within minimally overlapping customer profiles despite shared ASTM F2245 certification compliance.
| Leading Market Players |
|---|
| Pipistrel |
| Evektor-Aerotechnik a.s. |
| Cirrus Aircraft |
| Jabiru Aircraft Pty Ltd. |
| Diamond Aircraft Industries |
| Textron Inc. |
| Costruzioni Aeronautiche TECNAM S.p.A |
| CubCrafters, Inc. |
| Flight Design General Aviation GmbH |
| Others |
Pricing and Supply Chain Analysis
Ninety-day airframe kit lead times from Slovenian and Czech manufacturing clusters concentrate pricing power with composite fabrication specialists, while ASTM F2245 compliance engineering costs propagate downstream to flight school fleet operators. Inventory velocity at United States dealer networks fluctuates with seasonal pilot training demand, compressing margin buffers for backcountry configuration specialists during winter quarters.
Pricing Analysis
ASTM F2245 certification tiers dictate the pricing tier structure across factory-built, ready-to-fly aircraft. Three-tier pricing structure across premium handcrafted aluminum, standard composite production, and economy kit-built configurations separates CubCrafters backcountry specialists from Diamond Aircraft diesel-integrated platforms and entry-level powered parachute vendors. Cost compression in electric-hybrid propulsion tiers is intensifying because lithium-ion battery raw material volatility compresses margins on Pipistrel battery-electric architectures. Flight school procurement teams exhibit highest price sensitivity due to hourly operating cost benchmarking against legacy Cessna trainers, while private backcountry enthusiasts demonstrate lowest sensitivity when STOL performance specifications justify premium positioning.
Supply Chain Analysis
Just-in-time composite pre-preg inventory management dominates Slovenian and Czech manufacturing corridors, contrasting with strategic Rotax engine stockpiling at United States flight school distribution hubs. Airframe production draws from Austria, Slovenia, and the Czech Republic, with carbon fiber sourcing tethered to European automated fiber placement specialists and reciprocating engine supply anchored in Austrian Rotax facilities. Single-source vulnerability concentrates in 100LL avgas refinery capacity across a handful of North American suppliers. Distribution runs through factory-direct dealer networks for fixed-wing configurations and recreational expo channels for weight-shift and powered parachute variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight school fleet replacement cycles position this market as a cyclical recovery, justified by post-pandemic pilot training demand normalization across Arizona and Florida sunbelt regions.
For Market Incumbents: Secure composite repair technician training capacity through OEM service center partnerships, as certified carbon fiber damage assessment scarcity constrains field repair networks. Defend against electric-hybrid propulsion entrants by accelerating ASTM F2245 compliance engineering for battery-electric architectures, locking in certification pathway advantages before EASA-ASTM harmonization completes. For New Entrants and Emerging Players: Anchor in Brazilian recreational aviation whitespace where private airstrip infrastructure underdevelopment and rising middle-class disposable income create entry-level LSA penetration opportunities. Target battery-swapping network ground infrastructure innovation as the most penetrable application, unlocking tourism and rental electric LSA deployments through charging downtime elimination. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because ASTM F2245 compliance engineering burdens and annual consensus standard update cycles erect durable barriers against rapid competitive replication. Acquisition target archetype: European OEMs with transatlantic distribution networks positioned to capture EASA-ASTM harmonization simplification. Watch battery energy density threshold crossings at certified aviation-grade suppliers as the inflection indicator for electric propulsion economics viability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Certification | ASTM F2245 battery-electric compliance engineering unlocks flight school hourly cost advantages over Rotax alternatives. |
| Composite Manufacturing Scale-Up | Automated fiber placement investment in Slovenian corridors reduces airframe weight while accommodating ballistic parachute installations. |
| Flight School Fleet Partnership | Long-term lease programs with Arizona and Florida training institutions secure volume offtake against seasonal demand fluctuation. |
| Transatlantic Distribution Expansion | EASA CS-LSA framework revision alignment captures simplified type approval pathways for dual-compliant airframe designs. |
| Backcountry Configuration Specialization | STOL performance optimization and tundra tire compatibility defend premium positioning against commoditized cross-country tourer platforms. |
Research Methodology
Operator-level perspectives from flight school fleet managers, FAA designated engineering representatives, composite airframe manufacturing engineers, and recreational aviation dealer principals anchored the qualitative base. Primary interview synthesis combined with secondary validation from FAA type certificate databases, ASTM International consensus standard revision records, EASA CS-LSA regulatory filings, and United States sport pilot certificate issuance statistics. Bottom-up airframe production estimates and top-down recreational aviation expenditure analysis triangulated volume and value outputs.
Sensitivity analysis across electric propulsion adoption scenarios, lithium-ion battery cost trajectories, and EASA-ASTM harmonization timelines stress-tested projection robustness. Segmentation modeling spanned product type, propulsion architecture, end-user category, and regional regulatory framework across the analysis window. CAGRs derived from fitted trend extrapolation calibrated against historical flight school fleet replacement cycles and recreational aircraft registration patterns. Industry-specific forecast inputs incorporated ASTM F2245 weight limit enforcement stringency and 100LL avgas supply concentration risk.
Material uncertainties — lithium-ion raw material price volatility, EASA CS-LSA electric powertrain weight allowance revisions, and flight school insurance requirement shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding battery energy density progression and certification pathway streamlining efficacy. Revision becomes warranted when electric propulsion type certificate issuance velocity crosses thresholds that displace reciprocating engine share in flight school procurement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
America Attack Helicopter Market
Aircraft
Europe Business Jet Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Global Business Jets Market
Aircraft
North America Military Helicopters Market
Aircraft
Commercial Aircraft Market
Aircraft
Strategic Bomber Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Aircraft Seals Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Latin America General Aviation Market
Aircraft
Sailplane Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Global Aircraft Electric Brake Control System Market