
 France Nuclear Bombs and Missiles Market | 2026-2036
France Nuclear Bombs and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
France Nuclear Bombs and Missiles Market Insights
France's 2024 Loi de Programmation Militaire is broadening the cost-of-entry calculus for domestic defense contractors. Thales Group leverages its sovereign electronics supply chain to sustain competitive positioning in guidance and sensor packages. Safran anchors propulsion subsystem development through its aerospace heritage and dedicated defense division. MBDA navigates complex multinational joint ventures while maintaining French industrial control over missile system integration.
France nuclear bombs and missiles encompass strategic and tactical warheads plus their delivery vehicles, with SLBMs like the M51.2 carrying six to ten multiple independently targetable reentry vehicles over 9,000 kilometers. These systems serve the primary purpose of assuring national survival through credible second-strike deterrence under NATO's independent nuclear umbrella. Sea-based deployment modes currently dominate procurement budgets given the ongoing SNLE 3G program replacing four Le Triomphant-class submarines. Air-launched nuclear weapons represent a mature segment with incremental Rafale F5 standard upgrades sustaining manufacturing lines. Guidance systems technology attracts concentrated R&D investment as precision requirements tighten for penetrator and variable-yield applications.
France's Direction Générale de l'Armement enforces product standards through its qualification authority over all nuclear-capable systems. The country's national security doctrine, reinforced by the Commission du Secret de la Défense Nationale, restricts market access to cleared contractors with permanent sovereignty safeguards. European Union dual-use export controls under the Wassenaar Arrangement further constrain technology transfer pathways. Stakeholders must monitor the intersection of domestic budget cycles with NATO burden-sharing negotiations to anticipate procurement timing shifts.
Market Dynamics
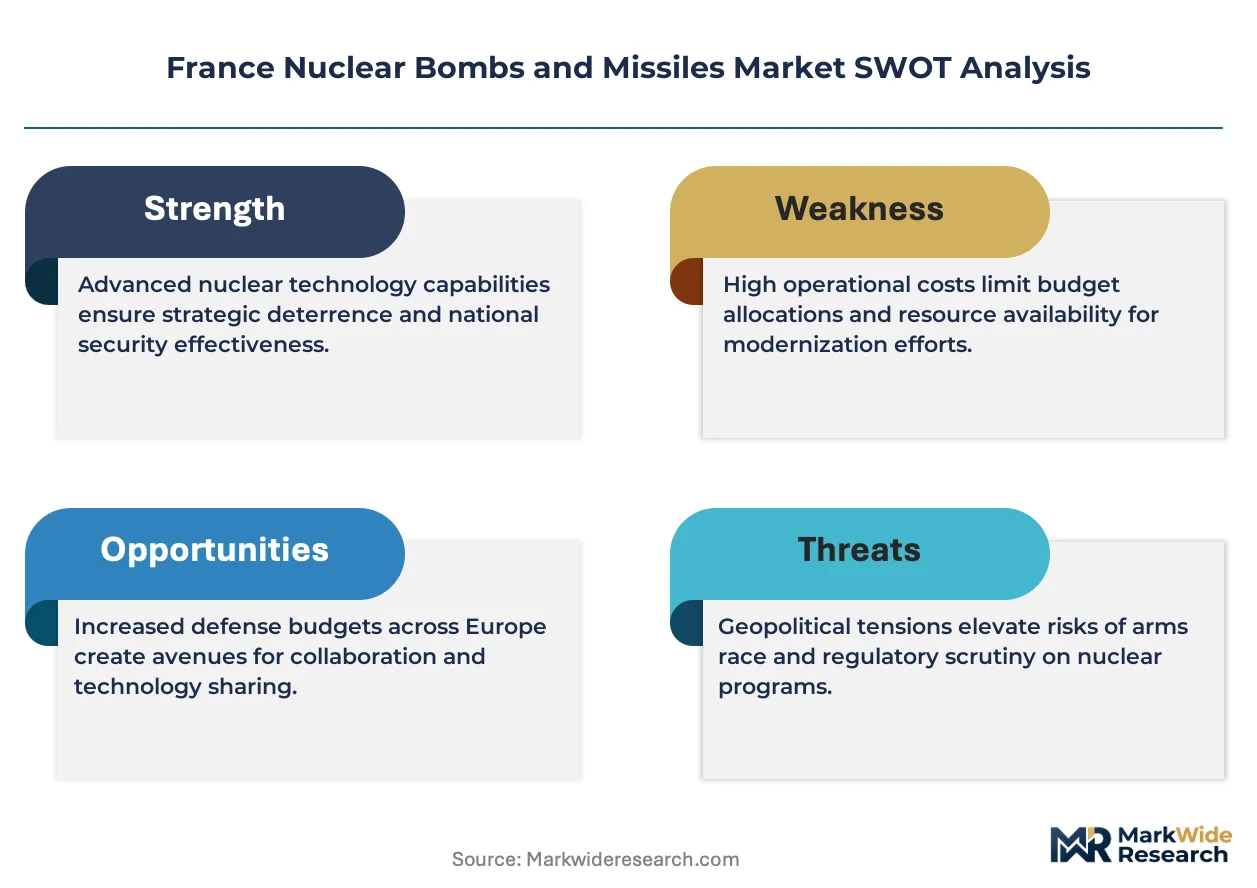
The SNLE 3G submarine replacement program is concentrating procurement budgets toward next-generation ballistic missile systems, compressing supplier margins while elevating technical qualification barriers for component vendors.
Growth Catalysts
- Loi de Programmation Militaire 2024-2030:The multi-year defense programming law locks in funding trajectories for nuclear deterrence modernization, giving contractors predictable revenue visibility across weapon system lifecycles.
- M51.3 SLBM development:Extended-range sea-launched ballistic missile upgrades are pulling advanced propulsion and guidance subsystem orders through the Direction Générale de l'Armement's qualification pipeline.
- Île-de-France aerospace cluster:Concentrated engineering talent around Paris-Saclay sustains rapid prototyping cycles for penetrator warhead aerodynamics and reentry vehicle thermal protection.
Market Restraints
- Highly enriched uranium supply concentration:Fuel cycle dependencies on a limited supplier base outside French borders create sovereign risk exposure for warhead production schedules.
- Commission du Secret de la Défense Nationale clearance requirements:Personnel vetting timelines extending 18-24 months restrict workforce scaling for cleared engineering positions.
- Tritium decay rates:Stockpile stewardship demands for gas transfer and recycling impose recurring maintenance burdens on warhead reliability certification.
Strategic Opportunities
- Rafale F5 standard integration:Air-launched nuclear cruise missile compatibility with upgraded fighter platforms opens manufacturing line extensions at Saint-Cloud.
- Hypersonic glide vehicle research:Converging scramjet propulsion with maneuverable reentry architectures is creating new qualification pathways for DGA-funded technology demonstrators.
- Brittany maritime test range:Expanded underwater acoustic measurement infrastructure at Brest supports accelerated SLBM validation cycles without third-party facility dependence.
Industry Challenges
- Systems engineering talent scarcity:Retirement waves among 1980s-era weapon designers are depleting institutional knowledge for two-stage thermonuclear device architecture.
- Microelectronics obsolescence management:Radiation-hardened component supply chains require continuous redesign cycles as commercial semiconductor nodes advance beyond qualified manufacturing processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Nuclear Bombs and Missiles Market |
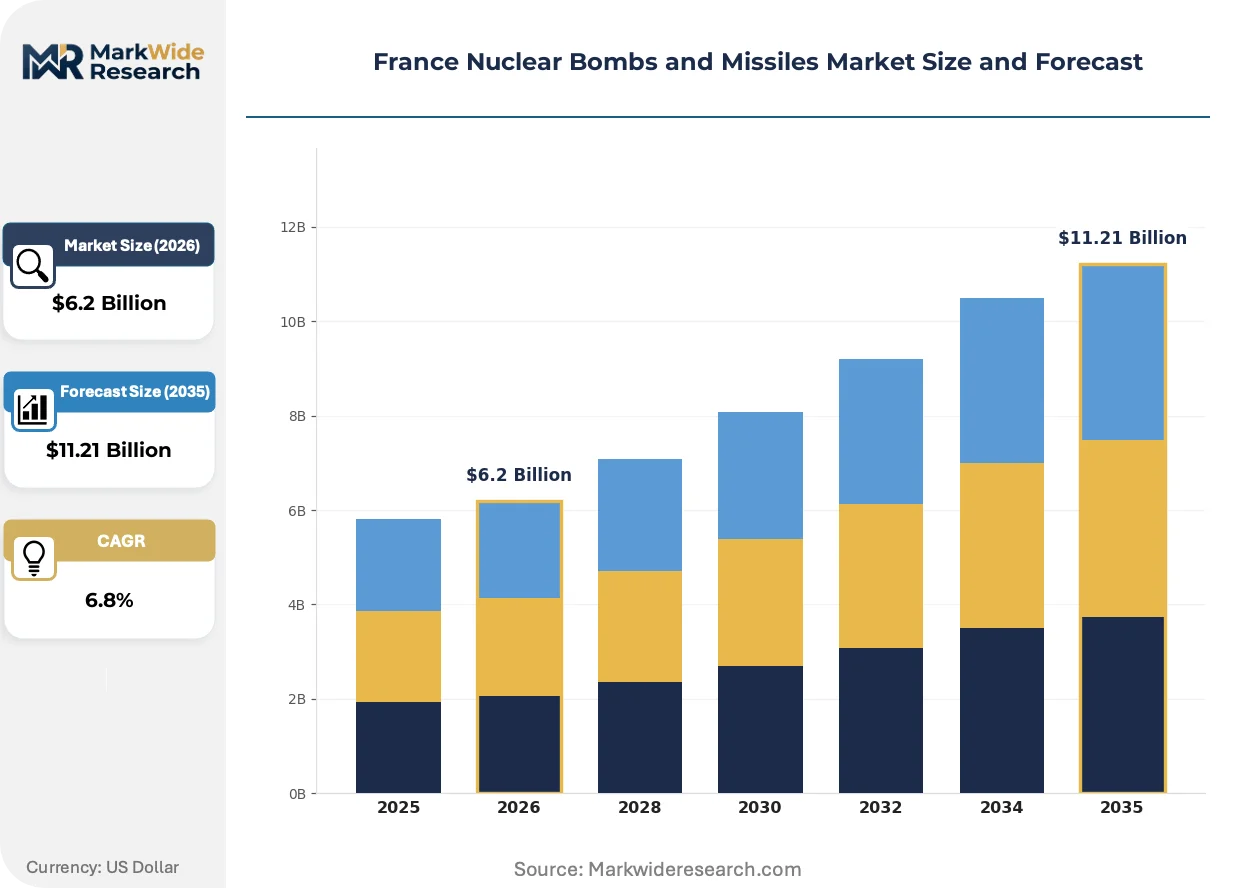
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ICBMs, SLBMs, Tactical Nuclear Weapons, Air-Launched Nuclear Weapons Deployment Mode: Land-Based, Sea-Based, Airborne, Mobile Platforms End User: Military, Government, Research Organizations, Defense Contractors Technology: Guidance Systems, Propulsion Systems, Detonation Mechanisms, Safety Mechanisms |
| Companies Covered | Thales Group, Safran, Naval Group, RTX (Raytheon France), DCNS (Naval Group subsidiary), MBDA, ArianeGroup, Lockheed Martin France, Dassault Aviation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Nuclear Bombs and Missiles Market Trends and Innovations
Digital engineering tools are compressing development timelines for nuclear weapon delivery systems while raising verification standards for simulation-to-flight correlation. This shift is redrawing supplier competencies around modeling expertise.
Modular payload bus architectures are integrating variable-yield physics packages with common aeroshell interfaces. The Direction Générale de l'Armement is mandating this flexibility for future stockpile configurations. Platform-agnostic warhead designs are reducing per-variant certification costs while expanding mission envelope options across submarine and air-launched basing modes.
France's transposition of EU dual-use export controls into national implementation decrees is tightening technology transfer pathways for subsystem vendors. The Wassenaar Arrangement category revisions are requiring enhanced end-user documentation for guidance electronics. Component suppliers serving both civilian aerospace and nuclear weapon programs are segmenting their order fulfillment systems to maintain compliance separation.
Consolidated prime contracting is displacing fragmented subsystem procurement for the SNLE 3G program. The French Ministry of Armed Forces is bundling propulsion, guidance, and reentry vehicle responsibilities under single-source arrangements. This concentration is compressing second-tier vendor access while elevating performance guarantees for integrated system deliveries.
France Nuclear Bombs and Missiles Market Segmentation
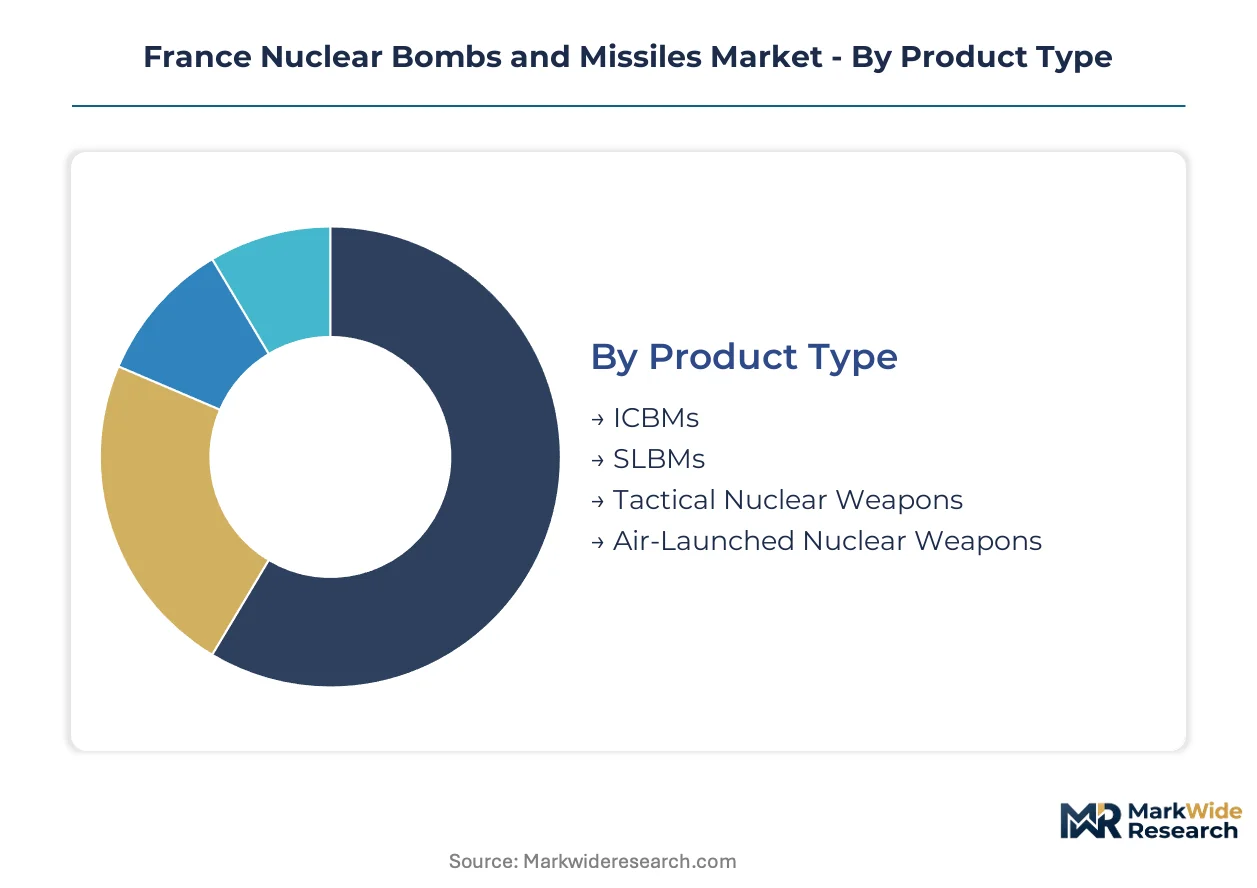
Segmentation in the France nuclear bombs and missiles market reveals how procurement priorities diverge across operational requirements and technical specifications. The Direction Générale de l'Armement structures qualification pathways differently for each category, creating distinct competitive dynamics among cleared contractors.
Product Type:
Buyers differentiate by strike range requirements and platform integration complexity, with longer-range systems demanding extended development timelines and higher subsystem qualification standards.
- ICBMs:Intercontinental ballistic missiles with ranges exceeding 5,500 kilometers require three-stage propulsion architectures and advanced penetration aids. France maintains no active ICBM inventory; research funding concentrates at Île-de-France aerospace clusters for technology preservation purposes.
- SLBMs:Sea-launched ballistic missiles like the M51 family carry multiple independently targetable reentry vehicles from submerged platforms. The SNLE 3G program is pulling procurement volumes toward next-generation M51.3 upgrades at the Brittany maritime test range.
- Tactical Nuclear Weapons:Short-range systems designed for battlefield employment with lower yield configurations and reduced collateral signatures.
- Air-Launched Nuclear Weapons:Cruise missile and gravity bomb configurations compatible with Rafale fighter platforms.
SLBMs lead volumes today; air-launched nuclear weapons are gaining share fastest through Rafale F5 standard integration.
Deployment Mode:
Platform selection determines survivability calculus and basing infrastructure requirements, with mobile and submerged options commanding premium qualification investments.
- Land-Based:Silo or road-mobile configurations requiring hardened command-and-control networks. France eliminated land-based nuclear forces under the 1996 defense review; residual infrastructure supports NATO coordination protocols.
- Sea-Based:Submarine-launched systems from Le Triomphant-class and successor SNLE 3G hulls. The French Ministry of Armed Forces concentrates modernization budgets here due to second-strike survivability requirements.
- Airborne:Fighter-delivered weapons from Rafale and successor platforms with aerial refueling support.
- Mobile Platforms:Rail or road-transportable launchers for rapid dispersal and target uncertainty.
Sea-based deployment absorbs the largest procurement allocation; airborne systems show the steepest expansion trajectory through platform upgrade cycles.
End User:
Clearance tiers and mission authority separate buyers, with operational military units holding exclusive custody of live warheads versus development organizations handling inert test articles.
- Military:The French Navy's Force Océanique Stratégique operates ballistic missile submarines; the Air and Space Force maintains nuclear-capable Rafale squadrons. Live weapon custody requires Commission du Secret de la Défense Nationale clearance at the highest level.
- Government:The Direction Générale de l'Armement and Commissariat à l'Énergie Atomique oversee development, testing, and stockpile stewardship functions.
- Research Organizations:CEA-DAM and affiliated laboratories conduct physics package design and materials aging studies.
- Defense Contractors:Thales, Safran, and MBDA perform subsystem integration under DGA supervision without warhead access.
Military end users dominate operational procurement; research organizations are expanding fastest through digital engineering and simulation investments.
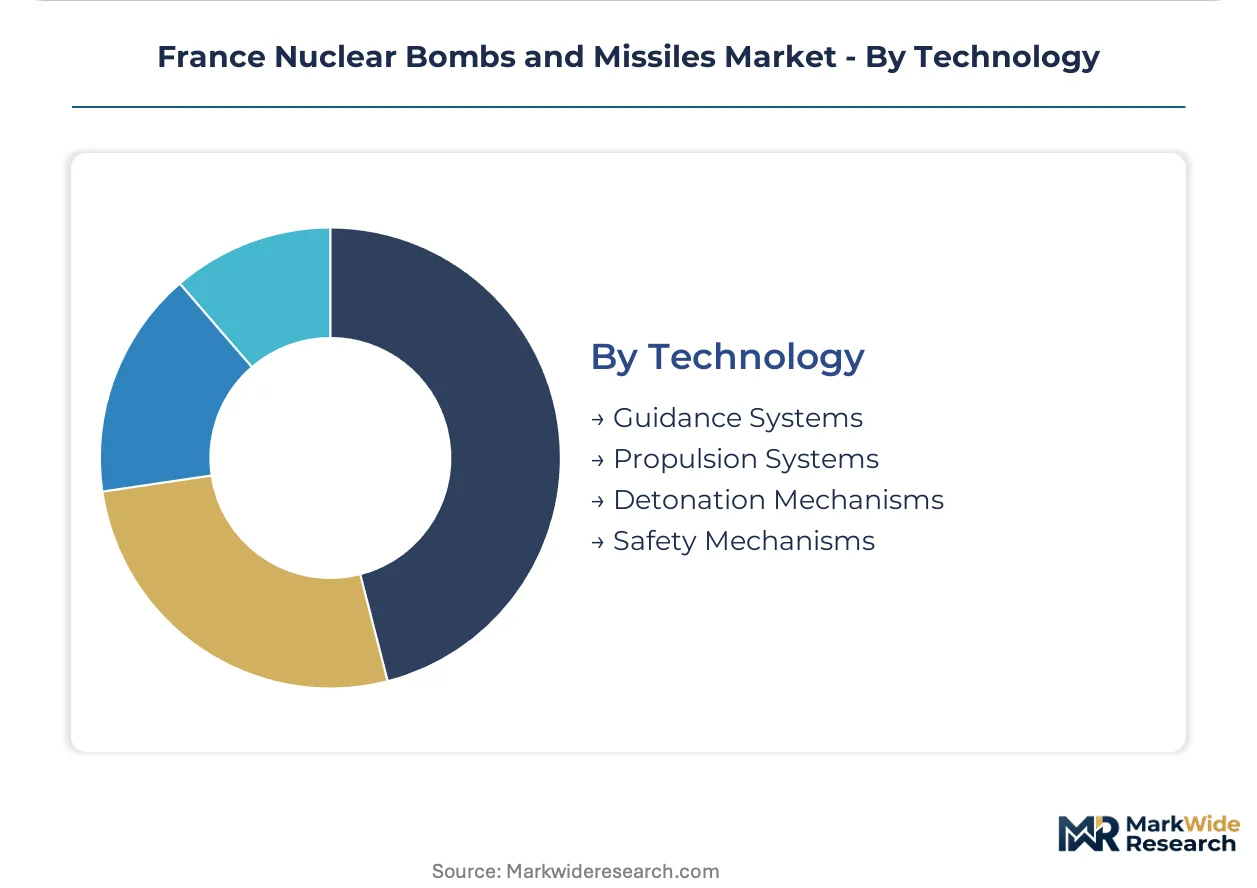
Technology:
Subsystem maturity and supply chain concentration determine vendor selection, with radiation-hardened electronics and specialized propulsion creating the highest barriers to entry.
- Guidance Systems:Inertial measurement units with stellar correction and terminal scene matching for precision targeting. Thales Group anchors this segment through sovereign electronics supply chains at Paris-Saclay facilities.
- Propulsion Systems:Solid-fuel rocket motors with composite casings and thrust vectoring nozzles. Safran's aerospace heritage supports two-stage motor development for extended-range SLBM applications.
- Detonation Mechanisms:Exploding bridgewire and slapper detonator technologies with enhanced safety interlocks.
- Safety Mechanisms:Command-disable and environmental sensing systems preventing unauthorized or accidental arming.
Guidance systems command the largest R&D allocation; propulsion systems are climbing the fastest through M51.3 range extension requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's nuclear weapons industry traces its origins to the post-war Commissariat à l'Énergie Atomique established in 1945, with industrial scale achieved through the 1960s Force de Frappe program. The current geography of production and R&D reflects this centralized heritage, concentrated in specific metropolitan clusters where sovereign capabilities were deliberately cultivated.
Île-de-France
The Paris-Saclay plateau hosts the densest concentration of nuclear weapons engineering talent in Europe, with Thales Group and ArianeGroup maintaining guidance and propulsion facilities. The Direction Générale de l'Armement enforces qualification standards from its Issy-les-Moulineaux headquarters. CEA-DAM laboratories at Bruyères-le-Châtel conduct physics package design and materials aging studies for warhead reliability certification.
Brittany
The Brest maritime test range provides underwater acoustic measurement infrastructure for SLBM validation without third-party facility dependence. Naval Group operates submarine construction yards at Cherbourg for the SNLE 3G program. The regional concentration of naval architecture expertise supports accelerated ballistic missile submarine prototyping cycles.
Auvergne-Rhône-Alpes
Safran anchors solid-fuel rocket motor development at its aerospace heritage facilities in the Grenoble-Valence corridor. The region's composite materials supply chain feeds thrust vectoring nozzle production for M51.3 range extension requirements. Local engineering schools feed specialized propulsion talent into cleared contractor positions.
Provence-Alpes-Côte d'Azur
MBDA maintains missile system integration capabilities near Cannes, navigating complex multinational joint ventures while preserving French industrial control. The region's microelectronics cluster supports radiation-hardened component sourcing for guidance electronics. Mediterranean test ranges complement Atlantic facilities for full-spectrum validation.
France Nuclear Bombs and Missiles Market Competitive Landscape
The competitive structure tilts toward prime contractor consolidation with sovereign safeguards. The French Ministry of Armed Forces bundles propulsion, guidance, and reentry vehicle responsibilities under single-source arrangements for the SNLE 3G program. Three archetypes dominate: state-backed primes with full-system responsibility, specialized subsystem vendors with DGA qualification authority, and multinational joint ventures with French control provisions. Competitive moves center on M&A to secure cleared engineering workforces and strategic partnerships to access restricted microelectronics supply chains.
Among the prime contractor tier, Naval Group and Thales Group exemplify the state-backed model with integrated submarine and electronics capabilities. Safran occupies a position as the propulsion anchor, drawing on aerospace heritage for solid-fuel motor development. MBDA represents the multinational joint venture archetype, maintaining French control over missile integration despite cross-border ownership structures. These three entities collectively embody the market's competitive logic: sovereign capability preservation through concentrated industrial organization.
| Leading Market Players |
|---|
| Thales Group |
| Safran |
| Naval Group |
| RTX (Raytheon France) |
| DCNS (Naval Group subsidiary) |
| MBDA |
| ArianeGroup |
| Lockheed Martin France |
| Dassault Aviation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between DGA-qualified primes and uncleared subsystem vendors manifests in both pricing premiums and captive supply chain configurations. The Direction Générale de l'Armement's qualification authority creates a two-tier structure where sovereign-cleared contractors command cost-plus margins while second-tier vendors face margin compression from bundled procurement.
Pricing Analysis
Bundled system integration versus unbundled component supply splits the market's pricing logic. Single-source prime arrangements for SNLE 3G propulsion and guidance packages operate on cost-plus-fee structures with performance guarantees, while radiation-hardened microelectronics and specialty materials trade on spot-adjacent contract terms with volume-scale discounts. Pricing pressure stems from the French Ministry of Armed Forces' consolidated procurement bundling, which compresses subsystem vendor margins. Research organizations at CEA-DAM exhibit the highest price sensitivity due to fixed budget allocations, whereas operational military units prioritize reliability over unit cost.
Supply Chain Analysis
Highly enriched uranium supply rests on a concentrated international supplier base outside French borders, creating sovereign risk exposure for warhead production schedules. Tritium gas and radiation-hardened semiconductors draw from specialized production facilities in the United States and European partners, with composite motor casings sourced from domestic Auvergne-Rhône-Alpes suppliers. Single-source vulnerability for fissile material feedstock represents the dominant structural risk. Distribution runs through Direction Générale de l'Armement-controlled qualification pipelines with direct prime contractor allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France nuclear bombs and missiles market reads as a late-cycle quality story where procurement concentration favors incumbent primes with cleared workforces. Demand is shifting toward extended-range SLBM specifications and digital engineering capabilities that elevate technical qualification barriers.
For Market Incumbents: Deepen sovereign electronics supply chain control through backward integration into radiation-hardened component design, securing against microelectronics obsolescence cycles that threaten guidance system margins. Expand cleared engineering workforce pipelines by partnering with Île-de-France technical universities to address Commission du Secret de la Défense Nationale vetting bottlenecks. For New Entrants and Emerging Players: Research organizations with digital engineering and simulation capabilities represent the most penetrable buyer archetype, as CEA-DAM expands outsourcing for physics package modeling and materials aging studies. Target subcontracts for penetrator warhead aerodynamics and reentry vehicle thermal protection at Paris-Saclay facilities. Position through specialized modeling expertise rather than full-system integration. For Investors and Strategic Acquirers: Consolidation pressure builds where cleared engineering talent scarcity intersects with retirement-driven institutional knowledge depletion. Five-to-ten-year viability favors primes with captive DGA qualification authority and SNLE 3G program exposure. Watch for Direction Générale de l'Armement bundling announcements as inflection indicators for second-tier vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Radiation-Hardened Electronics | Sovereign supply chain control reduces microelectronics obsolescence risk for Thales guidance packages. |
| Cleared Workforce Pipeline Partnerships | Engineering school alliances address Commission du Secret de la Défense Nationale vetting timelines constraining scaling. |
| Digital Engineering Capability Acquisition | Simulation expertise targets CEA-DAM outsourcing expansion for physics package modeling. |
| Brittany Test Range Infrastructure Expansion | Underwater acoustic measurement capacity accelerates M51.3 validation cycles without foreign facility dependence. |
| Hypersonic Glide Vehicle Research Funding | DGA technology demonstrator programs open new qualification pathways for scramjet propulsion integration. |
Research Methodology
Coverage spans metropolitan France with primary inputs from Île-de-France, Brittany, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur, combining interviews with Direction Générale de l'Armement program officers, Naval Group submarine architects, Thales guidance system engineers, Safran propulsion specialists, and CEA-DAM research directors. Secondary validation draws from French Ministry of Armed Forces budget documentation, Loi de Programmation Militaire filings, EU dual-use export control transposition decrees, and Wassenaar Arrangement category revisions. Bottom-up segment sizing triangulates against top-down defense expenditure allocation analysis.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include product type, deployment mode, end user, and technology subsystem with platform-agnostic warhead design trajectories modeled separately. CAGRs derive from fitted trend extrapolation with program milestone adjustments. Forecast inputs incorporate SNLE 3G construction schedules, M51.3 development timelines, and Rafale F5 standard integration cycles without specific year anchoring.
Underlying measurement precision varies by segment; sea-based SLBM procurement carries tighter precision than air-launched weapons given defined program budgets, while hypersonic research allocations exhibit wider uncertainty bands. Forecasts reflect documented assumptions about Direction Générale de l'Armement bundling continuity and NATO burden-sharing negotiations. A small set of triggers warrants ongoing watch: fissile material supply disruptions, Commission du Secret de la Défense Nationale clearance processing delays, and EU dual-use control category revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Electromagnetic Weapons Market